
 Sorghum by-Products Market | 2026-2036
Sorghum by-Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sorghum by-Products Market Outlook
Texas is tilting the North American sorghum processing map with expanded wet-mill and dry-grind capacity additions. Archer Daniels Midland Company leverages its Decatur, Illinois complex to sustain integrated sorghum-to-ethanol and high-protein feed operations. Cargill Incorporated anchors grain origination networks across Kansas and Nebraska that compete for supply with food-grade processors. Nu Life Market specializes in gluten-free sorghum flour milling that differentiates its product line from commodity handlers.
Sorghum by-products encompass the residual and co-product streams generated from grain processing, including distillers grains with solubles containing 25-30% crude protein, bran fractions, and syrup extracts recovered from juice pressing. These materials serve primarily as livestock feed inputs, fermentation substrates for biofuel production, and functional ingredients in human food formulations. Sorghum flour occupies the premium tier within product type segmentation as clean-label and gluten-free bakery applications expand. Sorghum stover represents the fastest-growing category among product types as cellulosic biofuel research advances and ruminant bedding demand rises. Animal feed dominates end-use segmentation with established volume, while biofuels capture widening margin pools under renewable fuel policy frameworks.
The EPA administers Renewable Fuel Standard compliance pathways that shape sorghum ethanol economics and by-product valuation. FDA food-contact and GRAS determinations govern sorghum ingredient access to human nutrition markets. USDA crop insurance and commodity programs influence planted acreage decisions that cascade into by-product supply volumes. Stakeholders must monitor how the next farm bill reauthorization reshapes sorghum program benefits relative to competing grains.
Market Dynamics
The EPA's Renewable Fuel Standard compliance pathways are compressing sorghum ethanol economics while concentrating by-product valorization decisions among a handful of integrated processors with wet-mill and dry-grind capabilities.
Growth Catalysts
- Distillers grains protein premium:Livestock feed manufacturers in the Texas Panhandle corridor are substituting sorghum DDGS for soybean meal in cattle finishing rations, drawn by cost spreads and amino acid profiles.
- Cellulosic biofuel R&D pipelines:Sorghum stover collection systems are scaling as biorefinery pilots advance enzymatic hydrolysis yields for second-generation ethanol pathways under DOE funding.
- Gluten-free formulation mandates:FDA food-labeling enforcement is accelerating sorghum flour adoption in clean-label bakery applications, creating pull-through demand for bran and germ fractions.
Market Restraints
- Input cost volatility:Sorghum grain prices track corn futures with a lag, exposing processors to margin compression when energy markets spike fertilizer and diesel costs simultaneously.
- Supply concentration risk:Kansas and Nebraska origination networks dominate U.S. grain flows, leaving processors vulnerable to drought-induced yield shocks in the Southern Plains.
- Technical limitation:Sorghum tannins and phytates reduce digestibility in monogastric feed formulations, limiting DDGS penetration in poultry and swine rations relative to corn alternatives.
Strategic Opportunities
- Underpenetrated human nutrition:Sorghum protein isolate extraction remains below commercial scale, presenting white space for ingredient suppliers targeting plant-based meat analogs.
- Regulatory tailwind:USDA crop insurance program reauthorization in the next farm bill could tilt planted acreage toward sorghum relative to competing grains, expanding by-product supply pools.
- Technology convergence:Precision fermentation platforms are converging with sorghum syrup substrates to produce alternative proteins, opening novel valorization routes for molasses streams.
Industry Challenges
- Skill gap in bioprocessing:Cellulosic ethanol engineering talent remains scarce, delaying stover-to-fuel project timelines and raising recruitment costs for pilot facilities.
- Capex intensity:Wet-mill fractionation equipment requires substantial capital deployment, constraining mid-size grain handlers from entering high-margin food-grade flour markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorghum by-Products Market |
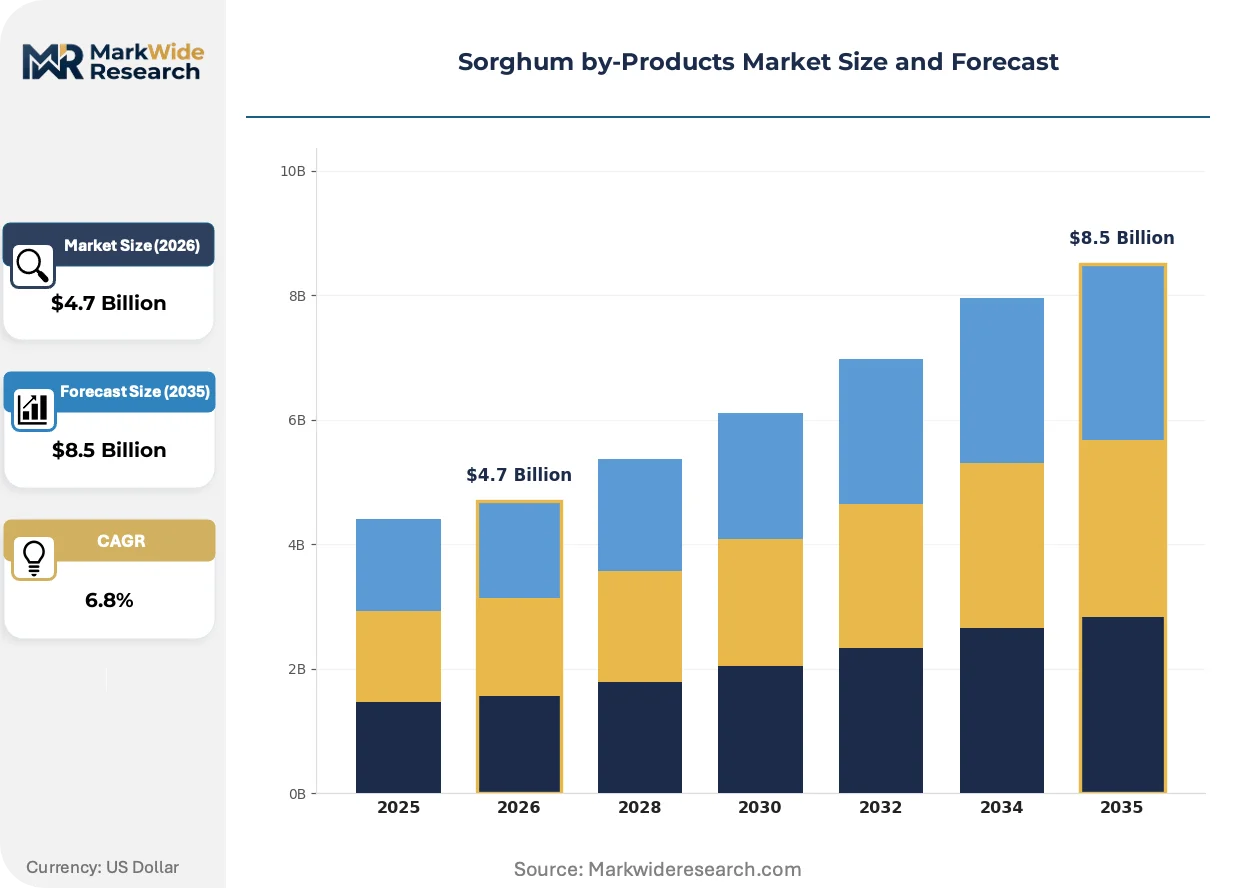
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorghum Flour, Sorghum Grain, Sorghum Syrup, Sorghum Stover End Use: Beverages, Animal Feed, Food Ingredients, Biofuels Packaging Type: Bulk Bags, Retail Packaging, Bins, Pallets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ardent Mills, The Scoular Company, Seedway LLC, Nu Life Market, Bunge Limited, Louis Dreyfus Company, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorghum by-Products Market Strategic Shifts
Processing technology is migrating toward integrated fractionation systems that capture multiple value streams from single grain intake, while regulatory compliance costs are reshaping facility location decisions.
Enzymatic dry-grind processes are migrating from pilot-scale demonstration to commercial deployment at ethanol facilities seeking to extract corn oil analogs from sorghum germ. Integrated processors with existing fermentation infrastructure are retrofitting front-end equipment at accelerated capital deployment schedules. This technology is migrating from niche applications to mainstream adoption, compressing the cost gap between sorghum and corn ethanol pathways while raising protein concentration in residual DDGS.
The EPA's Renewable Fuel Standard RIN generation pathways are tightening qualification criteria for sorghum-based advanced biofuels, forcing processors to document lifecycle greenhouse gas reductions through improved farming practices. This regulatory pressure is redirecting capital toward facilities with verified supply chain traceability systems. Dry-grind operators in the Texas Panhandle are responding by contracting directly with growers for climate-smart cultivation protocols.
Feedlot procurement patterns are consolidating around long-term offtake agreements with specified protein content and mycotoxin thresholds, displacing spot-market transactions for distillers grains. Large cattle-finishing operations are vertically integrating into sorghum processing through equity stakes and dedicated supply contracts. This behavioral shift is most visible across the Southern Plains feedlot corridor, where volume concentration is compressing margins for independent commodity handlers.
Sorghum by-Products Market Segmentation
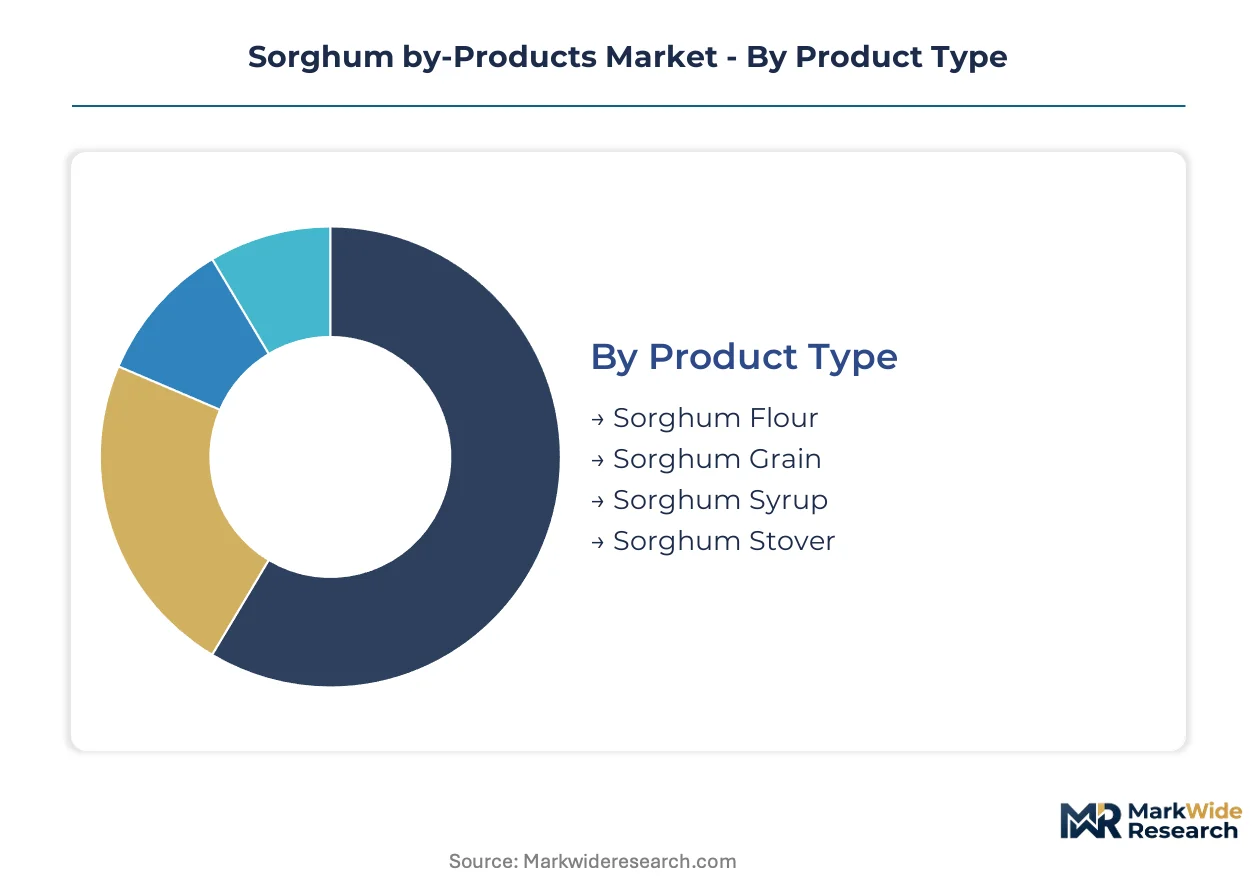
Sorghum by-product streams fragment across distinct valorization pathways where protein content, moisture stability, and handling characteristics dictate commercial destination. Processors optimize revenue capture by routing high-protein fractions toward feed contracts while directing food-grade outputs through specialized milling infrastructure.
Product Type:
Use-case spectrum spans human nutrition premiums, livestock energy density, fermentation substrates, and cellulosic biomass reserves with divergent margin profiles.
- Sorghum Flour:Milled endosperm fractions achieve 8-12% protein content with fine particle distribution required for gluten-free bakery formulations. Clean-label adoption in Texas and Kansas retail channels drives contract premiums for certified gluten-free milling operations.
- Sorghum Stover:Residual stalk, leaf, and cob biomass contains 35-45% cellulose content suitable for enzymatic hydrolysis platforms. DOE-funded pilot facilities in the Southern Plains are scaling collection logistics for second-generation ethanol pathways.
- Sorghum Grain:Whole kernel supply moves through dry-grind ethanol facilities and wet-mill fractionation complexes with protein recovery systems.
- Sorghum Syrup:Concentrated juice extracts from sweet sorghum varieties serve fermentation feedstocks and specialty food sweetener markets.
Established volume favors Sorghum Grain; emerging adoption favors Sorghum Stover.
End Use:
Customer type stratification separates commodity volume buyers from specification-driven purchasers with certificate requirements.
- Animal Feed:Distillers dried grains with solubles deliver 25-30% crude protein and metabolizable energy values competitive with soybean meal in cattle finishing rations. Texas Panhandle feedlots are locking multi-year offtake agreements with DDGS suppliers.
- Biofuels:Dry-grind ethanol facilities generate D5 RIN credits under EPA Renewable Fuel Standard pathways with documented lifecycle greenhouse gas reductions. Sorghum ethanol qualifies for advanced biofuel status with qualifying farming practice verification.
- Food Ingredients:Bran and germ fractions enter gluten-free flour blends and extruded snack matrices with FDA GRAS status.
- Beverages:Fermented sorghum bases support traditional African beer analogs and emerging craft spirit formulations in niche distribution.
Margin concentration sits with Animal Feed; technology optionality sits with Biofuels.
Packaging Type:
Supply concentration in grain origination corridors dictates bulk handling infrastructure deployment versus retail-ready unitization.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate DDGS shipment to feedlot operations with pneumatic discharge systems.
- Bins:Fixed-site grain storage with aeration capacity supports origination network accumulation before processor delivery.
- Retail Packaging:Multi-layer laminated pouches preserve flour moisture specifications below 12% for grocery channel distribution.
- Pallets:Unitized loads facilitate warehouse handling for specialty ingredient distributors serving food manufacturing accounts.
Cost efficiency favors Bulk Bags; specification control favors Retail Packaging.
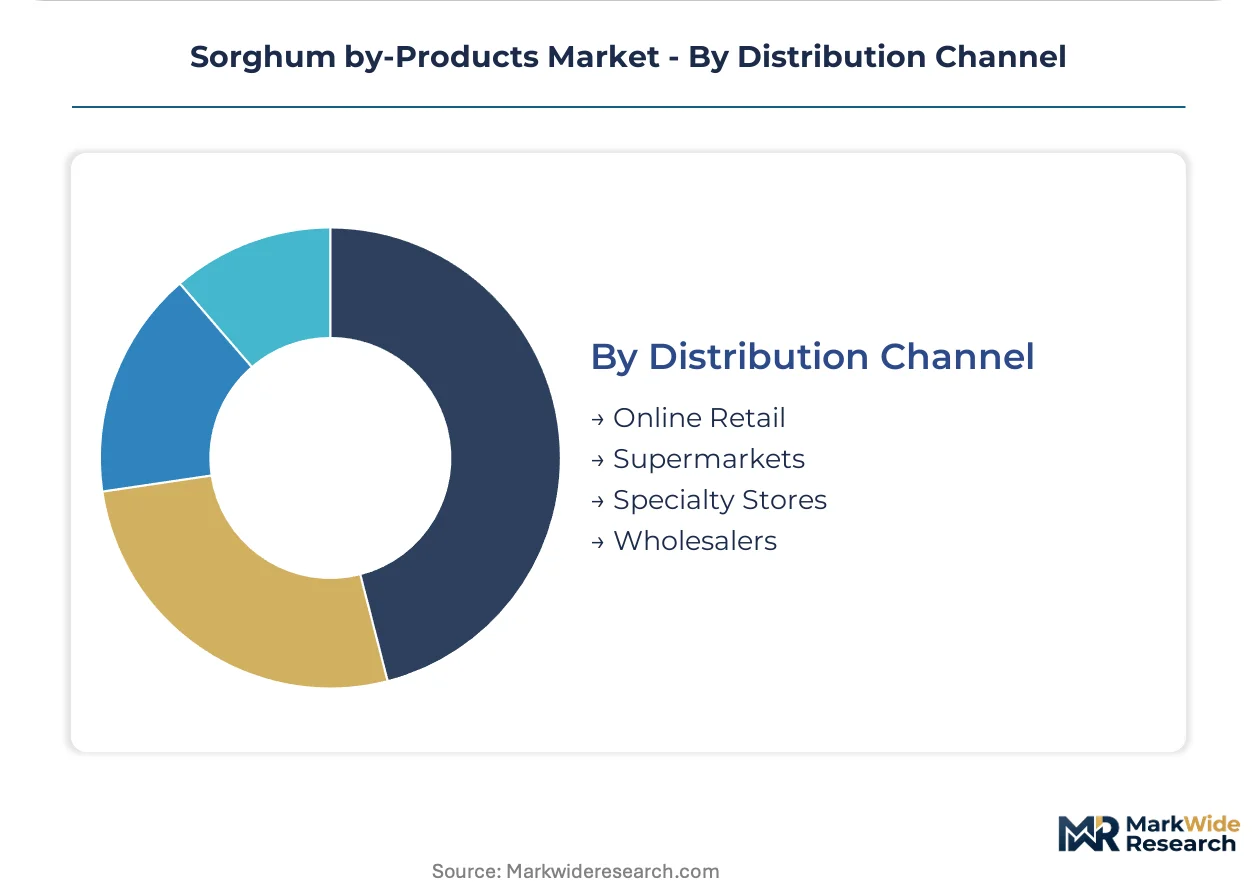
Distribution Channel:
Geography of demand shapes channel selection between direct processor contracting and layered wholesale intermediation.
- Wholesalers:Regional grain elevators and feed supply cooperatives aggregate sorghum DDGS from multiple ethanol facilities for lot-sized delivery to cattle operations.
- Supermarkets:Clean-label sorghum flour placement in natural foods aisles requires branded packaging and third-party gluten-free certification.
- Specialty Stores:Ethnic grocery channels in Houston and Dallas metropolitan areas stock sorghum syrup for traditional recipe formulations.
- Online Retail:Direct-to-consumer flour sales bypass wholesale markups but require cold-chain logistics investment for germ-included whole grain products.
Volume throughput favors Wholesalers; margin capture favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sorghum processing capacity clusters along grain origination corridors where wet-mill and dry-grind infrastructure can access feedstock at scale. The United States dominates installed base, though Brazil and India are expanding processing footprints to capture export premiums and domestic ethanol mandates.
United States
Kansas and Nebraska origination networks supply grain to Texas Panhandle ethanol corridors and Illinois wet-mill complexes. The EPA's Renewable Fuel Standard generates D5 RIN credits for qualifying sorghum ethanol pathways. Decatur, Illinois anchors integrated sorghum-to-ethanol operations with co-located high-protein feed recovery systems.
Brazil
Livestock feed manufacturers in São Paulo state are testing sorghum DDGS imports as corn price hedges during planting season volatility. The country's national biofuel regulator, ANP, maintains RenovaBio carbon intensity scoring that could advantage sorghum ethanol if lifecycle certifications align. Sorghum stover collection pilots in Minas Gerais are scaling logistics for cellulosic ethanol research funded by BNDES.
India
Maharashtra and Karnataka sweet sorghum varieties supply jaggery processors and emerging ethanol distilleries under the Ethanol Blending Programme. The Food Safety and Standards Authority of India governs sorghum flour labeling for gluten-free claims in urban retail channels. Hyderabad-based research stations are advancing high-biomass varieties for fodder and fuel dual-use applications.
China
Shandong Province wet-mill operators process sorghum for baijiu fermentation and co-product feed streams. The Ministry of Agriculture and Rural Affairs includes sorghum in strategic grain reserve calculations alongside corn and wheat. Inner Mongolia autonomous region is piloting drought-resistant sorghum varieties for marginal land cultivation with state agricultural extension support.
Australia
Queensland feedlot operators source sorghum DDGS from domestic ethanol facilities as protein supplements for cattle finishing rations. The Grains Research and Development Corporation funds sorghum breeding programs targeting both grain yield and stover quality for ruminant bedding markets. Darling Downs processing infrastructure is expanding storage capacity to handle harvest timing mismatches with Asian export windows.
Sorghum by-Products Market Competitive Environment
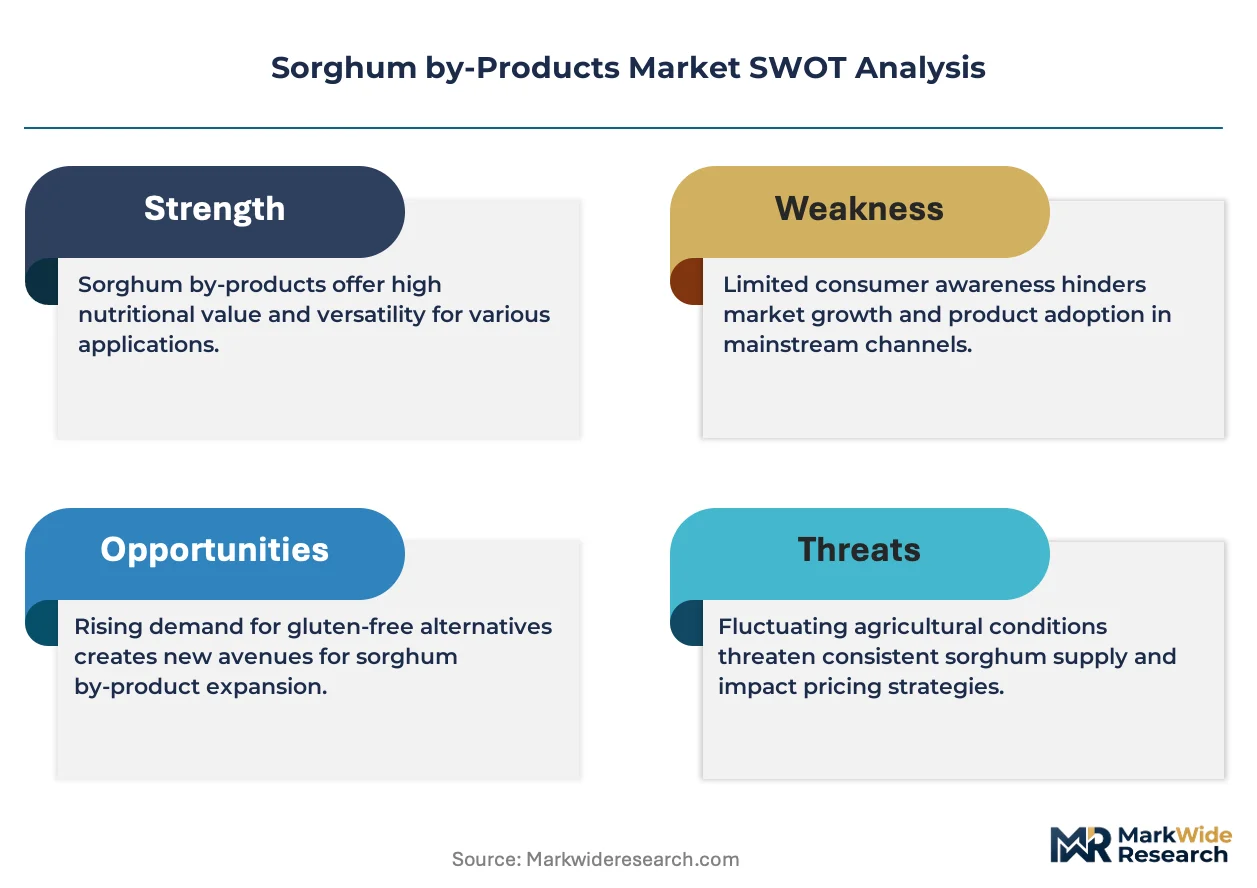
Integrated grain processors and specialized ingredient suppliers split the market between commodity volume plays and premium fractionation niches. The vendor base concentrates among agricultural conglomerates with origination networks and mid-size millers with certified food-grade capabilities. Two archetypes dominate: scale-driven ethanol-integrated processors capturing RIN economics, and gluten-free specialists commanding bakery channel premiums. Competitive moves center on origination contract consolidation and front-end fractionation technology licensing.
Within the integrated processor tier, Archer Daniels Midland Company and Cargill Incorporated exemplify scale-driven ethanol and feed co-product operations. Nu Life Market occupies a position among certified gluten-free flour specialists targeting clean-label bakery channels. Bunge Limited and Louis Dreyfus Company represent agricultural trading houses with origination network leverage across multiple grain categories.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ardent Mills |
| The Scoular Company |
| Seedway LLC |
| Nu Life Market |
| Bunge Limited |
| Louis Dreyfus Company |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
Texas Panhandle rail corridors transmit freight cost volatility directly into sorghum DDGS price spreads between wet-mill and dry-grind processors, compressing margins for handlers without captive origination networks while amplifying protein-premium capture for integrated ethanol-feed operators.
Pricing Analysis
EPA Renewable Fuel Standard compliance dictates the pricing tier structure across sorghum by-product streams, separating D5 RIN-qualified ethanol pathways from conventional feed-grade outputs. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein certification, gluten-free labeling, and mycotoxin thresholds. Cost compression in standard-grade DDGS is intensifying because Kansas-Nebraska supply concentration exposes processors to simultaneous fertilizer and diesel spikes. Feedlot procurement teams exhibit highest price sensitivity, while gluten-free flour manufacturers absorb premiums for certified clean-label supply.
Supply Chain Analysis
Extended payment terms from ethanol processors to Kansas and Nebraska grain elevators are tightening working capital for mid-size handlers competing with ADM and Cargill origination networks. Supply draws from sorghum grain, fermentation enzymes, and protein recovery chemicals, with flows anchored in United States, Brazil, and India processing corridors. Single-source vulnerability concentrates in Southern Plains drought corridors where yield shocks cascade into feedlot ration disruptions. Distribution runs through direct processor contracting for volume buyers and layered wholesale intermediation for specialty ingredient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sorghum by-product markets reward defensive positioning through regulatory entrenchment, where EPA RIN qualification pathways and FDA GRAS certifications erect switching costs that protect incumbent margin structures from commodity handler competition.
For Market Incumbents: Harden RIN credit capture through direct grower contracting for climate-smart cultivation protocols that satisfy EPA lifecycle documentation requirements. Expand wet-mill fractionation capacity in Texas Panhandle corridors to consolidate protein-recovery economics against dry-grind competitors. Lock multi-year offtake agreements with cattle-finishing operations specifying mycotoxin thresholds that spot-market handlers cannot match. For New Entrants and Emerging Players: Brazil ethanol import corridors present white-space targeting for sorghum DDGS suppliers seeking corn-price hedge positioning during São Paulo planting volatility. Sweet sorghum syrup valorization for precision fermentation substrates offers penetrable entry into alternative protein ingredient markets. Pursue ANP RenovaBio carbon intensity certification alignment to qualify for Brazilian biofuel mandates before established traders consolidate logistics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with wet-mill infrastructure and verified supply chain traceability systems. Long-term viability rests on cellulosic stover-to-ethanol pathway maturation and human nutrition fractionation scale-up. Monitor DOE pilot facility yield announcements as inflection indicators for second-generation biofuel capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Smart Cultivation Contracting | EPA RIN qualification secures advanced biofuel premiums for integrated processors. |
| Protein Recovery System Retrofit | Dry-grind ethanol facilities extract corn oil analogs to compress sorghum cost gaps. |
| Gluten-Free Certification Investment | FDA labeling enforcement accelerates clean-label bakery channel premiums. |
| Cellulosic Stover Collection Scaling | DOE-funded pilot logistics advance second-generation ethanol pathway economics. |
| Feedlot Vertical Integration | Equity stakes in cattle-finishing operations displace spot-market DDGS transactions. |
Study Parameters
The analysis maps sorghum flour milling, DDGS feed processing, ethanol fermentation, and cellulosic stover valorization, each validated through grain origination managers, ethanol plant engineers, feedlot nutritionists, and gluten-free certification specialists. Primary interviews with Kansas-Nebraska elevator operators and Texas Panhandle procurement directors combined with secondary validation from USDA crop insurance filings, EPA RIN generation databases, and FDA GRAS determination records. Bottom-up volume triangulation across product type segments reconciled with top-down market sizing from processor capacity disclosures.
Assumptions held fixed include EPA Renewable Fuel Standard compliance pathway continuity and FDA food-labeling enforcement intensity, while sorghum acreage response to farm bill reauthorization and cellulosic ethanol yield advances were modeled as scenario variables. Segmentation dimensions span product type, end-use application, protein content tier, and regional origination corridor. CAGRs derived from processor revenue recognition patterns and feedlot procurement volume trends across the analysis window, with biofuel policy incentive schedules and livestock feed substitution elasticities as primary forecast inputs.
Practitioners should monitor farm bill reauthorization negotiations and DOE pilot facility yield announcements for early signals of supply pool expansion or cellulosic pathway maturation. Forecasts reflect documented assumptions without contingency for abrupt regulatory revocation or drought-induced yield collapse. Macroeconomic commodity price spikes, EPA pathway modification, or enzymatic hydrolysis breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
India Compound Feed Market