
 Kenya Floriculture Market | 2026-2036
Kenya Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Floriculture Market Foresight
Naivasha-based commercial growers is decoupling from rain-fed dependence through geothermal-powered greenhouse expansion. Black Petals Ltd leverages its integrated cold-chain infrastructure to sustain year-round supply consistency for European buyers. Oserian Development Company Limited anchors its competitive position through geothermal energy self-sufficiency at its Lake Naivasha complex. Sunfloritech Ltd differentiates via specialized summer flower varieties that command premium positioning in Dutch auctions.
Kenya floriculture encompasses the commercial cultivation, post-harvest processing, and export of cut flowers—primarily roses, carnations, lilies, and chrysanthemums—grown under controlled greenhouse conditions with specified stem lengths of 40–90 cm and vase-life thresholds exceeding 12 days. The sector functions as a foreign-exchange generator and rural employer, supplying fresh-cut blooms to European and Middle Eastern retail and wholesale channels. Roses occupy the dominant volume position within product type segmentation, while organic quality grades represent the fastest-expanding margin pool as EU retailers impose stricter residue protocols. Direct sales channels to supermarket chains are displacing traditional Dutch auction dependency, though wholesalers retain critical aggregation functions for smaller farms.
Kenya's Water Resources Authority regulates abstraction permits for Lake Naivasha basin farms, while the Kenya Plant Health Inspectorate Service enforces phytosanitary certification for EU market access. The Horticultural Crops Directorate implements cold-chain and traceability standards that shape export eligibility. Stakeholders must monitor evolving EU deforestation-free supply-chain regulations and geothermal lease renegotiations that could reshape cost structures for energy-intensive greenhouse operations.
Market Dynamics
European supermarket chains are consolidating direct procurement relationships with certified Kenyan rose growers, bypassing traditional Dutch auction intermediaries and compressing margin structures across the Lake Naivasha supply basin.
Growth Catalysts
- EU deforestation-free supply-chain regulations:The EU Green Deal mandates traceability documentation for agricultural imports, creating competitive advantage for Kenyan farms with established certification infrastructure.
- Geothermal energy expansion:Steam fields around Lake Naivasha enable year-round greenhouse climate control independent of rainfall variability.
- Phytosanitary standardization:Kenya Plant Health Inspectorate Service protocols align with EFSA residue thresholds, accelerating customs clearance at Rotterdam and Frankfurt entry points.
Market Restraints
- Water abstraction permit scarcity:Kenya's Water Resources Authority has frozen new permits for Lake Naivasha basin extraction, capping expansion for uncertified farms.
- Input cost volatility:Fertilizer and agrochemical prices fluctuate with natural gas benchmarks, squeezing margin predictability for mid-scale operations.
- Freight capacity concentration:Nairobi-Jomo Kenyatta International Airport cold-chain slots prioritize perishables with established forwarder contracts, marginalizing smaller exporters.
Strategic Opportunities
- Middle East retail penetration:UAE and Saudi supermarket chains are developing direct sourcing programs for premium-grade Kenyan roses outside EU auction channels.
- Organic certification acceleration:EU organic label demand outpaces certified African supply, rewarding early conversion investments with price premiums.
- Blockchain-IoT convergence:Farm-to-shelf traceability platforms satisfy retailer ESG disclosure requirements while reducing audit costs.
Industry Challenges
- Skilled agronomist scarcity:Integrated pest management and hydroponic system expertise commands wage premiums that smaller farms cannot match.
- Certification timeline compression:GLOBALG.A.P. and Fairtrade audit cycles extend 18-24 months, delaying market access for new entrants.
- Cold-chain infrastructure gaps:Last-mile temperature control from farm packhouses to airport cargo terminals remains inconsistent outside Naivasha and Thika corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Floriculture Market |
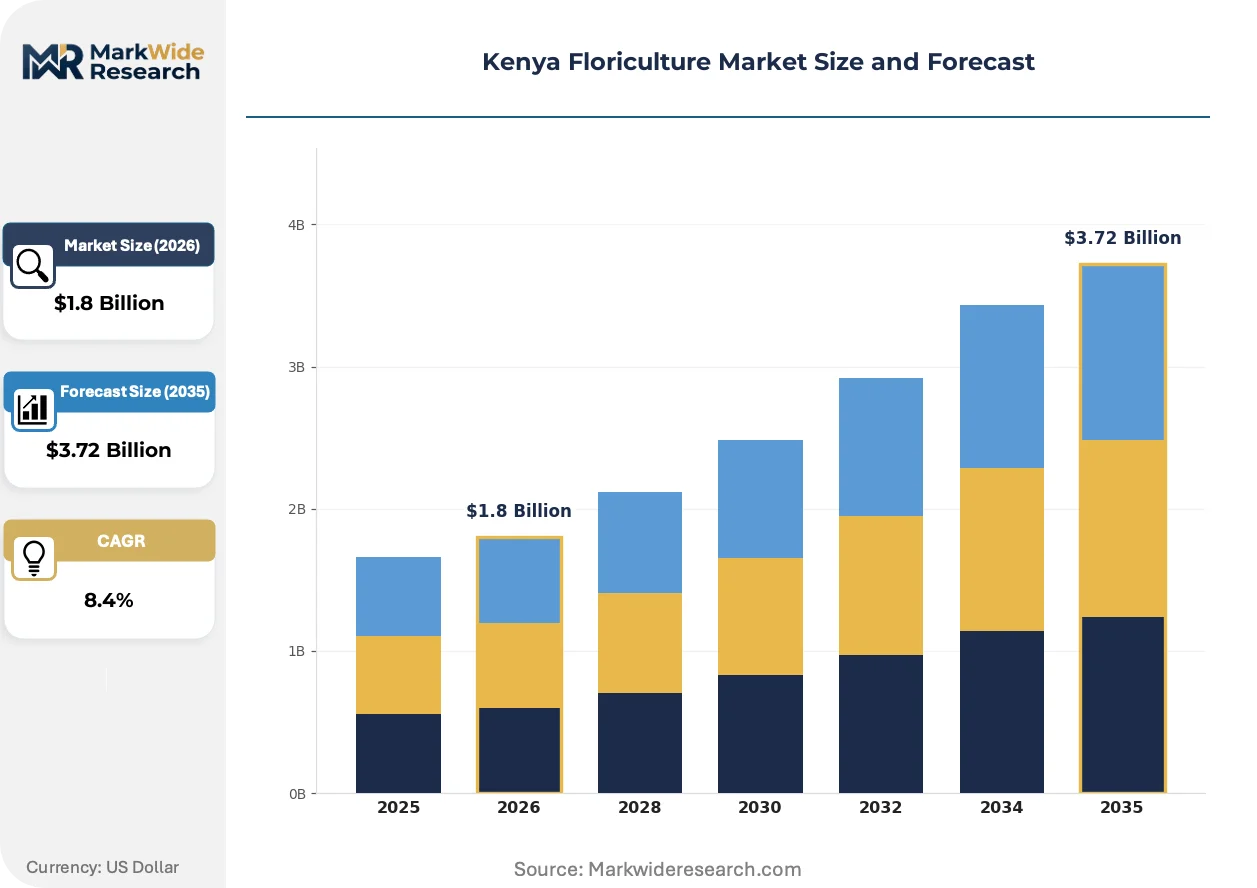
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roses, Carnations, Lilies, Chrysanthemums Distribution Channel: Online Retail, Wholesalers, Supermarkets, Direct Sales Consumer Type: Event Planners, Retail Florists, Hotels, Retail Consumers Quality Grade: Premium, Standard, Value, Organic |
| Companies Covered | Black Petals Ltd, Sunfloritech Ltd, Oserian Development Company Limited, Eco Roses, Utee Estate Ltd, Black Tulip Group, Golden Tulip Farms, Batian Farms, Laurel Investments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Floriculture Market Shifts & Advancements
Digital traceability platforms and renewable energy integration are restructuring how Kenyan flower farms validate sustainability claims and manage input costs for European buyers.
Sensor-based irrigation management is converging with geothermal-powered climate systems at Naivasha-area operations. Large-scale exporters deploy soil-moisture telemetry to optimize water use per stem. This convergence is compressing unit production costs while satisfying Water Resources Authority consumption reporting requirements.
EU deforestation-free supply-chain regulations now mandate geolocation documentation for agricultural imports entering Dutch and German ports. Kenyan exporters must submit polygon mapping of cultivation areas to customs authorities. Rose shipments lacking compliant traceability documentation face extended inspection delays at Rotterdam.
Direct contracting between supermarket chains and certified farms is displacing auction-house intermediation for premium-grade volumes. German retail buyers now negotiate annual supply agreements specifying stem length and vase-life thresholds. This pattern concentrates procurement leverage among farms with integrated cold-chain infrastructure.
Kenya Floriculture Market Segmentation
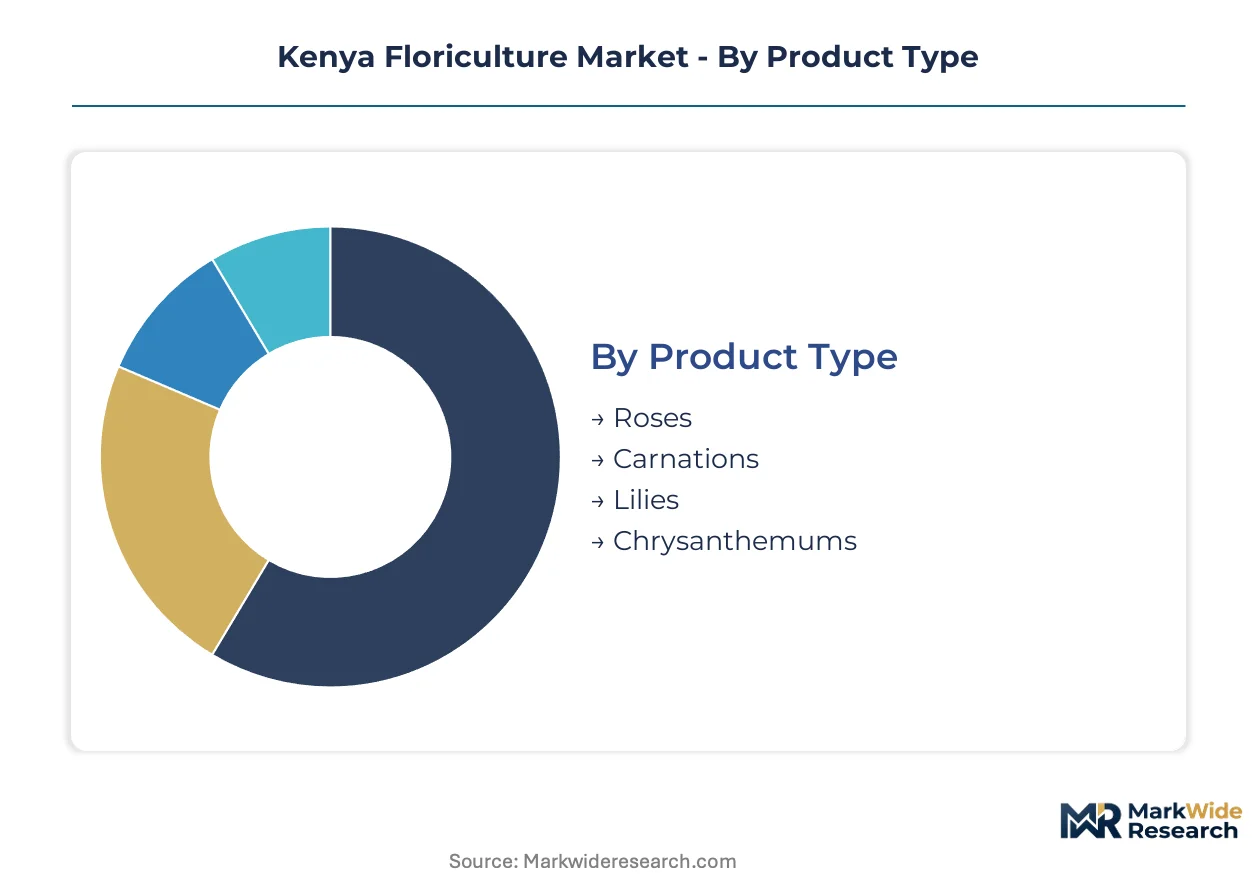
Kenyan flower farms calibrate production specifications to distinct buyer requirements across product categories and quality tiers. Segmentation reveals how procurement leverage concentrates among large-scale retail chains versus fragmented wholesale channels.
Product Type:
Buyers differentiate by stem length durability, color consistency, and vase-life thresholds for specific retail applications.
- Roses:Long-stemmed hybrids with 40-90 cm specifications dominate Dutch auction volumes. German retail buyers specify minimum 12-day vase life for direct procurement contracts.
- Carnations:Spray and standard varieties serve Middle Eastern event markets requiring bulk volume with lower per-stem price sensitivity. UAE supermarket chains specify carnations for promotional bouquet programs.
- Lilies:Oriental and Asiatic hybrids command premium positioning in hotel and corporate segments across Saudi Arabia and Qatar.
- Chrysanthemums:Disbud and spray types anchor funeral and commemorative demand in European wholesale channels.
Volume sits with roses; growth tilts toward lilies.
Distribution Channel:
Channel selection determines margin capture, traceability burden, and payment terms for Naivasha-based growers.
- Direct Sales:Annual supply agreements with German and Dutch supermarket chains specify stem length, residue thresholds, and ESG documentation. Farms with integrated cold-chain infrastructure secure preferred supplier status.
- Supermarkets:UK and French retail buyers impose blockchain-traceability requirements for deforestation-free compliance. Direct contracting compresses auction margins but locks in volume commitments.
- Wholesalers:Dutch auction houses aggregate smaller farm output for Rotterdam distribution. Smaller exporters depend on wholesaler freight consolidation for Jomo Kenyatta airport cargo slots.
- Online Retail:Subscription-based flower delivery platforms in London and Amsterdam source certified organic grades with shortened fulfillment windows.
Procurement leverage concentrates in direct sales; wholesaler dependency persists among uncertified mid-scale farms.
Consumer Type:
End-use applications impose divergent specifications for shelf life, packaging, and delivery reliability.
- Hotels:Luxury properties in Dubai and Riyadh specify daily fresh delivery with color-matched lobby arrangements. Contracts demand 14-day minimum vase life for reduced replacement frequency.
- Event Planners:Wedding and corporate segments in Qatar and Kuwait require volume surge capacity with guaranteed shipment windows. Seasonal demand spikes align with European and Gulf holiday calendars.
- Retail Florists:Independent shops in Amsterdam and Frankfurt depend on auction liquidity for variety breadth and price discovery.
- Retail Consumers:Supermarket bouquet purchases in Germany and UK drive impulse demand for value-grade mixed arrangements.
Revenue stability favors hotel contracts; margin expansion tracks event planner premium specifications.
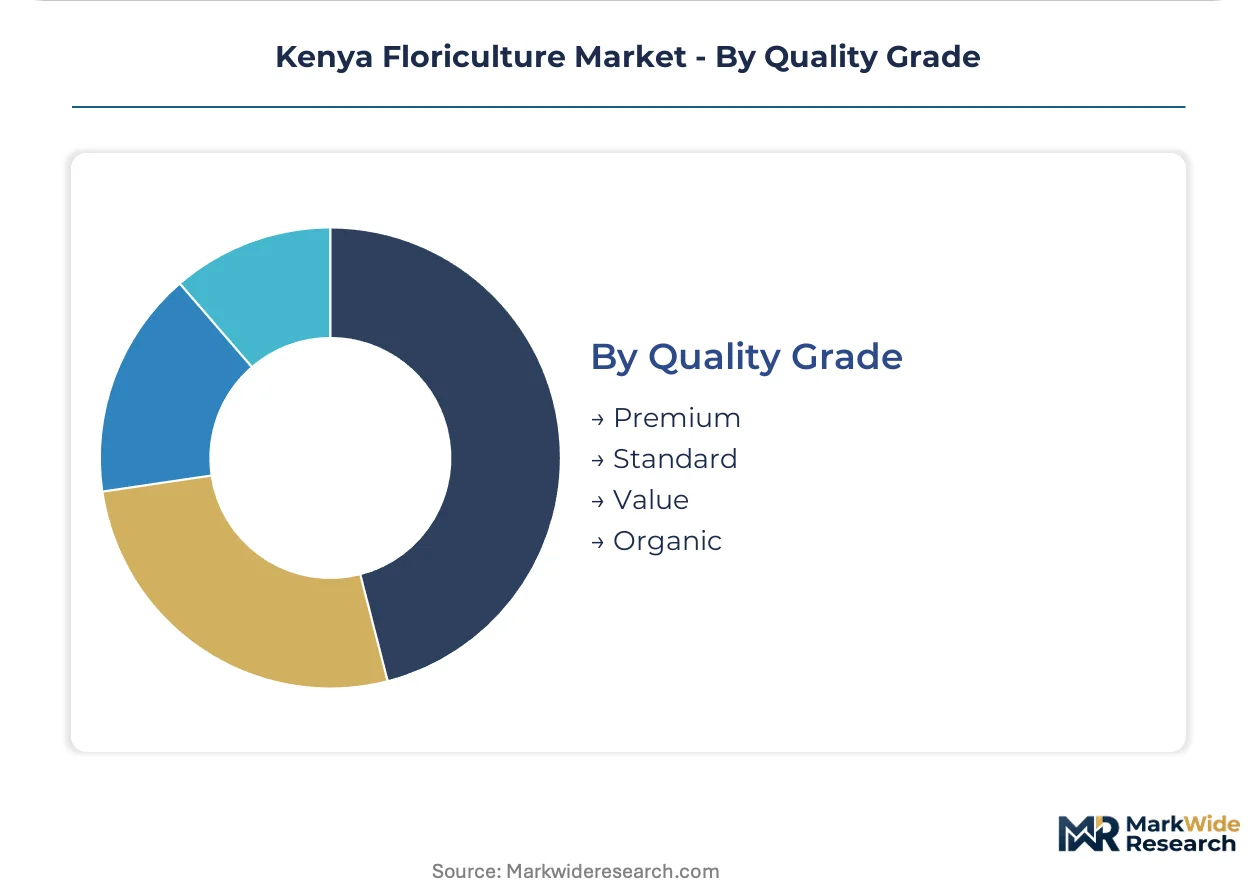
Quality Grade:
Certification tier determines market access eligibility and price realization across European regulatory environments.
- Premium:GLOBALG.A.P. and MPS-certified stems meet EU retailer residue protocols with full traceability documentation. German chains specify premium grades for private-label rose programs.
- Organic:EU organic label demand outpaces certified African supply. Conversion timelines of 24-36 months create supply scarcity for early adopters around Lake Naivasha.
- Standard:Conventionally grown stems serve wholesale auction channels with less stringent documentation requirements. Price compression intensifies as direct procurement expands.
- Value:Shorter stem lengths and reduced vase life specifications supply price-sensitive retail segments in Eastern Europe and domestic Kenyan markets.
Certified supply concentrates in premium; organic conversion investments are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lake Naivasha's geothermal steam fields anchor Kenya's floriculture geography, concentrating greenhouse infrastructure within a 50-kilometer radius of the Rift Valley basin. Water abstraction permits from Kenya's Water Resources Authority shape expansion feasibility across sub-regional clusters.
Naivasha Basin
Direct procurement contracts with German supermarket chains drive demand for certified rose volumes with 12-day minimum vase life. Kenya's Water Resources Authority enforces consumption reporting for farms drawing from Lake Naivasha. Oserian Development Company Limited anchors geothermal-powered operations at this complex, achieving energy self-sufficiency for year-round climate control.
Thika Corridor
Jomo Kenyatta International Airport proximity enables cold-chain access for exporters securing forwarder contracts on perishable cargo slots. The Horticultural Crops Directorate implements traceability standards that determine export eligibility from this cluster. Black Petals Ltd leverages integrated packhouse infrastructure here to sustain supply consistency for European buyers.
Nairobi Periphery
Event planner demand from UAE and Saudi Arabia concentrates procurement of lily and chrysanthemum varieties for hotel and corporate segments. Kenya Plant Health Inspectorate Service phytosanitary protocols align with EFSA residue thresholds for Middle East shipment clearance. Sunfloritech Ltd specializes in summer flower cultivation from this zone, commanding premium positioning at Dutch auctions.
Rift Valley Highlands
Organic certification conversion timelines of 24-36 months create supply scarcity for EU label demand outpacing certified African production. EU Green Deal deforestation-free regulations mandate geolocation documentation for agricultural imports from this region. Smaller farms in this sub-region depend on wholesaler freight consolidation for airport cargo slot access.
Kenya Floriculture Market Competitive Landscape
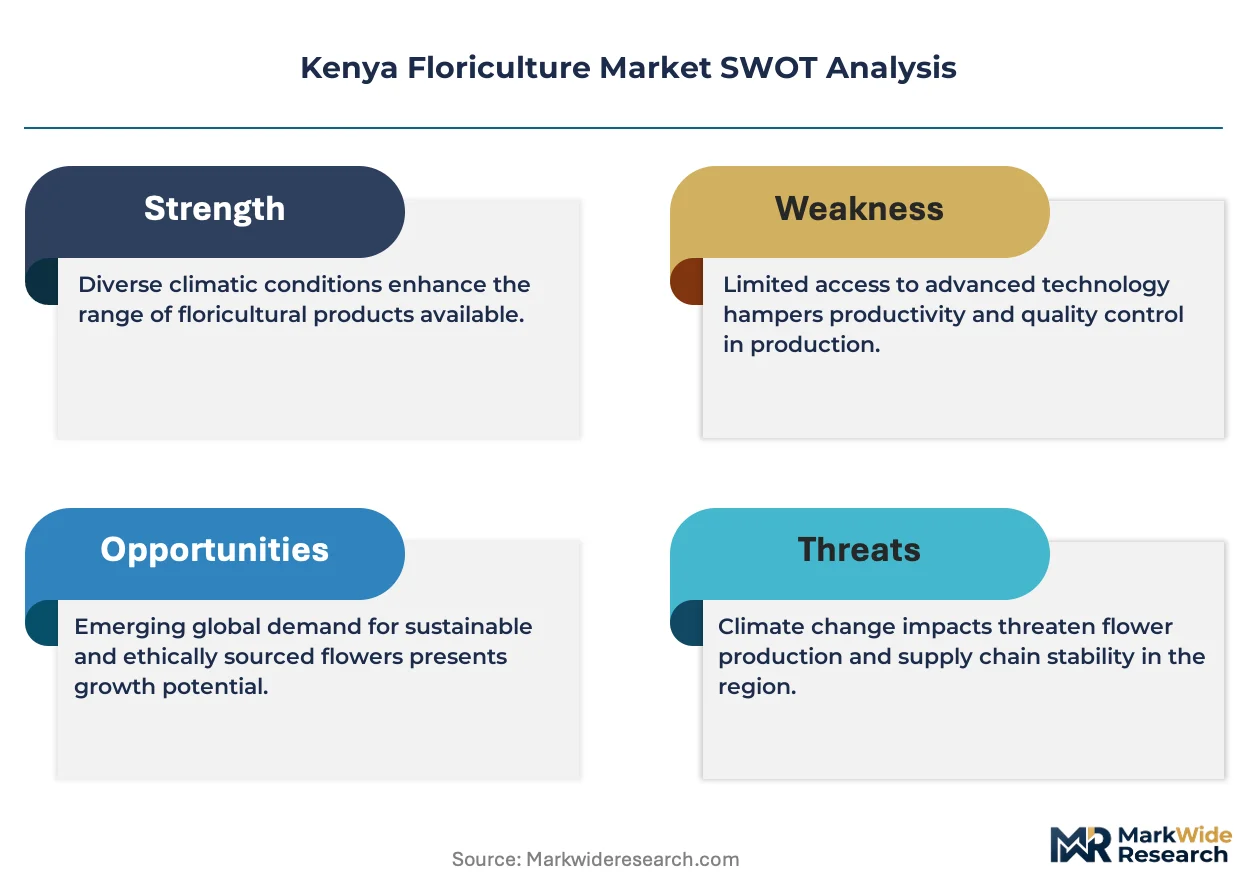
Established producers occupy the standard tier; emerging entrants pursue organic certification and direct retail contracting as differentiation vectors. The vendor base clusters around integrated cold-chain operators and specialized variety cultivators, with scale advantages concentrating among geothermal-powered facilities. Strategic archetypes include energy-self-sufficient integrated growers, certification-focused premium specialists, and wholesaler-dependent mid-scale aggregators. Competitive moves center on backward integration into captive geothermal energy supply and forward integration into direct supermarket chain relationships.
Within the integrated infrastructure tier, Black Petals Ltd and Oserian Development Company Limited exemplify scale-driven positioning through cold-chain and energy assets. Sunfloritech Ltd occupies a specialization niche among variety-focused operators. These three entities represent the dominant competitive archetypes visible across the Lake Naivasha supply basin: energy-integrated volume producers, infrastructure-heavy logistics operators, and premium-variety cultivators.
| Leading Market Players |
|---|
| Black Petals Ltd |
| Sunfloritech Ltd |
| Oserian Development Company Limited |
| Eco Roses |
| Utee Estate Ltd |
| Black Tulip Group |
| Golden Tulip Farms |
| Batian Farms |
| Laurel Investments |
| Others |
Supply & Pricing Matrix
EU Green Deal deforestation-free supply-chain regulations gate qualified supply and premium-tier pricing access for Kenyan rose exporters, compressing margins for uncertified farms while rewarding early compliance investments with preferred supplier status among German retail buyers.
Pricing Analysis
After-sales service bundling separates direct-contract farms from auction-dependent competitors, with cold-chain guarantees and traceability documentation now standard in annual supply agreements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and vase-life performance, with GLOBALG.A.P.-certified stems commanding substantial premiums over conventional auction lots. Cost compression in the standard tier intensifies because supermarket chains consolidate procurement leverage, while organic-certified supply scarcity renders that segment least price-sensitive among EU buyers.
Supply Chain Analysis
Certification/qualification gating concentrates export-eligible supply in Kenya, with Ethiopia and Uganda as secondary East African sources drawing from shared logistics infrastructure. Production rests on geothermal energy access, specialized greenhouse cladding, and phytosanitary-compliant propagation stock. Single-source vulnerability runs through Jomo Kenyatta International Airport cold-chain capacity, where perishable cargo slot allocation favors established forwarder relationships. Distribution runs through direct retail contracting, Dutch auction intermediation, and emerging Middle East wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water abstraction permit scarcity around Lake Naivasha props pricing for certified incumbent farms by capping expansion capacity across the supply basin.
For Market Incumbents: Extend geothermal energy self-sufficiency through lease renegotiations that lock in cost advantages against input price volatility. Deepen backward integration into captive cold-chain infrastructure to defend margin position against freight capacity concentration at Nairobi-Jomo Kenyatta International Airport. For New Entrants and Emerging Players: Direct-to-retail digital platforms in UK and Netherlands represent the most penetrable route, bypassing auction intermediaries and wholesaler dependency. Target organic certification conversion as the fastest-expanding margin pool, with blockchain-traceability integration as the primary go-to-market angle for ESG-compliant retail buyers. For Investors and Strategic Acquirers: Kenya Water Resources Authority permit reactivation announcements are the leading indicator that expansion-constrained supply will loosen, compressing incumbent pricing power. Long-term viability favors integrated operators with captive geothermal assets and established EU retail relationships. Watch EU organic label demand acceleration as the signal for premium-tier supply scarcity duration.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Lease Renegotiation | Captive energy supply locks in cost predictability against natural gas benchmark volatility. |
| Organic Certification Conversion | EU organic label scarcity rewards early adopters with price premiums and retail access. |
| Blockchain-IoT Traceability Deployment | Farm-to-shelf platforms satisfy EU Green Deal documentation requirements while reducing audit burden. |
| Direct Retail Contracting Expansion | Annual supply agreements with German chains displace auction intermediation for premium volumes. |
| Cold-Chain Infrastructure Investment | Integrated packhouse-to-airport temperature control secures preferred forwarder cargo slot allocation. |
Research Methodology
Document review covered customs export records, Kenya Water Resources Authority permit databases, and EU phytosanitary inspection reports, complemented by interviews with greenhouse operations managers, cold-chain logistics coordinators, Dutch auction house procurement specialists, and German supermarket category buyers. Secondary sources included Horticultural Crops Directorate export statistics, EFSA residue threshold documentation, and geothermal energy production data from Kenya Electricity Generating Company. Bottom-up farm-level production estimates triangulated against top-down export value aggregation.
Segmented outputs across product type, distribution channel, quality grade, and regional production cluster informed the analytical framework over the projection horizon. CAGRs derived from historical export volume trajectories adjusted for permit-constrained capacity expansion, EU regulatory compliance timeline acceleration, and Middle East retail penetration rates. Modeled inputs incorporated geothermal energy cost curves, fertilizer price volatility indices, and cold-chain infrastructure deployment schedules.
Inputs from Kenya Plant Health Inspectorate Service certification records and Water Resources Authority consumption reports were available through the study window; gaps in smallholder farm production data introduce uncertainty bands around aggregate supply estimates. Forecasts reflect assumptions regarding EU deforestation-free regulation enforcement intensity and geothermal lease renewal terms. A model refresh is warranted upon material change in Kenya Water Resources Authority permit allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market