
 Japan Compound Feed Market | 2026-2036
Japan Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Compound Feed Market Foresight
Precision fermentation and enzymatic processing is rewriting how Japanese compound feed manufacturers optimize protein conversion and reduce soybean dependency. Cargill Inc. leverages its global grain procurement network to secure cost-advantaged raw material flows into Japan. Feedone Co., Ltd anchors domestic production with vertically integrated milling complexes serving Kyushu poultry integrators. Charoen Pokphand Foods PCL extends its aquaculture feed expertise from Southeast Asia into Japanese marine fish farming operations.
Compound feed denotes industrially manufactured mixtures of grains, oilseeds, nutritional additives, and processing by-products formulated to deliver complete dietary requirements for targeted livestock species, with protein content typically ranging from 14% to 22% depending on animal class and growth stage. Poultry feed dominates volume throughput due to Japan's concentrated broiler and layer industries, while aquaculture feed commands premium formulation margins driven by marine species specialization. Grains and oilseeds constitute the foundational raw material base, though additive blends represent the fastest-growing margin pool as producers seek differentiation through functional nutrition claims.
METI's feed sustainability guidelines and Japan's Agricultural Standards (JAS) certification shape product formulation requirements and market access conditions for domestic and imported compound feed. The country's national pharmaceutical regulator oversees veterinary drug residue limits in feed additives, constraining antibiotic growth promoter usage. Stakeholders must monitor evolving carbon accounting rules for imported soy and corn, as supply chain disclosure mandates will soon differentiate compliant feed suppliers from legacy operators.
Market Dynamics
Precision fermentation and enzymatic processing are compressing formulation costs while METI tightens carbon disclosure rules for imported soy and corn, forcing feed manufacturers to requalify supplier bases and reformulate protein matrices.
Growth Catalysts
- Feed Sustainability Guidelines:METI mandates reduced carbon intensity in animal agriculture, compelling commercial livestock farms to source certified low-emission compound feed formulations.
- Dairy Belt Expansion:Hokkaido's concentrated dairy operations are scaling precision-formulated feed procurement to optimize milk yield per cow and reduce nitrogen waste runoff.
- Enzymatic Processing:Protease and carbohydrase additives are improving protein digestibility in poultry and aquaculture feeds, lowering soybean inclusion rates without compromising amino acid profiles.
Market Restraints
- Soybean Import Dependency:Japan sources over 90% of soy from North and South American suppliers, exposing compound feed margins to currency volatility and maritime freight disruptions.
- JAS Certification Complexity:Japan Agricultural Standards impose multi-year compliance timelines for imported feed additives, delaying market entry for novel nutritional technologies.
- Antibiotic Growth Promoter Limits:PMDA residue restrictions constrain conventional disease prevention strategies in poultry and swine operations, requiring costly alternative health management systems.
Strategic Opportunities
- Marine Fish Farming:Kyushu and Shikoku aquaculture zones lack specialized high-protein marine feed capacity, creating white space for premium formulation entrants with species-specific expertise.
- Carbon Accounting Differentiation:Early adoption of supply chain disclosure protocols aligned with METI guidelines will segment compliant feed suppliers from legacy operators in procurement tenders.
- Functional Additive Convergence:Combining precision fermentation-derived proteins with phytogenic compounds enables premium positioning in layer and broiler feed segments.
Industry Challenges
- Formulation Talent Scarcity:Japan's agricultural universities produce insufficient feed science specialists to staff expanding R&D functions at domestic milling complexes.
- Legacy System Integration:Smaller prefectural feed cooperatives lack capital to retrofit batch control systems for precision additive dosing, creating quality consistency gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Compound Feed Market |
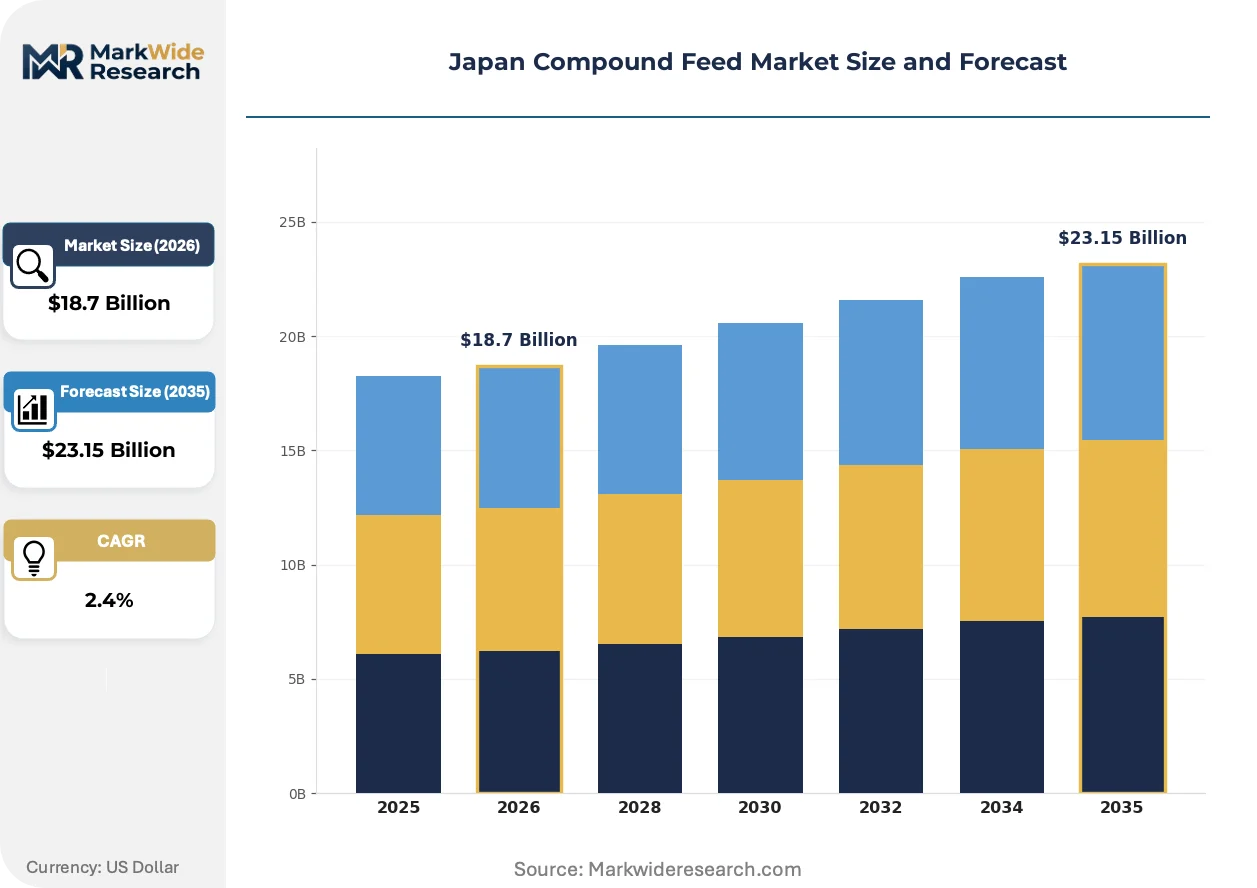
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Cattle Feed, Aquaculture Feed, Swine Feed Raw Material: Grains, Oilseeds, By-products, Additives End User: Commercial Farms, Feed Manufacturers, Resellers, Independent Livestock Producers Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesalers |
| Companies Covered | Alltech Inc., Charoen Pokphand Foods PCL, Feedone Co., Ltd, Land O’Lakes, New Hope Group, Cargill Inc., Archer Daniels Midland (ADM), Guangdong Haid Group Co., Ltd, SHV (Nutreco NV), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Compound Feed Market Shifts & Advancements
Active protein sourcing strategies and regulatory disclosure mandates are reconfiguring how Japanese compound feed manufacturers design formulations, qualify suppliers, and compete for livestock integrator contracts.
Fermentation-derived single-cell proteins are migrating from aquaculture feed niche applications into poultry and swine formulations. Large-scale broiler integrators in Kyushu are trialing 5-10% fishmeal replacement rates with microbial biomass. This substitution trajectory is compressing traditional marine protein price premiums while opening formulation flexibility for species-specific amino acid optimization.
METI's evolving carbon accounting framework for agricultural supply chains now requires granular disclosure of embedded emissions in imported corn and soy. Feed manufacturers must requalify North American and Brazilian suppliers against new verification protocols. Premium compound feed segments in Hokkaido's dairy belt are already sourcing identity-preserved low-carbon grain streams to maintain contract eligibility with sustainability-focused milk cooperatives.
Livestock integrators are consolidating feed procurement through direct mill relationships rather than agricultural cooperative intermediaries. Kyushu's poultry corridor operations now negotiate volume contracts with compound feed producers for customized additive blends and just-in-time delivery scheduling. This disintermediation concentrates formulation expertise at fewer manufacturing sites while squeezing margins for smaller regional mills dependent on cooperative distribution networks.
Japan Compound Feed Market Segmentation
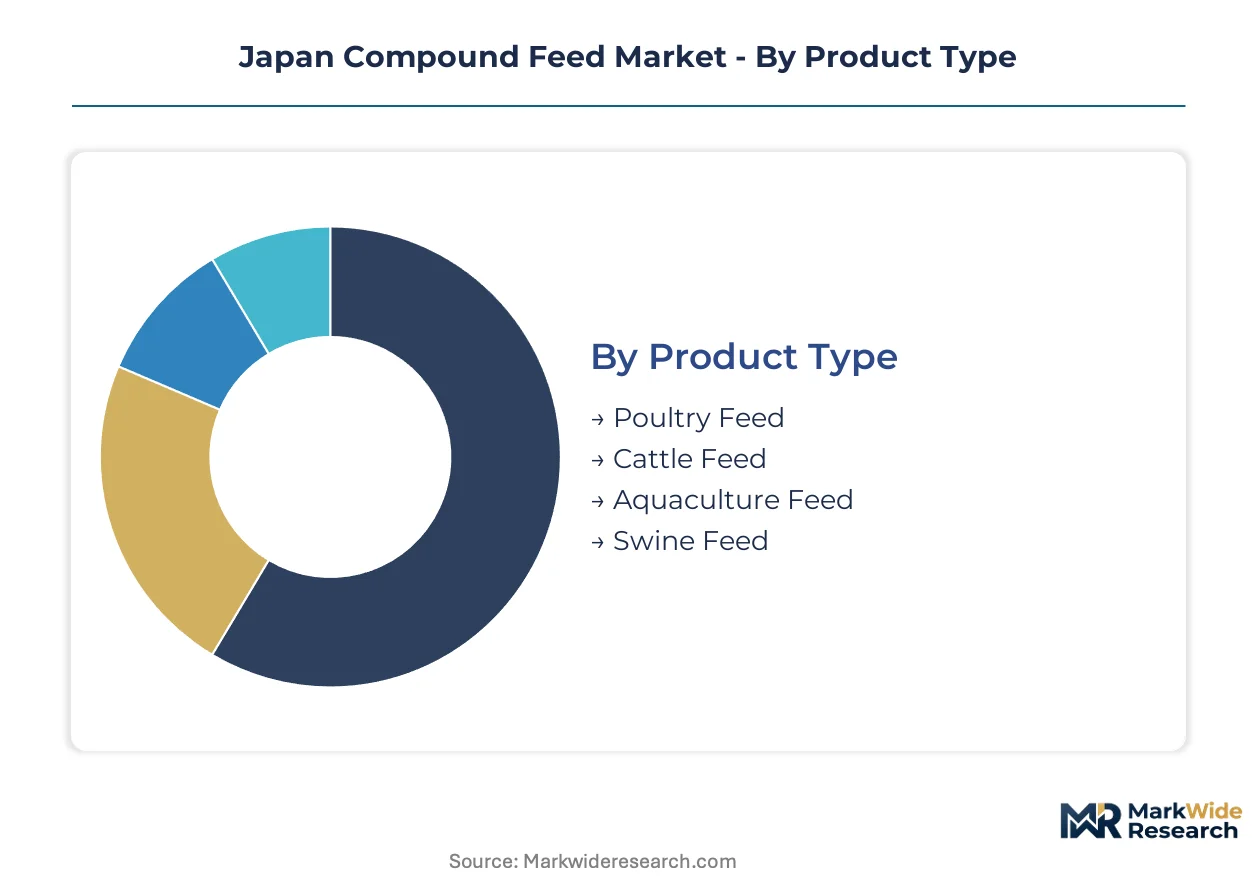
Segmentation in Japan's compound feed market reveals how procurement cycles, formulation complexity, and channel economics fragment demand across livestock species and customer types. Understanding these divisions exposes where margin pools concentrate and which supply configurations capture volume.
Product Type:
Turnover velocity varies sharply across species formulations, with poultry feed cycling fastest due to compressed broiler growth periods and aquaculture feed moving slowest given marine species extended production timelines.
- Poultry Feed:Formulations deliver 14-20% protein content optimized for rapid broiler weight gain and layer egg production consistency. Kyushu's vertically integrated poultry corridor drives bulk procurement of precision-formulated rations with enzyme-enhanced digestibility profiles.
- Aquaculture Feed:High-protein marine formulations ranging 35-50% protein content incorporate specialized lipid profiles for yellowtail and sea bream species. Kyushu and Shikoku marine farming zones generate premium-margin demand for species-specific extruded feeds with extended water stability.
- Cattle Feed:Hokkaido dairy operations dominate offtake with fiber-optimized rations balancing rumen health and milk yield metrics.
- Swine Feed:Formulations emphasize lysine-to-energy ratios for lean meat conversion in western Japan's concentrated pork production belt.
Poultry feed dominates installed base. Aquaculture feed is where expansion concentrates.
Raw Material:
Cost tier stratification separates commodity foundation inputs from value-added functional ingredients that command formulation premiums.
- Grains:Corn and wheat constitute the caloric backbone of compound feed matrices, with Hokkaido dairy cooperatives increasingly sourcing identity-preserved low-carbon grain streams to satisfy METI disclosure requirements for contracted milk processors.
- Additives:Enzyme blends, single-cell proteins from precision fermentation, and phytogenic compounds represent the fastest-climbing margin pool as manufacturers differentiate through functional nutrition claims and reduced antibiotic dependency.
- Oilseeds:Soybean meal provides essential amino acid profiles despite Japan's structural dependency on North and South American imports exposed to currency and freight volatility.
- By-products:Wheat bran, rice polish, and food processing residues offer cost-competitive fiber and energy substitution in ruminant formulations.
Grains anchor volume throughput. Additives capture expanding value share.
End User:
Customer scale determines formulation customization depth and contract structure, with large commercial operations bypassing traditional cooperative intermediaries.
- Commercial Farms:Hokkaido dairy belt and Kyushu poultry corridor operations negotiate direct mill relationships for customized additive blends, just-in-time delivery scheduling, and volume pricing structures that disintermediate agricultural cooperatives.
- Feed Manufacturers:Compound feed producers sourcing intermediate premixes and base mixes for further processing at regional milling facilities concentrate procurement through long-term supply agreements with global grain traders.
- Resellers:Agricultural cooperative networks and independent distributors serve fragmented independent livestock producers with standardized formulation portfolios and credit-extended terms.
- Independent Livestock Producers:Smaller prefectural operations lacking capital for precision feeding systems rely on cooperative-supplied rations with limited formulation flexibility.
Commercial farms drive specification intensity. Independent producers sustain cooperative channel viability.
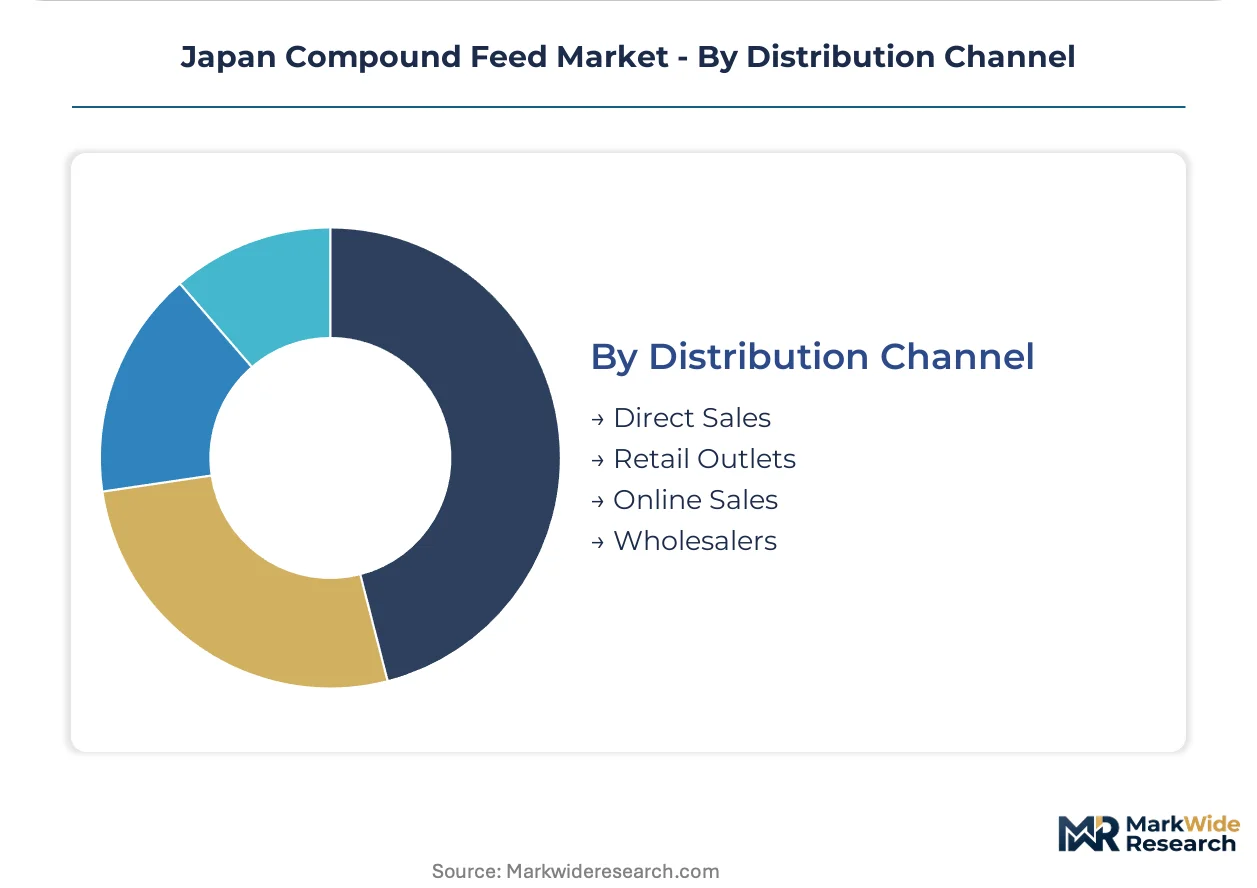
Distribution Channel:
Channel selection correlates with customer scale and formulation complexity requirements, compressing margin structures for intermediary-dependent routes.
- Direct Sales:Volume contracts between compound feed manufacturers and large livestock integrators eliminate distribution markups while enabling customized scheduling and formulation co-development for Kyushu poultry and Hokkaido dairy operations.
- Wholesalers:Regional feed distributors aggregate demand from smaller commercial farms and resellers, maintaining inventory buffers that add cost but reduce supply uncertainty for geographically dispersed operations.
- Retail Outlets:Agricultural supply stores serve independent livestock producers with bagged feed products and limited technical support, concentrating in prefectural farming centers with established cooperative presence.
- Online Sales:Digital procurement platforms emerging for specialty additives and small-lot formulations remain marginal to bulk compound feed distribution given logistics constraints and just-in-time delivery requirements.
Direct sales capture specification-intensive demand. Wholesalers retain intermediary role for fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial livestock integrators in Hokkaido and Kyushu drive specification-intensive procurement, while prefectural cooperatives sustain fragmented demand across Japan's secondary agricultural zones.
Hokkaido
Dairy belt operations scale precision-formulated feed procurement to optimize milk yield metrics and reduce nitrogen waste runoff. METI's carbon disclosure requirements for contracted milk processors accelerate identity-preserved low-carbon grain sourcing. Sapporo-based milling complexes serve concentrated Holstein operations with fiber-optimized rations.
Kyushu
Vertically integrated poultry corridors generate bulk demand for enzyme-enhanced broiler and layer formulations. PMDA residue restrictions compel alternative health management investments across concentrated broiler operations. Kumamoto and Miyazaki prefectures anchor marine fish farming zones requiring specialized high-protein extruded feeds.
Kanto
Metropolitan adjacency supports niche organic and specialty feed segments serving peri-urban livestock operations. Japan Agricultural Standards certification complexity delays novel additive market entry for regional distributors. Ibaraki and Tochigi prefectures maintain mixed livestock bases with cooperative-dependent procurement patterns.
Chubu
Industrial feed manufacturing capacity concentrates in Nagoya-adjacent milling corridors serving central Japan's fragmented pork and poultry bases. Freight cost advantages from Port of Nagoya grain terminals attract bulk import consolidation. Shizuoka's dairy operations represent secondary demand nodes with limited direct mill contracting scale.
Tohoku
Reconstituting livestock bases following regional disruptions create variable feed demand with limited specification intensity. Prefectural agricultural cooperatives retain dominant channel control over smaller-scale cattle and swine producers. Sendai distribution hubs intermediate between Hokkaido-sourced grains and dispersed regional offtake.
Japan Compound Feed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structure consolidates around vertically integrated milling complexes and global grain traders serving large integrators, while fragmented prefectural cooperatives sustain smaller regional mills. Three archetypes dominate: global traders with cost-advantaged raw material flows, domestic vertically integrated producers with direct integrator relationships, and regional cooperative-affiliated mills dependent on intermediary distribution. Competitive moves concentrate on direct contracting disintermediation and carbon-accounting supplier requalification.
Among global trading houses, Cargill Inc. and Archer Daniels Midland occupy positions anchored by grain procurement networks. Domestic integrated producers include Feedone Co., Ltd, representing the vertically complex archetype serving Kyushu poultry corridors. Charoen Pokphand Foods PCL exemplifies aquaculture feed specialization extending from Southeast Asian marine farming expertise. These three represent distinct strategic positions without implying specific market shares or operational claims.
| Leading Market Players |
|---|
| Alltech Inc. |
| Charoen Pokphand Foods PCL |
| Feedone Co., Ltd |
| Land O'Lakes |
| New Hope Group |
| Cargill Inc. |
| Archer Daniels Midland (ADM) |
| Guangdong Haid Group Co., Ltd |
| SHV (Nutreco NV) |
| Others |
Supply & Pricing Matrix
Soybean import dependency from North and South American suppliers compresses pricing power across Japanese compound feed tiers while forcing supply chain reconfiguration toward identity-preserved low-carbon grain streams. Currency volatility and maritime freight disruptions determine spread differentials between premium certified formulations and commodity-standard rations.
Pricing Analysis
Cost-plus contracts indexed to CBOT soybean futures and CME corn benchmarks dominate procurement agreements between Hokkaido dairy cooperatives and compound feed manufacturers. Price differentiation separates JAS-certified additive-enhanced formulations from economy-tier cooperative-supplied rations. Cost compression in standard poultry feeds intensifies as Kyushu integrators consolidate direct mill relationships. Independent livestock producers in prefectural cooperative channels exhibit highest price sensitivity, while commercial dairy operations prioritize yield-optimization over unit cost.
Supply Chain Analysis
Japan's feed additive import controls under PMDA veterinary drug residue limits constrain novel ingredient flows from non-approved suppliers. Raw material sourcing draws from Brazilian soy crushing operations, US corn belt terminals, and Australian wheat exporters. Single-source vulnerability concentrates in North American soy logistics chains exposed to Panama Canal transit constraints. Distribution runs through vertically integrated milling complexes serving Kyushu poultry corridors and Hokkaido dairy belts, with cooperative networks sustaining fragmented prefectural coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation science expertise scarcity defines competitive positioning in Japan's compound feed sector, with agricultural universities producing insufficient feed science specialists to staff expanding R&D functions at domestic milling complexes.
For Market Incumbents: Harden supplier requalification protocols against METI's evolving carbon disclosure mandates to preempt procurement disqualification from sustainability-focused milk cooperatives. Deepen backward integration into precision fermentation capacity for single-cell protein production, reducing exposure to marine protein price volatility and antibiotic growth promoter restrictions.
For New Entrants and Emerging Players: Pursue specialized marine fish feed formulation gaps in Kyushu and Shikoku aquaculture zones where domestic capacity lags species-specific demand. Target direct contracting relationships with mid-scale dairy operations in Hokkaido's secondary production belts bypassed by major integrators, leveraging technical advisory services as entry wedge.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated producers with captive additive blending capabilities and certified low-carbon grain sourcing infrastructure. Acquisition candidates should demonstrate established direct mill relationships with Kyushu poultry or Hokkaido dairy integrators. Monitor PMDA approval timelines for novel enzymatic additives as inflection signal for formulation margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Reduces soybean dependency while meeting METI carbon intensity targets for contracted dairy operations. |
| JAS Certification Investment | Accelerates market entry for novel additive technologies constrained by multi-year compliance timelines. |
| Direct Mill Relationship Expansion | Captures procurement consolidation trend as livestock integrators disintermediate agricultural cooperatives. |
| Marine Feed Specialization | Addresses supply gap in Kyushu yellowtail and sea bream farming zones lacking domestic formulation expertise. |
| Carbon Accounting Protocol Adoption | Differentiates compliant suppliers in METI-mandated procurement tenders for low-emission feed formulations. |
Research Methodology
Operator-level perspectives from compound feed plant managers, livestock procurement officers at dairy cooperatives, poultry integrator nutritionists, and agricultural cooperative distribution heads anchored the qualitative base. Secondary validation drew from METI feed sustainability guideline releases, PMDA veterinary drug residue limit updates, Japan Agricultural Standards certification databases, and customs trade records for soy and corn imports. Bottom-up volume estimates from prefectural milling capacity and top-down demand calibration from livestock inventory data were triangulated.
Scenario-bracketing around regulatory implementation pace and commodity price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included livestock species, raw material composition tiers, end-user scale categories, and distribution channel structures. CAGRs were derived from trend extrapolation of procurement intensity metrics and livestock population projections. Forecast inputs incorporated enzyme adoption curves in poultry formulations and carbon disclosure compliance rates among grain suppliers.
Sensitivities concentrate around METI carbon accounting mandate enforcement timing, PMDA novel additive approval velocity, and Brazilian soy export logistics disruptions. Forecasts reflect documented assumptions regarding livestock herd stability and cooperative channel retention rates. Material shifts in JAS certification requirements or maritime freight cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Post-Harvest Treatment Market