
 Reusable Resuscitators Market | 2026-2036
Reusable Resuscitators Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Resuscitators Market Analytics
The EU Green Deal is decoupling European hospital procurement from disposable resuscitator dependence. Laerdal Medical anchors Scandinavian emergency medical services through silicone product specialization. Ambu A/S competes across European clinics with thermoplastic elastomer lines that sustain lower lifecycle costs. Medline Industries, LP extends North American hospital contracts through bag-valve-mask volume manufacturing.
Reusable resuscitators are manually operated or oxygen-assisted breathing support devices constructed from autoclavable silicone, PVC, or thermoplastic elastomers, designed for repeated sterilization cycles between patients in emergency and critical care settings. Silicone resuscitators dominate hospital procurement due to thermal stability across steam sterilization protocols, while bag-valve-mask configurations lead emergency medical services adoption because of rapid deployment requirements in field settings. PVC alternatives occupy price-sensitive clinic segments where replacement frequency remains elevated despite reusability claims.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape material selection and biocompatibility testing burdens for manufacturers entering either jurisdiction. ISO 10651 performance standards for lung ventilators and resuscitators establish minimum delivered tidal volume tolerances that silicone constructions more reliably satisfy across extended use cycles. Stakeholders must monitor evolving EPA guidance on medical device reprocessing waste streams alongside state-level hospital sustainability procurement mandates.
Market Dynamics
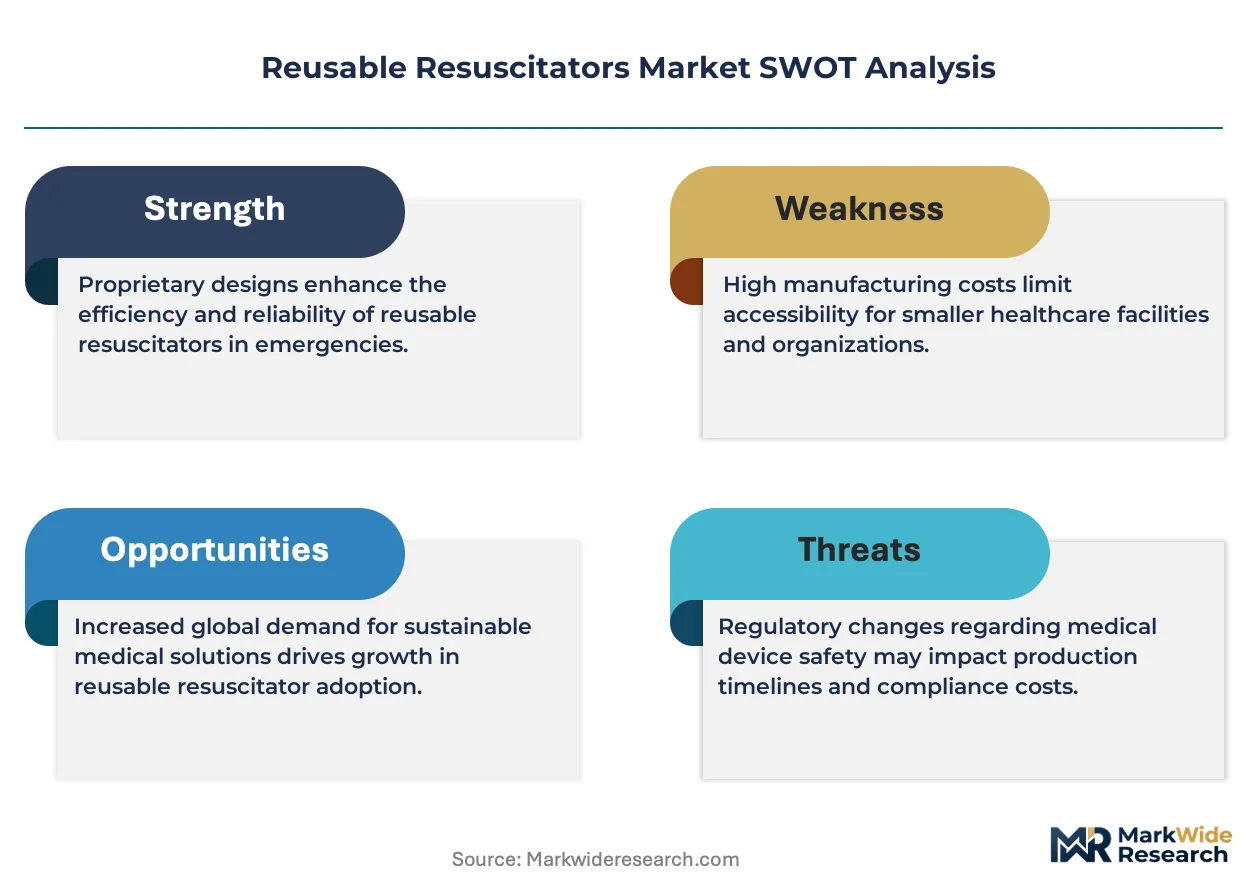
Hospital sustainability mandates are compressing procurement timelines for autoclavable silicone resuscitators as waste reduction targets harden into contract requirements across emergency medical services.
Growth Catalysts
- EU Green Deal procurement rules:German emergency medical services retrofit programs now specify durable resuscitation equipment in tender documents. Danish hospitals align capital budgets with circular economy purchasing criteria.
- Silicone thermal stability:Steam sterilization protocols favor silicone constructions that withstand repeated autoclave cycles without material degradation. Critical care units prioritize devices with validated lifecycle performance.
- Bag-valve-mask emergency deployment:Field settings demand rapid-assembly configurations that oxygen-assisted resuscitators provide. Ambulance fleets standardize on modular designs for interoperability.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in select industrial regions, exposing manufacturers to input volatility. Alternative thermoplastic formulations face performance trade-offs in tidal volume consistency.
- EU MDR technical documentation burden:Biocompatibility testing requirements for reusable device materials extend certification timelines. Small manufacturers struggle with notified body capacity constraints.
- Single-use device substitution threat:PVC disposables retain cost advantages in price-sensitive clinic segments despite reusability claims. Cross-contamination liability concerns drive some facilities toward disposable alternatives.
Strategic Opportunities
- India clinic network expansion:Primary health centers in tier-two cities lack standardized resuscitation equipment. Central government health infrastructure programs create procurement pipelines for autoclavable devices.
- ISO 10651 performance tier differentiation:Manufacturers can segment offerings by validated tidal volume tolerance ranges. Premium positioning targets tertiary hospitals with intensive care unit requirements.
- Reprocessing service bundling:Third-party sterilization providers offer lifecycle management contracts that reduce hospital capital outlay. Equipment-as-a-service models penetrate budget-constrained emergency medical services.
Industry Challenges
- Autoclave validation technician shortage:Hospital sterile processing departments lack personnel trained on reusable resuscitator reprocessing protocols. Training program development stretches implementation timelines.
- Legacy device integration complexity:New silicone constructions must interface with existing oxygen supply infrastructure. Adapter standardization delays fleet-wide upgrades.
- FDA 510(k) predicate device navigation:Material substitutions require substantial equivalence demonstrations that compress R&D budgets. Clearance pathway uncertainty deters formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Resuscitators Market |
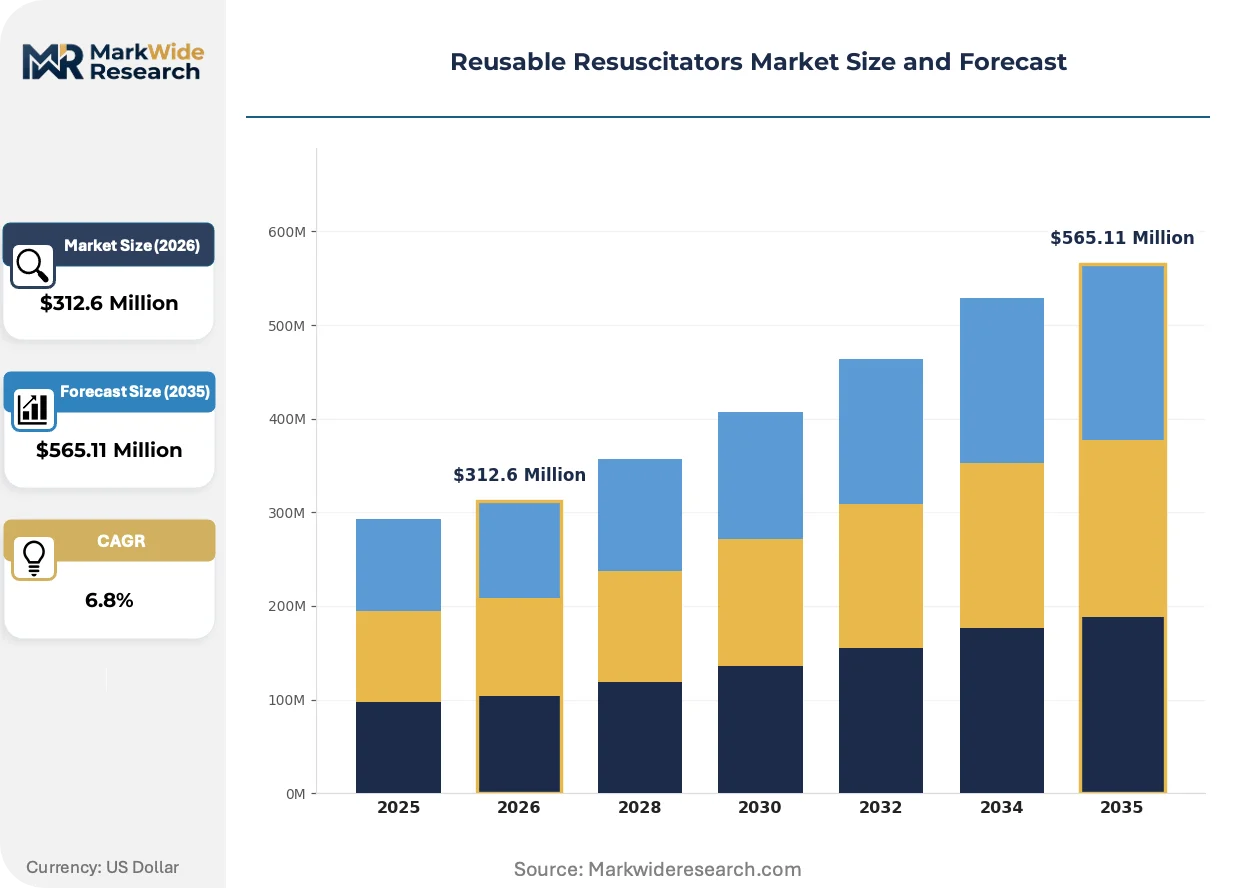
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
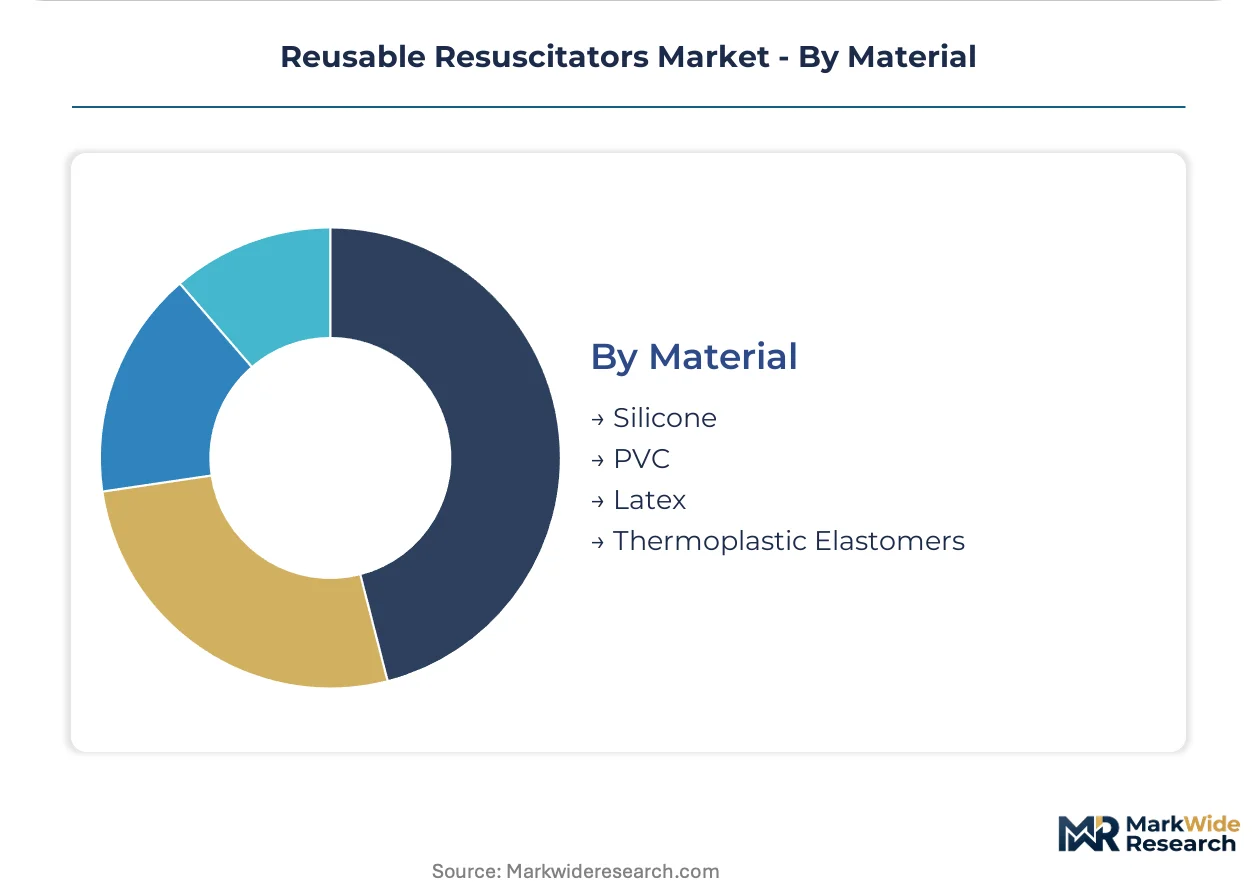
| Segmentation | Product Type: Manual Resuscitators, Bag-Valve-Mask, Oxygen Masks, Pulmonary Devices Application: Emergency Medical Services, Hospitals, Clinics, Home Care End User: Healthcare Professionals, First Responders, Patients, Caregivers Material: Silicone, PVC, Latex, Thermoplastic Elastomers |
| Companies Covered | Medline Industries, LP, Hopkins Medical Products, Laerdal Medical, PERSYS MEDICAL, HUM Gesellschaft für Homecare und Medizintechnik mbH, WEINMANN Emergency Medical Technology GmbH + Co. KG, ResMed, Inc., Teleflex Incorporated, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Resuscitators Market Evolving Landscape
Material science advances and regulatory waste-reduction mandates are converging to accelerate hospital transitions from disposable to autoclavable resuscitation platforms.
Thermoplastic elastomer formulations are electrifying product development pipelines by combining silicone-equivalent thermal stability with injection-molding cost structures. Scandinavian emergency medical services deploy these hybrid materials in field trials for durability validation. The technology is electrifying competitive positioning among mid-tier manufacturers previously excluded from premium hospital contracts.
EU MDR biocompatibility testing requirements are hardening material selection criteria for reusable device manufacturers seeking CE marking. Notified bodies now demand extended-use cycle validation data that silicone constructions more readily supply. German hospitals respond by consolidating procurement around suppliers with established MDR technical documentation.
Hospital purchasing departments are unbundling after-sales service from equipment acquisition, favoring standalone sterilization validation contracts. Emergency medical services in Denmark and Sweden pilot third-party reprocessing arrangements that transfer lifecycle liability. This behavioral shift concentrates most visibly in Nordic countries with mature healthcare outsourcing frameworks.
Reusable Resuscitators Market Segmentation
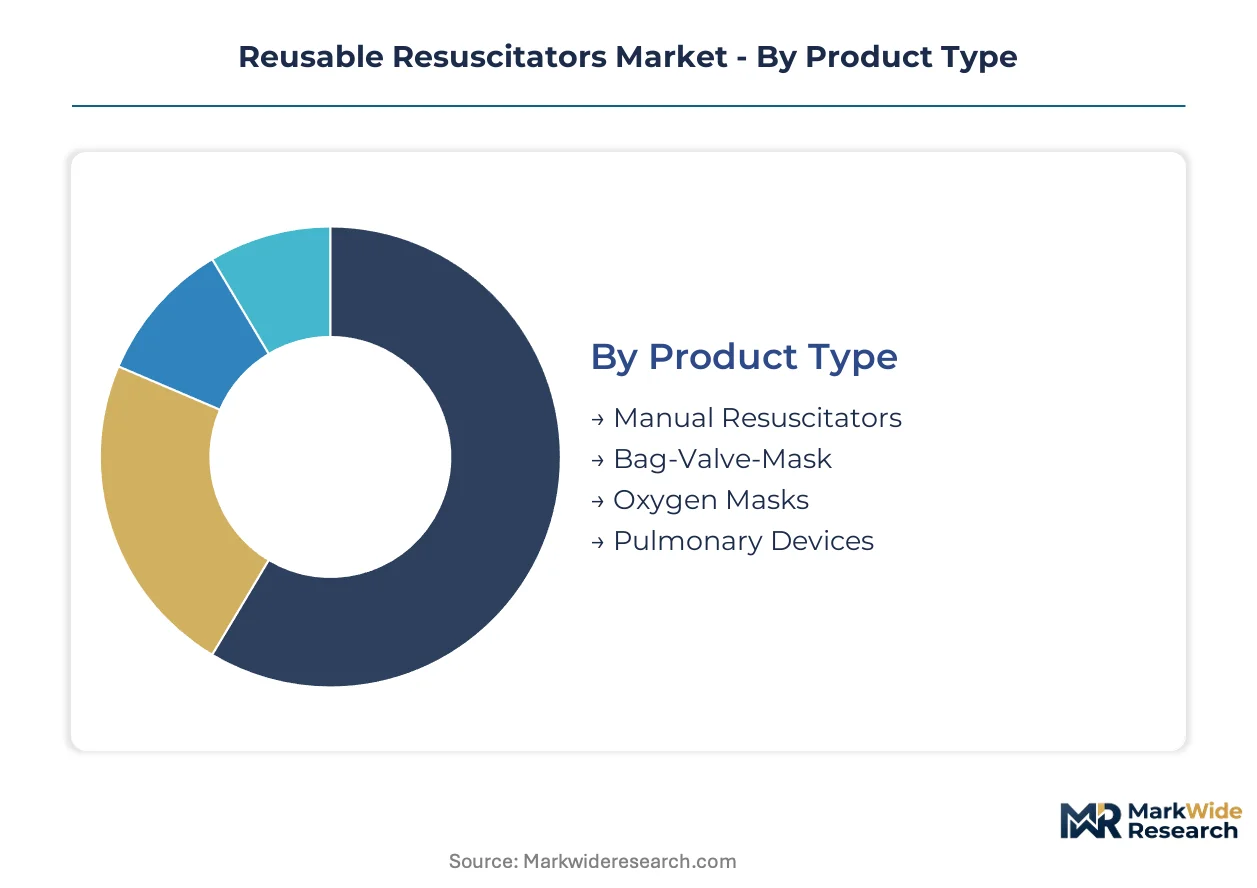
Procurement patterns across reusable resuscitators diverge sharply by clinical setting and sterilization protocol compatibility. Hospital capital committees weight material lifecycle costs against emergency medical services' field-deployment priorities.
Product Type:
Replacement cycles accelerate where device durability intersects with sterilization frequency demands.
- Bag-Valve-Mask:Modular assemblies with detachable face masks and oxygen reservoir bags dominate ambulance fleet standardization. German emergency medical services retrofit programs specify these configurations for rapid airway management in pre-hospital settings.
- Manual Resuscitators:Hand-powered breathing support devices with self-inflating bags and pressure-limiting valves anchor intensive care unit equipment pools. Danish hospitals consolidate procurement around autoclavable silicone constructions that withstand steam sterilization protocols.
- Oxygen Masks:Reusable oxygen delivery interfaces with adjustable flow connectors serve post-resuscitation stabilization.
- Pulmonary Devices:Specialized lung expansion equipment with calibrated pressure monitoring occupies niche respiratory therapy applications.
Bag-Valve-Mask sits at the top of the volume ranking, with Manual Resuscitators climbing the fastest.
Application:
Cost tier stratification separates capital-intensive hospital deployments from budget-constrained clinic networks.
- Hospitals:Tertiary care centers with centralized sterile processing departments drive silicone resuscitator adoption through validated reprocessing workflows. EU Green Deal procurement rules now embed circular economy criteria into Danish and German hospital tender documents.
- Emergency Medical Services:Ambulance fleets prioritize rapid-assembly bag-valve-mask systems with standardized oxygen connector interfaces. Field durability requirements favor thermoplastic elastomer formulations emerging from Scandinavian material science pipelines.
- Clinics:Primary health centers in price-sensitive segments balance acquisition cost against replacement frequency.
- Home Care:Patient-operated resuscitation support occupies limited indications with specialized training requirements.
Hospitals capture the dominant procurement value, while Emergency Medical Services expand most quickly under fleet modernization mandates.
End User:
Training certification requirements segment demand by clinical competency depth and liability exposure.
- Healthcare Professionals:Physicians and respiratory therapists with advanced airway management credentials operate fully featured resuscitation systems. EU MDR technical documentation requirements now demand validated performance data that concentrates procurement among established suppliers.
- First Responders:Paramedics and emergency technicians deploy standardized configurations with simplified assembly protocols. German emergency medical services specify interoperable designs across state-level ambulance contracts.
- Patients:Self-administered breathing support remains restricted to prescribed home care scenarios.
- Caregivers:Family members with basic training operate simplified manual resuscitators under clinical supervision.
Healthcare Professionals anchor procurement volume, with First Responders gaining share fastest through emergency services expansion.
Material:
Supply concentration for medical-grade elastomers shapes manufacturer sourcing strategies and pricing structures.
- Silicone:Platinum-cured elastomers with thermal stability across 100+ steam autoclave cycles dominate hospital procurement. FDA 510(k) clearance pathways favor silicone predicates with established biocompatibility profiles.
- Thermoplastic Elastomers:Injection-moldable formulations combining silicone-equivalent heat resistance with manufacturing cost advantages electrify mid-tier competitive positioning. Scandinavian field trials validate durability for emergency medical services deployment.
- PVC:Lower-cost polymers with limited thermal cycling tolerance serve price-sensitive clinic segments.
- Latex:Natural rubber formulations face declining adoption due to allergen sensitization risks.
Silicone maintains volume leadership, with Thermoplastic Elastomers climbing fastest as injection-molding scale economies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reusable resuscitator manufacturing originated in post-war European medical device clusters, where Danish and German engineering traditions established autoclavable silicone as the clinical standard. These regional capabilities now shape procurement patterns across emergency medical services and hospital systems worldwide.
Germany
German emergency medical services retrofit programs specify durable resuscitation equipment in state-level tender documents. EU Green Deal procurement rules embed circular economy criteria into hospital capital budgets. The Baden-Württemberg medical technology corridor concentrates silicone molding expertise serving Scandinavian and Central European ambulance fleets.
Denmark
Danish hospitals align procurement with circular economy purchasing criteria through centralized sterile processing departments. EU MDR technical documentation requirements concentrate demand among established suppliers with validated lifecycle performance data. Copenhagen anchors emergency medical services pilot programs for third-party reprocessing arrangements.
United States
FDA 510(k) clearance pathways shape material selection and biocompatibility testing burdens for manufacturers entering the jurisdiction. EPA guidance on medical device reprocessing waste streams influences state-level hospital sustainability procurement mandates. Minnesota and Illinois host bag-valve-mask volume manufacturing operations extending North American hospital contracts.
India
Primary health centers in tier-two cities lack standardized resuscitation equipment, creating procurement pipelines for autoclavable devices. Central government health infrastructure programs drive clinic network expansion. Maharashtra and Karnataka medical device clusters develop thermoplastic elastomer formulations for price-sensitive segments.
Sweden
Scandinavian emergency medical services deploy thermoplastic elastomer formulations in field trials for durability validation. Mature healthcare outsourcing frameworks concentrate third-party reprocessing arrangements in Nordic procurement. Stockholm-Gothenburg medical technology corridors specialize in silicone product lines for premium hospital contracts.
Reusable Resuscitators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material validation and sterilization protocol compatibility. The vendor base organizes into three tiers: silicone specialists with established MDR documentation, thermoplastic elastomer innovators scaling injection-molding cost structures, and PVC commodity suppliers serving replacement-heavy clinic segments. Strategic moves concentrate on capacity expansion for medical-grade elastomer processing and technology licensing for hybrid material formulations.
Among Scandinavian silicone specialists, Laerdal Medical exemplifies premium-tier positioning through autoclavable product lines. Danish-based Ambu A/S occupies a position within thermoplastic elastomer innovation, representing mid-tier competitive repositioning. North American volume manufacturers include Medline Industries, LP, which anchors bag-valve-mask supply through scale-driven fabrication. German engineering-focused entities such as WEINMANN Emergency Medical Technology GmbH + Co. KG and HUM Gesellschaft für Homecare und Medizintechnik mbH sit within precision-manufacturing archetypes serving emergency medical services retrofit programs.
| Leading Market Players |
|---|
| Medline Industries, LP |
| Hopkins Medical Products |
| Laerdal Medical |
| PERSYS MEDICAL |
| HUM Gesellschaft für Homecare und Medizintechnik mbH |
| WEINMANN Emergency Medical Technology GmbH + Co. KG |
| ResMed, Inc. |
| Teleflex Incorporated |
| Ambu A/S |
| Others |
Value Network & Pricing Analysis
Silicone-to-thermoplastic elastomer tier divergence separates hospital-grade autoclavable units from clinic-grade alternatives, concentrating pricing power among MDR-validated suppliers while supply chains bifurcate between platinum-cured elastomer clusters and injection-molding scale economies. German and Danish procurement contracts now embed lifecycle cost calculations that compress margins for PVC commodity suppliers unable to validate extended sterilization performance.
Pricing Analysis
Three-tier pricing structure across premium silicone, validated thermoplastic, and economy PVC levels anchors procurement negotiations, with ISO 10651 certification grade and validated autoclave cycle count serving as primary price differentiation drivers. Cost compression in thermoplastic tiers is intensifying because Scandinavian field trials demonstrate silicone-equivalent durability at lower manufacturing scale. Clinic networks in India exhibit highest price sensitivity, while German tertiary hospitals prioritize lifecycle-validated premium tiers regardless of acquisition premium.
Supply Chain Analysis
Freight cost volatility from medical-grade silicone production centers in Germany, Denmark, and the United States shapes regional procurement strategies for North American hospital systems. Raw material flows draw from platinum-cured elastomer feedstocks, thermoplastic polymer resins, and precision-molded valve components. Single-source vulnerability concentrates in specialty silicone suppliers serving FDA 510(k) predicate device manufacturers. Distribution runs through hospital GPO contracts, emergency medical services fleet procurement offices, and clinic network central purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic elastomer scale economies are compressing premium-tier production costs, expanding margin capture for manufacturers with validated MDR documentation and established autoclave cycle performance data.
For Market Incumbents: Lock in silicone supply agreements with Baden-Württemberg molding clusters before thermoplastic alternatives achieve full MDR validation parity. Deepen backward integration into platinum-cured elastomer production to defend against emerging injection-molding competitors from Maharashtra medical device corridors. Prioritize CE marking pathway acceleration for next-generation hybrid material formulations. For New Entrants and Emerging Players: E-commerce direct procurement channels offer lowest-friction entry into Indian tier-two clinic networks lacking standardized resuscitation equipment. Target primary health centers in Karnataka and Maharashtra with thermoplastic elastomer lines priced below silicone alternatives. Pursue equipment-as-a-service bundling with third-party sterilization providers to reduce hospital capital barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation requirements exceed small-manufacturer compliance capacity. Frame long-term viability around MDR-validated lifecycle data assets rather than pure manufacturing scale. Monitor notified body queue lengths as inflection indicator for acquisition timing in Scandinavian and German specialty manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR technical documentation concentrates procurement among validated suppliers in Denmark and Germany. |
| Backward Integration into Elastomer Production | Captive silicone supply secures margin defense against thermoplastic displacement in hospital segments. |
| Hospital System Partnership | Long-term GPO contracts with German tertiary centers anchor volume visibility across sterilization protocol upgrades. |
| Equipment-as-a-Service Launch | Third-party reprocessing bundling penetrates budget-constrained emergency medical services in Nordic markets. |
| Reimbursement Strategy Development | Lifecycle cost validation supports premium positioning within EU Green Deal circular economy procurement frameworks. |
Research Methodology
Multiple input streams — hospital procurement database analysis, emergency medical services fleet operator interviews, and regulatory filing review — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged biomedical engineers, sterile processing department managers, GPO contracts specialists, and ambulance fleet procurement officers across German, Danish, and North American healthcare systems. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation databases, hospital sustainability procurement mandates, and ISO 10651 performance standard revisions. Bottom-up equipment deployment counts and top-down healthcare expenditure allocations were triangulated to anchor volume projections.
Data-stream reconciliation across product type, application setting, material formulation, and end-user certification requirements shaped the analytical framework throughout the projection horizon. CAGRs were derived from sterilization protocol transition rates and fleet modernization cycle timing. Industry-specific forecast inputs included EU Green Deal procurement mandate implementation timelines, autoclave validation technician training program expansion rates, and thermoplastic elastomer durability validation completion schedules.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic elastomer field validation would alter the outlook for silicone demand concentration. Forecasts reflect assumptions regarding MDR notified body capacity expansion, medical-grade silicone supply stability, and emergency medical services retrofit program funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cough Assist Devices Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Allografts Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Arthroscopy Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Latin America Breast Biopsy Needle Market