
 Non-Surgical Rhinoplasty Market | 2026-2036
Non-Surgical Rhinoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Surgical Rhinoplasty Market Intelligence
Board certification in facial plastic surgery is redrawing competitive boundaries in non-surgical rhinoplasty. AbbVie Inc. leverages its Allergan Aesthetics portfolio to sustain channel dominance across North American clinics. Merz Pharma anchors European supply through its Radiesse calcium hydroxylapatite franchise. Galderma S.A. competes on hyaluronic acid innovation with its Restylane Lyft positioning for nasal dorsum augmentation.
Non-surgical rhinoplasty employs injectable fillers—hyaluronic acid, calcium hydroxylapatite, or poly-L-lactic acid—delivered via microcannula or needle into the nasal subcutaneous plane to reshape contour without osteotomy. The procedure addresses dorsal humps, tip projection deficits, and post-rhinoplasty irregularities with 15-30 minute clinic visits and minimal downtime. Hyaluronic acid formulations occupy the largest volume share due to reversibility with hyaluronidase and favorable safety profiles, while calcium hydroxylapatite commands premium positioning for structural support in nasal bridge augmentation. Application demand skews heavily toward cosmetic improvement, though functional correction of post-traumatic deformities represents a faster-growing subsegment as otolaryngologists expand office-based offerings.
The FDA regulates dermal fillers as Class III medical devices, requiring premarket approval or 510(k) clearance that shapes product development timelines and clinical evidence requirements. EMA's Medical Device Regulation imposes equivalent conformity assessment burdens across European markets, while state-level medical board scope-of-practice rules determine whether nurse injectors or physician assistants may administer treatments in US jurisdictions. Stakeholders must monitor evolving FDA guidance on vascular occlusion risk mitigation and emerging state legislation restricting filler administration to licensed physicians.
Market Dynamics
Injectable filler reversibility with hyaluronidase is compressing patient hesitation and expanding addressable demand beyond traditional surgical candidates into correction-seeking revision populations.
Growth Catalysts
- FDA Class III pathway maturation:Established premarket approval frameworks reduce clinical evidence uncertainty for new hyaluronic acid formulations entering nasal indication expansion.
- Post-traumatic deformity correction:Otolaryngologists are building office-based aesthetic service lines that capture functional reconstruction patients seeking contour refinement without secondary rhinoplasty.
- Microcannula technique diffusion:Vascular occlusion risk reduction through blunt-tip delivery is expanding treatable nasal zones previously considered high-risk for sharp needle approaches.
Market Restraints
- Calcium hydroxylapatite supply concentration:European manufacturing of Radiesse creates single-source dependency for structural nasal bridge augmentation requiring premium positioning.
- Hyaluronidase cost volatility:Enzyme price sensitivity constrains clinic margin structures when managing vascular compromise emergencies or patient dissatisfaction reversals.
- State scope-of-practice fragmentation:Medical board variations restrict nurse injector administration in jurisdictions like Texas and New York, compressing clinic throughput capacity.
Strategic Opportunities
- Poly-L-lactic acid nasal indication development:Collagen-stimulating biostimulators offer durable structural support for dorsal augmentation with extended longevity versus hyaluronic acid.
- Telemedicine pre-consultation channels:Virtual assessment workflows reduce geographic access barriers for patients in secondary metropolitan markets seeking specialist evaluation.
- EMA MDR harmonization:Unified European conformity assessment creates streamlined multi-country launch pathways for manufacturers with notified body relationships.
Industry Challenges
- Microvascular anatomy mastery:Safe nasal tip and alar base injection requires advanced cadaveric training that exceeds standard dermal filler certification curricula.
- Reversal protocol standardization:Clinic-level hyaluronidase dosing algorithms for impending nasal skin necrosis lack consensus guidelines, elevating malpractice exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Surgical Rhinoplasty Market |
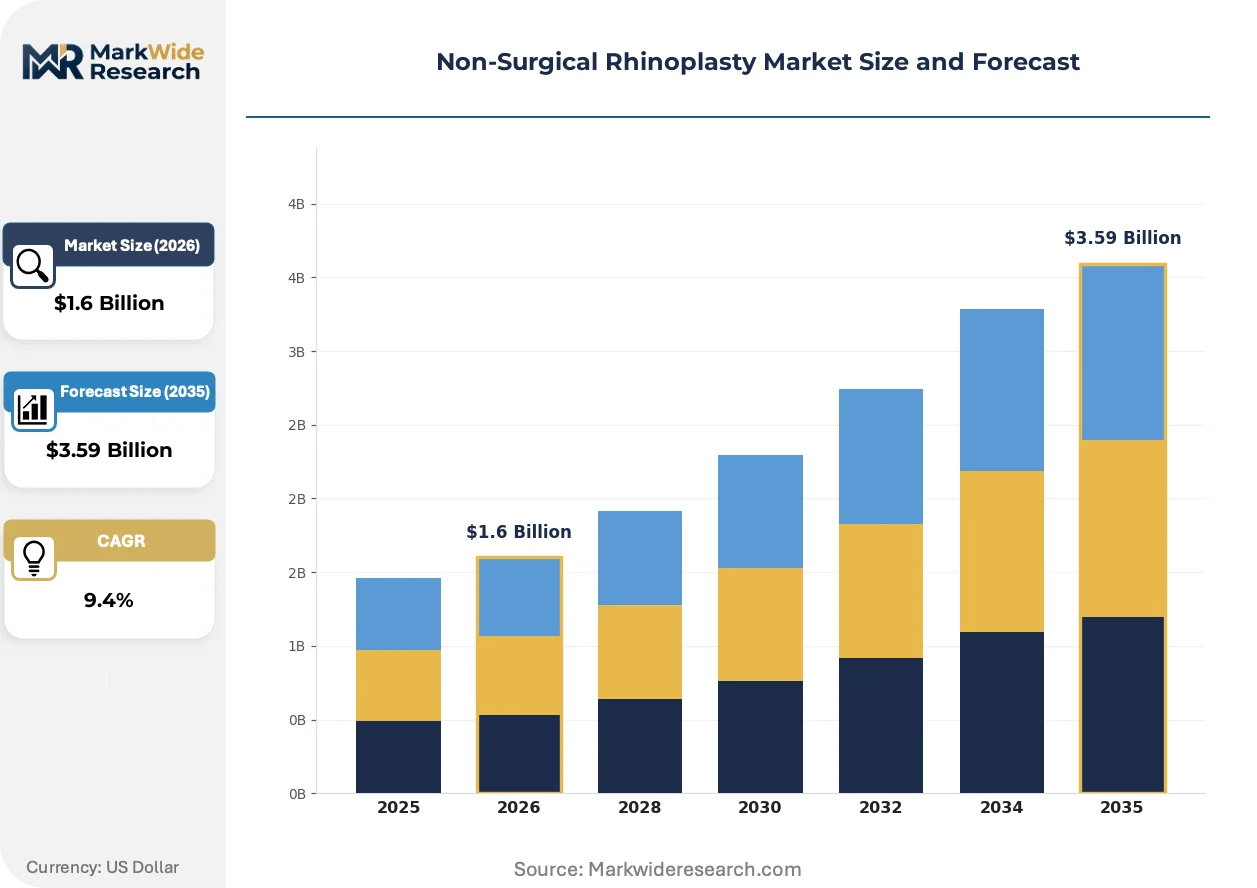
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.59 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Autologous Fat Application: Cosmetic Improvement, Functional Correction, Scar Revision, Nasal Contouring End User: Clinics, Beauty Salons, Hospitals, Aesthetic Centers Age Group: Teens, Adults, Seniors, Others |
| Companies Covered | Sinclair Pharma Ltd., Hugel Inc., AbbVie Inc., Ipsen Pharma, Teoxane, Merz Pharma, Galderma S.A., Croma Pharma, Revance Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Surgical Rhinoplasty Market Strategic Shifts & Innovations
Injectable rhinoplasty is separating into reversible maintenance procedures and permanent-appearing structural corrections, with technique and material selection increasingly tied to patient commitment duration rather than anatomical indication alone.
Hyaluronic acid filler formulations is bifurcating into high-G prime products for dorsal structural support and low-G prime options for subtle tip refinement. Aesthetic clinics in Los Angeles and Miami are adopting dual-product protocols that segment patients by desired longevity. This material stratification is compressing single-formula approaches and elevating consultation complexity.
EMA's Medical Device Regulation imposes post-market surveillance obligations that extend clinical evidence requirements beyond initial conformity assessment. Manufacturers must maintain vigilance systems for rare vascular events that nasal injections elevate. European notified bodies are demanding extended follow-up data for filler families seeking expanded facial indication claims.
Patient acquisition through social media visualization is displacing traditional referral networks in aesthetic practice development. Instagram and TikTok before-after content drives consultation requests among 25-34 year-old demographics seeking subtle profile enhancement. This channel shift concentrates marketing investment in content production capability rather than physician referral relationship maintenance.
Non-Surgical Rhinoplasty Market Segmentation
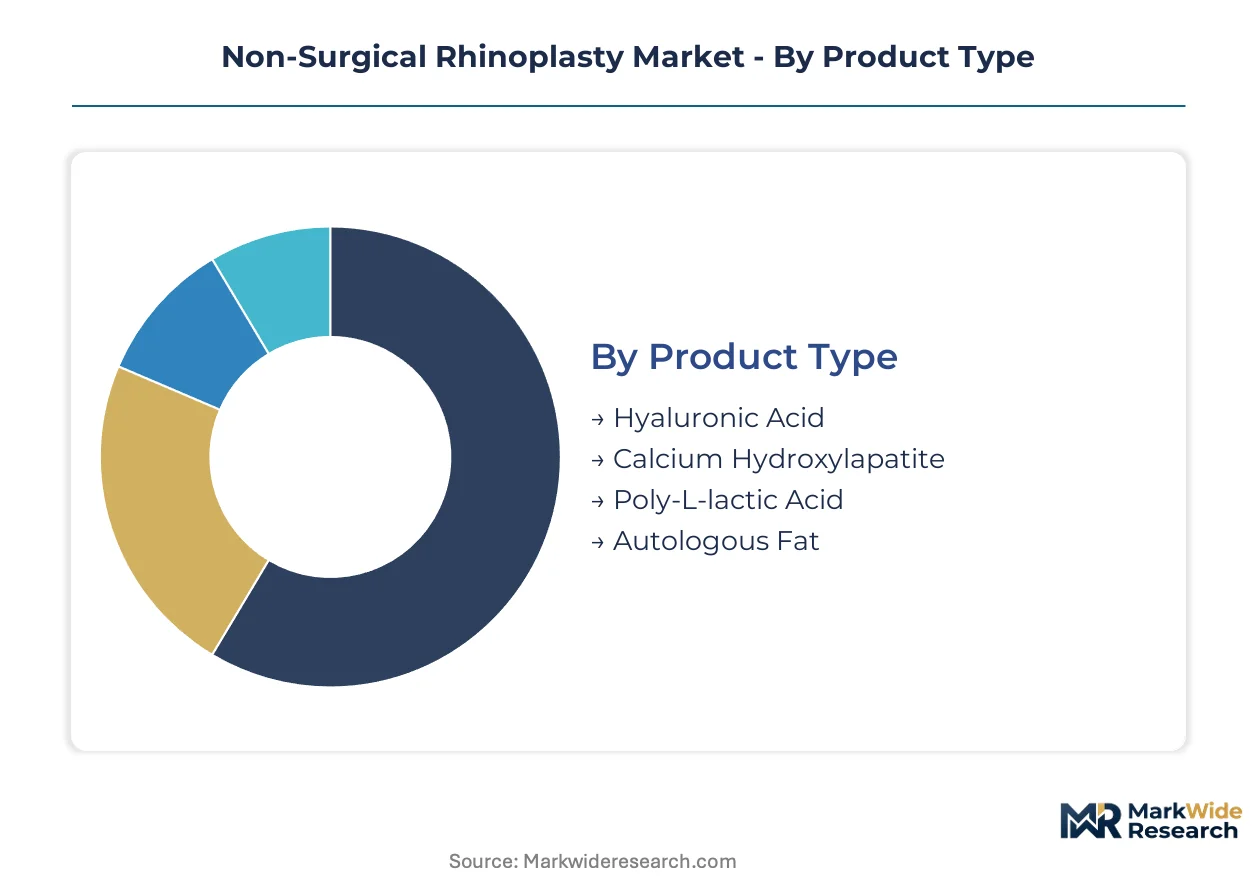
Non-surgical rhinoplasty segmentation reveals divergent margin structures across filler technologies and care settings. Product type stratification separates reversible maintenance revenues from premium structural augmentation, while end-user concentration in physician-supervised clinics limits price compression from non-medical channels.
Product Type:
Margin pools concentrate in structural support formulations commanding premium positioning for dorsal bridge augmentation.
- Hyaluronic Acid:Cross-linked gel formulations deliver immediate contour correction with enzymatic reversibility via hyaluronidase. Demand concentrates in US aesthetic clinics seeking low-risk entry procedures for first-time nasal augmentation patients concerned about surgical commitment.
- Calcium Hydroxylapatite:Microsphere suspensions provide rigid structural support mimicking nasal bone density for dorsal augmentation. European supply chains anchor manufacturing, with German and Swiss clinics driving adoption for patients seeking 12-18 month longevity without surgical recovery.
- Poly-L-lactic Acid:Biostimulating microparticles trigger collagen neogenesis for gradual volume restoration.
- Autologous Fat:Liposuction-harvested adipose tissue offers permanent correction without foreign material reaction risk.
Hyaluronic acid holds installed capacity. Poly-L-lactic acid is rotating up the share rankings.
Application:
Volume concentration tracks toward revision populations seeking correction of prior surgical outcomes rather than primary augmentation.
- Cosmetic Improvement:Profile refinement for dorsal humps, tip projection, and nasal asymmetry dominates clinic throughput. Los Angeles and Miami aesthetic practices report patient acquisition through social media visualization driving 25-34 demographic consultation requests for subtle enhancement.
- Functional Correction:Post-traumatic deformity restoration addresses airway compromise sequelae with simultaneous contour refinement. US otolaryngology office-based service lines are expanding fastest as surgeons capture reconstruction patients avoiding secondary rhinoplasty.
- Scar Revision:Injectable camouflage of post-surgical irregularities and traumatic scar contractures.
- Nasal Contouring:Comprehensive reshaping combining multiple injection zones for overall proportion restoration.
Cosmetic improvement commands procedure volume. Functional correction is gaining share fastest.
End User:
Regulatory scope-of-practice rules fragment channel economics across jurisdictions with divergent injector qualification requirements.
- Clinics:Physician-owned aesthetic practices deliver 15-30 minute microcannula procedures with standardized reversal protocols. Texas and New York medical board restrictions on nurse injector administration compress throughput in these states compared to California's expanded scope environment.
- Aesthetic Centers:Multi-specialty facilities combine dermatology and facial plastic surgery expertise for complex revision cases. German and UK centers lead European adoption of dual-product protocols segmenting patients by desired longevity.
- Hospitals:Academic medical centers integrate injectable rhinoplasty into otolaryngology and plastic surgery residency training.
- Beauty Salons:Non-medical venues face regulatory prohibition in most US states and European markets.
Clinics hold installed capacity. Aesthetic centers are rotating up the share rankings.
Age Group:
Customer lifetime value stratifies sharply between maintenance-dependent younger cohorts and single-procedure older segments.
- Adults:25-45 year-olds drive repeat procedure economics with hyaluronic acid maintenance cycles every 9-12 months. Social media visualization channels concentrate marketing investment toward this demographic's consultation requests.
- Teens:Regulatory and ethical constraints limit access pending skeletal maturity.
- Seniors:Skin thickness changes and vascular compromise risk elevate consultation complexity.
- Others:Pediatric and geriatric edge cases with specific anatomical indications.
Adults hold installed capacity. Seniors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young adults seeking subtle profile refinement concentrate demand in aesthetic clusters across four countries. Regulatory scope-of-practice rules and social media-driven patient acquisition reshape geographic competitive intensity.
United States
FDA Class III premarket pathways for hyaluronic acid fillers stabilize product entry timelines for nasal indication expansion. State medical boards in Texas and New York restrict nurse injector administration, compressing clinic throughput versus California's expanded scope environment. Los Angeles and Miami aesthetic practices drive patient acquisition through Instagram and TikTok visualization channels targeting 25-34 year-old demographics.
Germany
EMA Medical Device Regulation post-market surveillance obligations extend clinical evidence requirements for expanded facial indication claims. German aesthetic centers lead European adoption of dual-product protocols segmenting patients by desired longevity versus reversibility. Berlin and Munich clusters anchor calcium hydroxylapatite adoption for dorsal bridge augmentation with 12-18 month durability positioning.
South Korea
MFDS oversight of dermal fillers as medical devices shapes import registration requirements for foreign manufacturers. Seoul Capital Area aesthetic clinics concentrate demand for microcannula technique diffusion reducing vascular occlusion risk in nasal tip zones. Domestic social media platforms drive consultation requests among young professionals seeking non-surgical alternatives to traditional rhinoplasty.
United Kingdom
UK medical board scope-of-practice guidance determines injector qualification requirements across England, Scotland, and Wales. London aesthetic centers combine dermatology and facial plastic surgery expertise for complex revision cases requiring dual-product approaches. Manchester and Birmingham secondary markets expand through telemedicine pre-consultation channels reducing geographic access barriers.
Brazil
ANVISA medical device registration pathways for dermal fillers influence product launch sequencing for nasal indication development. São Paulo aesthetic clinics concentrate demand for hyaluronic acid maintenance procedures among repeat-treatment cohorts. Rio de Janeiro practices capture post-traumatic deformity correction patients seeking functional reconstruction without secondary surgical recovery.
Non-Surgical Rhinoplasty Market Key Industry Players
Player mix skews toward multinational pharmaceutical conglomerates with established aesthetic medicine portfolios. Market structure concentrates around three to four integrated manufacturers controlling hyaluronic acid and calcium hydroxylapatite supply chains. Strategic archetypes separate legacy dermatology players, biostimulator specialists, and Korean challenger firms. Competitive moves center on indication expansion filings and microcannula technique training program deployment.
Within the integrated pharmaceutical tier, AbbVie Inc. and Galderma S.A. occupy anchor positions representing scale-driven portfolio breadth. Merz Pharma exemplifies the European structural support specialist archetype. Korean challenger Hugel Inc. sits within the Asia-Pacific expansion vector. Sinclair Pharma Ltd. and Teoxane represent mid-scale European specialists with concentrated facial aesthetic positioning. Croma Pharma and Revance Therapeutics Inc. occupy emerging technology niches.
| Leading Market Players |
|---|
| Sinclair Pharma Ltd. |
| Hugel Inc. |
| AbbVie Inc. |
| Ipsen Pharma |
| Teoxane |
| Merz Pharma |
| Galderma S.A. |
| Croma Pharma |
| Revance Therapeutics Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for hyaluronic acid raw materials compress margin buffers while amplifying pricing power for integrated manufacturers with captive fermentation capacity. This lead-time structure concentrates procurement leverage among AbbVie Inc., Galderma S.A., and Merz Pharma, forcing smaller clinics toward group purchasing organizations to offset volume disadvantages.
Pricing Analysis
Cost-plus contracts with hyaluronidase indexation dominate clinic procurement for emergency reversal protocols. Three-tier pricing structure across premium structural fillers, standard hyaluronic acid maintenance products, and economy-grade volume alternatives segments buyer archetypes by procedure complexity. Pricing pressure stems from hyaluronidase cost volatility constraining clinic margins during vascular compromise emergencies. Nurse injector-dependent practices in California exhibit highest price sensitivity due to throughput advantages, while physician-only jurisdictions like Texas absorb premium positioning with lower volume thresholds.
Supply Chain Analysis
Sweden and France anchor European hyaluronic acid fermentation capacity, while German manufacturing clusters produce calcium hydroxylapatite microspheres for structural augmentation. Supply chains draw from pharmaceutical-grade sodium hyaluronate, cross-linking agents, and sterile packaging components. Single-source vulnerability concentrates in European calcium hydroxylapatite production for Radiesse-dependent dorsal bridge procedures. Distribution runs through specialty pharmaceutical wholesalers with cold-chain requirements, bypassing direct-to-clinic models except for large aesthetic center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multi-site aesthetic center chains that extract volume discounts from manufacturers, fragmenting pricing power previously held by independent physician practices.
For Market Incumbents: Fortify channel control through exclusive microcannula training certification programs that lock injector loyalty against Korean challenger firms expanding hyaluronic acid portfolios. Deepen backward integration into hyaluronidase production to offset enzyme cost volatility threatening clinic margin structures. Invest in FDA indication expansion filings for poly-L-lactic acid nasal applications ahead of collagen-stimulator competition. For New Entrants and Emerging Players: Anchor in telemedicine pre-consultation workflows for secondary metropolitan markets like Manchester and Birmingham where geographic access barriers persist. Target post-traumatic deformity correction within US otolaryngology office-based service lines, the fastest-growing subsegment with limited incumbent penetration. Pursue EMA MDR streamlined launch pathways through notified body relationships in Germany to bypass fragmented national registrations. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting non-core aesthetic medicine portfolios. Long-term viability centers on biostimulator innovation pipelines and microcannula technique IP rather than commoditized hyaluronic acid formulations. Watch FDA guidance evolution on vascular occlusion risk mitigation as inflection indicator for regulatory compliance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Indication Expansion Filing | Premarket approval pathways for nasal-specific hyaluronic acid formulations reduce clinical evidence uncertainty. |
| Microcannula Training Program Deployment | Blunt-tip delivery certification locks injector loyalty and reduces vascular occlusion liability exposure. |
| EMA MDR Harmonization Pathway | Unified European conformity assessment streamlines multi-country launch for manufacturers with notified body relationships. |
| Telemedicine Pre-Consultation Channel Buildout | Virtual assessment workflows reduce geographic access barriers in secondary metropolitan markets. |
| Hyaluronidase Backward Integration | In-house enzyme production offsets cost volatility constraining clinic margins during emergency reversals. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with facial plastic surgeons, otolaryngologists, aesthetic clinic operators, and dermal filler procurement managers; and secondary validation through FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital purchasing committee records, and GPO contract databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Across the analysis window, forecasts modeled product type segmentation by filler technology, application split between cosmetic and functional correction, end-user channel economics, and age-group cohort lifetime value. CAGRs derived from procedure volume growth trajectories, pricing elasticity assumptions, and regulatory pathway maturation timelines. Inputs included social media-driven patient acquisition channel shifts and state-level scope-of-practice rule variations.
Material uncertainties — FDA guidance evolution on vascular occlusion mitigation, hyaluronidase supply disruptions, and state medical board injector qualification restrictions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and clinic throughput capacity. Recalibration cycles align with material shifts in FDA Class III pathway timelines and EMA MDR post-market surveillance obligations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market