
 Artificial Disc Replacement Market | 2026-2036
Artificial Disc Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Disc Replacement Market Intelligence
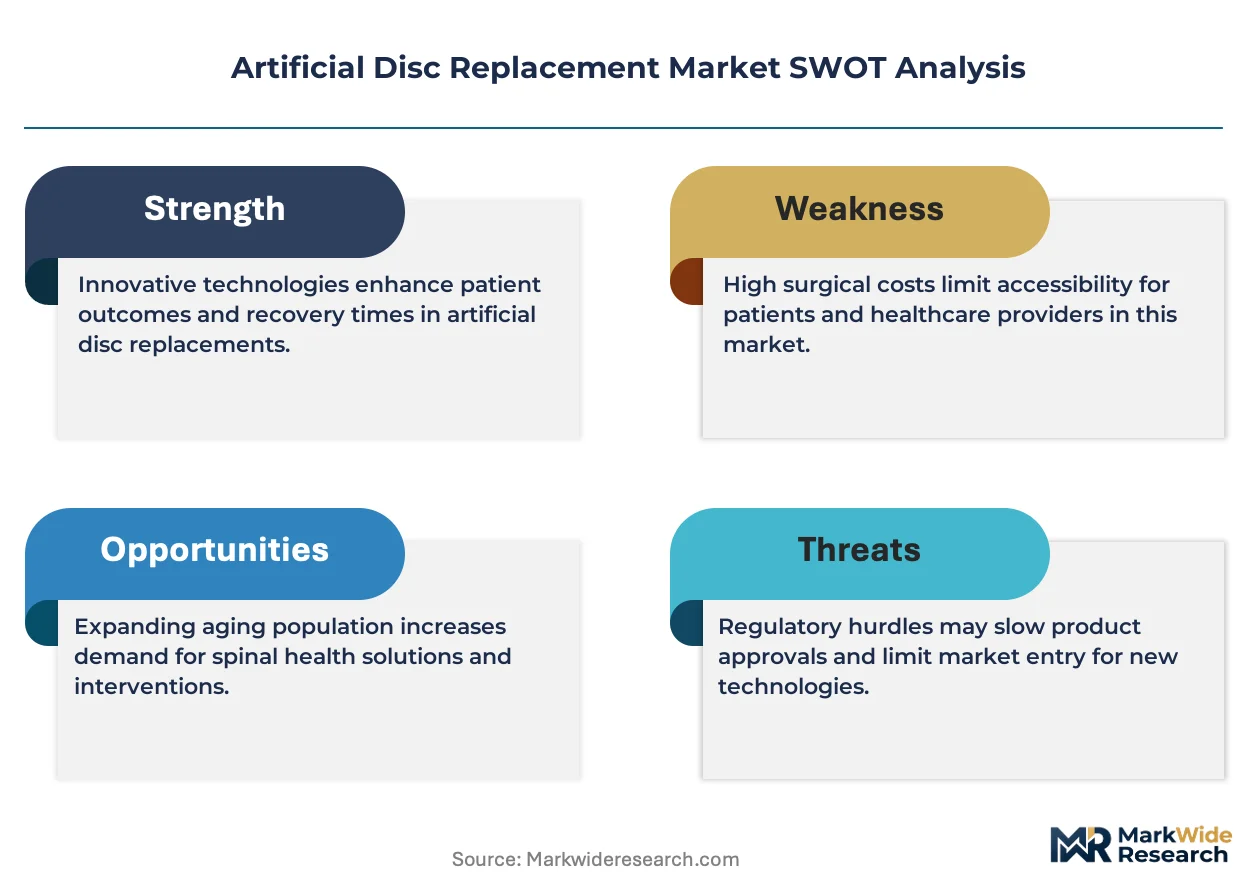
Project finance partnerships between device manufacturers and ambulatory surgery center chains are reshaping competitive dynamics in artificial disc replacement. Medtronic leverages its captive financing arm to lock in multi-year supply agreements with large hospital networks. Zimmer Biomet anchors its position through direct-to-facility leasing models that reduce capital barriers for mid-tier orthopedic clinics. Stryker Corporation competes by bundling robotic navigation systems with disc implant contracts.
Artificial disc replacement involves the surgical implantation of a prosthetic device to replace a damaged intervertebral disc, typically constructed from cobalt-chromium-molybdenum alloys, titanium, or ultra-high molecular weight polyethylene, designed to preserve segmental motion while restoring disc height and neural decompression. Cervical disc implants dominate procedural volumes due to lower surgical complexity and faster recovery trajectories, though lumbar discs command premium pricing because of larger device sizes and more demanding biomechanical requirements. Robotics-assisted placement technology is gaining fastest adoption among ambulatory surgery centers seeking to differentiate on precision and reduce revision liability.
The FDA premarket approval process and the European Medical Device Regulation (MDR) impose stringent clinical evidence and post-market surveillance obligations on artificial disc manufacturers, effectively filtering out undercapitalized entrants. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) maintains separate durability testing standards that delay market entry for non-domestic firms. Stakeholders must monitor reimbursement recalibrations by national health technology assessment bodies as these determinations increasingly gate commercial viability ahead of regulatory clearance.
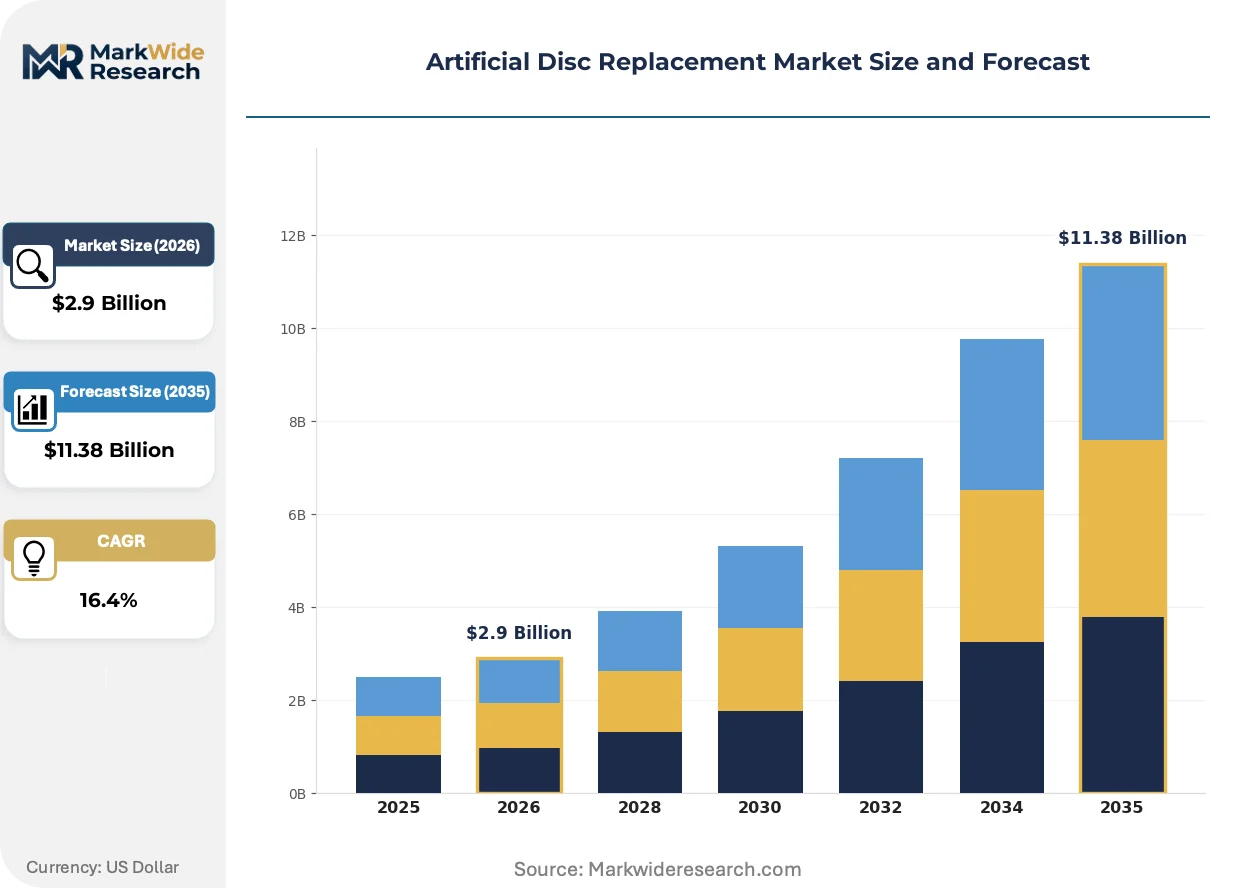
Market Dynamics
Motion-preserving spine surgery is fragmenting procedural volume across hospital outpatient departments and ambulatory surgery centers, forcing implant manufacturers to restructure pricing and service models around site-of-care economics rather than traditional inpatient bundled contracts.
Growth Catalysts
- Statutory reimbursement expansion:Germany's statutory health insurance funds have broadened coverage for cervical disc replacement, creating predictable payment pathways that accelerate physician adoption in Western Europe's largest procedural market.
- Biomaterial advances:Cobalt-chromium-molybdenum alloys with enhanced wear profiles are extending implant durability benchmarks, satisfying FDA long-term follow-up requirements for premarket approval submissions.
- Ambulatory migration:United States hospital systems are relocating select lumbar disc cases to licensed outpatient facilities, expanding addressable procedure volumes beyond traditional inpatient constraints.
Market Restraints
- Clinical evidence thresholds:FDA premarket approval pathways now mandate minimum seven-year follow-up data for novel motion-preserving implants, extending development timelines and capital lockup periods for device developers.
- Titanium supply concentration:Aerospace and defense procurement is absorbing limited titanium sponge capacity, transmitting volatility into implant-grade titanium pricing for disc endplates and fixation components.
- Fusion substitution:Minimally invasive transforaminal lumbar interbody fusion techniques with expandable cages are capturing degenerative disc cases previously slated for arthroplasty, particularly among payers with restrictive prior authorization.
Strategic Opportunities
- Japanese market entry:PMDA durability testing standards currently delay non-domestic disc manufacturers, creating first-mover advantage for firms that complete accelerated wear simulator protocols aligned with JIS specifications.
- Robotic navigation bundling:Spine surgery platforms integrating intraoperative navigation with implant delivery systems are commanding premium positioning in United States ambulatory surgery center procurement.
- EU MDR transition:Notified body capacity constraints under the European Medical Device Regulation are forcing smaller competitors into portfolio rationalization, opening shelf space for firms with established quality management systems.
Industry Challenges
- Surgeon training pipelines:Fellowship programs in motion-preserving spine surgery remain concentrated at academic medical centers, limiting community hospital access to qualified arthroplasty specialists.
- Post-market surveillance infrastructure:FDA-mandated patient registries for approved cervical and lumbar discs require substantial data management investment, straining mid-tier manufacturers without established health economics departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Disc Replacement Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $11.38 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cervical Disc, Lumbar Disc, Metal, Polymer End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Artificial Intelligence, Robotics, Minimally Invasive Surgery, Imaging Systems Delivery Mode: Outpatient, Inpatient, Telemedicine, Conventional |
| Companies Covered | Medtronic, Zimmer Biomet, Stryker Corporation, Johnson & Johnson, NuVasive, Globus Medical, B. Braun Melsungen AG, Orthofix Medical, Aesculap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Disc Replacement Market Strategic Shifts & Innovations
Artificial disc replacement is experiencing simultaneous pressure from three vectors: materials science breakthroughs that compress manufacturing complexity, regulatory frameworks that filter market participation, and site-of-care economics that redistribute buyer power across facility types.
Polyethylene-on-metal bearing surfaces are collapsing the historical durability gap between cervical and lumbar implant longevity expectations. Ambulatory surgery centers in the United States are adopting these advanced bearing couples fastest, recognizing that reduced wear debris profiles translate directly into lower revision liability exposure. The structural consequence is compression of premium pricing tiers for conventional metal-on-metal constructs.
European Medical Device Regulation Article 117 requirements for clinical evaluation reports are reshaping submission strategies for motion-preserving implants. Manufacturers now face mandatory notified body consultation for class III devices with novel materials, extending time-to-CE-mark by twelve to eighteen months. Cervical disc portfolios with legacy approvals under the Medical Devices Directive face the steepest compliance cliff.
Hospital procurement committees are unbundling implant costs from robotics and navigation service fees, reversing prior bundled contracting conventions. Large United States health systems are negotiating direct manufacturer agreements that bypass distributor markups, particularly for high-volume cervical disc SKUs. This behavioral shift is most visible in multi-hospital networks with centralized spine service line management.
Artificial Disc Replacement Market Segmentation
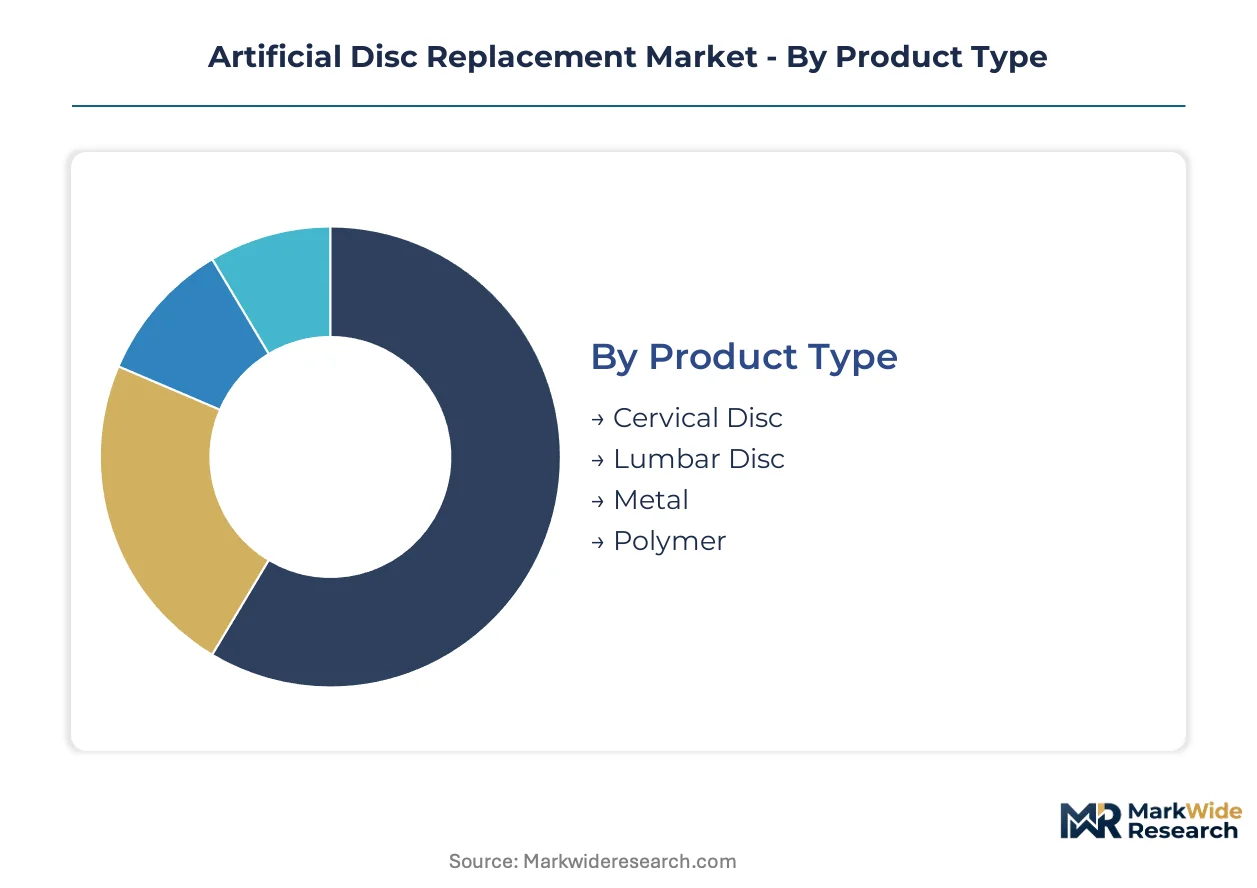
Artificial disc replacement segmentation reveals how procedural economics, site-of-care migration, and technology integration reshape competitive positioning across implant categories. Manufacturers must align portfolio development with distinct reimbursement pathways and capital intensity requirements.
Product Type:
Cervical and lumbar implants serve fundamentally different surgical workflows, anatomical constraints, and durability expectations across the use-case spectrum.
- Cervical Disc:Smaller device footprints accommodate the delicate cervical spine anatomy with lower surgical complexity and reduced operative time. Demand concentrates in Germany where statutory health insurance reimbursement expansion accelerates physician adoption beyond traditional fusion alternatives.
- Lumbar Disc:Larger bearing surfaces and enhanced load-bearing specifications address the biomechanical demands of the lower spine with premium pricing structures. United States ambulatory surgery centers are selectively migrating lumbar cases to outpatient settings, expanding addressable volumes beyond inpatient constraints.
- Metal:Cobalt-chromium-molybdenum alloys dominate endplate construction with established wear profiles and long-term clinical data packages.
- Polymer:Ultra-high molecular weight polyethylene bearing surfaces reduce debris generation and extend implant longevity benchmarks.
The dominant share belongs to Cervical Disc, while Lumbar Disc is closing the gap fastest.
End User:
Facility type determines capital deployment models, surgeon training requirements, and procurement negotiation leverage across cost tiers.
- Hospitals:Academic medical centers anchor complex revision cases and fellowship training pipelines with centralized spine service line management. Large United States health systems negotiate direct manufacturer agreements that bypass distributor markups for high-volume cervical disc procurement.
- Ambulatory Surgery Centers:Licensed outpatient facilities prioritize robotics-assisted placement technology to differentiate on precision and reduce revision liability exposure. These centers command favorable site-of-care economics for select lumbar disc cases previously restricted to inpatient settings.
- Orthopedic Clinics:Mid-tier clinics access implants through direct-to-facility leasing models that reduce capital barriers and preserve cash flow flexibility.
- Rehabilitation Centers:Post-acute facilities coordinate recovery protocols and patient selection criteria for motion-preserving outcomes.
Hospitals retain the dominant share, while Ambulatory Surgery Centers are expanding most quickly.
Technology:
Digital and robotic adjuncts reshape procedural precision, training requirements, and bundled contracting structures across application categories.
- Robotics:Spine surgery platforms integrate intraoperative navigation with implant delivery systems, commanding premium positioning in United States ambulatory surgery center procurement decisions.
- Minimally Invasive Surgery:Reduced tissue disruption accelerates recovery trajectories and supports outpatient migration strategies.
- Artificial Intelligence:Preoperative planning algorithms optimize implant sizing and positioning predictions.
- Imaging Systems:Intraoperative fluoroscopy and navigation guidance enable real-time placement verification.
Robotics holds the dominant share, while Minimally Invasive Surgery is climbing the fastest.
Delivery Mode:
Care setting selection reflects reimbursement calibration, patient acuity stratification, and facility licensing boundaries across volume distribution.
- Inpatient:Traditional hospital admission supports complex lumbar revisions and multi-level procedures with overnight monitoring capabilities.
- Outpatient:Same-day discharge protocols concentrate in cervical disc replacement with established rapid recovery pathways.
- Telemedicine:Remote consultation and postoperative monitoring extend geographic reach for preoperative screening and follow-up care.
- Conventional:Standard office-based evaluation persists in markets with limited digital infrastructure or restrictive payer policies.
Inpatient retains the dominant share, while Outpatient is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in artificial disc replacement track divergent regulatory clearance timelines and reimbursement policy cycles across major economies. The United States maintains net importer status for premium motion-preserving implants while Germany and Japan cultivate domestic manufacturing capacity through targeted health technology assessment frameworks.
United States
Hospital systems in Texas and California are consolidating spine service lines under centralized procurement committees that negotiate direct manufacturer agreements bypassing traditional distributor networks. FDA premarket approval pathways now mandate minimum seven-year follow-up data for novel cervical and lumbar disc implants, extending development timelines for domestic and foreign developers alike. The Greater Boston corridor anchors fellowship training pipelines in motion-preserving techniques, limiting community hospital access to qualified arthroplasty specialists.
Germany
Statutory health insurance funds have broadened coverage for cervical disc replacement procedures, creating predictable payment pathways that accelerate physician adoption beyond traditional fusion alternatives. The European Medical Device Regulation imposes stringent clinical evidence and post-market surveillance obligations through notified body consultation requirements for class III devices. The Rhine-Ruhr metropolitan region concentrates ambulatory surgery center chains expanding motion-preserving spine programs under site-of-care economics restructuring.
Japan
Domestic demand for artificial disc replacement concentrates in academic medical centers with established durability testing capabilities aligned with PMDA standards. The Pharmaceuticals and Medical Devices Agency maintains separate wear simulator protocols that delay market entry for non-domestic firms lacking JIS specification alignment. The Kanto region around Tokyo anchors the country's largest procedural volumes while Kansai-based manufacturers develop captive supply chains for implant-grade titanium endplates.
China
Provincial health security bureaus are piloting diagnosis-related group reimbursement for select motion-preserving spine procedures in tier-one cities. NMPA regulatory pathways for imported class III orthopedic implants require domestic clinical trial data, filtering market participation to firms with substantial local development infrastructure. The Yangtze River Delta clusters spine surgery robotics manufacturers integrating navigation systems with disc implant delivery platforms.
Australia
Private health insurers are recalibrating prosthesis list benefits for cervical disc replacement amid pressure from hospital networks to reduce out-of-pocket patient contributions. TGA conformity assessment procedures for novel bearing surfaces require enhanced biocompatibility documentation extending time-to-market for emerging material platforms. Sydney and Melbourne metropolitan areas concentrate ambulatory surgery centers migrating select lumbar cases from inpatient settings under favorable site-of-care licensing frameworks.
Artificial Disc Replacement Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in materials and bearing surface supply. The vendor base concentrates around three strategic tiers: diversified orthopedic conglomerates with captive financing arms, mid-scale spine-focused manufacturers with robotics bundling capabilities, and regional specialists leveraging direct-to-facility leasing models. Dominant competitive moves include backward integration into implant-grade titanium supply chains and strategic partnerships with ambulatory surgery center chains for multi-year exclusive supply agreements.
Among diversified orthopedic conglomerates, Medtronic plc, Zimmer Biomet Holdings, Inc., and Stryker Corporation exemplify platform integrators combining implant portfolios with navigation and robotics ecosystems. These firms occupy positions where captive financing capabilities and direct hospital contracting relationships create defensive moats against mid-tier competitors. Their geographic footprints span multiple regulatory jurisdictions, allowing regulatory approval data packages to transfer across FDA, EMA, and PMDA submission pathways.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Stryker Corporation |
| Johnson & Johnson |
| NuVasive |
| Globus Medical |
| B. Braun Melsungen AG |
| Orthofix Medical |
| Aesculap |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta manufacturing cluster anchors global capacity for spine surgery robotics and navigation systems, concentrating component sourcing leverage among firms with established supplier relationships. This geographic concentration transmits directly into pricing power for integrated platform vendors negotiating with ambulatory surgery centers and hospital networks.
Pricing Analysis
Hospital purchasing committees anchor pricing stratification across premium, standard, and economy tiers in artificial disc replacement. Price differentiation rests on FDA premarket approval tier, robotics bundling, and volume scale commitments. Cost compression in mid-tier cervical disc SKUs is intensifying because large United States health systems negotiate direct manufacturer agreements bypassing distributor markups. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for implant-grade titanium endplates and cobalt-chromium-molybdenum alloy components. Manufacturing concentrates in Germany, the United States, and Japan for finished devices, while raw material feedstocks draw from Australian titanium sponge and South African chromium. Single-source vulnerability persists in ultra-high molecular weight polyethylene bearing surfaces from specialized polymer suppliers. Distribution runs through GPO contracts and direct-to-facility leasing models to hospital systems and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial disc replacement sits in early-cycle expansion as ambulatory surgery centers migrate lumbar cases to outpatient settings and statutory reimbursement frameworks broaden access in Western Europe. Robotics-assisted placement technology accelerates penetration beyond traditional inpatient constraints.
For Market Incumbents: Pre-empt fusion substitution threats from minimally invasive expandable cage techniques by deepening robotics bundling with cervical disc portfolios. Prioritize backward integration into implant-grade titanium supply chains to offset aerospace and defense procurement competition for limited sponge capacity. Lock multi-year exclusive supply agreements with expanding ambulatory surgery center chains before notified body capacity constraints under EU MDR force smaller competitors into portfolio rationalization. For New Entrants and Emerging Players: Pursue white-space opportunity in Japanese market entry by completing accelerated wear simulator protocols aligned with PMDA JIS specifications ahead of non-domestic competitors. Target Germany's statutory health insurance reimbursement expansion for cervical disc replacement with direct-to-facility leasing models that reduce capital barriers for mid-tier orthopedic clinics. Lead with robotics-assisted placement technology as the go-to-market differentiator in United States ambulatory surgery center procurement. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because motion-preserving spine surgery is fragmenting procedural volume across site-of-care types and concentrating buyer power among large health systems. Target mid-scale spine-focused manufacturers with established robotics bundling capabilities and quality management systems positioned for EU MDR transition shelf space capture. Watch FDA premarket approval pathway tightening for novel motion-preserving implants as the signal for development timeline extension and capital lockup period risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Seven-year follow-up data mandates filter undercapitalized entrants from cervical and lumbar disc development. |
| CE Marking Pathway | Notified body consultation requirements under EU MDR extend time-to-market for class III motion-preserving implants. |
| Hospital System Partnership | Direct manufacturer agreements with centralized procurement committees bypass distributor markups in large United States networks. |
| Software Companion Development | Intraoperative navigation integration with implant delivery systems commands premium positioning in ambulatory surgery centers. |
| Reimbursement Strategy | Statutory health insurance coverage expansion in Germany creates predictable payment pathways accelerating physician adoption. |
Research Approach
Initial hypotheses were tested against primary input from spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary research incorporated structured interviews with academic medical center fellowship program directors and ambulatory surgery center administrators. Secondary sources included FDA premarket approval databases, EMA submission records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates were triangulated against top-down implant manufacturer revenue analysis.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, end user facility category, technology integration level, and delivery mode. Cervical versus lumbar implant splits, ambulatory versus inpatient site-of-care migration rates, and robotics adoption curves were derived through regression analysis against historical procedural volumes. CAGRs were computed from compound growth trajectory fitting across the analysis window. Industry-specific inputs included PMDA durability testing standard compliance timelines and statutory health insurance reimbursement policy calibration cycles.
Sensitivities concentrate around FDA long-term follow-up requirement modifications, titanium sponge capacity allocation shifts between aerospace and medical device demand, and EU MDR notified body capacity bottlenecks. Forecasts reflect documented assumptions regarding ambulatory surgery center licensing expansion and statutory reimbursement policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Global Medical Drones Market
Medical Devices
Global Electroceuticals Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Deaver Retractor Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Artificial Retina Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market