
 Lactate Dehydrogenase Test Market | 2026-2036
Lactate Dehydrogenase Test Market Size, Share, and Industry Trends Forecast 2026-2036
Lactate Dehydrogenase Test Market Outlook
Software-defined assay calibration is broadening what laboratories purchase beyond physical reagent kits. Thermo Fisher Scientific leverages its ion chromatography expertise to anchor premium LDH workflows in academic medical centers. Randox Laboratories Ltd. competes through vertically integrated reagent manufacturing that sustains cost advantages in high-throughput environments. Roche Diagnostics dominates automated platform placements, extending its installed base into mid-tier hospital labs across Europe and Asia.
Lactate Dehydrogenase Test measures the enzymatic activity of LDH, a tetrameric oxidoreductase found in heart, liver, muscle, kidney, and red blood cells, typically quantified through spectrophotometric detection of NADH formation at 340 nm wavelength. Clinicians order this assay to detect tissue damage, monitor cancer progression, and differentiate between myocardial infarction and pulmonary embolism in emergency settings. Reagents and kits command the largest revenue pool given recurring consumption patterns, while fluorescence-based technologies represent the fastest-expanding segment as multiplexing capabilities improve sensitivity for low-abundance samples. Hospitals remain the dominant end-user channel, though diagnostic labs are capturing incremental volume as point-of-care protocols shift routine testing away from centralized wards.
The FDA oversees premarket notification pathways for new LDH assay platforms under 510(k) requirements, while the EU Medical Device Regulation mandates clinical performance validation for in vitro diagnostic devices entering European markets. ISO 15189 accreditation standards shape laboratory purchasing criteria by linking reimbursement to demonstrated analytical precision. Stakeholders must monitor evolving harmonization between FDA and EMA guidance on companion diagnostic claims, as LDH assays gain traction in immuno-oncology monitoring protocols.
Market Dynamics
Decentralized testing infrastructure is fragmenting procurement authority away from centralized hospital laboratories toward distributed diagnostic networks, forcing reagent manufacturers to reconfigure distribution logistics and service models around smaller, more numerous endpoints.
Growth Catalysts
- CLIA quality benchmarks:The FDA's renewed clinical laboratory improvement amendments tighten enzymatic assay precision requirements, compelling laboratories to upgrade LDH testing platforms and driving replacement demand for compliant instrumentation.
- Integrated health networks:Consolidated procurement portfolios in the United States create volume commitments that stabilize reagent consumption patterns and reduce customer acquisition costs for assay suppliers.
- Point-of-care protocols:Emergency departments are adopting rapid LDH assays to differentiate myocardial infarction from pulmonary embolism, expanding the addressable testing volume beyond traditional core lab settings.
Market Restraints
- Reagent cost volatility:NADH cofactor prices fluctuate with specialty chemical supply chains concentrated in German and Swiss pharmaceutical intermediate manufacturers, compressing gross margins for kit producers.
- Spectrophotometric obsolescence risk:Fluorescence-based multiplexing platforms threaten conventional 340 nm wavelength detection systems, creating stranded asset risk for laboratories with recent instrument investments.
- EU MDR validation burden:Clinical performance validation requirements for in vitro diagnostic devices entering European markets extend regulatory timelines and inflate premarket development expenditures.
Strategic Opportunities
- Companion diagnostic protocols:LDH assays are gaining traction in immuno-oncology monitoring workflows, opening reimbursement pathways tied to pembrolizumab and nivolumab therapy management.
- Software-defined calibration:Assay calibration algorithms enable recurring SaaS revenue streams beyond physical reagent sales, shifting customer relationships toward subscription-based engagement models.
- Diagnostic laboratory expansion:Mid-tier independent labs in India and Brazil represent underpenetrated endpoints where decentralized infrastructure investment is outpacing hospital centralization trends.
Industry Challenges
- ISO 15189 accreditation complexity:Analytical precision demonstration requirements consume 12-18 month compliance timelines, delaying market entry for novel assay formats and freezing procurement decisions.
- Legacy LIS integration:Automated platform deployments require middleware development to connect with entrenched laboratory information systems, inflating implementation costs and extending sales cycles.
- Multiplexing skill gaps:Fluorescence-based technologies demand specialized training in low-abundance sample handling that existing clinical laboratory staff frequently lack, constraining adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactate Dehydrogenase Test Market |
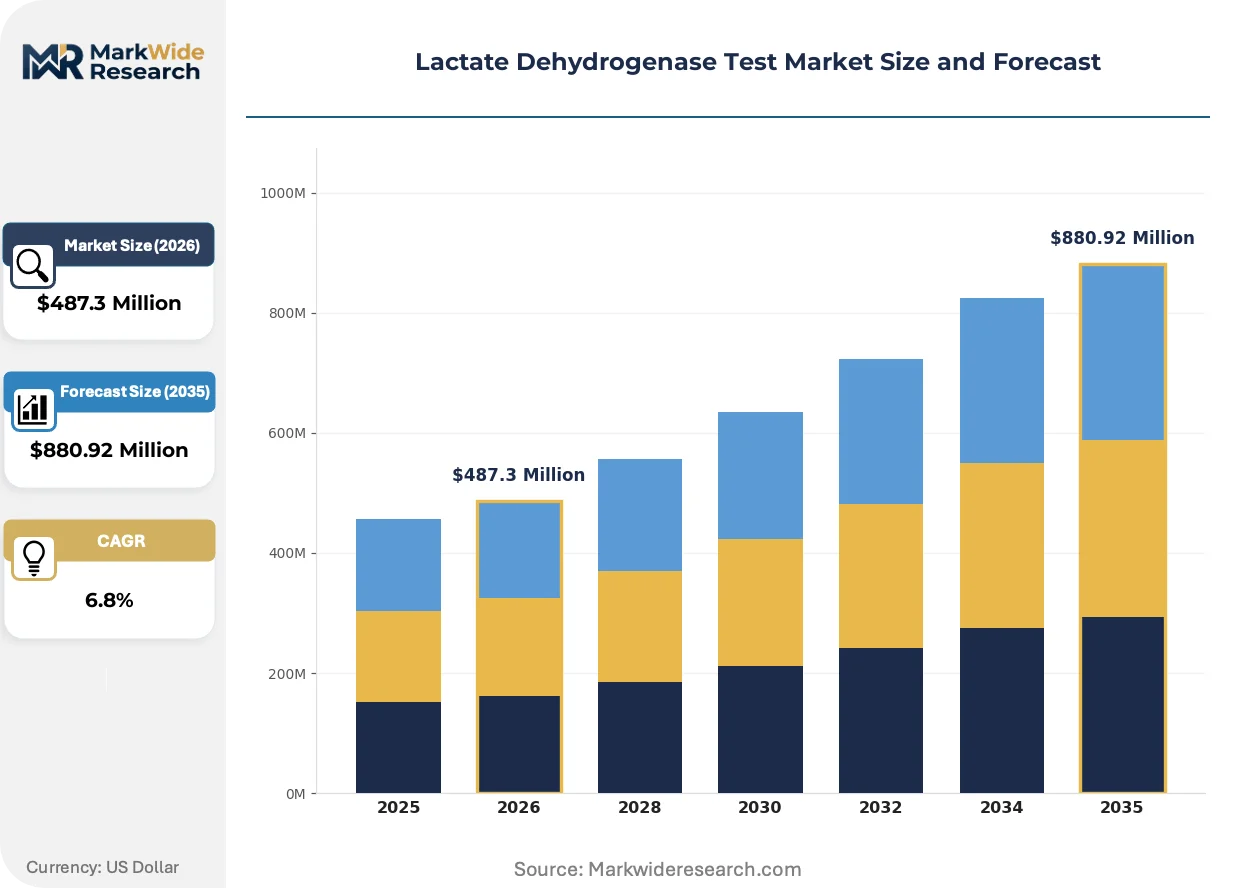
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Kits Technology: Enzymatic Assay, Spectrophotometry, Immunoassay, Fluorescence End User: Hospitals, Diagnostic Labs, Research Organizations, Home Care Application: Cancer Detection, Cardiovascular Disorders, Liver Diseases, Metabolic Disorders |
| Companies Covered | Thermo Fisher Scientific, Randox Laboratories Ltd., Roche Diagnostics, PerkinElmer Inc., Merck KGaA, Abbott Laboratories, Danaher Corporation, Abcam plc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactate Dehydrogenase Test Market Strategic Shifts
Enzymatic assay workflows are converging with digital calibration platforms and multiplexed detection modalities, compressing the traditional separation between hardware instrumentation and consumable reagents into integrated testing ecosystems.
Fluorescence-based multiplexing technologies are rewriting sensitivity benchmarks for LDH quantification in low-volume samples. Academic medical centers in Germany and Japan are piloting these platforms for cancer progression monitoring. The technology is compressing the minimum sample volume threshold from milliliters to microliters, enabling needle-biopsy specimen analysis previously excluded from enzymatic testing protocols.
The EU Medical Device Regulation mandates clinical performance validation through notified body review, extending premarket pathways for LDH assay platforms entering European markets. Manufacturers must generate patient cohort data demonstrating diagnostic accuracy across intended use populations. Mid-tier hospital laboratories in France and Italy are postponing procurement decisions until 2026 to evaluate post-MDR product portfolios.
Health system procurement committees are consolidating vendor relationships around automated platform suppliers capable of servicing multi-analyte testing menus. Hospital laboratories in the United States are displacing point-solution reagent contracts with enterprise agreements covering chemistry, immunoassay, and enzymatic workflows. This concentration is most visible within integrated delivery networks in Texas and California, where procurement authority has shifted from individual hospital administrators to regional supply chain executives.
Lactate Dehydrogenase Test Market Segmentation
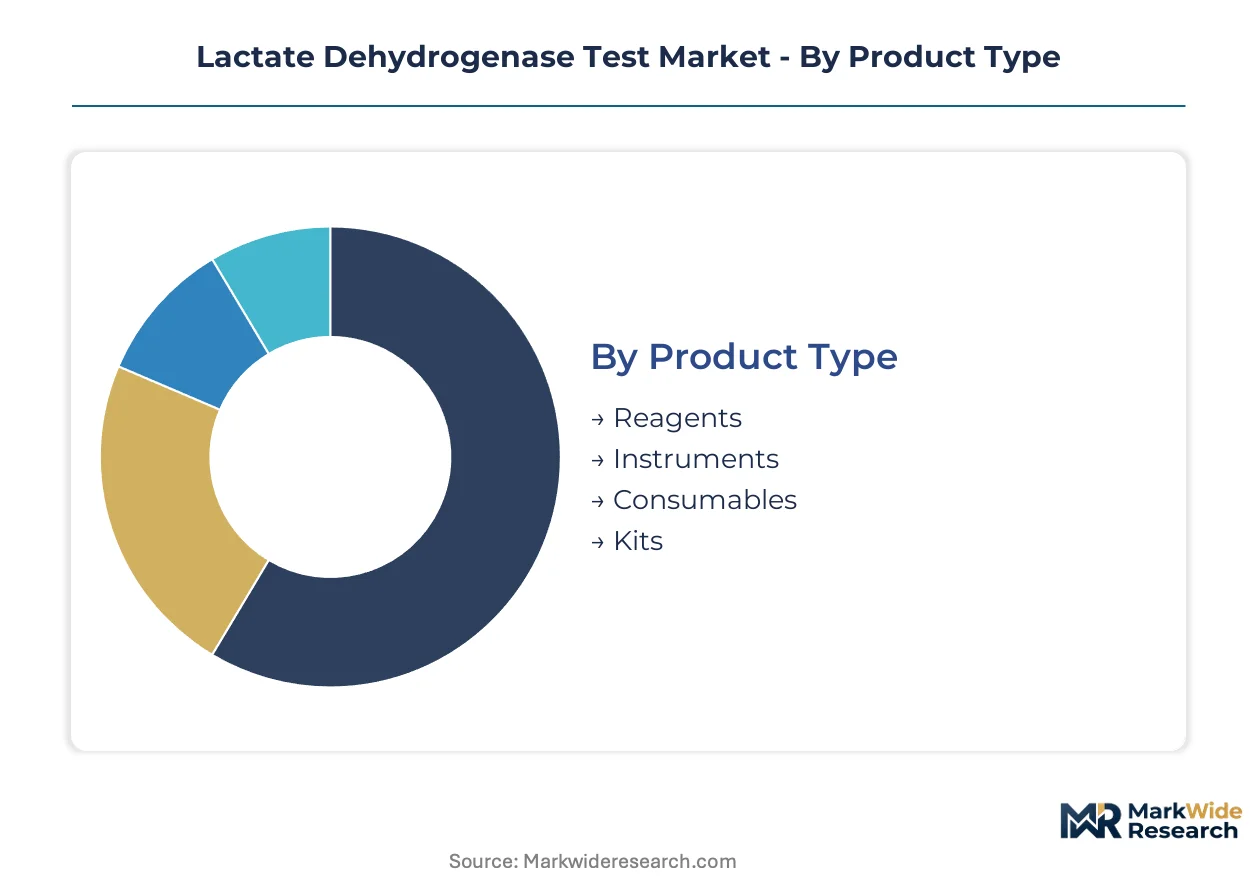
Segmentation in the LDH test market determines procurement authority, regulatory pathway complexity, and service model requirements. Manufacturers must align product portfolios with distinct certification burdens and end-user technical capabilities.
Product Type:
FDA 510(k) clearance applies to instruments and kits as complete systems, while reagents and consumables face lighter premarket notification requirements under CLIA amendments.
- Reagents:NADH-dependent enzymatic formulations require cold-chain logistics and lot-to-lot stability validation. Demand concentrates in high-throughput hospital laboratories across the United States, where integrated health networks negotiate multi-year supply commitments that stabilize consumption patterns.
- Instruments:Automated spectrophotometric and fluorometric platforms integrate with laboratory information systems and demand substantial middleware development. Academic medical centers in Germany and Japan pilot these placements for cancer progression monitoring, compressing minimum sample volume thresholds from milliliters to microliters.
- Consumables:Cuvettes, pipette tips, and reaction vessels face ISO 15189 traceability mandates.
- Kits:Complete assay systems bundle reagents, calibrators, and controls for point-of-care deployment.
Reagents sit at the top of the volume ranking, with instruments climbing the fastest as laboratories replace legacy 340 nm detection systems.
Technology:
Cost tiers separate established enzymatic methods from premium fluorescence platforms, with capital requirements and consumable pricing creating distinct customer entry barriers.
- Enzymatic Assay:Conventional NADH-coupled reactions at 340 nm wavelength remain the clinical standard for LDH quantification. Mid-tier hospital laboratories in France and Italy postpone procurement decisions pending evaluation of post-MDR product portfolios, extending replacement timelines.
- Spectrophotometry:Single-wavelength detection systems face stranded asset risk from multiplexing alternatives. Diagnostic laboratories in India and Brazil represent underpenetrated endpoints where decentralized infrastructure investment outpaces hospital centralization trends.
- Immunoassay:Antibody-based detection offers specificity advantages for complex matrices.
- Fluorescence:Multiplexed detection modalities enable low-abundance sample analysis previously excluded from enzymatic protocols.
Enzymatic assay commands the largest installed base, though fluorescence gains share fastest through immuno-oncology monitoring adoption.
End User:
Customer type dictates service intensity, with hospitals requiring comprehensive maintenance contracts and diagnostic labs prioritizing reagent flexibility.
- Hospitals:Centralized core laboratories anchor LDH testing volume within emergency departments and oncology units. Procurement committees in Texas and California integrated delivery networks consolidate vendor relationships around multi-analyte platform suppliers.
- Diagnostic Labs:Independent and network-affiliated laboratories capture incremental volume as point-of-care protocols shift routine testing away from centralized wards. Mid-tier independent labs in Brazil face ISO 15189 accreditation timelines consuming 12-18 months, delaying novel assay adoption.
- Research Organizations:Academic and contract research settings drive fluorescence platform pilot programs.
- Home Care:Point-of-care protocols in emergency settings differentiate myocardial infarction from pulmonary embolism.
Hospitals retain the dominant revenue position, while diagnostic labs expand most quickly through decentralized infrastructure deployment.
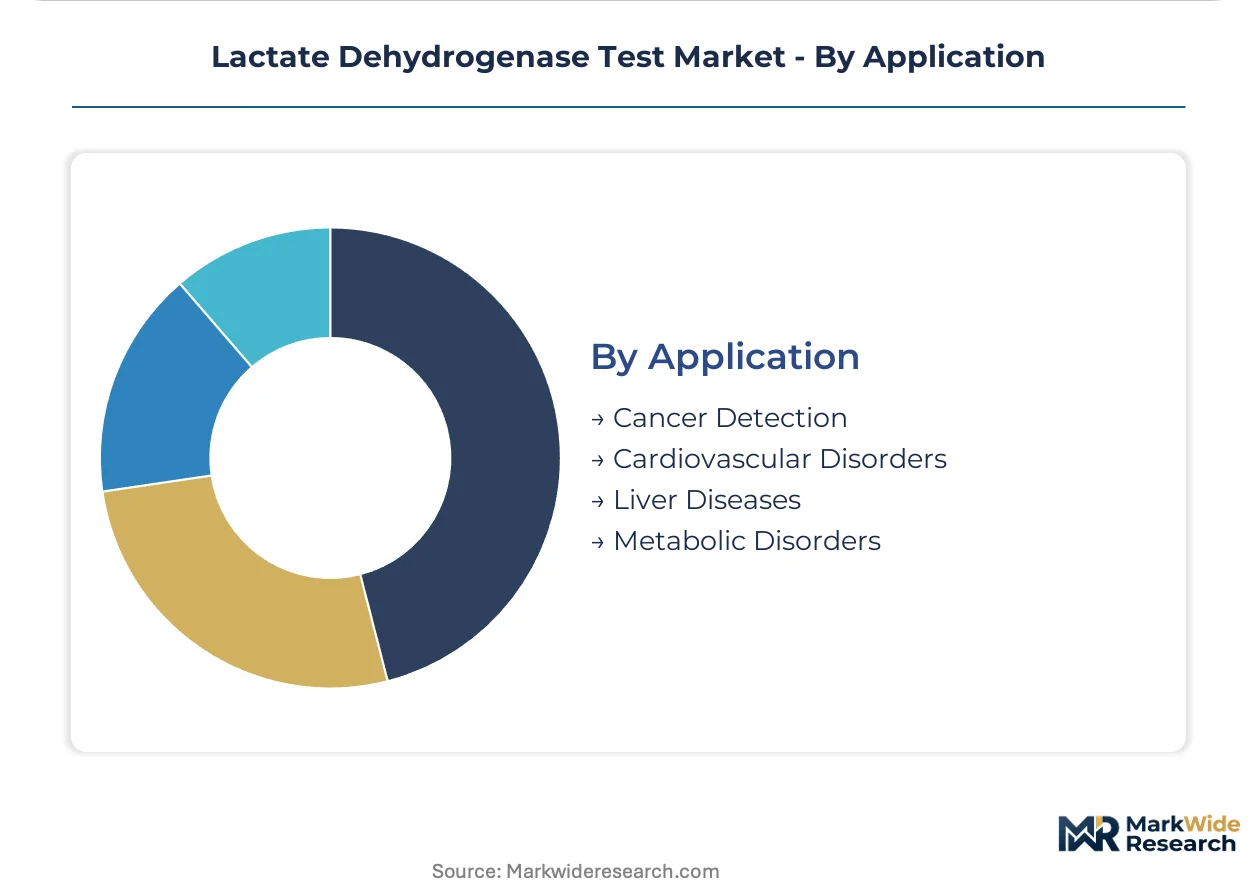
Application:
Maturity varies across clinical indications, with cardiovascular emergency applications commanding premium pricing and cancer monitoring driving platform upgrade cycles.
- Cancer Detection:LDH assays gain traction in immuno-oncology monitoring workflows tied to pembrolizumab and nivolumab therapy management. Companion diagnostic reimbursement pathways in the United States open recurring revenue streams beyond conventional laboratory billing codes.
- Cardiovascular Disorders:Emergency department protocols for myocardial infarction differentiation demand rapid turnaround times. Point-of-care deployment in United States hospital networks expands addressable testing volume beyond traditional core lab settings.
- Liver Diseases:Hepatocellular damage assessment represents established clinical utility with stable demand.
- Metabolic Disorders:Rare disease and mitochondrial function testing occupies niche laboratory segments.
Cardiovascular applications lead procedure volume, with cancer detection ascending fastest through companion diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting LDH assay manufacturing toward jurisdictions with streamlined premarket pathways. The FDA's 510(k) requirements and the EU MDR's clinical validation burden create divergent cost-of-compliance profiles that shape geographic investment decisions.
United States
Integrated health networks in Texas and California are consolidating procurement authority around multi-analyte platform suppliers. FDA CLIA amendments tighten enzymatic assay precision requirements, compelling laboratory infrastructure upgrades. Academic medical centers in Boston and the Research Triangle pilot fluorescence-based multiplexing for cancer monitoring protocols.
Germany
Mid-tier hospital laboratories postpone procurement decisions until 2026 to evaluate post-MDR product portfolios. The EU Medical Device Regulation mandates clinical performance validation through notified body review, extending regulatory timelines. Industrial clusters in Baden-Württemberg and Bavaria anchor precision instrumentation manufacturing for European distribution.
Japan
PMDA oversight shapes premarket notification pathways for novel assay platforms entering domestic markets. METI industrial policy supports diagnostic technology development through targeted R&D subsidies. The Kansai region around Osaka concentrates reagent manufacturing infrastructure serving Asia-Pacific export demand.
India
Mid-tier independent laboratories face ISO 15189 accreditation timelines consuming 12-18 months, delaying novel assay adoption. CDSCO regulates in vitro diagnostic device imports while domestic manufacturing expands under PLI scheme incentives. Diagnostic laboratory networks in Maharashtra and Karnataka capture incremental volume as decentralized infrastructure outpaces hospital centralization.
Brazil
ANVISA governs IVD registration pathways with extended review cycles for enzymatic assay platforms. Diagnostic laboratory expansion in São Paulo and Minas Gerais represents underpenetrated endpoints for decentralized testing infrastructure. Point-of-care protocol adoption in emergency departments differentiates myocardial infarction from pulmonary embolism, expanding addressable testing volume.
Lactate Dehydrogenase Test Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with automated platform suppliers commanding consolidated procurement relationships while reagent specialists compete on cost efficiency. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with ion chromatography expertise, vertically integrated reagent manufacturers, and automated platform specialists extending installed bases. Dominant competitive moves include software-defined calibration transitions toward subscription revenue models and geographic expansion into mid-tier diagnostic laboratory networks.
Among diversified conglomerates, Thermo Fisher Scientific occupies a position representing premium workflow anchoring in academic medical centers. Roche Diagnostics exemplifies the automated platform archetype, with placements extending into mid-tier hospital laboratories. Randox Laboratories Ltd. sits within the vertically integrated tier, sustaining cost positioning in high-throughput environments through captive reagent manufacturing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Randox Laboratories Ltd. |
| Roche Diagnostics |
| PerkinElmer Inc. |
| Merck KGaA |
| Abbott Laboratories |
| Danaher Corporation |
| Abcam plc. |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Fluorescence-based multiplexing platforms are compressing cost economics for high-sensitivity LDH quantification while concentrating manufacturing expertise among German and Japanese precision instrumentation clusters. This technological transition simultaneously elevates R&D amortization burdens and consolidates supplier power around captive reagent formulations.
Pricing Analysis
Distributor margins on enzymatic assay kits compress pricing power for mid-tier manufacturers serving diagnostic laboratories in India and Brazil. Three-tier pricing structure across premium, standard, and economy levels separates fluorescence platforms from conventional spectrophotometric systems and basic reagent bundles. Cost compression in economy-tier enzymatic reagents is intensifying because NADH cofactor supply chains concentrate in Swiss and German pharmaceutical intermediate manufacturers. Hospital procurement committees in United States integrated delivery networks exhibit lowest price sensitivity due to bundled multi-analyte platform contracts, while independent diagnostic laboratories in emerging markets demonstrate highest sensitivity to per-test reagent costs.
Supply Chain Analysis
ISO 15189 accreditation requirements and FDA CLIA amendment compliance gating filter supplier eligibility, elevating qualification costs for new market entrants. Manufacturing concentration centers on Germany, Japan, and the United States for precision instrumentation, while reagent formulation draws from industrial clusters in Switzerland and the United Kingdom. Critical dependencies include NADH cofactors, specialized optical components, and cold-chain logistics infrastructure. Single-source vulnerability persists for fluorescence detection module suppliers serving academic medical center pilot programs. Distribution runs through regional laboratory supply distributors in North America and direct-to-hospital contracts in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LDH test market functions as a stable compounder anchored by recurring reagent consumption patterns and regulatory-mandated platform upgrade cycles. CLIA quality benchmark tightening ensures sustained replacement demand regardless of macroeconomic fluctuations.
For Market Incumbents: Extend software-defined calibration offerings to capture recurring SaaS revenue beyond physical reagent sales, insulating against NADH price volatility. Deepen backward integration into specialty chemical intermediates to secure cofactor supply against Swiss and German manufacturer concentration. Strengthen ISO 15189 accreditation support services to accelerate customer compliance timelines and freeze out non-compliant competitors.
For New Entrants and Emerging Players: Launch via white-label partnerships with established diagnostic laboratory networks in Maharashtra and Karnataka, bypassing 12-18 month direct accreditation timelines. Target mid-tier independent laboratories in Brazil and India where decentralized infrastructure investment outpaces hospital centralization and incumbent platform saturation remains lowest. Emphasize fluorescence-based multiplexing capabilities to differentiate from entrenched spectrophotometric installed bases.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertically integrated reagent manufacturers with captive NADH formulation capabilities and limited instrument platform exposure. The five-to-ten year viability window favors suppliers with demonstrated EU MDR clinical performance validation and established companion diagnostic reimbursement pathways. Monitor FDA guidance harmonization with EMA on immuno-oncology monitoring claims as the critical inflection signal for platform upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Development | Shifts revenue model toward SaaS subscriptions beyond physical reagent sales. |
| EU MDR Clinical Performance Validation | Extends regulatory timelines but secures premium pricing in European hospital laboratories. |
| Companion Diagnostic Reimbursement Strategy | Opens recurring billing pathways tied to pembrolizumab and nivolumab therapy protocols. |
| Diagnostic Laboratory Network Partnership | Captures decentralized testing volume shifting from centralized hospital wards. |
| Backward Integration into NADH Supply | Reduces exposure to Swiss and German pharmaceutical intermediate price volatility. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers, alongside secondary validation against FDA 510(k) filings, CMS Medicare reimbursement data, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Conversations with diagnostic laboratory directors and regulatory affairs specialists at IVD manufacturers informed platform adoption timelines and compliance burden assessments. Secondary sources included EU MDR notified body guidance documents, ISO 15189 accreditation standards, and trade data on NADH cofactor imports.
Data-stream reconciliation anchored volume projections to segmented modeling across technology type, end-user channel, and application indication throughout the forecast period. Analytical frameworks incorporated instrument placement cycles, reagent consumption rates per installed platform, and regional regulatory pathway divergences. CAGRs were derived from weighted average of historical replacement demand, emerging fluorescence adoption curves, and decentralized infrastructure expansion trajectories. Industry-specific inputs included CLIA amendment implementation timelines and companion diagnostic reimbursement code adoption rates.
Several conditions sit outside the modeled scope, including unforeseen regulatory harmonization between FDA and EMA, disruptive non-enzymatic LDH detection technologies, and macroeconomic shocks affecting health system capital expenditure budgets. Forecasts reflect documented assumptions regarding reagent stability validation requirements and fluorescence platform training adoption curves. A model refresh is warranted upon material change in FDA guidance on immuno-oncology companion diagnostic claims or NADH supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market