
 Self-Monitoring Blood Glucose Strips Market | 2026-2036
Self-Monitoring Blood Glucose Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Monitoring Blood Glucose Strips Market Analysis
Bundle-to-strip unbundling is shifting how patients acquire glucose testing supplies, with meter-plus-strip starter kits giving way to standalone strip replenishment models that reduce upfront costs. Abbott Diabetes Care leverages its FreeStyle platform to sustain recurring strip revenue through locked sensor-strip ecosystems. Roche Diabetes Care competes by anchoring hospital procurement contracts that extend into home discharge protocols. Sinocare dominates retail pharmacy shelf space across Asia through aggressive unit pricing and local manufacturing scale.
Self-monitoring blood glucose strips are thin electrochemical biosensors, typically constructed from polyethylene terephthalate substrates coated with glucose oxidase or glucose dehydrogenase enzyme layers, designed to quantify capillary blood glucose concentration via handheld meters within seconds. Single-use strips generate the majority of unit volume globally, while high-sensitivity strips command premium positioning among insulin-dependent users requiring tighter glycemic control. Home users represent the largest end-user segment by volume, though diabetes clinics drive higher per-patient strip consumption through structured monitoring protocols.
FDA 510(k) clearance requirements and EMA In Vitro Diagnostic Regulation standards enforce minimum accuracy thresholds that reshape strip chemistry investments and manufacturing quality systems. ISO 15197 compliance for meter-strip system accuracy functions as a de facto market access gate for new entrants across North America and Europe. Stakeholders must monitor evolving reimbursement banding decisions by national health authorities, as strip coverage limits directly determine patient testing frequency and brand switching behavior.
Market Dynamics
Reimbursement banding decisions by national health authorities are compressing patient testing frequency and forcing brand switching behavior across the Self-Monitoring Blood Glucose Strips Market. CMS coverage limits in the United States and NHS rationing protocols in the United Kingdom directly constrain per-capita strip consumption despite rising diagnosed diabetic populations.
Growth Catalysts
- ISO 15197 Accuracy Mandates:Meter-strip system compliance requirements function as de facto market access gates across North America and Europe, filtering out substandard competitors and consolidating demand around certified manufacturers.
- Home-Based Diabetes Management:Elderly patients living independently are expanding strip consumption through structured self-monitoring programs that embed testing into daily routines.
- Enzyme Chemistry Advances:Glucose dehydrogenase formulations with improved oxygen insensitivity are displacing glucose oxidase in premium strip segments, reducing interference from hematocrit variations.
Market Restraints
- PET Substrate Cost Volatility:Polyethylene terephthalate prices fluctuate with crude oil derivatives, squeezing manufacturing margins for electrochemical biosensor substrates.
- Supply Concentration in East Asia:Precision coating equipment and enzyme raw material suppliers cluster in China and South Korea, creating single-source vulnerability for Western strip manufacturers.
- Continuous Glucose Monitor Substitution:Factory-calibrated sensor systems eliminate fingerstick requirements for Type 1 diabetics, eroding the highest-testing-frequency patient segment.
Strategic Opportunities
- India Retail Pharmacy Expansion:Underpenetrated tier-2 and tier-3 cities present white space for affordable strip brands as CDSCO streamlines IVD registration pathways.
- Telehealth Integration:Remote patient monitoring platforms create demand for Bluetooth-enabled meter-strip systems that transmit readings directly to clinical dashboards.
- Dual Carbon Goals in China:NMPA green manufacturing incentives favor domestic strip producers investing in solvent-reduced coating processes and recyclable substrate materials.
Industry Challenges
- FDA 510(k) Timeline Compression:New predicate device requirements and enhanced clinical data demands extend clearance cycles for novel strip chemistries, delaying revenue recognition.
- Legacy Meter Compatibility:Proprietary strip form factors lock patients into aging meter ecosystems, complicating product line transitions and obsolescence planning for manufacturers.
- Skill Scarcity in Precision Coating:Thin-film enzyme deposition requires specialized electrochemical engineering expertise that concentrates in a handful of regional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Monitoring Blood Glucose Strips Market |
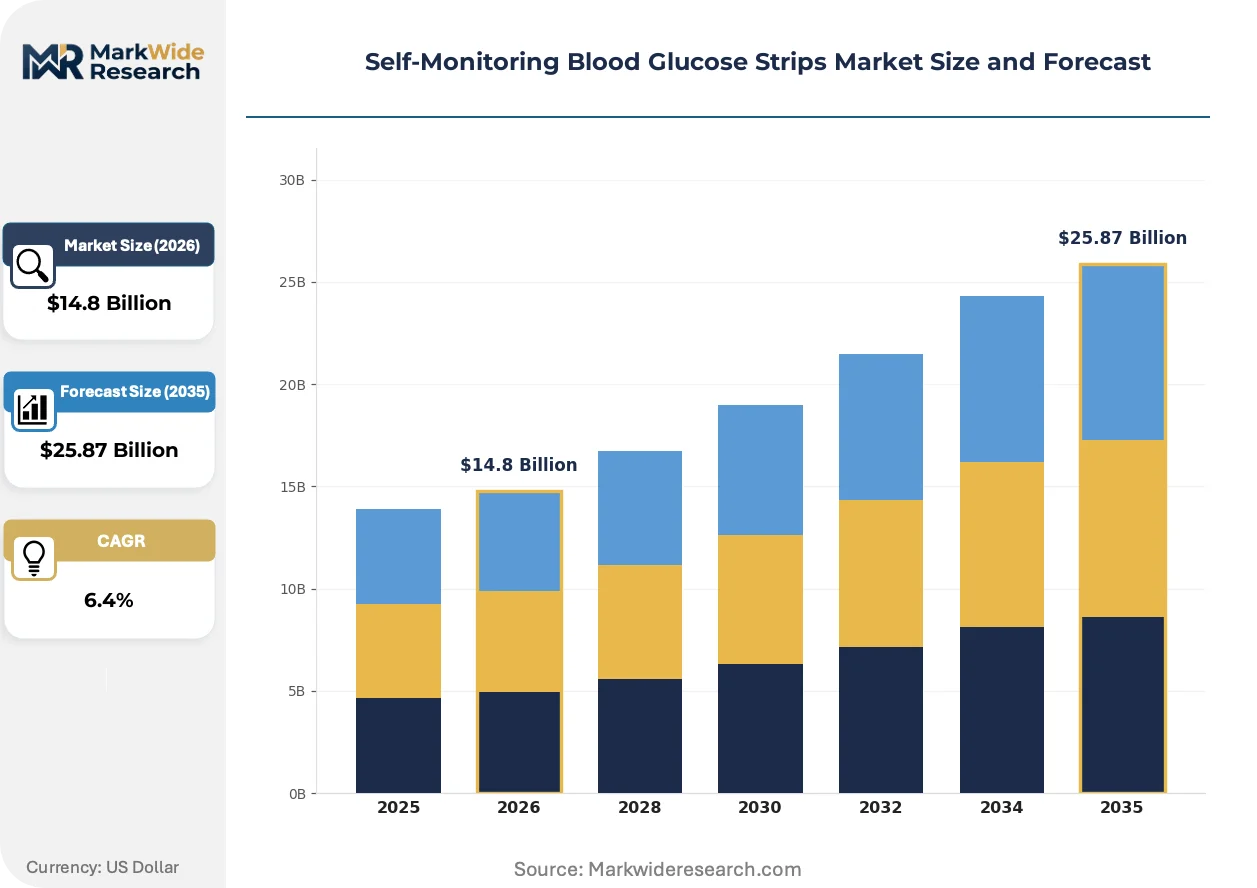
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Strips, Reusable Strips, High-Sensitivity Strips, Coding Strips End User: Home Users, Diabetes Clinics, Hospitals, Diagnostic Laboratories Distribution Channel: Retail Pharmacies, Online Stores, Wholesale Suppliers, Medical Supply Stores Application: Type 1 Diabetes, Type 2 Diabetes, Prediabetes, Insulin Therapy |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, LifeScan, Ascensia Diabetes Care, ARKRAY, Bionime Corporation, AgaMatrix, Sinocare, i-SENS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Monitoring Blood Glucose Strips Market Emerging Trajectories
Electrochemical biosensor architecture is fragmenting into interchangeable component layers that separate enzyme deposition from substrate handling. This decomposition of the traditional integrated strip is enabling new manufacturing partnerships and challenging established integrated production models.
Microfluidic channel designs with integrated hematocrit correction are modularizing the functional separation of sample handling from electrochemical measurement. Insulin-dependent users requiring tighter glycemic control are adopting these high-sensitivity configurations fastest. The technology is modularizing what were previously monolithic strip architectures into swappable functional blocks that reduce redesign cycles.
EMA In Vitro Diagnostic Regulation enforcement is tightening post-market surveillance requirements for glucose monitoring systems. Manufacturers must now maintain active complaint handling systems and periodic safety update reporting that extends far beyond initial CE marking. Small and mid-sized strip producers without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies or exiting European markets entirely.
Standalone strip replenishment models are displacing bundled meter-plus-starter-kit distribution through pharmacy direct-to-patient channels. Retail chains in Germany and the United States are capturing patient loyalty through subscription-based auto-refill programs that bypass traditional durable medical equipment suppliers. This channel compression is most visible among Medicare Part B beneficiaries in the United States where competitive bidding reforms have eliminated many local DME intermediaries.
Self-Monitoring Blood Glucose Strips Market Segmentation
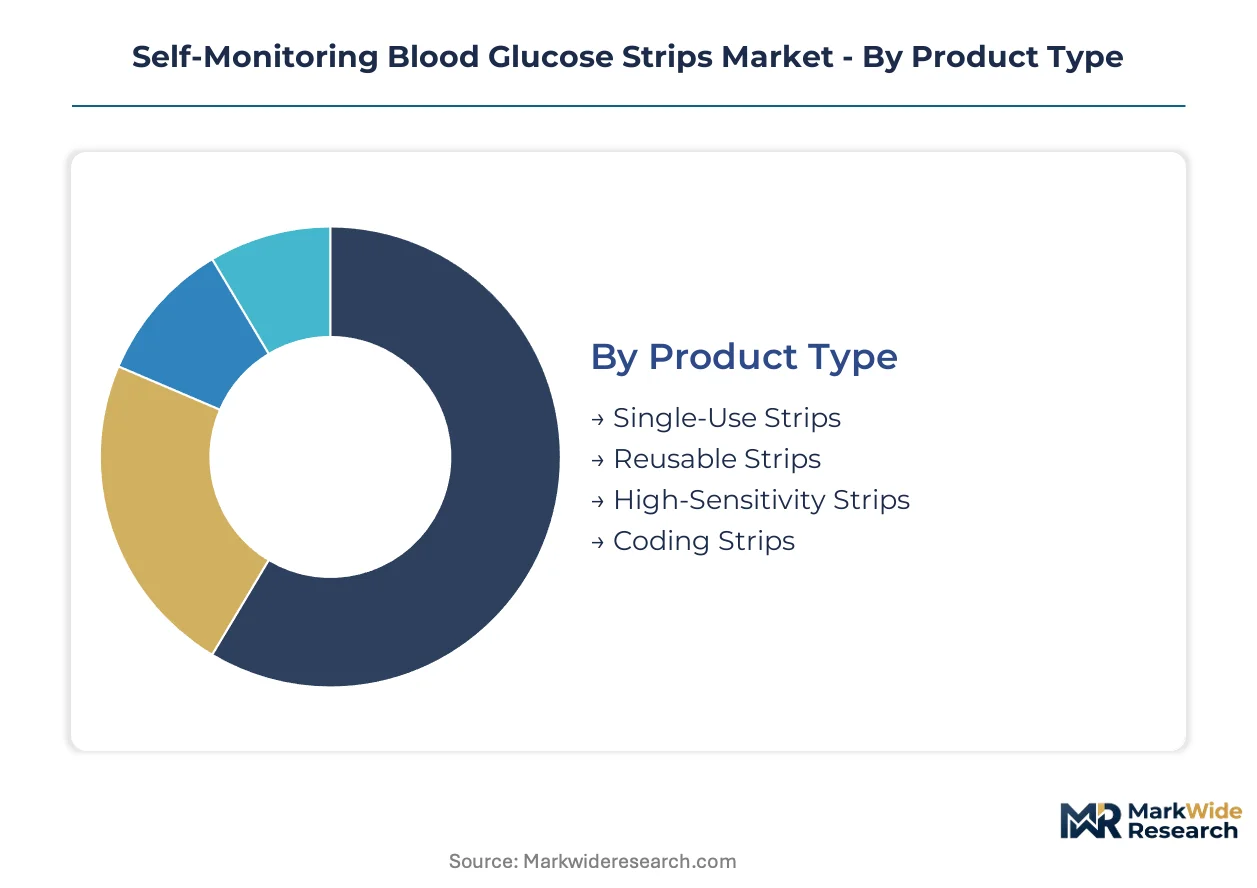
Segmentation in the Self-Monitoring Blood Glucose Strips Market reveals how capital allocation, reimbursement pathways, and patient behavior intersect. Manufacturers optimize production lines around strip chemistry and distribution economics rather than pursuing uniform scale across all configurations.
Product Type:
Capital intensity varies sharply across strip architectures, with enzyme formulation precision and coating equipment requirements determining minimum viable scale for each segment.
- Single-Use Strips:Disposable electrochemical biosensors built on polyethylene terephthalate substrates with glucose oxidase or glucose dehydrogenase enzyme layers. Home users in the United States and Germany consume the majority of unit volume as Medicare and statutory health insurance programs maintain broad reimbursement for daily testing protocols.
- High-Sensitivity Strips:Enhanced-accuracy configurations incorporating microfluidic channels with integrated hematocrit correction. Insulin-dependent patients requiring tight glycemic control drive demand concentration in diabetes clinics across China and the United States where structured monitoring protocols mandate frequent precision testing.
- Reusable Strips:Multi-test electrochemical sensors with wash-and-reuse protocols. Limited commercial penetration due to FDA 510(k) complexity and patient preference for disposability.
- Coding Strips:Calibration strips requiring manual code entry to match meter-strip batches. Declining share as factory-calibrated systems displace legacy compatibility requirements.
Single-use strips absorb the bulk of installed coating capacity; high-sensitivity strips are expanding most quickly among insulin-dependent populations.
End User:
Testing frequency and reimbursement intensity diverge substantially across patient settings, with per-capita strip consumption ranging from sporadic home monitoring to intensive clinical protocols.
- Home Users:Independent diabetic patients conducting self-monitoring without clinical supervision. Elderly populations in Germany and Japan generate sustained replenishment demand through pharmacy subscription programs embedded in long-term care insurance frameworks.
- Diabetes Clinics:Specialized outpatient facilities implementing structured glycemic control protocols. These settings in the United States and United Kingdom drive the highest per-patient strip volumes through mandated pre- and post-consultation testing regimens.
- Hospitals:Acute care facilities utilizing strips for perioperative glucose management and emergency department triage.
- Diagnostic Laboratories:Centralized testing facilities employing strips for high-throughput screening and confirmatory testing.
Home users dominate absolute unit volume; diabetes clinics command the steepest expansion trajectory as value-based care models intensify outpatient monitoring.
Distribution Channel:
Channel economics reshape manufacturer margin structures, with direct-to-patient models compressing intermediary layers while wholesale contracts secure institutional volume.
- Retail Pharmacies:Brick-and-mortar dispensaries capturing patient loyalty through auto-refill subscriptions. CVS and Walgreens in the United States plus Boots in the United Kingdom have built recurring revenue streams that bypass traditional durable medical equipment suppliers.
- Online Stores:E-commerce platforms enabling price comparison and bulk purchasing. Amazon and Tmall in China aggregate demand from price-sensitive patients in tier-2 and tier-3 cities where physical pharmacy penetration remains uneven.
- Wholesale Suppliers:Institutional procurement channels serving hospital systems and clinic networks through multi-year contracts.
- Medical Supply Stores:Specialized distributors targeting Medicare Part B beneficiaries with competitive bidding compliance requirements.
Retail pharmacies capture the majority of recurring patient relationships; online stores are gaining share fastest among younger, digitally native diabetic populations.
Application:
Disease severity and treatment intensity dictate testing frequency, with insulin therapy creating structural demand for precision monitoring regardless of diabetes classification.
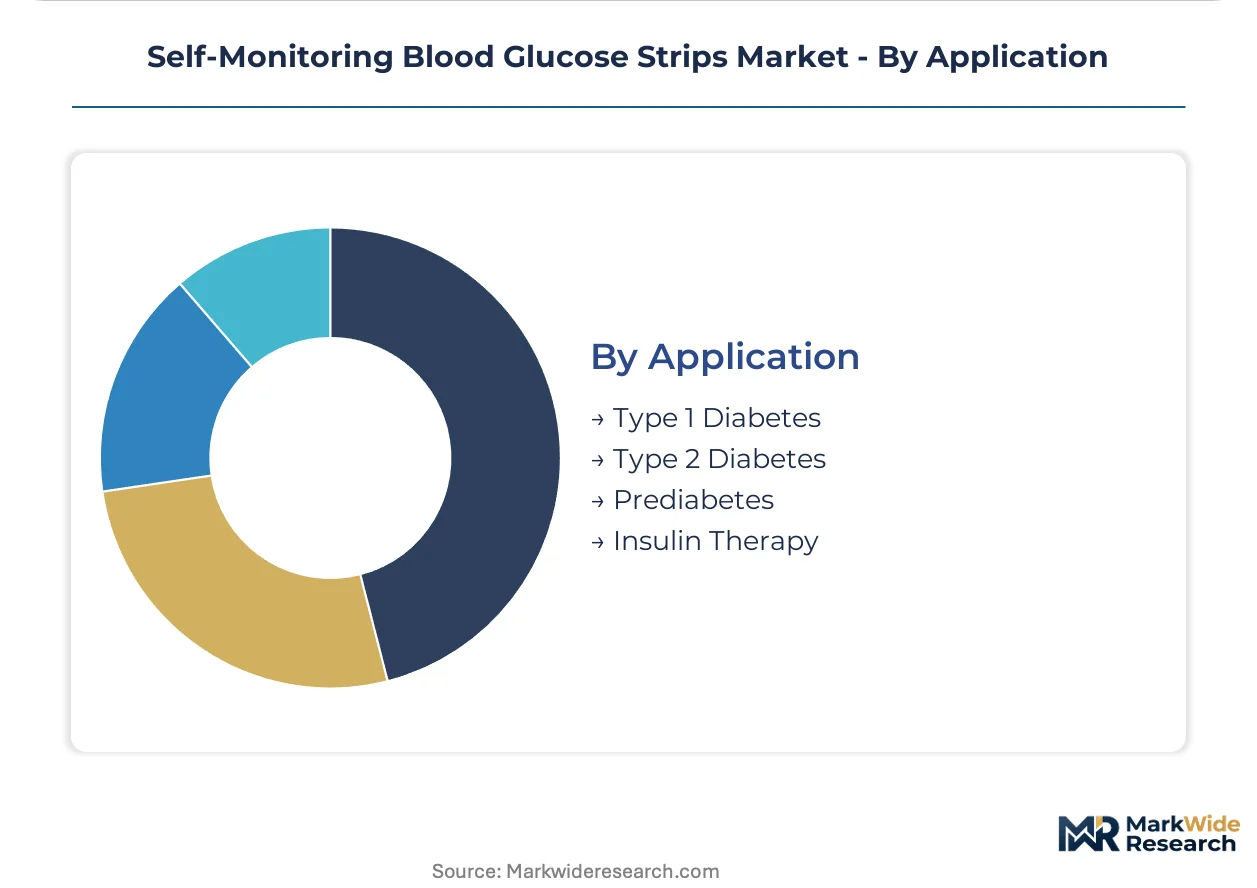
- Type 1 Diabetes:Autoimmune insulin deficiency requiring intensive glucose monitoring. Patients in the United States and Nordic countries maintain the highest testing frequencies as pump therapy and multiple daily injection regimens demand 4-10 daily measurements.
- Insulin Therapy:Glucose-lowering treatment protocol spanning Type 1, Type 2, and gestational diabetes. This cross-cutting application in Germany and Japan concentrates demand for high-accuracy strips as dosing decisions carry immediate hypoglycemic risk.
- Type 2 Diabetes:Insulin-resistant metabolic disorder managed through lifestyle, oral agents, or insulin. Testing intensity varies with medication regimen.
- Prediabetes:Elevated glucose below diabetic threshold requiring lifestyle intervention. Limited strip reimbursement constrains commercial significance.
Type 1 diabetes absorbs the bulk of precision-strip manufacturing capacity; insulin therapy applications are climbing the fastest as intensification protocols expand across Type 2 populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free Trade Zone and surrounding Yangtze River Delta industrial parks concentrate precision coating equipment suppliers serving electrochemical biosensor manufacturers. This tax-advantaged corridor anchors substrate handling and enzyme deposition capacity for Western and Asian strip producers alike.
United States
Medicare Part B competitive bidding reforms eliminated durable medical equipment intermediaries, compressing distribution layers and shifting volume toward retail pharmacy auto-refill subscriptions. FDA 510(k) clearance timelines for novel strip chemistries now extend beyond historical baselines as predicate device requirements tighten. Minnesota and Massachusetts host precision coating engineering talent clusters that supply process optimization consulting to domestic manufacturers.
Germany
Statutory health insurance maintains broad reimbursement for daily self-monitoring protocols, sustaining per-capita strip consumption among elderly home users. EMA In Vitro Diagnostic Regulation enforcement requires active complaint handling systems and periodic safety reporting that extends far beyond initial CE marking. Baden-Württemberg precision engineering firms supply thin-film deposition equipment to strip manufacturers across Europe.
China
NMPA green manufacturing incentives favor domestic producers investing in solvent-reduced coating processes and recyclable substrate materials under dual carbon goals. Tier-2 and tier-3 cities present white space for affordable strip brands as pharmacy penetration deepens beyond coastal metros. Shenzhen and Suzhou industrial zones concentrate domestic enzyme raw material suppliers and precision equipment fabricators.
India
CDSCO streamlines IVD registration pathways for affordable strip brands targeting underpenetrated tier-2 and tier-3 cities where physical pharmacy networks remain uneven. National health mission programs embed diabetes screening into primary care, expanding diagnosed populations eligible for self-monitoring supplies. Mumbai and Ahmedabad pharmaceutical clusters incubate local strip manufacturers competing on unit pricing against imports.
Japan
Long-term care insurance frameworks embed pharmacy subscription programs for elderly diabetic populations, generating sustained replenishment demand through structured self-monitoring. METI industrial standards for electrochemical biosensors enforce accuracy thresholds that filter substandard imports. Osaka-Kobe manufacturing corridor hosts precision coating equipment suppliers serving domestic and regional strip producers.
Self-Monitoring Blood Glucose Strips Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation concentrates around manufacturers with captive enzyme chemistry capabilities and integrated coating operations. Three archetypes dominate: multinational health technology conglomerates with diabetes care divisions, regional pure-play specialists with local manufacturing scale, and emerging Asian producers competing on unit economics. Competitive moves center on hospital procurement contract anchoring and retail pharmacy direct-to-patient channel capture.
Among multinational health technology conglomerates, Abbott Diabetes Care and Roche Diabetes Care exemplify the integrated-platform archetype, each anchoring recurring revenue through locked meter-strip ecosystems. Sinocare represents the regional scale-driven specialist, occupying a position defined by aggressive unit pricing and domestic manufacturing concentration across Asian retail pharmacy networks. These three anchors illustrate how competitive positioning stratifies between premium accuracy positioning and volume-driven accessibility.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| LifeScan |
| Ascensia Diabetes Care |
| ARKRAY |
| Bionime Corporation |
| AgaMatrix |
| Sinocare |
| i-SENS |
| Others |
Supply Flow & Price Mechanics
Enzyme raw material costs originating from Chinese and South Korean fermentation facilities cascade through three distinct pricing tiers, with glucose dehydrogenase formulations commanding premium positioning over glucose oxidase alternatives while PET substrate volatility squeezes margins at the economy tier.
Pricing Analysis
Cost-down pressure on standard-tier strips accelerates because CMS competitive bidding reforms and NHS rationing protocols constrain reimbursement ceilings, forcing manufacturers to absorb PET substrate volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15197-certified systems with microfluidic hematocrit correction from basic single-use configurations and private-label pharmacy brands. Price differentiation rests on certification grade and manufacturing scale, with insulin-dependent users showing lowest price sensitivity and prediabetes-screening populations exhibiting highest elasticity.
Supply Chain Analysis
Specialized electrochemical engineering expertise concentrates in the Shanghai-Suzhou corridor and Osaka-Kobe manufacturing belt, creating workforce scarcity that limits coating capacity expansion for Western entrants. Precision coating equipment and enzyme raw material suppliers cluster in China, South Korea, and Japan, drawing from polyethylene terephthalate substrate producers and glucose dehydrogenase fermentation specialists. Single-source vulnerability around precision deposition equipment creates structural risk, while distribution runs through retail pharmacy auto-refill subscriptions and hospital procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film enzyme deposition capacity scarcity props pricing power for incumbent manufacturers with captive coating operations, constraining volume expansion for competitors lacking integrated production.
For Market Incumbents: Anchor hospital procurement contracts that extend into home discharge protocols to defend against continuous glucose monitor substitution, while investing in solvent-reduced coating processes to capture NMPA green manufacturing incentives in China. Backward integration into enzyme fermentation secures supply continuity as raw material suppliers consolidate in East Asia. For New Entrants and Emerging Players: Enter via CDSCO-streamlined IVD registration pathways targeting India's tier-2 and tier-3 cities, where pharmacy penetration remains uneven and affordable strip brands face limited multinational competition. White space exists in Bluetooth-enabled meter-strip systems for telehealth integration, with pharmacy direct-to-patient subscriptions offering the most penetrable go-to-market angle. For Investors and Strategic Acquirers: EMA In Vitro Diagnostic Regulation enforcement extending post-market surveillance requirements is the leading indicator that regulatory compliance scale will determine long-term viability, favoring acquisition targets with dedicated regulatory affairs functions and active complaint handling systems. Watch for FDA 510(k) timeline compression signals that would disadvantage smaller players lacking clinical data generation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance unlocks European market access for certified meter-strip systems. |
| Hospital System Partnership | Roche Diabetes Care anchors procurement contracts extending from acute care into home discharge protocols. |
| Software Companion Development | Bluetooth-enabled meters transmitting readings to clinical dashboards capture telehealth integration demand. |
| Reimbursement Strategy | Medicare Part B competitive bidding compliance determines auto-refill subscription eligibility for pharmacy channels. |
| Green Manufacturing Transition | Solvent-reduced coating processes align with NMPA incentives under China's dual carbon goals framework. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA In Vitro Diagnostic Regulation submissions, and CMS Medicare reimbursement databases, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at glucose monitoring device manufacturers. Secondary sources included ISO 15197 certification records, hospital procurement databases, and trade data on PET substrate imports. Bottom-up strip volume estimates triangulated against top-down market sizing from reimbursement coverage analysis.
Cross-referencing historical testing frequency patterns against clinician panel input on protocol intensification trends shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include strip chemistry type, end-user setting, distribution channel, and insulin therapy status. CAGRs derived from patient population growth, reimbursement banding adjustments, and testing protocol evolution. Industry-specific inputs incorporated enzyme chemistry substitution rates and continuous glucose monitor penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated CGM substitution or abrupt reimbursement compression. Forecasts reflect assumptions on regulatory timeline stability and raw material supply continuity. Material deviation in FDA predicate device requirements or NMPA green manufacturing incentive scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
North America Insulin Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Digital Diabetes Management Market