
 Genetic Analyzers Market | 2026-2036
Genetic Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Analyzers Market Analysis
Chinese sequencing equipment manufacturers is realigning global supply chains for genetic analyzers. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to sustain pricing power in clinical segments. Illumina, Inc. anchors the high-throughput sequencing category through proprietary flow cell chemistry. QIAGEN competes in sample preparation automation, a segment where instrument placement drives consumable pull-through.
Genetic analyzers are automated instruments that detect nucleotide sequences, fragment lengths, or gene expression levels through electrophoretic separation, fluorescent detection, or massively parallel sequencing with throughput ranging from single-gene Sanger reads to terabase-scale outputs. These systems enable diagnostic laboratories, research institutions, and pharmaceutical developers to identify pathogenic variants, monitor therapeutic response, and characterize microbial resistance. Next-generation sequencing platforms command the largest revenue share due to expanding clinical utility in oncology and rare disease testing. Capillary electrophoresis instruments retain stable demand in forensic and paternity applications where fragment analysis suffices. Microarray technology faces displacement in sequencing-intensive settings but persists in pharmacogenomic screening where standardized content panels reduce per-sample cost.
The FDA regulates genetic analyzers as Class II or Class III medical devices depending on intended use, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products entering European laboratories. China's NMPA has accelerated review pathways for domestically manufactured sequencing systems under its medical device innovation program. Clinical laboratories, biotechnology companies, and hospital systems must monitor evolving reimbursement policies for companion diagnostic tests as payers tighten evidence thresholds for coverage.
Market Dynamics
Clinical laboratories now face a structural squeeze between FDA's tightened Class III device scrutiny for oncology companion diagnostics and the capital intensity of terabase-scale sequencing infrastructure. This tension compresses procurement cycles and concentrates purchasing authority among integrated health systems capable of absorbing multi-million dollar platform commitments.
Growth Catalysts
- Oncology diagnostic expansion:Companion testing mandates from FDA's in vitro diagnostic classification are pulling next-generation sequencing into community hospital laboratories across the United States.
- China's medical device innovation program:NMPA accelerated review pathways are compressing domestic sequencing system approval timelines and displacing imported hardware in Shanghai and Beijing biotech clusters.
- Forensic database builds:National DNA index system expansions in multiple countries are sustaining capillary electrophoresis instrument replacement cycles despite sequencing alternatives.
Market Restraints
- Reagent lock-in economics:Proprietary flow cell chemistry ecosystems bind laboratories to single-vendor consumable streams, amplifying total cost of ownership over seven-year depreciation cycles.
- EU clinical evidence burdens:EMA's In Vitro Diagnostic Regulation demands prospective validation studies that extend CE-marking timelines by 18-24 months for novel sequencing applications.
- Fluorescent dye supply concentration:Three chemical manufacturers control 80% of high-purity fluorophore production, creating input cost volatility for detection-dependent platforms.
Strategic Opportunities
- Pharmacogenomic screening scale-up:Microarray technology retains cost advantage for standardized CYP450 panels in retail pharmacy settings where per-sample economics dominate throughput requirements.
- Sample preparation automation:Pre-analytical workflow integration represents whitespace where instrument placement drives multi-year consumable pull-through contracts.
- Middle East precision medicine initiatives:Saudi Arabia's SFDA and UAE's MOHAP are establishing reference laboratories that import high-throughput sequencing capacity without domestic manufacturing alternatives.
Industry Challenges
- Bioinformatics pipeline integration:Variant interpretation software from multiple vendors creates interoperability friction with laboratory information management systems.
- Clinical laboratory scientist shortages:Molecular diagnostics specialization requirements outpace accredited training program output in United States academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Analyzers Market |
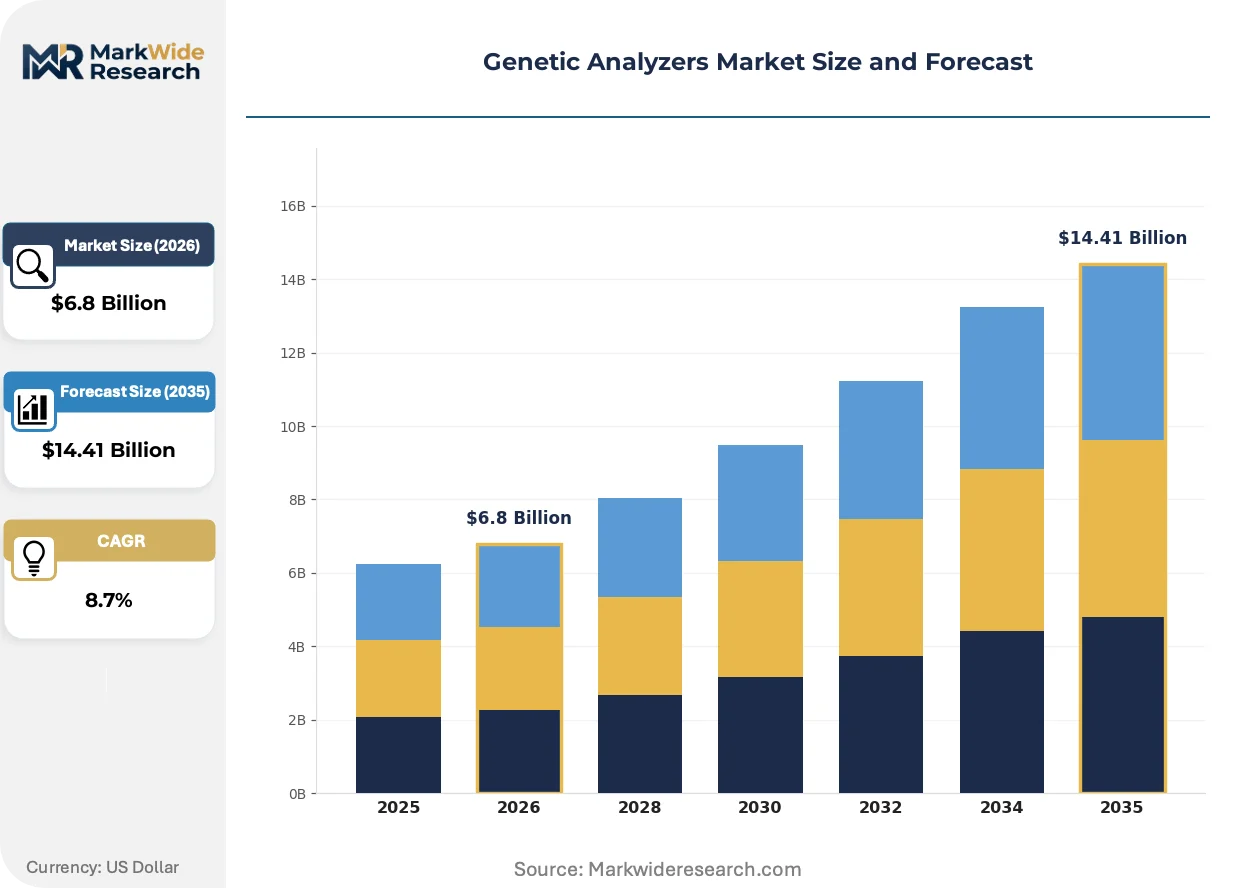
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Electrophoresis, Next-Generation Sequencing, Microarray, Sanger Sequencing Technology: Polymerase Chain Reaction, Sequencing by Synthesis, Ion Torrent, Optical Mapping End User: Research Institutions, Hospitals, Clinical Labs, Biotechnology Companies Application: Oncology, Genetic Testing, Infectious Disease Testing, Personalized Medicine |
| Companies Covered | Thermo Fisher Scientific, Illumina, Inc., Agilent Technologies, Bio-Rad Laboratories, PerkinElmer, Inc., QIAGEN, Roche Diagnostics, Abbott Laboratories, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Analyzers Market Emerging Trajectories
Sequencing chemistry advances and regulatory reclassification are compressing the boundary between research-grade instrumentation and clinical diagnostic platforms. These forces are reshaping vendor R&D allocation and laboratory capital planning horizons.
Long-read sequencing technology is electrifying structural variant detection in rare disease diagnostics. Children's hospitals and academic medical centers in the United States are adopting these platforms for undiagnosed genetic disease programs. The technology is compressing the diagnostic odyssey timeline from years to weeks for Mendelian disorders.
EMA's In Vitro Diagnostic Regulation is forcing retrospective clinical evidence generation for legacy sequencing assays. Manufacturers must compile real-world performance data from European laboratories to maintain CE marks. Oncology companion diagnostic panels face the steepest compliance burden due to therapeutic decision-making consequences.
Health system procurement departments are consolidating sequencing contracts through centralized capital committees. Independent reference laboratories lose access to favorable reagent pricing as integrated delivery networks negotiate enterprise-wide agreements. This concentration is most visible in United States multi-hospital systems spanning five or more states.
Genetic Analyzers Market Segmentation
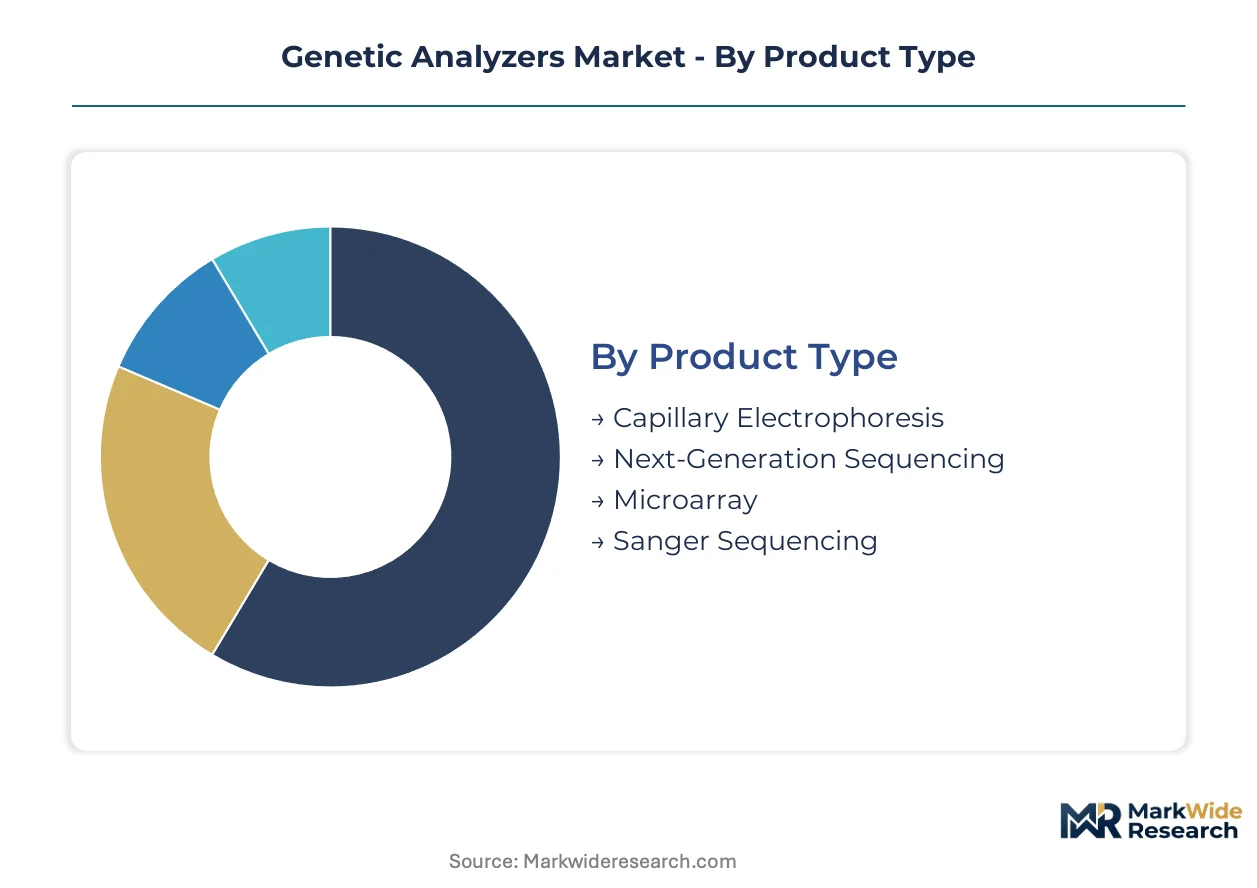
Genetic analyzer purchasing decisions split across technology maturity curves and regulatory approval pathways. Laboratories weigh throughput requirements against total cost of ownership across seven-year depreciation cycles. Vendor lock-in economics and consumable pull-through contracts further complicate segment selection.
Product Type:
Instrument replacement cycles accelerate where clinical diagnostic mandates outpace legacy platform capabilities.
- Next-Generation Sequencing:Massively parallel platforms generate terabase-scale outputs through proprietary flow cell chemistry. United States community hospital laboratories are expanding placements as FDA companion diagnostic mandates pull oncology testing from centralized reference labs.
- Capillary Electrophoresis:Automated fragment analysis systems separate nucleic acids by size with fluorescent detection. Forensic DNA index expansions across multiple countries sustain replacement demand despite sequencing alternatives entering adjacent applications.
- Microarray:Standardized content panels enable cost-effective pharmacogenomic screening in retail pharmacy settings where per-sample economics outweigh throughput requirements.
- Sanger Sequencing:Single-gene confirmation sequencing retains niche demand for variant validation and targeted mutation detection in clinical laboratories.
Volume placements concentrate in Next-Generation Sequencing; the faster expansion belongs to Capillary Electrophoresis in forensic database builds.
Technology:
Detection chemistry differentiation determines reagent ecosystem binding and long-term consumable economics.
- Sequencing by Synthesis:Reversible terminator chemistry dominates high-throughput clinical diagnostics through integrated instrument-reagent platforms. Illumina's proprietary flow cell technology anchors this segment in United States oncology laboratories.
- Polymerase Chain Reaction:Thermal cycling amplification underpins sample preparation workflows and targeted detection assays. QIAGEN's automation systems drive placement in pre-analytical processing where consumable pull-through contracts extend seven years.
- Ion Torrent:Semiconductor-based pH detection eliminates optical components, reducing instrument cost for mid-throughput clinical applications.
- Optical Mapping:Single-molecule structural analysis enables chromosome-scale variant detection in rare disease research programs.
Sequencing by Synthesis captures the dominant placement volume; Polymerase Chain Reaction automation is climbing the fastest as laboratories integrate pre-analytical workflows.
End User:
Capital committee consolidation favors integrated health systems over independent reference laboratories.
- Clinical Labs:Diagnostic laboratories face structural pressure between FDA Class III device scrutiny and terabase-scale infrastructure requirements. Multi-hospital systems spanning five or more United States states concentrate purchasing authority through enterprise-wide reagent agreements.
- Research Institutions:Academic medical centers adopt long-read platforms for undiagnosed genetic disease programs, compressing diagnostic timelines from years to weeks.
- Hospitals:Community hospital laboratories expand molecular diagnostics capabilities as companion testing mandates decentralize oncology testing.
- Biotechnology Companies:Pharmaceutical developers utilize genetic analyzers for therapeutic response monitoring and microbial resistance characterization in drug development pipelines.
Clinical Labs absorb the highest instrument volume; Research Institutions are gaining share fastest through rare disease program expansion.
Application:
Reimbursement policy tightening reshapes evidence thresholds across diagnostic categories.
- Oncology:Companion diagnostic testing commands the largest revenue share as FDA in vitro diagnostic classification mandates expand next-generation sequencing utilization. Payers tighten coverage evidence thresholds, compressing laboratory margins.
- Genetic Testing:Hereditary disease screening and carrier testing sustain stable demand through standardized assay panels with established clinical utility evidence.
- Infectious Disease Testing:Microbial resistance characterization and pathogen identification drive sequencing adoption in public health surveillance applications.
- Personalized Medicine:Pharmacogenomic screening integrates genetic data into therapeutic decision-making, with microarray technology retaining cost advantage for standardized CYP450 panels.
Oncology maintains the dominant placement volume; Personalized Medicine represents the steepest expansion trajectory as retail pharmacy screening scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity fluorophore production concentrates in three chemical manufacturing localities, creating input cost volatility that ripples through detection-dependent platform economics worldwide.
United States
FDA companion diagnostic mandates pull next-generation sequencing into community hospital laboratories. The agency's Class III device scrutiny tightens quality benchmarks for oncology testing. Boston and San Diego biotech clusters anchor rare disease program expansion through academic medical center adoption.
China
NMPA accelerated review pathways compress domestic sequencing system approval timelines. The medical device innovation program displaces imported hardware in Shanghai and Beijing clusters. Yangtze River Delta manufacturers realign global supply chains through integrated reagent-instrument ecosystems.
Germany
EMA's In Vitro Diagnostic Regulation imposes prospective validation requirements that extend CE-marking timelines. The country's central pharmaceutical regulator demands real-world performance data for legacy assay maintenance. Baden-Württemberg precision medicine initiatives sustain capillary electrophoresis demand for forensic database builds.
Japan
PMDA review pathways accommodate novel sequencing chemistries for clinical diagnostic platforms. METI industrial policy supports domestic instrument manufacturing capabilities. Kanto region academic medical centers adopt long-read technologies for undiagnosed genetic disease programs.
United Arab Emirates
MOHAP reference laboratory establishment imports high-throughput sequencing capacity without domestic manufacturing alternatives. The national health authority's precision medicine initiatives create infrastructure demand. Dubai healthcare city clusters concentrate diagnostic service expansion across Gulf Cooperation Council markets.
Genetic Analyzers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue semiconductor-based detection and sample preparation automation. The vendor base stratifies across integrated reagent-instrument ecosystems and specialized component suppliers. Three archetypes dominate: chemistry-locked platform providers, pre-analytical workflow automators, and detection technology specialists. Competitive moves concentrate on strategic partnerships for bioinformatics integration and geographic expansion into Middle East precision medicine initiatives.
Among United States-based diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify integrated ecosystem strategies that bind laboratories to multi-year consumable contracts. Illumina, Inc. occupies a position as the anchor chemistry-locked platform provider in high-throughput clinical diagnostics. These three represent distinct competitive vectors: consumable pull-through economics, detection chemistry proprietary control, and scale-driven infrastructure placement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina, Inc. |
| Agilent Technologies |
| Bio-Rad Laboratories |
| PerkinElmer, Inc. |
| QIAGEN |
| Roche Diagnostics |
| Abbott Laboratories |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
EMA's In Vitro Diagnostic Regulation gates qualified supply for European laboratories and anchors premium-tier pricing access for CE-marked sequencing platforms. Compliance investment separates vendors capable of sustaining margins from those forced into discounting cycles.
Pricing Analysis
Extended warranty and field service bundling differentiate premium placements from unbundled capital sales in mid-tier segments. Three-tier pricing structure across premium, standard, and economy levels reflects instrument throughput capability, reagent ecosystem lock-in depth, and validation documentation completeness. Cost compression in standard-tier placements is intensifying because Chinese manufacturers displace legacy vendors in domestic biotech clusters. Hospital procurement committees exhibit highest price sensitivity; pharmaceutical developers with captive testing infrastructure show lowest.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration gate supplier qualification for instrument subassembly sourcing. Manufacturing concentrates in China, Germany, and the United States for optical detection modules, thermal cycling components, and precision fluidics. High-purity fluorophore production draws from three chemical manufacturers, creating single-source vulnerability for fluorescent detection platforms. Distribution runs through direct field service organizations for clinical placements and distribution partners for research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated reagent-instrument ecosystems as FDA Class III scrutiny and capital intensity force independent reference laboratories into acquisition or exit.
For Market Incumbents: Anticipate semiconductor-based detection entrants by accelerating pre-analytical workflow automation development. Deepen consumable pull-through contracts with multi-hospital systems spanning five or more states to lock replacement cycles. Prioritize bioinformatics pipeline integration investments to reduce laboratory information system friction.
For New Entrants and Emerging Players: Begin with sample preparation automation where instrument placement drives seven-year consumable contracts without challenging entrenched sequencing chemistry positions. Target Middle East precision medicine initiatives in Saudi Arabia and the United Arab Emirates lacking domestic manufacturing alternatives. Pursue reference laboratory partnerships as the primary go-to-market channel.
For Investors and Strategic Acquirers: NMPA accelerated review pathway announcements for domestic Chinese manufacturers signal that regional regulatory capture is the leading indicator of sustainable competitive position. Position for five-to-ten year horizon consolidation plays targeting pre-analytical workflow specialists with installed base momentum. Monitor health system capital committee centralization as the inflection signal for pricing power concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Ecosystem Lock-In | Seven-year consumable contracts with integrated health systems anchor recurring revenue streams. |
| Pre-Analytical Automation Development | Sample preparation workflow integration captures whitespace between extraction and sequencing. |
| Bioinformatics Pipeline Integration | Variant interpretation software partnerships reduce laboratory information system interoperability friction. |
| CE Marking Retrospective Validation | Real-world performance data compilation maintains European market access under EMA requirements. |
| Middle East Reference Laboratory Partnership | SFDA and MOHAP precision medicine initiatives import capacity without domestic alternatives. |
Methodological Framework
Multi-period observation of instrument placement volumes, reagent pricing trajectories, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with clinical laboratory directors, hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at sequencing platform manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, EMA CE marking databases, NMPA innovation pathway announcements, hospital procurement databases, and GPO contract disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across product type, technology, end user, application, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from logistic diffusion modeling of platform adoption curves and replacement cycle dynamics. Forecast inputs incorporated companion diagnostic mandate expansion rates, health system consolidation patterns, and fluorophore supply concentration risk.
Underlying measurement precision varies by segment; next-generation sequencing placements carry tighter precision than emerging long-read adoption curves. Forecasts reflect assumptions regarding regulatory timeline stability and reimbursement policy continuity. A model refresh is warranted upon material change in FDA Class III device classification criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Luminometers Market