
 Creatinine Meter Market | 2026-2036
Creatinine Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Creatinine Meter Market Analysis
Clinical-grade accuracy is unwinding legacy tolerance bands that previously accepted wider measurement variance in creatinine testing. Nova Biomedical leverages its hospital-installed base to sustain recurring consumable revenue. Abbott anchors point-of-care positioning through handheld electrochemical architectures. Siemens Healthineers competes on integrated laboratory workflow automation.
A creatinine meter is an analytical instrument that quantifies creatinine concentration in blood or urine specimens, typically operating via enzymatic colorimetric or amperometric biosensor detection with reported precision thresholds of ±5 percent coefficient of variation. The device serves nephrology monitoring, drug dosing protocols, and chronic kidney disease staging across clinical and ambulatory settings. Portable meters and handheld devices lead volume shipment counts, while bench-top meters retain margin concentration in reference laboratories. Electrochemical technology is displacing photometric methods in point-of-care deployments due to faster turnaround and reduced sample volume requirements.
The FDA governs 510(k) clearance pathways for creatinine meters intended for clinical decision-making, while the Clinical Laboratory Improvement Amendments establish proficiency testing and quality control benchmarks that shape product development priorities. ISO 15189 accreditation standards for medical laboratories in Europe and analogous frameworks from Japan's PMDA create parallel compliance architectures that manufacturers must navigate for multi-region commercialization. Stakeholders should monitor evolving home-use regulatory pathways and reimbursement coding decisions that will determine whether consumer-accessible creatinine testing achieves scalable adoption outside traditional care settings.
Market Dynamics
Electrochemical biosensor architectures are compressing turnaround times from hours to minutes, forcing legacy photometric systems into reference-laboratory niches and rewriting point-of-care procurement criteria across nephrology departments.
Growth Catalysts
- CLIA-waived test expansion:The FDA's streamlined 510(k) pathways for moderate-complexity devices accelerate hospital point-of-care adoption without requiring laboratory technician oversight.
- Diabetes-nephrology comorbidity protocols:Endocrinology clinics integrate creatinine screening into routine HbA1c workflows, creating bundled testing demand for dual-parameter meters.
- Enzymatic dry chemistry strips:Room-temperature stability eliminates cold-chain logistics, enabling pharmacy retail distribution in rural and emerging markets.
Market Restraints
- Platinum-group metal cost volatility:Electrochemical electrodes depend on iridium and ruthenium catalysts, exposing manufacturers to commodity price swings from South African and Russian supply concentration.
- Proficiency testing burden:CLIA mandates bi-annual external quality assessment for waived devices, creating recurring compliance costs that deter smaller diagnostic entrants.
- Central laboratory consolidation:Health system mergers concentrate purchasing power among integrated delivery networks, squeezing point-of-care device margins through volume-based contracting.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled meters feeding cloud-based EHR platforms capture chronic kidney disease management contracts from Medicare Advantage plans.
- Pharmacy clinic expansion:MinuteClinic and similar retail health models seek CLIA-waived creatinine testing to support metformin prescribing protocols in prediabetic populations.
- ISO 15189 harmonization:Convergence of European accreditation standards with FDA quality system regulations reduces dual-certification costs for multi-region product launches.
Industry Challenges
- Electrochemical engineer scarcity:Amperometric biosensor design requires specialized expertise in thin-film electrode fabrication, constraining R&D throughput at mid-tier manufacturers.
- Legacy LIS integration complexity:Hospital information systems built on HL7 v2.x architectures demand costly middleware development to accommodate wireless meter data streams.
- Biomarker patent thickets:Enzyme stabilizer formulations and interference-blocking membranes sit within dense intellectual property landscapes, complicating freedom-to-operate analyses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatinine Meter Market |
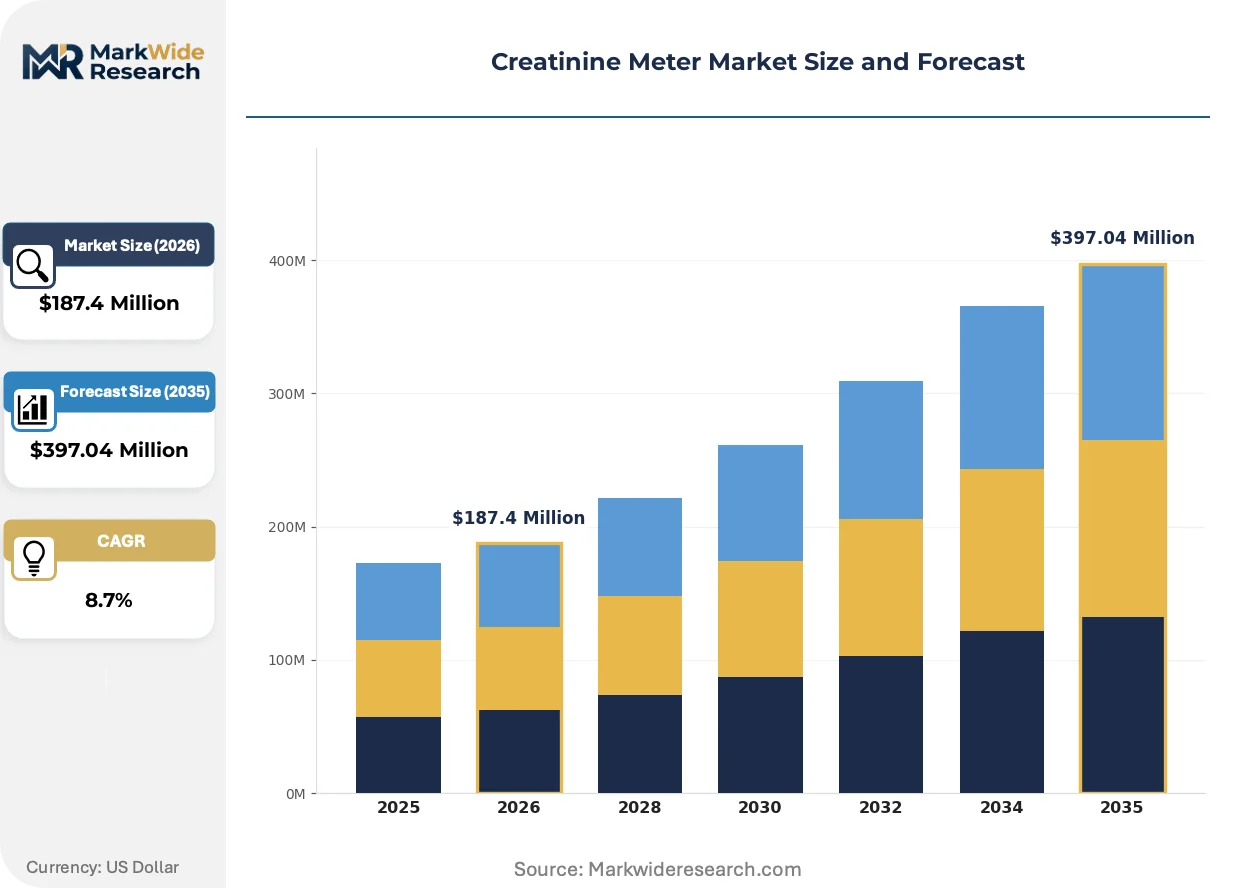
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Bench-top Meters, Handheld Devices, Continuous Monitoring Devices End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Technology: Colorimetric, Electrochemical, Photometric, Biosensor Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Others |
| Companies Covered | Nova Biomedical, Abbott, Thermo Fisher Scientific, Siemens Healthineers, Randox Laboratories, DH Life Sciences, MedTest Holdings, DiaSys Diagnostic Systems, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatinine Meter Market Emerging Trajectories
Creatinine meter development is splitting along performance-versus-convenience axes, with clinical laboratories demanding reference-grade precision while home-use segments prioritize connectivity and simplified workflows.
Amperometric biosensor technology is bifurcating the competitive landscape. Screen-printed carbon electrodes with immobilized creatinine deiminase enable sub-microliter sample volumes. Dialysis centers and emergency departments adopt these systems for rapid drug-dosing decisions. The technology is bifurcating procurement budgets, with capital allocations separating high-throughput laboratory analyzers from disposable handheld units.
Europe's Medical Device Regulation (MDR) intensifies post-market surveillance obligations for Class IIa diagnostic devices. Manufacturers must maintain clinical evidence registries and periodic safety update reports. Point-of-care creatinine meters with software-as-a-service components face heightened scrutiny in Germany and France, prompting vendors to segregate European product SKUs from US configurations.
Hospital procurement committees now unbundle device acquisition from consumable supply agreements. Integrated delivery networks negotiate meter placement at nominal cost while locking in multi-year reagent strip contracts. This purchasing pattern shift concentrates negotiating leverage among group purchasing organizations in the United States, compressing standalone device margins while securing recurring revenue streams for incumbent suppliers.
Creatinine Meter Market Segmentation
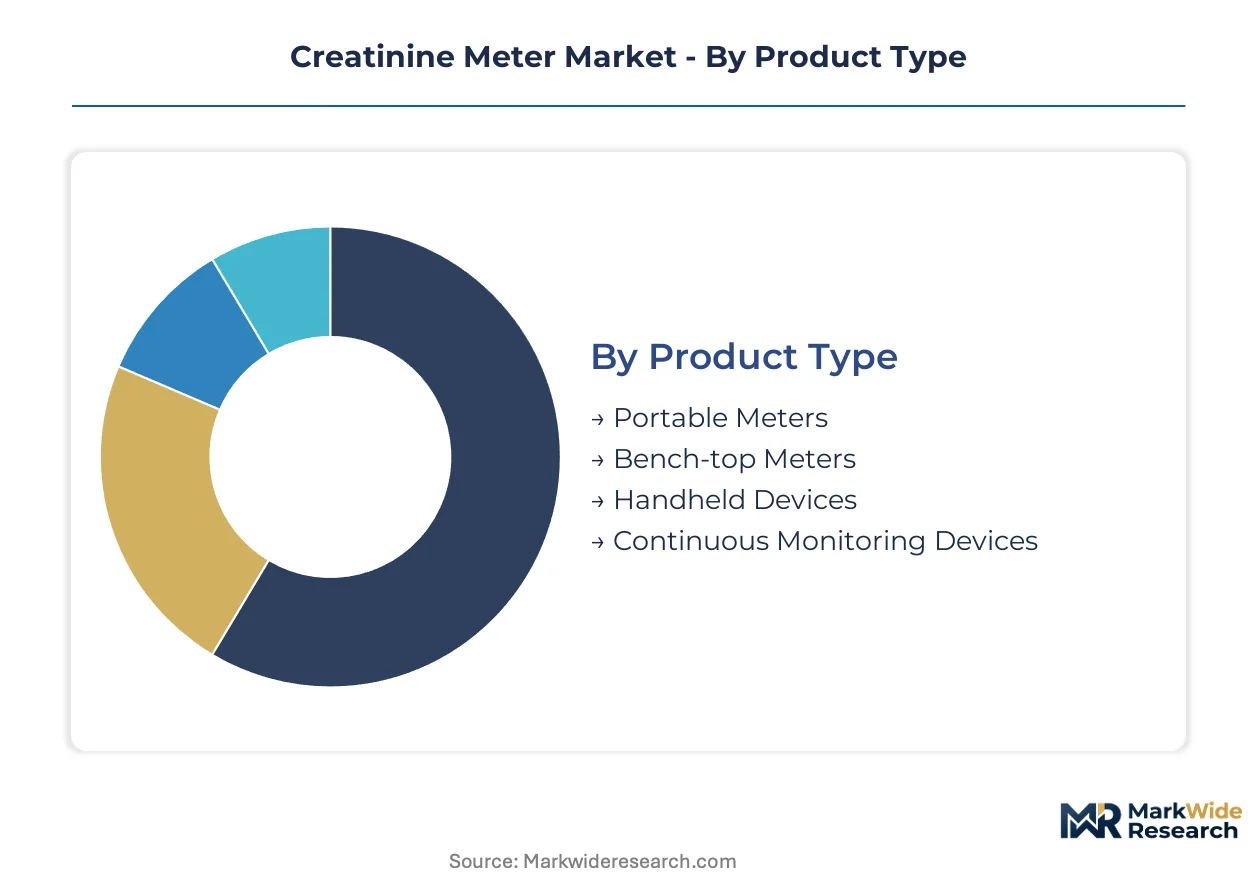
Creatinine meter procurement splits sharply between clinical precision requirements and ambulatory convenience demands. Substitution threats from laboratory outsourcing and emerging wearable biomarkers reshape segment prioritization across manufacturers' R&D portfolios.
Product Type:
Portable meters face the most acute substitution pressure from smartphone-connected continuous monitoring patches entering validation trials.
- Portable Meters:Battery-operated units with electrochemical strip readers deliver results in under 60 seconds from capillary samples. Hospital emergency departments and dialysis centers in the United States concentrate procurement for rapid drug-dosing protocols, though reimbursement compression under Medicare's hospital outpatient prospective payment system constrains margin expansion.
- Handheld Devices:Pocket-sized amperometric systems with Bluetooth connectivity target pharmacy clinic workflows and home care monitoring contracts. MinuteClinic and similar retail health models in Texas and Florida drive volume for CLIA-waived configurations supporting metformin prescribing decisions.
- Bench-top Meters:High-throughput photometric analyzers with automated sample handling serve reference laboratory quality control requirements.
- Continuous Monitoring Devices:Subcutaneous biosensor implants with real-time creatinine trending remain in investigational stages with FDA breakthrough device designation pathways.
Portable meters anchor the volume base while handheld devices gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from consumable-driven home care economics.
- Hospitals:Integrated delivery networks negotiate meter placement through group purchasing organizations while locking in multi-year reagent contracts. The United States health system merger wave concentrates purchasing leverage among ten dominant IDNs spanning California, New York, and Illinois.
- Home Care:Medicare Advantage chronic kidney disease management programs reimburse remote patient monitoring with cellular-enabled meters. CMS billing code expansions for transitional care management accelerate adoption among Florida and Arizona retirement corridor populations.
- Clinics:Federally qualified health centers and endocrinology practices seek dual-parameter meters combining creatinine with HbA1c testing.
- Diagnostic Laboratories:Centralized reference labs maintain photometric systems for proficiency testing and external quality assessment compliance.
Hospitals retain the installed base concentration while home care climbs the fastest on reimbursement tailwinds.
Technology:
Application-driven selection separates rapid point-of-care electrochemical methods from reference-grade photometric precision.
- Electrochemical:Amperometric biosensors with immobilized creatinine deiminase on screen-printed carbon electrodes enable sub-microliter sample volumes. Dialysis chains in Germany and Japan adopt these systems for intra-treatment drug adjustments, displacing legacy enzymatic colorimetric workflows.
- Biosensor:Next-generation affinity-based sensors with reduced interference from bilirubin and hemoglobin target intensive care unit deployment. Academic medical centers in Massachusetts and California pilot these platforms for acute kidney injury early warning systems.
- Colorimetric:Enzymatic dry chemistry strips with room-temperature stability serve pharmacy retail distribution in rural markets.
- Photometric:Jaffe and enzymatic endpoint methods retain dominance in high-throughput laboratory analyzers.
Electrochemical platforms command the volume base while biosensor configurations expand most quickly on precision advantages.
Distribution Channel:
Customer type concentration favors direct sales for institutional contracts versus online retail for consumer-accessible segments.
- Direct Sales:Manufacturer field organizations negotiate enterprise agreements with integrated delivery networks and dialysis chains. Siemens Healthineers and Abbott maintain dedicated nephrology sales teams covering the United States, Germany, and Japan.
- Medical Distributors:Cardinal Health and McKesson stock CLIA-waived meters for same-day delivery to clinic customers. Their logistics networks reach federally qualified health centers in rural Montana and Mississippi.
- Online Retail:Amazon Business and specialized durable medical equipment portals serve cash-pay home care patients outside traditional reimbursement pathways.
- Others:Group purchasing organization contracts and pharmacy wholesale arrangements capture residual volume.
Direct sales anchor the revenue base while online retail gains share fastest on consumer-directed purchasing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of creatinine meters concentrates among German precision instrumentation clusters, Japanese biosensor specialists, and United States point-of-care device producers. This geographic distribution shapes regulatory compliance requirements and procurement patterns across major demand centers.
United States
Medicare Advantage chronic kidney disease management programs drive meter adoption across Florida and Arizona retirement corridors. FDA 510(k) clearance pathways for moderate-complexity devices enable hospital point-of-care deployment without laboratory technician oversight. Integrated delivery networks in California, New York, and Illinois negotiate meter placement through group purchasing organizations while securing multi-year reagent contracts.
Germany
Dialysis chains adopt electrochemical systems for intra-treatment drug adjustments, displacing legacy enzymatic workflows. EU Medical Device Regulation intensifies post-market surveillance obligations for Class IIa diagnostic devices, requiring clinical evidence registries. The Baden-Württemberg medical technology cluster hosts precision instrumentation manufacturers serving both European and export markets.
Japan
Aging demographics and diabetes prevalence sustain instrument replacement cycles in nephrology departments. PMDA quality system regulations create parallel compliance architectures that manufacturers navigate for multi-region commercialization. The Kansai region around Osaka anchors biosensor R&D activity for amperometric detection platforms.
China
Domestic production of diagnostic devices accelerates under national healthcare infrastructure investment programs. NMPA medical device registration requirements shape product development priorities for manufacturers targeting hospital procurement tenders. The Yangtze River Delta medical device manufacturing base supplies both domestic demand and Southeast Asian export markets.
United Kingdom
NHS England integrated care systems bundle creatinine screening into chronic disease management pathways. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards while establishing independent conformity assessment procedures. The Oxford-Cambridge life sciences corridor hosts point-of-care diagnostic developers targeting European market entry.
Creatinine Meter Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized diagnostic manufacturers. The vendor base splits between hospital-installed base incumbents sustaining recurring consumable revenue and emerging point-of-care specialists. Three archetypes dominate: electrochemical biosensor technology leaders, integrated laboratory workflow automation providers, and handheld connectivity-focused device makers. Competitive moves center on multi-year reagent supply contract lock-ins and middleware development for EHR platform integration.
Among United States-based diversified health technology corporations, Abbott and Nova Biomedical occupy positions across the point-of-care and hospital-installed base segments. Siemens Healthineers, as a German medical technology GmbH, exemplifies the integrated laboratory workflow automation archetype. These three anchors represent distinct strategic positioning vectors: handheld electrochemical architectures, recurring consumable revenue models, and automated high-throughput systems respectively.
| Leading Market Players |
|---|
| Nova Biomedical |
| Abbott |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Randox Laboratories |
| DH Life Sciences |
| MedTest Holdings |
| DiaSys Diagnostic Systems |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Multi-year reagent strip contracts lock in supply access and price visibility for integrated delivery networks negotiating meter placement at nominal cost across the United States, Germany, and Japan. This contracting pattern concentrates purchasing leverage among group purchasing organizations while securing recurring revenue streams for manufacturers navigating FDA 510(k) and EU MDR compliance costs.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across hospital, clinic, and home care segments. Three-tier pricing structure across premium reference-grade, standard point-of-care, and economy pharmacy-retail levels separates CLIA-waived handheld devices from bench-top laboratory analyzers. Pricing pressure stems from health system mergers concentrating volume-based contracting power among ten dominant integrated delivery networks. Federally qualified health centers in rural markets exhibit highest price sensitivity, while academic medical centers prioritize precision specifications over unit cost.
Supply Chain Analysis
Electrode inventory cycles run 90-120 days for iridium and ruthenium catalysts sourced from South African and Russian suppliers. Manufacturing concentrates in Germany's Baden-Württemberg precision instrumentation cluster, Japan's Kansai biosensor corridor, and the United States point-of-care device base. Screen-printed carbon electrodes and enzymatic dry chemistry strips draw from specialty chemical suppliers in China and Switzerland. Single-source vulnerability for platinum-group metals exposes producers to commodity price volatility. Distribution runs through Cardinal Health and McKesson logistics networks reaching clinic customers in rural Montana and Mississippi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film electrode fabrication expertise sits in critically short supply, constraining R&D throughput at mid-tier manufacturers and amplifying acquisition premiums for specialized engineering teams. This capability gap shapes competitive positioning across electrochemical biosensor development.
For Market Incumbents: Shield consumable revenue streams by locking in multi-year reagent contracts with dialysis chains and integrated delivery networks before emerging connectivity-focused entrants capture Medicare Advantage remote monitoring contracts. Deepen backward integration into enzyme stabilizer formulations to reduce patent thicket exposure. Prioritize middleware development for HL7 v2.x hospital information system integration to defend installed base positions against wireless meter data stream competitors. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for continuous monitoring biosensor implants targeting acute kidney injury early warning systems in academic medical centers. Pharmacy clinic expansion in Texas and Florida offers the most penetrable white-space for CLIA-waived metformin prescribing protocols. Pursue direct-to-patient online retail channels outside traditional reimbursement pathways to bypass group purchasing organization concentration. For Investors and Strategic Acquirers: Capital is best deployed toward electrochemical engineering specialists with captive thin-film fabrication capabilities and existing hospital procurement relationships. Long-term viability hinges on convergence of home-use regulatory pathways with Medicare reimbursement coding decisions. Watch for FDA home-use pathway clarifications and CMS billing code expansions as inflection indicators for scalable consumer-accessible adoption.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Test Expansion | Streamlined FDA 510(k) pathways accelerate hospital point-of-care deployment without laboratory technician oversight. |
| Bluetooth-Enabled Meter Development | Cloud-based EHR platform integration captures chronic kidney disease management contracts from Medicare Advantage plans. |
| Enzymatic Dry Chemistry Strip Scale-Up | Room-temperature stability eliminates cold-chain logistics for pharmacy retail distribution in rural markets. |
| ISO 15189 Harmonization Investment | Convergence of European accreditation standards with FDA quality system regulations reduces dual-certification costs. |
| Remote Patient Monitoring Integration | Cellular-enabled meters serve Florida and Arizona retirement corridor populations under transitional care management billing. |
Methodological Framework
A standing panel of nephrology department heads, biomedical engineers, hospital purchasing committee members, and group purchasing organization contract managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR clinical evidence registries. Primary interviews with dialysis chain procurement directors and pharmacy clinic operators combined with top-down trade data triangulation.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated product type, end user, technology platform, and distribution channel dimensions with geographic regulatory cluster overlays. CAGRs were derived from instrument replacement cycle analysis, diabetes-nephrology comorbidity protocol adoption curves, and Medicare Advantage chronic kidney disease management program expansion rates.
Underlying assumptions cover CLIA-waiver pathway stability, platinum-group metal supply continuity, and Medicare reimbursement coding decisions, with deviation risk concentrated in FDA home-use regulatory clarifications and health system merger consolidation pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Band Ligators Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Pen Injectors Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
North America Ablation Devices Market