
 In-Vitro Colorectal Cancer Screening Tests Market | 2026-2036
In-Vitro Colorectal Cancer Screening Tests Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Colorectal Cancer Screening Tests Market Intelligence
Hospital procurement dominance is collapsing toward diagnostic laboratories and home care channels. Quest Diagnostics Incorporated leverages its national laboratory footprint to capture outpatient volume migration. Exact Sciences Corporation anchors the stool DNA segment through Cologuard's established payer contracts. Sysmex Corporation competes in immunochemical testing with automated analyzer platforms designed for high-throughput laboratory workflows.
In-vitro colorectal cancer screening tests detect occult blood, altered DNA markers, or protein biomarkers in stool samples using immunochemical, molecular, or biochemical methods, with sensitivity thresholds calibrated to stage-specific lesion detection. These products serve commercial and clinical purposes by enabling population-level early detection without endoscopic resource burden. Fecal immunochemical testing leads volume due to low cost and workflow simplicity, while stool DNA testing captures premium positioning through multi-marker panels with higher sensitivity for advanced adenomas. Molecular technology platforms are expanding fastest as next-generation sequencing costs decline and multi-cancer early detection portfolios converge on colorectal applications.
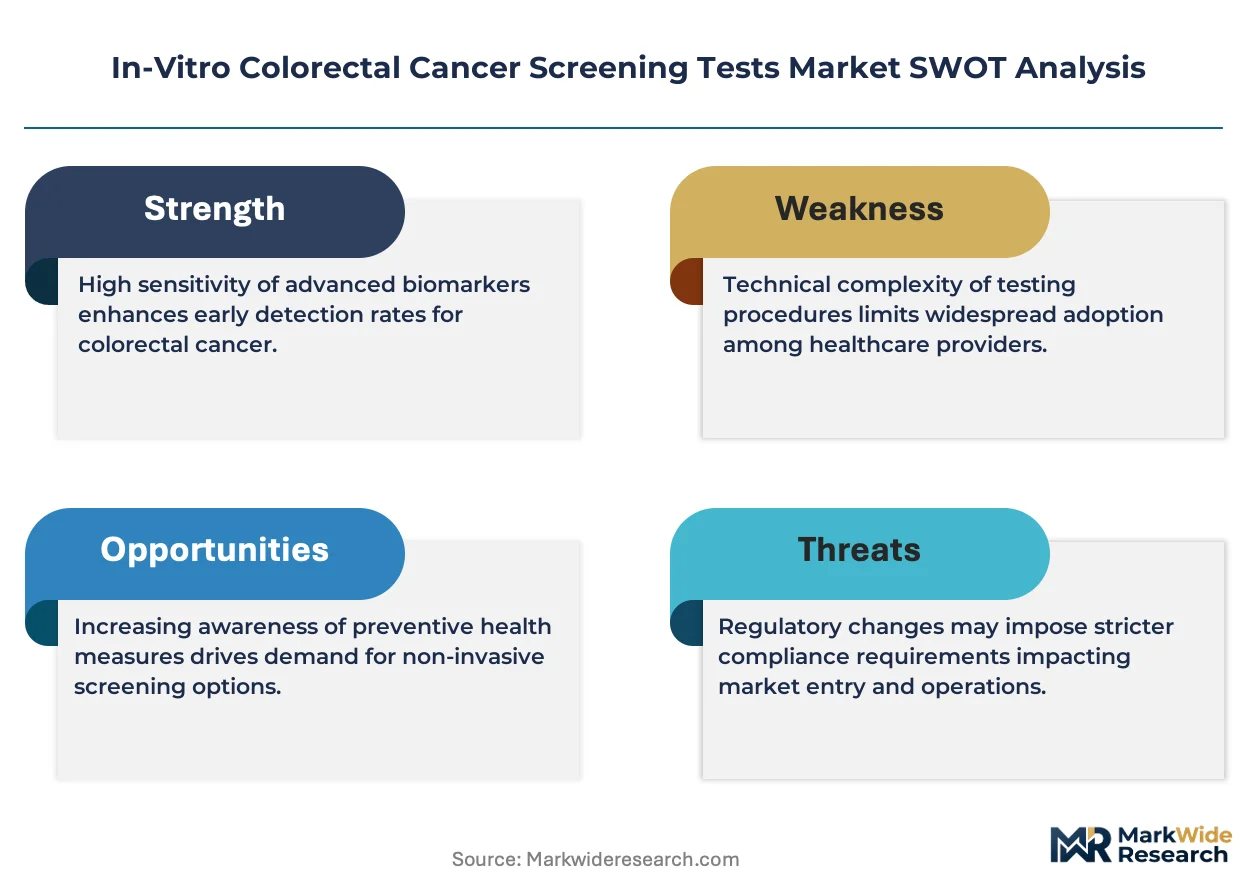
FDA premarket review governs in vitro diagnostic classification and clinical validation requirements for stool-based assays, while CMS national coverage determinations directly shape reimbursement accessibility and provider adoption incentives. The EU In Vitro Diagnostic Regulation imposes stricter performance evaluation and post-market surveillance obligations for CE-marked screening tests entering European markets. CLIA laboratory certification standards in the United States further constrain which entities can process and report screening results. Stakeholders must monitor how FDA guidance on multi-cancer detection assays reshapes competitive boundaries between single-purpose colorectal tests and broader liquid biopsy platforms.
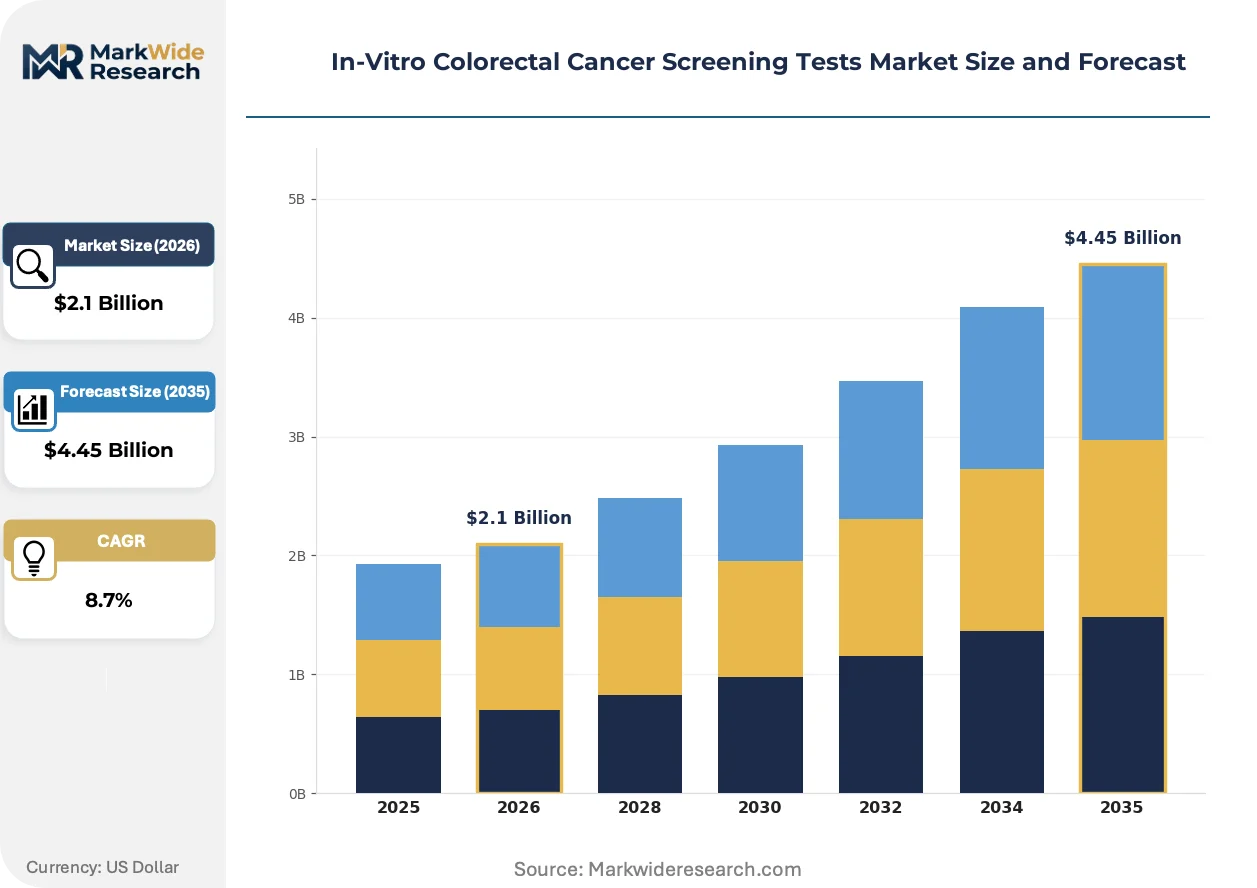
Market Dynamics
CMS national coverage determinations for stool DNA assays have restructured provider economics, tilting outpatient volume toward diagnostic laboratories and away from hospital-based endoscopy suites. This reimbursement pivot concentrates demand among high-throughput commercial labs capable of processing population-scale screening volumes.
Growth Catalysts
- Medicare coverage parity:CMS reimbursement alignment between FIT-DNA testing and colonoscopy removes cost barriers for Medicare beneficiaries, expanding addressable screening populations in the United States.
- Immunochemical automation:Laboratory analyzers with throughput exceeding 200 tests per hour reduce per-sample processing costs and enable same-day result reporting for FIT-based protocols.
- Multi-marker sensitivity thresholds:Stool DNA panels detecting KRAS mutations, NDRG4 methylation, and hemoglobin simultaneously improve advanced adenoma detection rates beyond single-analyte FIT methods.
Market Restraints
- Reimbursement compression:Commercial payers in the United States impose prior authorization requirements and coverage limitations on stool DNA testing, constraining volume growth outside Medicare populations.
- Laboratory capacity concentration:CLIA-certified high-complexity testing facilities cluster in metropolitan areas, creating geographic access gaps for rural screening populations.
- Endoscopic substitution:Direct-to-consumer colonoscopy marketing and employer wellness programs steer high-compliance patients toward optical colonoscopy despite its higher procedural cost.
Strategic Opportunities
- Home collection integration:At-home stool sample collection kits with prepaid logistics enable screening completion without clinical visits, capturing non-adherent populations in employer-sponsored health plans.
- Liquid biopsy convergence:Blood-based circulating tumor DNA assays for colorectal cancer screening create technology overlap opportunities for laboratories with existing NGS infrastructure.
- EU-MDR pathway expansion:The EU In Vitro Diagnostic Regulation's performance evaluation requirements, once satisfied, open reimbursement negotiations with national health technology assessment bodies across Germany, France, and the Netherlands.
Industry Challenges
- Bioinformatics pipeline validation:Stool DNA assays require computational algorithm validation for variant calling and methylation scoring, extending FDA premarket review timelines beyond traditional immunoassay submissions.
- Specimen stability logistics:DNA preservation buffers and temperature-controlled transport networks demand capital investment to maintain analyte integrity from collection through laboratory processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Colorectal Cancer Screening Tests Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colonoscopy, Fecal Immunochemical Test, Stool DNA Test, Flexible Sigmoidoscopy End User: Hospitals, Diagnostic Laboratories, Clinics, Home Care Technology: Immunochemical, Molecular, Genetic, Biochemical Application: Early Detection, Routine Screening, Risk Assessment, Diagnostic Confirmation |
| Companies Covered | Exact Sciences Corporation, Guardant Health Inc., Quest Diagnostics Incorporated, Siemens Healthcare GmbH, Roche Diagnostics, Abbott Laboratories, Sysmex Corporation, Eiken Chemical Co., Ltd., Epigenomics AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Colorectal Cancer Screening Tests Market Strategic Shifts & Innovations
Next-generation sequencing cost curves and artificial intelligence-enabled pathology are compressing detection thresholds while fragmenting the traditional dichotomy between stool-based screening and diagnostic colonoscopy. These forces are reshaping competitive boundaries between single-purpose assays and multi-cancer detection platforms.
Automated fecal immunochemical testing platforms with random-access architecture are displacing manual batch-processing workflows in mid-volume hospital laboratories. Diagnostic chains with centralized reference lab networks adopt these systems to capture employer contract screening volumes. This displacement compresses turnaround times from 48 hours to same-day reporting, eroding the service-level differentiation that previously sustained premium pricing for regional laboratory networks.
The EU In Vitro Diagnostic Regulation's post-market surveillance requirements impose annual safety reporting and performance trend analysis obligations on CE-marked stool screening tests. Manufacturers must maintain clinical evidence registries tracking real-world sensitivity metrics across diverse European populations. German and French notified bodies interpret these requirements most stringently, delaying market entry for assays without prospective European validation cohorts.
Employer-sponsored health plans increasingly unbundle screening program administration from medical benefit management, contracting directly with diagnostic laboratories for population health services. This channel disintermediation bypasses traditional payer networks and enables risk-based contracting tied to screening completion rates rather than per-test reimbursement. The model is most visible in self-insured Fortune 500 employers with concentrated employee populations in Texas, California, and Illinois.
In-Vitro Colorectal Cancer Screening Tests Market Segmentation
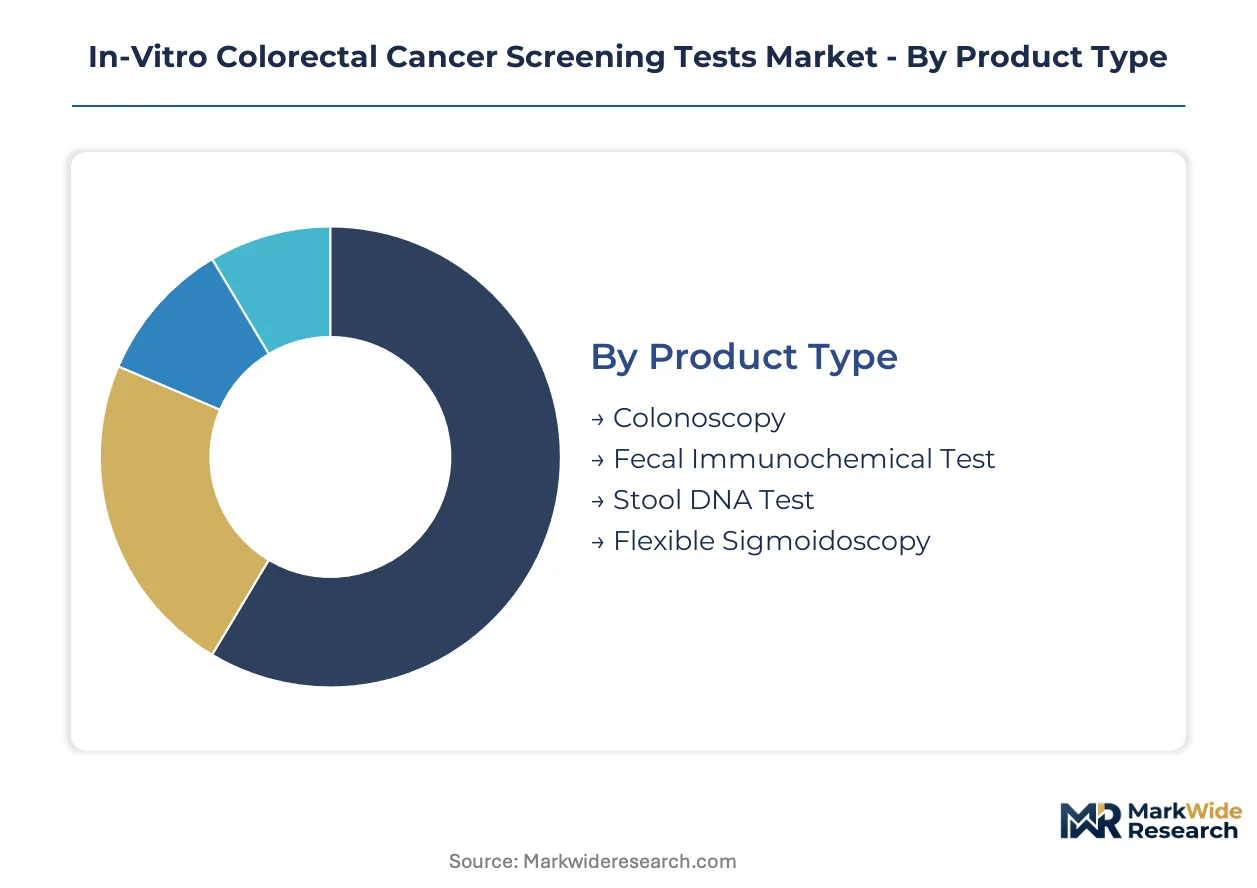
Segmentation reveals how stool-based assays compete against endoscopic procedures across divergent reimbursement environments and workflow requirements. Product type and end-user channel divisions expose where non-invasive modalities capture volume from traditional colonoscopy.
Product Type:
Margin pools concentrate in stool-based assays where Medicare reimbursement parity and automated laboratory processing create sustainable economics.
- Colonoscopy:Optical examination of the entire colon using flexible endoscopy remains the diagnostic gold standard with therapeutic capability for polypectomy. Demand concentrates in hospital outpatient departments where procedural revenue sustains endoscopy suite investments, though CMS reimbursement shifts are eroding this advantage.
- Fecal Immunochemical Test:Antibody-based detection of human hemoglobin in stool samples operates without dietary restrictions and integrates with automated laboratory analyzers. United States diagnostic laboratories process population-scale FIT volumes under Medicare annual wellness visit coverage, capturing employer contract screening programs.
- Stool DNA Test:Multi-marker molecular panels combining KRAS mutation detection with methylation analysis and hemoglobin quantification.
- Flexible Sigmoidoscopy:Limited endoscopic examination of the distal colon with lower procedural cost but incomplete anatomical coverage.
The dominant share belongs to Fecal Immunochemical Test, while Stool DNA Test is closing the gap fastest.
End User:
Volume distribution tracks the migration of screening completion from institutional settings toward decentralized collection models.
- Diagnostic Laboratories:High-throughput CLIA-certified facilities process stool-based assays with automated immunochemical analyzers and molecular testing platforms. Quest Diagnostics and LabCorp capture outpatient volume migration through national logistics networks and direct employer contracting.
- Home Care:At-home stool collection kits with prepaid shipping enable screening completion without clinical encounters. United States self-insured employers in Texas and California deploy these programs to reach non-adherent populations.
- Hospitals:Endoscopy suites and affiliated pathology laboratories performing colonoscopy and surgical specimen analysis.
- Clinics:Primary care and gastroenterology practices coordinating patient education and test ordering.
Diagnostic Laboratories command the largest volume position, with Home Care expanding most quickly.
Technology:
Platform selection determines sensitivity thresholds, capital requirements, and regulatory pathway complexity.
- Molecular:Next-generation sequencing and PCR-based detection of DNA methylation markers and somatic mutations in stool samples. Declining NGS costs enable multi-marker panels with advanced adenoma sensitivity exceeding single-analyte methods.
- Immunochemical:Antibody capture of human hemoglobin with quantitative threshold calibration for neoplastic bleeding detection.
- Genetic:Germline variant analysis for hereditary colorectal cancer risk stratification in familial syndromes.
- Biochemical:Enzymatic and chemical detection methods for occult blood and metabolic markers.
Molecular platforms lead technology investment, though Immunochemical methods retain the highest test volume.
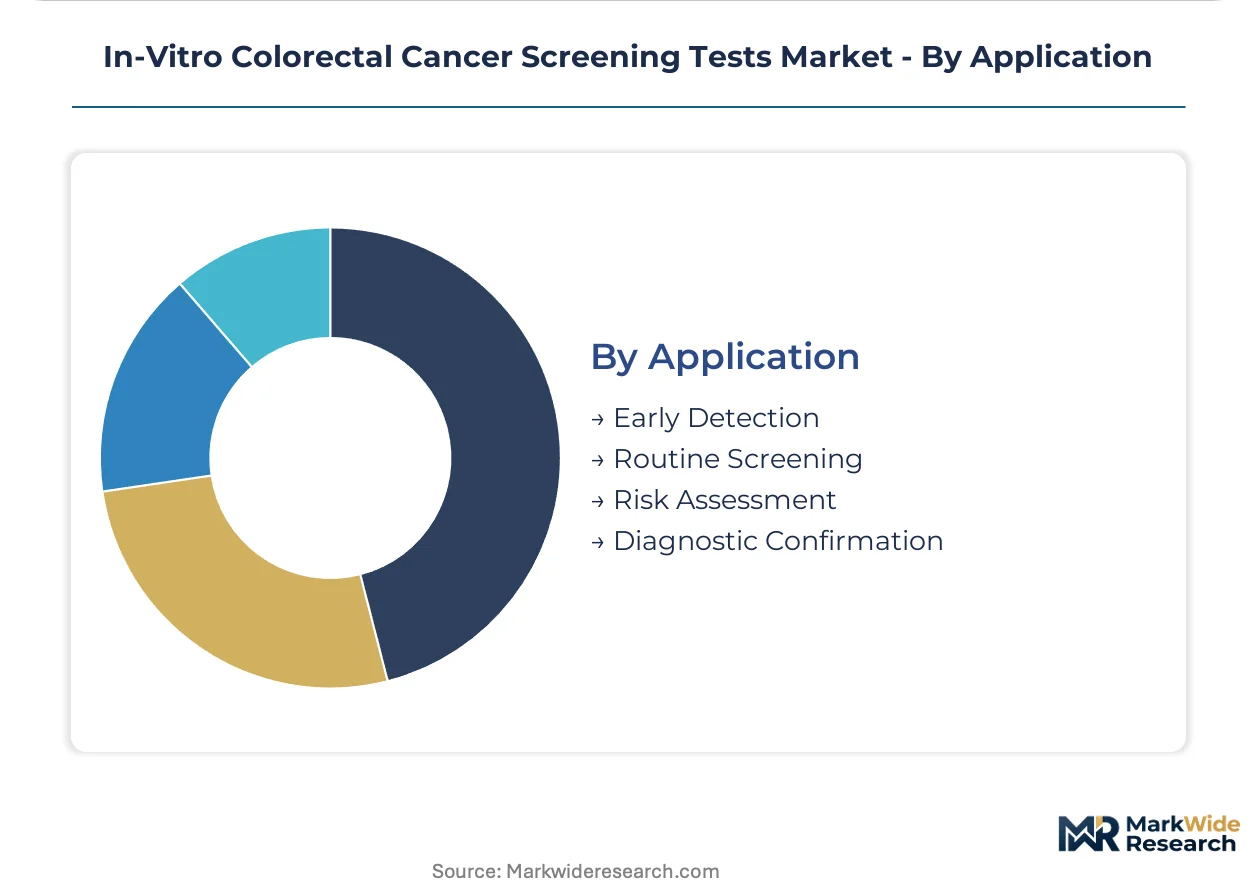
Application:
Use case differentiation shapes reimbursement coding and clinical utility claims.
- Routine Screening:Asymptomatic population testing at recommended intervals drives the majority of stool-based assay volume. United States Preventive Services Task Force guidelines and Medicare coverage determinations structure this segment.
- Early Detection:Symptomatic patient evaluation and post-treatment surveillance applications requiring higher diagnostic sensitivity.
- Diagnostic Confirmation:Triage of positive screening results toward colonoscopy referral.
- Risk Assessment:Stratification of individuals with family history or genetic predisposition.
Routine Screening generates the dominant procedure count, while Early Detection commands premium pricing per test.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution of temperature-sensitive stool DNA collection kits, while the US Interstate Highway System enables next-day specimen transport from rural collection points to CLIA-certified laboratories.
United States
Medicare reimbursement parity for FIT-DNA testing and colonoscopy removes cost barriers for beneficiaries aged 45 and older. FDA premarket review governs IVD classification and clinical validation requirements for stool-based assays. Diagnostic laboratory chains concentrate in Texas, California, and Illinois, processing population-scale screening volumes under direct employer contracts.
Germany
The national health technology assessment body evaluates stool DNA test cost-effectiveness for statutory health insurance inclusion. EU In Vitro Diagnostic Regulation imposes stricter performance evaluation and post-market surveillance obligations for CE-marked screening tests. Laboratory clusters in Bavaria and North Rhine-Westphalia deploy automated immunochemical analyzers for high-throughput FIT processing.
Japan
PMDA regulatory pathways for novel screening biomarkers shape commercialization timelines for multi-marker stool assays. METI industrial policy supports domestic diagnostic manufacturing capacity expansion. Tokyo and Osaka metropolitan areas host centralized reference laboratories processing specimens from nationwide colorectal cancer screening programs.
United Kingdom
NHS England bowel cancer screening programme procurement decisions determine national FIT kit supplier selection. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines. London and Southeast England diagnostic networks pilot blood-based liquid biopsy integration with existing stool screening infrastructure.
China
NMPA medical device registration requirements for in vitro diagnostic reagents structure market entry for foreign stool DNA test manufacturers. National cancer screening program expansion in urban centers drives demand for automated FIT platforms. Yangtze River Delta laboratory clusters in Shanghai and Jiangsu province adopt high-throughput molecular testing systems.
In-Vitro Colorectal Cancer Screening Tests Market Key Industry Players
Listed leaders compete with private specialists across reimbursement contracting and laboratory service networks, creating a tiered structure where scale-driven diagnostic chains face technology-focused molecular assay developers. The competitive landscape fragments across three strategic archetypes: national laboratory networks with logistics infrastructure, specialized molecular diagnostics firms with multi-marker platforms, and diversified healthcare conglomerates with automated analyzer portfolios. M&A activity concentrates on laboratory network consolidation and technology licensing partnerships.
Among US-based molecular diagnostics specialists, Exact Sciences Corporation and Guardant Health Inc. exemplify the technology-driven archetype, while Quest Diagnostics Incorporated occupies a position representing the scale-driven laboratory network tier. Sysmex Corporation anchors the automated immunochemical testing segment with analyzer platforms designed for high-throughput workflows.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| Guardant Health Inc. |
| Quest Diagnostics Incorporated |
| Siemens Healthcare GmbH |
| Roche Diagnostics |
| Abbott Laboratories |
| Sysmex Corporation |
| Eiken Chemical Co., Ltd. |
| Epigenomics AG |
| Others |
Cost & Logistics Intelligence
Seventy-two-hour specimen integrity windows from collection to laboratory processing constrain inventory positioning and concentrate pricing power among CLIA-certified facilities with automated cold-chain logistics. This lead-time compression rewards diagnostic laboratory networks with national scale while squeezing margins for regional players lacking temperature-controlled distribution infrastructure.
Pricing Analysis
Volume-discount tiering structures separate national laboratory contracts from regional hospital agreements and direct-to-consumer retail channels. Three-tier pricing stratification across Medicare-reimbursed, commercial payer-negotiated, and cash-pay economy levels reflects CLIA certification status and automated throughput capacity. Cost compression in the cash-pay tier intensifies as employer wellness programs consolidate purchasing through preferred laboratory networks. Medicare populations exhibit lowest price sensitivity due to coverage parity, while uninsured and high-deductible plan participants drive economy-tier demand.
Supply Chain Analysis
Inventory positioning centers on seven-day buffer stocks at centralized reference laboratories to accommodate seasonal screening campaign surges. Manufacturing concentrates in the United States, Germany, and Japan for automated immunochemical analyzers, while stool DNA collection kit production clusters in the United States and China. Raw material dependencies span DNA preservation buffers, monoclonal antibody reagents, and specialized transport media. Single-source vulnerability in NGS sequencing chip supply creates concentration risk for molecular assay manufacturers. Distribution runs through diagnostic laboratory logistics networks, direct-to-patient mail fulfillment, and hospital materials management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as multi-cancer detection portfolios converge on colorectal applications, creating interoperability demands between stool-based assays and liquid biopsy infrastructure. This ecosystem shift rewards laboratories with existing NGS capacity and punishes single-modality players.
For Market Incumbents: Consolidate reference laboratory networks in Texas, California, and Illinois to capture employer direct-contracting volume migration. Acquire CLIA-certified facilities in underserved metropolitan corridors to defend against home-collection kit disintermediation. Strengthen cold-chain logistics infrastructure to maintain specimen integrity advantages over emerging blood-based screening substitutes. For New Entrants and Emerging Players: Rural access gaps in CLIA-certified processing capacity offer immediate service-layer entry points where Quest Diagnostics and LabCorp under-invest. Target self-insured employers with concentrated employee populations in secondary metropolitan areas for direct laboratory service contracts. Pursue EU-MDR certification early to unlock German and French statutory health insurance reimbursement negotiations ahead of liquid biopsy platform maturation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates with underperforming diagnostic divisions lacking molecular assay development capabilities. Long-term viability hinges on multi-cancer portfolio integration rather than single-purpose colorectal test dependence. Watch FDA guidance on blood-based screening assay validation timelines as the critical inflection signal for technology obsolescence risk in stool-only platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cancer Portfolio Expansion | NGS infrastructure investments by Exact Sciences and Guardant Health converge stool DNA with liquid biopsy development pipelines. |
| CLIA Laboratory Network Consolidation | Quest Diagnostics acquires regional reference facilities to capture employer direct-contracting volume outside traditional payer networks. |
| EU-MDR Performance Evaluation Pathway | Epigenomics AG and Sysmex Corporation pursue CE marking with prospective European validation cohorts for German statutory insurance inclusion. |
| Home Collection Kit Logistics Integration | Prepaid specimen transport networks with temperature-controlled infrastructure reduce rural access gaps and capture non-adherent screening populations. |
| Medicare Reimbursement Strategy | CMS national coverage determination alignment between FIT-DNA testing and colonoscopy removes cost barriers for beneficiary populations aged 45 and older. |
Research Approach
Cross-validation between primary interviews with diagnostic laboratory executives, CLIA facility directors, hospital procurement managers, and payer contracting specialists anchors the qualitative findings. Secondary validation draws from FDA premarket notification databases, CMS national coverage determination records, EU MDR notified body guidance documents, and clinical validation study publications. Bottom-up test volume modeling triangulates against top-down market size estimates derived from Medicare claims data and employer-sponsored health plan screening program disclosures.
Sensitivity analysis examines reimbursement rate variability, screening compliance scenario adjustments, and technology substitution timelines across the projection horizon. Segmentation dimensions include product type, end-user channel, technology platform, and application use case, with regional regulatory clusters modeled separately for United States, German, Japanese, and Chinese market development stages. CAGR derivation incorporates test volume growth curves, pricing trajectory assumptions, and laboratory capacity expansion schedules without year-specific point estimates.
Underlying assumptions cover Medicare reimbursement stability, EU MDR implementation consistency, and NGS cost decline continuity, with deviation risk concentrated in FDA multi-cancer detection guidance timing and commercial payer prior authorization tightening. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Global Cardiac Marker Testing Market