
 Global Breast Cancer Screening Test Market | 2026-2036
Global Breast Cancer Screening Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Cancer Screening Test Market Foresight
Multi-source procurement of imaging hardware and molecular diagnostics is restructuring supply relationships across the breast cancer screening ecosystem. Hologic Inc. anchors its position through in-house manufacturing of 3D mammography systems. Siemens Healthineers competes by extending its service footprint into predictive maintenance and workflow optimization software.
Breast cancer screening tests encompass imaging modalities and molecular assays designed for asymptomatic detection of malignant tissue, with mammography systems typically operating at 25-30 kVp tube voltage to optimize soft-tissue contrast resolution. The primary commercial purpose centers on early-stage tumor identification to enable less invasive treatment protocols. Mammography and digital tomosynthesis occupy the largest installed base among test types, while automated detection technology captures expanding margin pools as radiologist workloads intensify. Home care remains nascent but represents the fastest-growing end-user channel as capillary blood collection and patient-administered sampling kits mature.
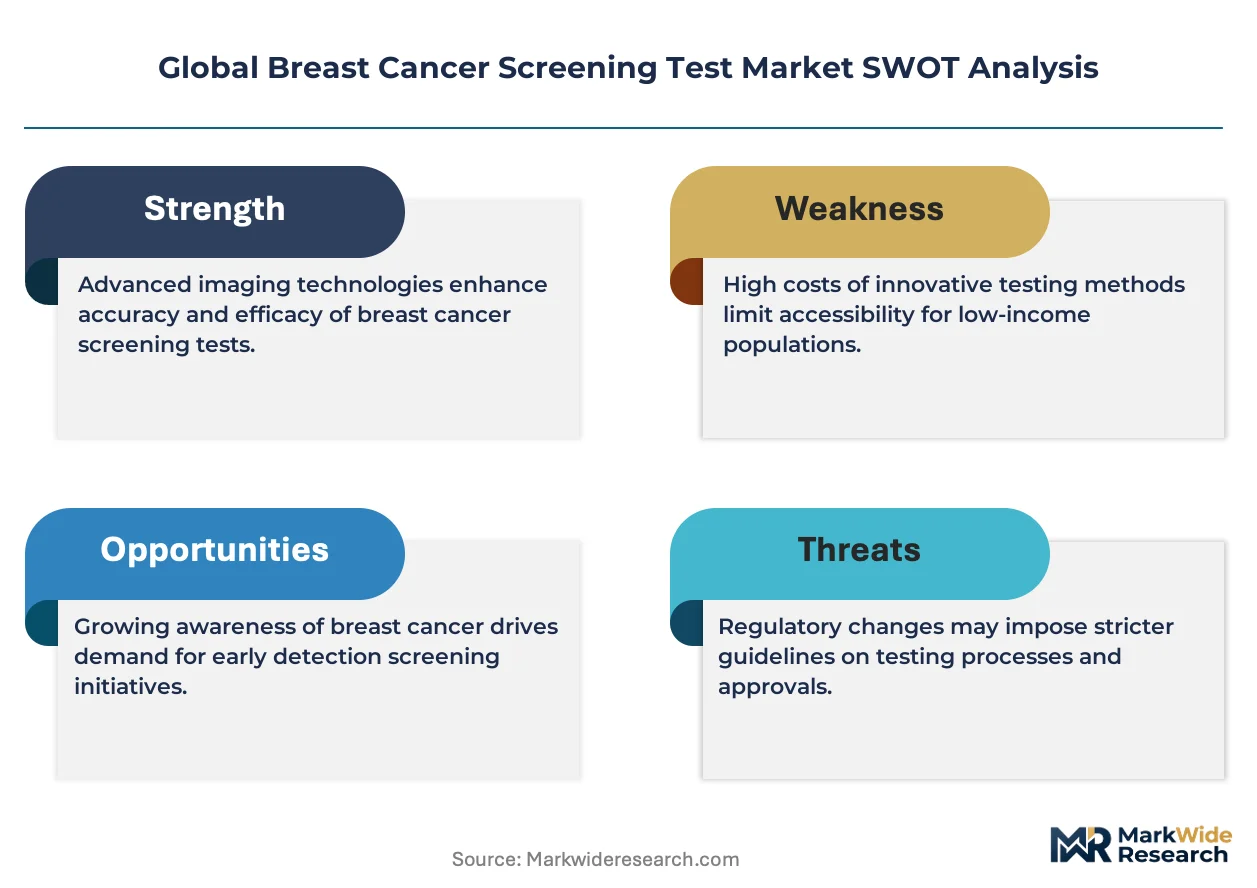
FDA premarket approval requirements and the EU Medical Device Regulation shape product development timelines and market access costs for screening device manufacturers. ISO 13485 quality management standards and national breast screening program specifications in Germany, Japan, and the United States dictate performance benchmarks that vendors must satisfy for procurement eligibility. Stakeholders must monitor reimbursement policy shifts for AI-augmented reads and liquid biopsy screening as these technologies challenge traditional fee-for-service structures.
Market Dynamics
AI-augmented mammography readouts are compressing radiologist throughput constraints while FDA 510(k) clearance pathways accelerate software deployment into hospital networks across Germany, Japan, and the United States.
Growth Catalysts
- FDA AI Clearance Pathways:Streamlined 510(k) review for computer-aided detection software reduces time-to-market for algorithm developers serving US hospital networks.
- German National Screening Program:Population-based mammography invitations for women aged 50-69 drive replacement demand for digital breast tomosynthesis systems in statutory health insurance clinics.
- Capillary Blood Collection Kits:Patient-administered liquid biopsy sampling enables decentralized screening expansion beyond radiology-dependent workflows into home care channels.
Market Restraints
- EU MDR Compliance Burden:Reclassification of screening software under stricter conformity assessment procedures extends certification timelines and elevates notified body costs for European market access.
- Helium Supply Concentration:Magnetic resonance imaging systems for supplemental screening depend on constrained helium reserves concentrated in Qatar and the United States, exposing molecular imaging modalities to input price volatility.
- Radiologist Workforce Density:Japan maintains 12 radiologists per 100,000 population versus 100-plus in the United States, creating diagnostic bottlenecks that limit effective utilization of installed screening capacity regardless of hardware availability.
Strategic Opportunities
- India Tier-2 City Penetration:Mobile mammography units and tele-radiology partnerships address screening gaps in Chennai, Pune, and Ahmedabad where fixed imaging infrastructure remains underdeveloped.
- IRDAI Preventive Health Coverage:Indian insurance regulator mandates inclusion of cancer screening in standard health policies, creating reimbursement tailwinds for molecular diagnostic providers entering the market.
- AI-Digital Pathology Convergence:Integration of mammography algorithms with whole-slide imaging systems enables single-vendor contracts spanning detection through histological confirmation.
Industry Challenges
- Radiologist-AI Collaboration Training:Clinical workflow redesign requires re-skilling programs for interpreting physicians to validate algorithm flagging without throughput degradation.
- Legacy PACS Integration:Hospital information systems built on DICOM 3.0 standards from the 1990s require middleware development to accommodate cloud-native AI screening platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Cancer Screening Test Market |
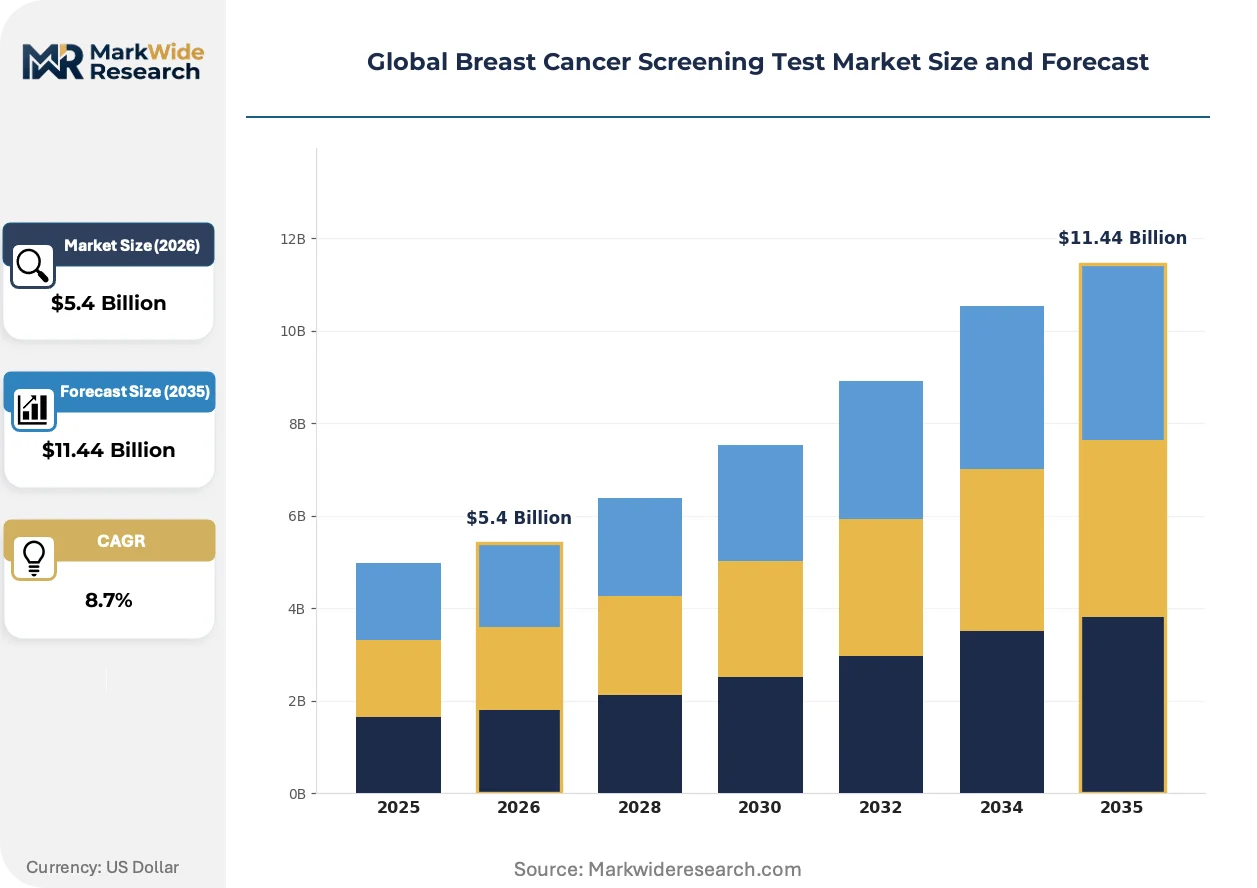
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Mammography, Ultrasound, MRI, Digital Tomosynthesis Technology: 2D Imaging, 3D Imaging, Automated Detection, Contrast-Enhanced End User: Hospitals, Diagnostic Centers, Research Institutions, Home Care Service Type: Screening, Diagnostic Surveillance, Follow-Up Care, Counseling |
| Companies Covered | Koninklijke Philips N.V., Exact Sciences Corporation, Hologic Inc., QIAGEN, Thermo Fisher Scientific Inc., GE HealthCare Technologies Inc., FUJIFILM Holdings Corporation, Myriad Genetics, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Cancer Screening Test Market Shifts & Advancements
Deep learning architectures trained on multi-institutional imaging datasets are redefining detection sensitivity benchmarks while regulatory frameworks scramble to validate algorithmic performance across diverse patient populations.
Contrast-enhanced spectral mammography is expanding into dense breast tissue evaluation where conventional 2D imaging suffers reduced sensitivity. Academic medical centers in the United States and university hospitals in Germany are adopting dual-energy acquisition protocols at accelerating replacement cycles. The technology is expanding into supplemental screening indications previously reserved for MRI, compressing the addressable market for high-field magnetic systems in intermediate-risk patient stratification.
Japan's PMDA introduced conditional early approval pathways for AI diagnostic software in 2020, creating regulatory arbitrage opportunities for developers seeking market entry ahead of full clinical validation completion. The framework permits limited commercial deployment with post-market surveillance obligations. Domestic health technology assessment bodies in Osaka and Tokyo are now demanding real-world performance data that exceeds pre-market trial metrics, forcing algorithm developers to maintain continuous learning infrastructure.
Hospital procurement committees are unbundling hardware acquisition from service contracts and AI software licensing, fragmenting vendor relationships that previously favored integrated system suppliers. German hospital networks now run competitive tenders separating 3D mammography equipment from predictive maintenance agreements and algorithm subscriptions. This pattern is most visible in North Rhine-Westphalia and Bavaria where purchasing cooperatives aggregate demand across multiple statutory insurance-affiliated clinics.
Global Breast Cancer Screening Test Market Segmentation
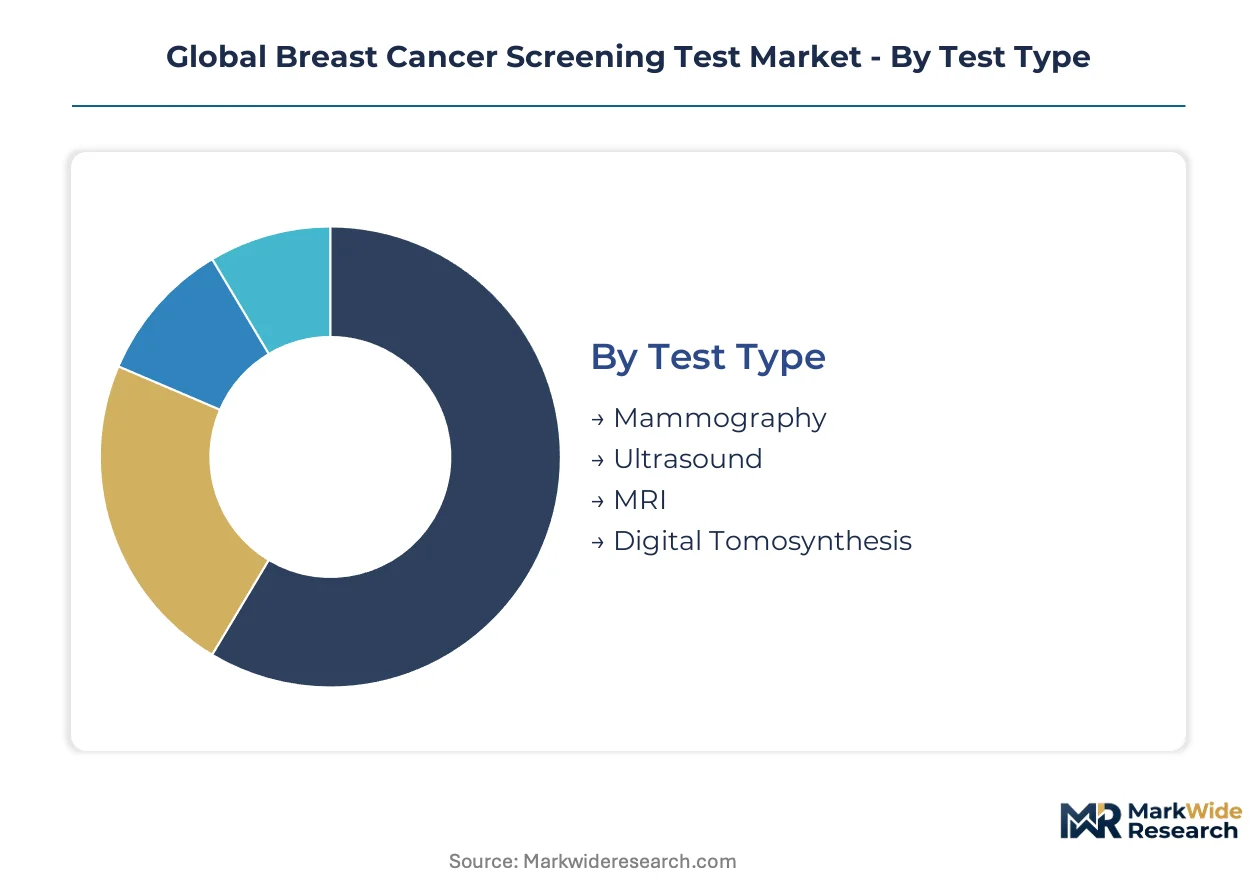
Test modality selection in breast cancer screening depends on tissue density, risk stratification, and reimbursement pathways. Segmentation reveals how hardware specifications, software capabilities, and service delivery models partition procurement budgets across healthcare systems.
Test Type:
FDA 510(k) clearance applies to mammography and digital tomosynthesis systems, while MRI breast coils require premarket approval with stricter clinical evidence standards. EU MDR conformity assessment timelines vary significantly across these modalities.
- Mammography:Conventional 2D X-ray systems operating at 25-30 kVp dominate installed bases in Germany, Japan, and the United States. Hospital networks in Bavaria and Texas are replacing analog units with digital detectors to meet national screening program specifications.
- Digital Tomosynthesis:Multi-angle acquisition reconstructs three-dimensional breast architecture, improving lesion localization in dense tissue. Statutory health insurance clinics in North Rhine-Westphalia are driving replacement demand as the technology captures margin from supplemental MRI indications.
- Ultrasound:Handheld probes enable point-of-care adjunctive screening without ionizing radiation. Demand concentrates in mobile screening units serving Chennai and Pune where fixed mammography infrastructure remains limited.
- MRI:High-field magnetic systems with dedicated breast coils serve high-risk patient surveillance. Helium supply constraints from Qatar and the United States expose this segment to input price volatility.
Leading the category by volume: Mammography. Growing fastest: Digital Tomosynthesis.
Technology:
Cost tiers separate premium acquisition protocols from standard screening workflows, with automated detection software commanding subscription pricing independent of hardware depreciation schedules.
- 3D Imaging:Tomosynthesis and synthetic 2D reconstruction reduce callback rates in dense breast populations. Academic medical centers in the United States are adopting dual-energy protocols at accelerating replacement cycles.
- Automated Detection:Deep learning algorithms flag suspicious regions for radiologist validation. Japan's PMDA conditional approval pathway permits limited commercial deployment with post-market surveillance obligations in Osaka and Tokyo.
- 2D Imaging:Legacy digital mammography remains prevalent in cost-constrained procurement environments. Budget limitations in tier-2 Indian cities sustain demand for refurbished detector installations.
- Contrast-Enhanced:Iodinated contrast protocols expand sensitivity for invasive cancer detection in heterogeneously dense tissue. University hospitals in Germany are validating spectral acquisition techniques against MRI benchmarks.
Highest procurement spend: 3D Imaging. Expanding most quickly: Automated Detection.
End User:
Customer type determines service intensity, with hospitals requiring 24/7 technical support contracts and home care channels demanding patient-administered sampling logistics.
- Hospitals:Integrated delivery networks in the United States operate centralized breast imaging centers with dedicated breast surgeons. PACS integration challenges with 1990s-era DICOM 3.0 systems complicate AI software deployment.
- Diagnostic Centers:Independent imaging facilities compete on throughput and radiologist availability. Workforce density constraints in Japan limit effective utilization regardless of hardware installation.
- Home Care:Capillary blood collection kits for liquid biopsy screening enable decentralized sample acquisition. IRDAI preventive health coverage mandates in India create reimbursement tailwinds for molecular diagnostic providers.
- Research Institutions:Academic sites conduct algorithm training and validation studies using multi-institutional imaging datasets. Real-world performance requirements from Japanese health technology assessment bodies exceed pre-market trial metrics.
Dominant procurement volume: Hospitals. Steepest expansion trajectory: Home Care.
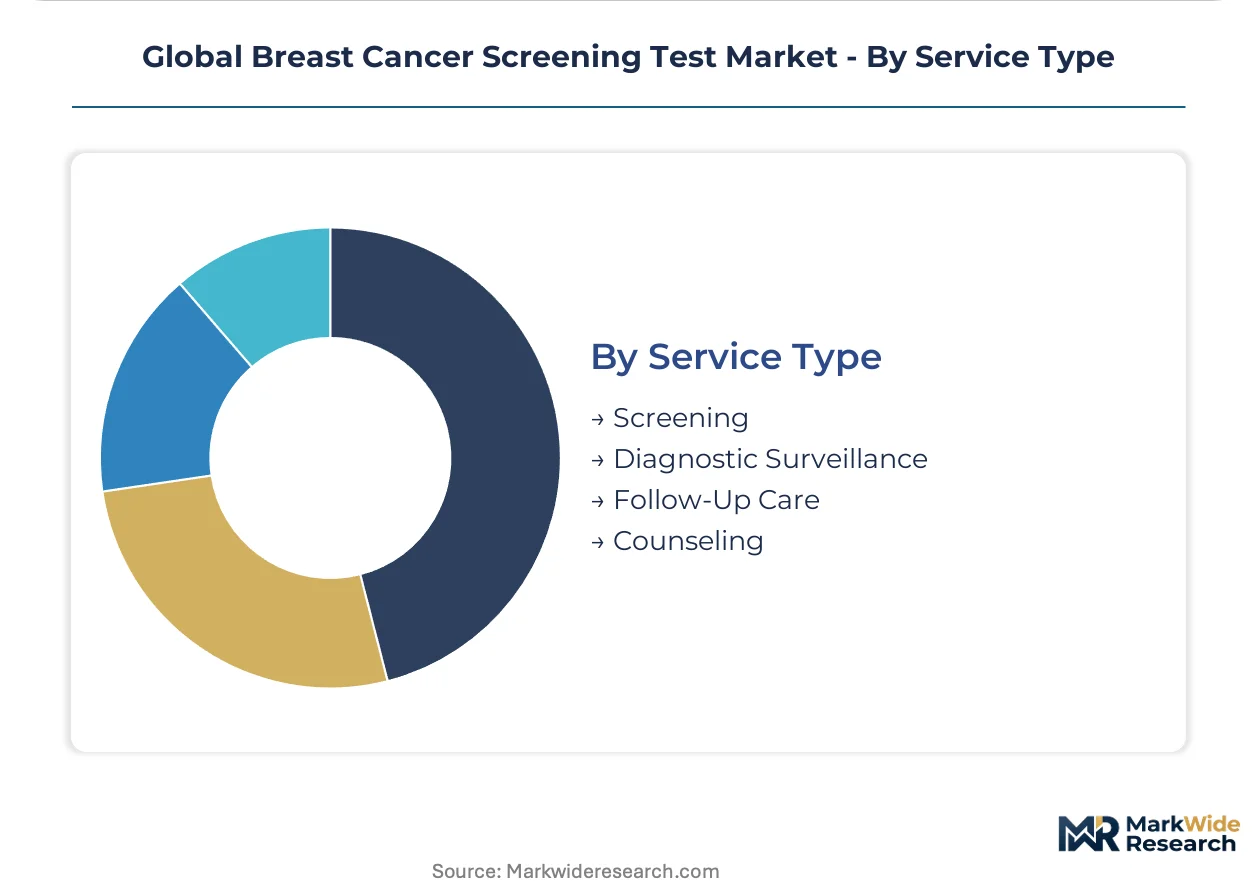
Service Type:
Application intensity varies by clinical purpose, with screening programs emphasizing throughput optimization and diagnostic surveillance requiring extended radiologist interpretation time.
- Screening:Population-based invitation systems for asymptomatic women aged 50-69 drive volume in German statutory health insurance clinics. FDA-cleared AI software compresses radiologist throughput constraints in high-volume US hospital networks.
- Diagnostic Surveillance:Short-interval imaging for BI-RADS 3 lesions and high-risk genetic carriers demands specialized breast radiologist expertise. Japanese screening programs face bottlenecks from 12 radiologists per 100,000 population versus 100-plus in the United States.
- Follow-Up Care:Imaging coordination with surgical and medical oncology services requires integrated workflow platforms. German hospital networks are unbundling hardware acquisition from service contracts and AI software licensing.
- Counseling:Genetic risk assessment and screening regimen personalization support shared decision-making. Mobile mammography units in Ahmedabad address counseling gaps where fixed infrastructure remains underdeveloped.
Highest service volume: Screening. Gaining share fastest: Diagnostic Surveillance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium reserves concentrated in Qatar and the United States anchor the geographic distribution of high-field MRI systems used in supplemental breast screening, while manufacturing clusters for digital mammography hardware concentrate in Germany, Japan, and the United States.
United States
FDA 510(k) clearance pathways for AI-assisted mammography software accelerate deployment into hospital networks across Texas and California. The national screening infrastructure operates through decentralized programs managed by integrated delivery networks. Academic medical centers in Boston and the Research Triangle validate contrast-enhanced spectral protocols against MRI benchmarks.
Germany
Statutory health insurance clinics in Bavaria and North Rhine-Westphalia drive replacement demand for digital breast tomosynthesis systems under the national mammography program for women aged 50-69. EU MDR conformity assessment procedures extend certification timelines for screening software vendors. University hospitals in Heidelberg and Munich validate dual-energy acquisition techniques.
Japan
PMDA conditional early approval pathways for AI diagnostic software permit limited commercial deployment with post-market surveillance obligations in Osaka and Tokyo. Health technology assessment bodies demand real-world performance data exceeding pre-market trial metrics. Radiologist workforce density of 12 per 100,000 population creates diagnostic bottlenecks in Kansai screening centers.
India
IRDAI mandates inclusion of cancer screening in standard health policies, creating reimbursement tailwinds for molecular diagnostic providers entering Maharashtra and Gujarat. Mobile mammography units address infrastructure gaps in Chennai, Pune, and Ahmedabad. Capillary blood collection kits enable decentralized screening expansion beyond radiology-dependent workflows.
Global Breast Cancer Screening Test Market Competitive Landscape
Global majors compete with regional champions across imaging hardware and molecular diagnostics, producing a tiered structure where integrated system suppliers face unbundling pressure from procurement committees separating equipment acquisition from service contracts and AI software licensing. Three archetypes dominate: full-stack imaging platform vendors, molecular assay specialists, and algorithm-focused software developers. Competitive moves center on predictive maintenance service extensions and workflow optimization partnerships.
Among Netherlands-based diversified health technology conglomerates, Koninklijke Philips N.V. occupies a position exemplifying integrated diagnostic imaging platforms, while Wisconsin-based Hologic Inc. anchors the dedicated women's health screening archetype through in-house manufacturing positions. German engineering conglomerate Siemens Healthineers represents the industrial automation-to-healthcare extension model, sitting within the premium-tier service footprint expansion segment.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Exact Sciences Corporation |
| Hologic Inc. |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| GE HealthCare Technologies Inc. |
| FUJIFILM Holdings Corporation |
| Myriad Genetics |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Hospital purchasing committees in Germany and the United States anchor procurement power through competitive tender unbundling, forcing vendors toward subscription-based AI software licensing separate from hardware depreciation schedules. This buyer concentration compresses margin pools for integrated system suppliers while elevating price transparency across predictive maintenance and algorithm performance tiers.
Pricing Analysis
Warranty and service contract bundling now separates from core equipment acquisition in Bavarian and North Rhine-Westphalian purchasing cooperatives, with predictive maintenance agreements commanding standalone subscription pricing. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification grade, and radiologist workflow integration depth. Cost compression in refurbished digital detector installations intensifies because budget-constrained tier-2 Indian clinics prioritize capital expenditure minimization over performance specifications. Diagnostic centers exhibit highest price sensitivity due to throughput-dependent revenue models, while academic medical centers demonstrate lowest sensitivity given research funding insulation.
Supply Chain Analysis
Freight cost escalation for liquid helium shipments from Qatar and the United States constrains MRI breast coil distribution economics, compressing effective margins on high-field magnetic systems. Manufacturing concentration for digital mammography detectors centers on Germany, Japan, and the United States, with flat-panel sensor fabrication drawing from specialized semiconductor foundries in Taiwan and South Korea. Gadolinium-based contrast agent supply hinges on Chinese rare earth processing capacity, exposing contrast-enhanced spectral mammography to single-source vulnerability. Distribution runs through statutory health insurance clinic networks in Germany, integrated delivery networks in the United States, and mobile screening unit operators in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Breast Cancer Screening Test Market functions as a vertical-integration race where algorithm developers pursue captive imaging hardware partnerships to secure workflow embedding, while equipment manufacturers acquire molecular assay capabilities to span detection through histological confirmation.
For Market Incumbents: Deepen predictive maintenance service footprints in German statutory health insurance clinics to defend against unbundling pressure from purchasing cooperatives. Secure exclusive AI software licensing arrangements with integrated delivery networks in Texas and California before cloud-native platforms achieve legacy PACS integration maturity. Incumbent position erodes where middleware developers solve DICOM 3.0 compatibility for algorithm-only vendors. For New Entrants and Emerging Players: Enter via capillary blood collection kit distribution partnerships with Indian molecular diagnostic providers, exploiting IRDAI preventive health coverage mandates as reimbursement tailwinds. Target home care channels in Maharashtra and Gujarat where radiologist workforce density constraints limit conventional imaging penetration. Go-to-market leverage rests on patient-administered sampling logistics rather than capital-intensive hardware installation. For Investors and Strategic Acquirers: The window for entry favors algorithm-focused software developers with conditional PMDA approval pathways and continuous learning infrastructure. Long-term viability centers on real-world performance data generation capabilities that exceed pre-market trial metrics demanded by Japanese health technology assessment bodies. Acquisition targets should demonstrate multi-institutional imaging dataset access and post-market surveillance compliance systems. Watch FDA 510(k) clearance velocity for AI-augmented mammography as inflection indicator for algorithmic pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Companion Development | FDA 510(k) clearance for computer-aided detection compresses radiologist throughput constraints in US hospital networks. |
| Hospital System Partnership | Exclusive service contracts with German purchasing cooperatives defend against procurement unbundling pressures. |
| CE Marking Pathway | EU MDR conformity assessment for screening software extends timelines but secures statutory insurance clinic eligibility. |
| Reimbursement Strategy | IRDAI preventive health coverage alignment unlocks molecular diagnostic access in Maharashtra and Gujarat markets. |
| Software Companion Development | Legacy PACS middleware integration enables cloud-native AI platform deployment into 1990s-era hospital information systems. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification completion rates, and national screening program procurement volumes anchored the trend analysis, supplemented by interviews with breast imaging radiologists, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and molecular diagnostic laboratory directors. Secondary validation drew from FDA premarket notification databases, EUDAMED device registration records, German Federal Joint Committee screening program specifications, and CMS Medicare reimbursement schedules. Bottom-up equipment installation tracking and top-down healthcare expenditure triangulation converged on segment-level demand estimates.
Segment-weighting across test modality, technology tier, end-user channel, and service application dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from replacement cycle analysis for digital breast tomosynthesis systems, algorithm adoption curves in US academic medical centers, and mobile screening unit deployment rates in Indian tier-2 cities. Forecast inputs incorporated helium supply constraint scenarios for MRI breast coils and PMDA conditional approval pathway utilization rates for AI diagnostic software.
Revisions become necessary when EU MDR notified body capacity constraints extend certification timelines beyond modeled assumptions, when helium supply disruptions from Qatar or the United States trigger MRI system price volatility, or when Japanese radiologist workforce density fails to expand in proportion to installed screening capacity. Forecasts reflect documented assumptions regarding reimbursement policy stability for AI-augmented reads and liquid biopsy screening. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market