
 Asia-Pacific Kaolin Market | 2026-2036
Asia-Pacific Kaolin Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Kaolin Market Outlook
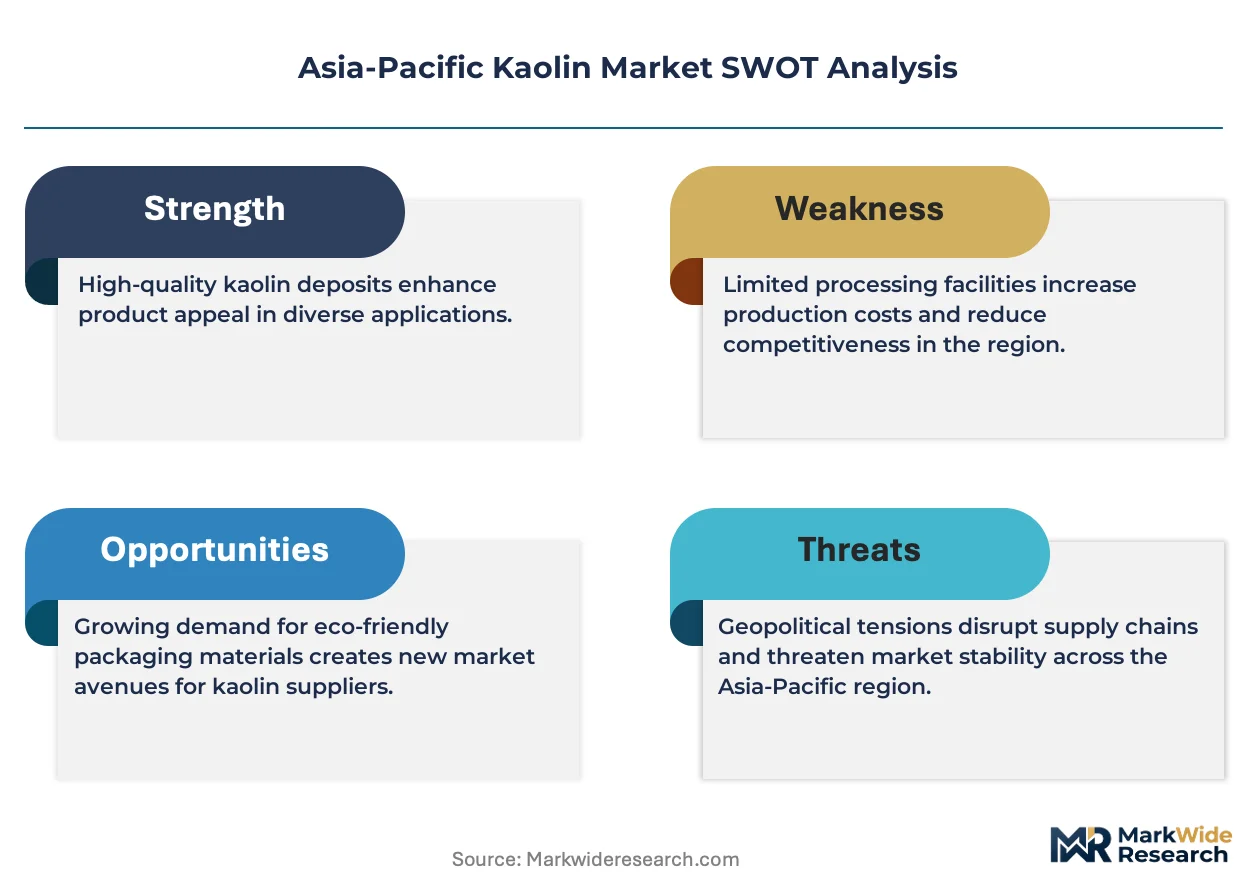
REACH compliance is repositioning export-oriented kaolin processors toward higher-purity beneficiation investments. Imerys S.A. leverages its calcination technology leadership to supply European-facing paper grades from Asian production nodes. Jiangxi Sincere Mineral Industry Co., Ltd. anchors its competitive position through captive hydrous kaolin reserves in China's largest deposit belt. 20 Microns Limited differentiates via ultra-fine grinding capabilities serving Indian plastics compounders and paint formulators.
Kaolin is a hydrated aluminum silicate clay mineral with the approximate chemical composition Al₂Si₂O₅(OH)₄, formed by weathering of feldspathic rocks and refined through wet processing, centrifugation, and thermal calcination to achieve controlled particle size distributions and brightness levels above 80 percent GE brightness. The material functions primarily as a functional filler, coating pigment, and rheology modifier across paper, ceramics, paints, plastics, and pharmaceutical applications. Calcined kaolin commands premium positioning in paper coating and titanium dioxide extension applications where opacity and ink receptivity drive specification. Hydrous kaolin maintains volume leadership in ceramics body formulations across Vietnam, Indonesia, and India's sanitaryware clusters. Ultra-fine kaolin represents the fastest-expanding quality tier as Asian automotive plastics demand surface-engineered fillers for dimensional stability.
China's GB standards for ceramic raw materials and India's BIS certification for paper-grade minerals establish dual compliance thresholds for cross-border suppliers. Japan's METI chemical substance reporting framework and South Korea's MFDS pharmaceutical excipient standards create additional segmentation pressure between industrial and food-grade kaolin streams. Stakeholders must monitor how Indonesia's emerging downstream ceramics protectionism and Australia's WA Kaolin export logistics reshape raw material flow patterns across the region.
Market Dynamics
Paper mills across China and India are retrofitting coating lines to handle higher filler loadings, compressing specification windows for brightness and particle size distribution while pulling hydrous kaolin into premium calcined territory.
Growth Catalysts
- PLI scheme for specialty minerals:India's production-linked incentive framework is accelerating domestic beneficiation investments, reducing import dependence for paper-grade and ceramics feedstocks.
- Sanitaryware cluster expansion:Vietnam's ceramics corridor from Binh Duong to Hai Phong is scaling output for ASEAN bathroom fixture demand, absorbing hydrous kaolin volumes.
- Calcination technology diffusion:Flash calcination systems are lowering energy intensity for metakaolin production, extending titanium dioxide substitution economics into mid-tier paper grades.
Market Restraints
- Natural gas price volatility:Calcination operations in Guangdong and Jiangsu provinces face margin compression from LNG import dependency, constraining capacity expansion timelines.
- Deposit depletion in Fujian:China's highest-brightness hydrous reserves are experiencing grade degradation, forcing processors to blend lower-quality feedstocks.
- Ground calcium carbonate substitution:Precipitated GCC from satellite plants at paper mills is capturing filler applications below 90 GE brightness thresholds.
Strategic Opportunities
- Indonesian downstream ceramics protectionism:Import substitution mandates for sanitaryware raw materials create captive offtake potential for Kalimantan-based kaolin projects.
- Pharmaceutical excipient certification:South Korea's MFDS standards for kaolin in antacid and topical formulations open premium pricing tiers for GMP-compliant processors.
- Surface-engineered fillers for automotive plastics:Coupling agent treatments are enabling kaolin displacement of talc in polypropylene bumper compounds across Thailand's auto parts belt.
Industry Challenges
- Beneficiation chemistry expertise:Wet processing facilities struggle to recruit flotation specialists capable of managing iron and titanium removal for 90+ brightness specifications.
- Dual certification timelines:Suppliers serving both China's GB ceramic standards and India's BIS paper grades face extended qualification cycles that delay revenue recognition.
- Logistics reconfiguration for Australian exports:WA Kaolin's port capacity constraints are forcing Southeast Asian buyers to reroute through Fremantle, lengthening supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Kaolin Market |
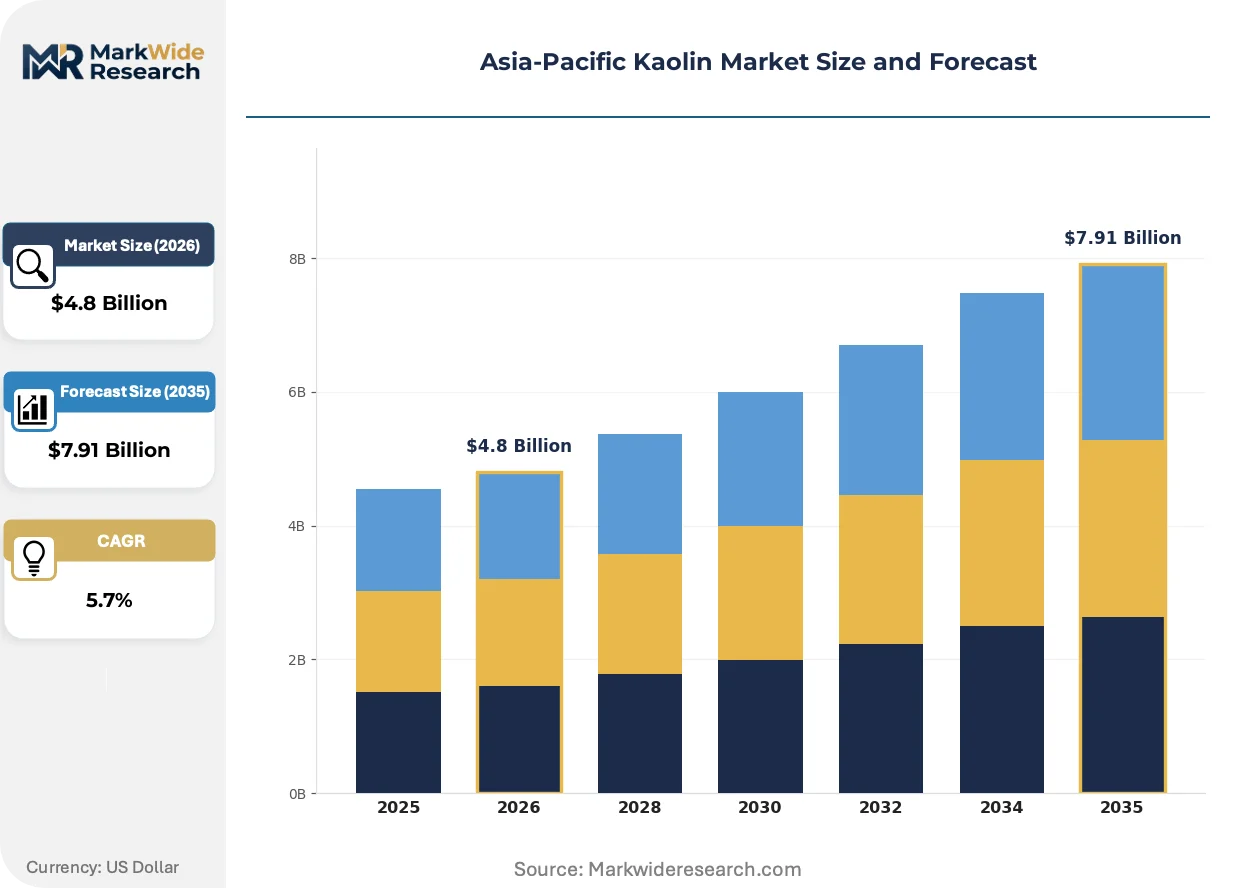
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Kaolin, Hydrous Kaolin, Ultra-fine Kaolin, Paper Grade Kaolin End Use Industry: Paper, Ceramics, Paints, Plastics Form: Powder, Granules, Slurry, Dispersions Quality Level: Industrial Grade, Food Grade, Pharmaceutical Grade, Others |
| Companies Covered | EICL Limited, 20 Microns Limited, Imerys S.A., Jiangxi Sincere Mineral Industry Co., Ltd., WA Kaolin, BASF SE, SCR-Sibelco, Uma Group of Kaolin, Ashapura Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Kaolin Market Strategic Shifts
Beneficiation technology and regulatory segmentation are fragmenting the kaolin value chain into distinct quality tiers, with calcination and surface modification capabilities becoming the primary axes of supplier differentiation.
Flash calcination systems with rapid temperature ramp control are integrating into Asian production nodes to supply European-facing paper grades. Imerys and domestic Chinese operators are deploying these units at Jiangxi and Guangdong sites to meet REACH-compliant brightness specifications. The technology is integrating calciner output directly into containerized export logistics, compressing the traditional trader-mediated supply chain.
China's GB standards for ceramic raw materials and India's BIS certification for paper-grade minerals are establishing divergent compliance thresholds that fragment supplier strategies. Processors must maintain parallel quality systems to serve both markets, raising fixed cost burdens for mid-cap participants. The ceramics segment faces the steepest adaptation curve as GB standards tighten on iron oxide content below 0.5 percent.
Automotive compounders in Thailand and Indonesia are consolidating kaolin procurement through direct mill relationships, bypassing regional distributors. Tier-1 suppliers specify surface-treated grades with silane coupling for dimensional stability in injection-molded polypropylene. This concentration is most visible in Rayong's eastern seaboard automotive cluster, where paint and plastics formulators are integrating technical service agreements into supply contracts.
Asia-Pacific Kaolin Market Segmentation
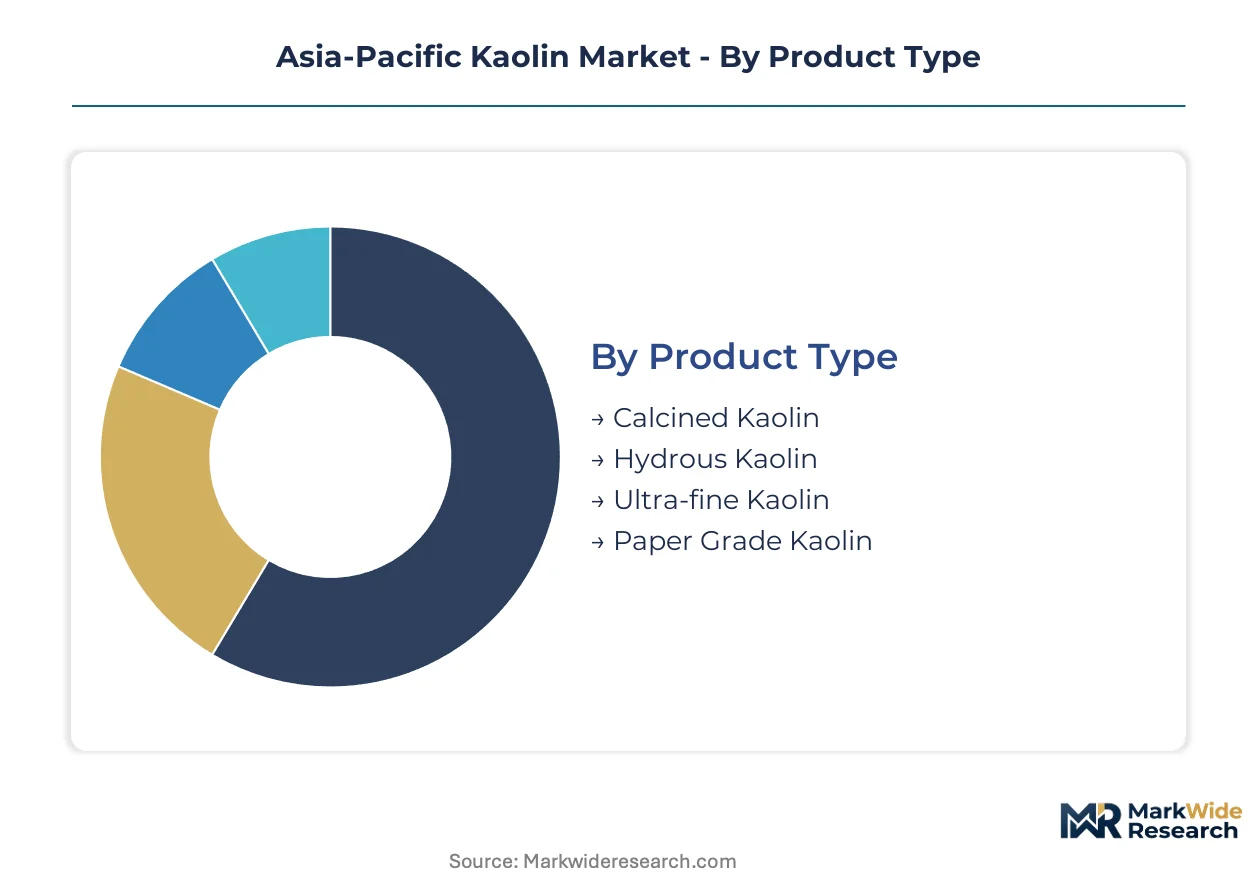
Kaolin's functional diversity across paper coating, ceramic body formulation, and polymer reinforcement creates distinct specification corridors. Each segment carries divergent certification burdens and margin profiles that reshape processor investment priorities across the Asia-Pacific region.
Product Type:
REACH compliance for European-facing exports and China's GB standards for domestic ceramics impose parallel technical validation requirements on calcination and beneficiation investments.
- Calcined Kaolin:Thermally processed at 600-1000°C to remove hydroxyl groups, achieving metakaolin structures with elevated brightness above 85 GE and controlled porosity. Paper mills in China's Shandong province are retrofitting coating lines to handle higher calcined loadings for titanium dioxide extension, compressing specification windows for particle size distribution. Leading the category by volume: Hydrous Kaolin. Growing fastest: Ultra-fine Kaolin.
- Hydrous Kaolin:Wet-processed aluminum silicate retaining crystalline water, offering lower cost and superior plasticity for ceramic body formulations. Vietnam's sanitaryware corridor from Binh Duong to Hai Phong absorbs bulk volumes for ASEAN bathroom fixture production, though deposit depletion in China's Fujian province forces processors to blend lower-quality feedstocks.
- Ultra-fine Kaolin:Sub-micron particle grades engineered for surface area optimization in automotive plastics and high-performance coatings.
- Paper Grade Kaolin:Brightness-calibrated specifications meeting ISO 3260 coating pigment standards for rotogravure and offset printing applications.
Calcination capability gaps between Jiangxi producers and European-facing exporters are narrowing through flash calcination technology diffusion.
End Use Industry:
Customer procurement patterns diverge sharply between specification-intensive paper coatings and volume-driven ceramic body applications.
- Paper:Coating pigments demand 90+ GE brightness with controlled particle size distributions for ink receptivity and opacity. India's BIS certification for paper-grade minerals and China's rising filler loading requirements are pulling hydrous grades into premium calcined territory.
- Ceramics:Sanitaryware and tableware formulations prioritize plasticity and fired whiteness over brightness metrics. Hydrous kaolin dominates Vietnam's ceramics corridor and India's Morbi cluster, with GB standards tightening iron oxide content below 0.5 percent for premium porcelain.
- Paints:Rheology modification and TiO2 extension drive demand for delaminated and calcined grades in architectural and industrial coatings.
- Plastics:Surface-engineered fillers for dimensional stability in polypropylene compounds, particularly across Thailand's Rayong automotive belt where tier-1 suppliers specify silane-coupled grades.
Paper commands premium pricing per ton. Plastics demonstrates steepest specification escalation as automotive compounders consolidate direct mill relationships.
Form:
Logistics economics and end-use processing infrastructure determine form selection across coastal versus inland demand centers.
- Powder:Standard pulverized grades for dry-compounding in ceramics and plastics, offering lowest unit cost but generating dust handling requirements.
- Granules:Agglomerated forms reducing dust emissions during pneumatic conveying, preferred by large-volume ceramic tile producers.
- Slurry:Pumpable 70% solids dispersions eliminating dust and milling steps at paper mill coating kitchens. Coastal processors in Guangdong leverage port-adjacent slurry plants for export efficiency.
- Dispersions:Stabilized colloidal suspensions with dispersant chemistry for direct incorporation into paint and coating formulations.
Slurry dominates coastal paper corridor offtake. Powder retains inland ceramics preference where water logistics are uneconomic.
Quality Level:
Regulatory segmentation between industrial, food, and pharmaceutical applications fragments supplier qualification timelines and fixed cost structures.
- Industrial Grade:Standard beneficiated kaolin for paper, ceramics, paints, and plastics without specialized purity certifications. Volume leadership rests here, though margin compression from GCC substitution below 90 GE brightness thresholds constrains expansion.
- Food Grade:Kaolin meeting national food contact material standards for use as anti-caking agents and processing aids. China's SAMR and India's FSSAI maintain divergent heavy metal limits that complicate cross-border supply.
- Pharmaceutical Grade:GMP-compliant kaolin for antacid and topical excipient applications. South Korea's MFDS standards and Japan's PMDA requirements create premium pricing tiers, though qualified Asian suppliers remain scarce relative to European sourcing.
- Others:Cosmetic and specialty grades outside standard industrial classification.
Industrial Grade captures volume concentration. Pharmaceutical Grade exhibits steepest expansion trajectory as MFDS-certified capacity lags Korean formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangxi Free Trade Zone and India's PLI-designated specialty mineral corridors are concentrating beneficiation investments, pulling capacity toward export-facing processing nodes.
China
Paper coating pigment demand and ceramics body formulation pull hydrous and calcined grades through the Jiangxi-Guangdong corridor. GB standards for ceramic raw materials tighten iron oxide thresholds below 0.5 percent for premium porcelain. Shandong province mills retrofit coating lines for higher filler loadings, compressing specification windows.
India
Sanitaryware cluster expansion in Morbi and paper-grade mineral demand drive hydrous kaolin absorption. The PLI scheme for specialty minerals accelerates domestic beneficiation capacity, reducing import dependence. Gujarat and Rajasthan processing nodes scale output for BIS-certified paper grades.
Vietnam
ASEAN bathroom fixture demand scales output across the Binh Duong to Hai Phong ceramics corridor. Hydrous kaolin dominates sanitaryware formulations prioritizing plasticity over brightness. Import substitution mandates create captive offtake potential for regional processors.
Thailand
Automotive plastics compounders in Rayong's eastern seaboard consolidate procurement through direct mill relationships. Tier-1 suppliers specify surface-engineered fillers for polypropylene bumper compounds. Silane-coupled grades displace talc in injection-molded applications.
Australia
WA Kaolin export logistics face port capacity constraints at Fremantle, forcing Southeast Asian buyers to reroute supply chains. Western Australian deposit development targets ceramics and paper-grade feedstock exports. Logistics reconfiguration lengthens delivery timelines to Indonesian and Vietnamese processors.
Asia-Pacific Kaolin Market Competitive Environment
Chinese producers anchor the volume tier; European and Australian specialists hold premium-grade positioning through calcination and logistics control. The vendor base separates into integrated miners with captive reserves, technology licensors with flash calcination systems, and regional grinders serving plastics compounders. Consolidation pressure concentrates among mid-cap beneficiators facing dual certification burdens. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the integrated miner tier, Jiangxi Sincere Mineral Industry Co., Ltd. exemplifies reserve-backed positioning through captive hydrous deposits. Imerys S.A. occupies the technology-licensor archetype with calcination system deployment across Asian production nodes. 20 Microns Limited represents the regional specialist model, anchoring ultra-fine grinding capabilities for Indian plastics and paint formulators.
| Leading Market Players |
|---|
| EICL Limited |
| 20 Microns Limited |
| Imerys S.A. |
| Jiangxi Sincere Mineral Industry Co., Ltd. |
| WA Kaolin |
| BASF SE |
| SCR-Sibelco |
| Uma Group of Kaolin |
| Ashapura Group |
| Others |
Value Chain & Pricing Dynamics
Captive reserve integration by Jiangxi Sincere Mineral Industry and Imerys S.A. anchors supply positioning while creating pricing power through controlled brightness-grade output. This vertical control over hydrous deposits and calcination technology shapes contract negotiations with paper mills and ceramics compounders across the region.
Pricing Analysis
Short lead-time premiums dominate contract structures, with spot inventory discounts emerging from Australian logistics constraints. Three-tier pricing structure across premium calcined, standard hydrous, and economy ceramic grades differentiates on brightness certification and particle size distribution. Cost compression in mid-tier hydrous grades intensifies from ground calcium carbonate substitution at paper mills below 90 GE brightness thresholds. Sanitaryware compounders in Vietnam demonstrate highest price sensitivity, while pharmaceutical formulators in South Korea accept premium positioning for MFDS-certified excipient grades.
Supply Chain Analysis
Certification gating through China's GB standards and India's BIS requirements fragments supplier qualification timelines and raises fixed cost entry barriers. Geographic concentration centers on China's Jiangxi-Guangdong corridor, India's Gujarat-Rajasthan processing nodes, and Western Australia's export-facing deposits. Raw material dependencies include high-brightness hydrous feedstocks, natural gas for calcination energy, and flotation reagents for iron removal. Single-source vulnerability runs through Fujian province deposit depletion, forcing blend strategies with lower-quality reserves. Distribution runs through coastal slurry terminals for paper mills and inland powder logistics for ceramic tile producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, where India's PLI scheme for specialty minerals creates a barrier-to-entry moat for domestic beneficiation investments that foreign entrants struggle to replicate.
For Market Incumbents: To counter ground calcium carbonate substitution at paper mills, deepen captive reserve control through lease extensions in Jiangxi and Rajasthan deposit belts, while accelerating flash calcination technology licensing to mid-tier processors seeking REACH-compliant export positioning. For New Entrants and Emerging Players: South Korea's MFDS standards open a window for pharmaceutical-grade kaolin production, targeting the antacid and topical excipient white-space where qualified Asian suppliers remain scarce relative to Korean formulation demand, with go-to-market through direct technical service agreements with Rayong automotive compounders. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-licensor acquisitions by integrated miners seeking calcination capability, with long-term viability hinging on beneficiation chemistry expertise scarcity; the signal to watch is flash calcination system order backlogs at Asian equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Jiangxi Sincere secures brightness-grade feedstock control against Fujian depletion. |
| Flash Calcination Technology Licensing | Imerys extends REACH-compliant output from Asian production nodes to European paper mills. |
| MFDS Pharmaceutical Certification Investment | Qualified processors capture premium pricing tiers in Korean antacid formulation supply. |
| Direct Mill Relationships in Automotive Plastics | Rayong compounders consolidate procurement through technical service-integrated contracts. |
| Slurry Terminal Expansion at Port-Adjacent Sites | Guangdong processors eliminate dust handling costs for coastal paper coating kitchens. |
Study Parameters
Multi-period observation of calcination capacity additions, BIS certification timelines, and PLI scheme disbursement rates anchored the trend analysis, supplemented by interviews with beneficiation plant managers, paper mill procurement leads, ceramic body formulators, and pharmaceutical excipient specialists. Secondary validation drew from China customs trade data, Indian Bureau of Mines production statistics, SEC filings of listed processors, and ASEAN ceramics association output surveys. Bottom-up volume builds across grade tiers triangulated against top-down market sizing from end-use consumption patterns.
Input-output matrix modeling connected kaolin grade specifications to end-use technical requirements across the projection horizon, with segmentation dimensions spanning product type, quality certification tier, and regional production hub. CAGRs derived from trend extrapolation of beneficiation capacity expansion and substitution elasticity estimates for titanium dioxide extension applications. Forecast inputs included natural gas price volatility assumptions for calcination economics and deposit depletion curves for Fujian province reserves.
The model assumes a particular technology adoption path for flash calcination diffusion; alternative pathways for energy-efficient metakaolin production would alter the outlook for mid-tier paper grade positioning. Forecasts reflect documented assumptions on regulatory enforcement intensity for GB and BIS standards. A model refresh is warranted upon material change in India's PLI scheme disbursement rates or Indonesian downstream ceramics protectionism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Potassium Silicate Market
Ceramics
Global Industrial Clay Market
Ceramics
Global Functional Ceramics Market
Ceramics
Glazed Bricks Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Zirconium Dioxide Market
Ceramics
Methyl Silicate Market
Ceramics
Clay Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Wollastonite Market
Ceramics
Ceramic Kilns Market
Ceramics
Calcium Silicate Market
Ceramics
Nano Ceramic Coatings Market