
 Methyl Silicate Market | 2026-2036
Methyl Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Silicate Market Foresight
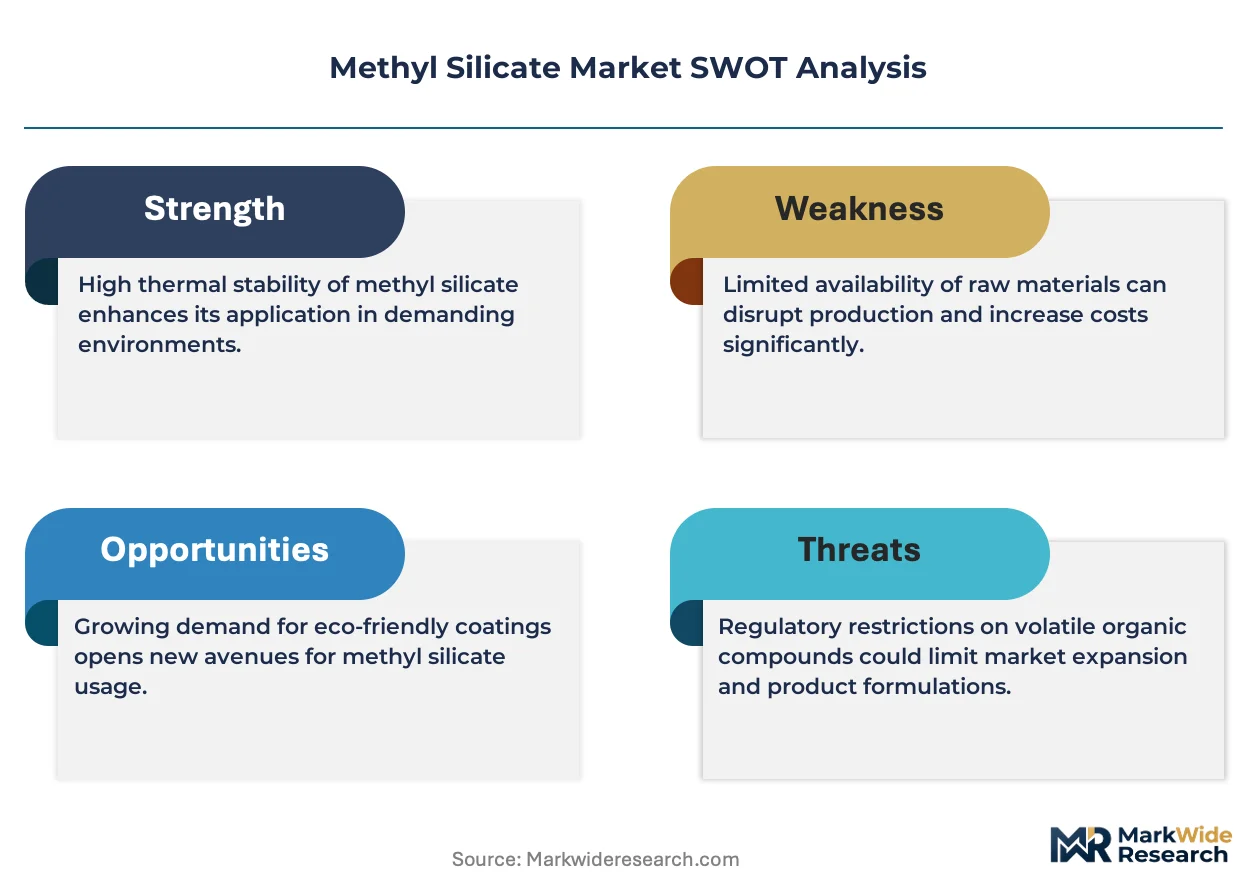
A capital-intensity divergence between integrated silane producers and specialty chemical distributors is unwinding traditional competitive boundaries in methyl silicate supply. Wacker Chemie AG leverages its backward integration into silicon metal and chlorosilane feedstocks to sustain cost leadership across European and Asian manufacturing nodes. BASF SE anchors its position through broad formulation expertise that extends methyl silicate into proprietary coating binder systems for automotive OEMs. Mitsubishi Chemical Corporation competes via dedicated silane R&D centers in Japan that specialize in ultra-purity grades for semiconductor encapsulation.
Methyl silicate refers to a family of silicon-based esters, primarily tetramethyl orthosilicate (TMOS), synthesized via alcoholysis of silicon tetrachloride with methanol and valued for their ability to form silica networks through hydrolysis-condensation reactions at room temperature. These compounds serve as crosslinking agents, adhesion promoters, and binders in sol-gel coatings, delivering chemical resistance and substrate bonding across metal, glass, and polymer surfaces. Methyl Trimethoxy Silane leads product type volumes due to its balanced reactivity and storage stability, while Methyl Triacetoxysilane commands premium positioning in electronics-grade sealants where moisture-cure speed determines manufacturing throughput. Coatings application segments dominate value capture, though adhesives and sealants for electric vehicle battery packs represent the fastest-expanding demand pool as thermal management requirements intensify.
EPA regulations under the Clean Air Act constrain solvent emissions from architectural and industrial coatings, directly shaping methyl silicate formulation thresholds and pushing manufacturers toward higher-solids or waterborne silane systems. REACH registration requirements and the EU Green Deal's chemical sustainability targets impose full substance lifecycle documentation, creating compliance barriers for non-integrated importers while rewarding producers with established European registration dossiers. ECHA's evolving restrictions on Substances of Very High Concern further tighten the acceptable impurity profile for methyl silicate destined for consumer-facing applications. Stakeholders must monitor the intersection of fluoropolymer phase-out timelines and silane-based alternatives development, as regulatory displacement of perfluorinated chemistry opens formulation partnerships that will redefine competitive positioning across the next decade.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound limits are forcing simultaneous reformulation of methyl silicate systems across construction coatings and electronics sealants, compressing product development cycles while opening substitution windows for lower-emission silane architectures.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Full lifecycle documentation mandates favor established European registrants with existing dossiers, accelerating market consolidation around compliant producers.
- Electric vehicle battery pack thermal management:Automakers specify methyl silicate-based sealants for flame-retardant encapsulation of lithium-ion cell arrays.
- Fluoropolymer phase-out timelines:Regulatory displacement of perfluorinated chemistry drives formulation partnerships toward silane-based alternatives in architectural coatings.
Market Restraints
- Chlorosilane feedstock concentration:Integrated producers in Germany and China control upstream silicon metal supply, constraining margin flexibility for non-integrated compounders.
- Moisture-cure speed limitations:Methyl triacetoxysilane electronics grades require controlled humidity environments, restricting high-throughput manufacturing adoption.
- ECHA Substances of Very High Concern restrictions:Tightening impurity thresholds for consumer-facing applications lengthen qualification timelines and raise analytical costs.
Strategic Opportunities
- Semiconductor encapsulation ultra-purity grades:Japanese R&D centers specialize in sub-ppm contamination specifications for advanced packaging applications.
- Waterborne silane system development:Higher-solids formulations capture architectural coatings demand as EPA Clean Air Act enforcement intensifies.
- Infrastructure renewal clusters:Weather-resistant building envelope specifications in the United States and Germany expand addressable market for sol-gel coating binders.
Industry Challenges
- Cross-functional formulation expertise scarcity:Hybrid competencies spanning silane chemistry, polymer science, and regulatory compliance command premium compensation and lengthen hiring cycles.
- Multi-jurisdiction registration synchronization:Divergent EPA, REACH, and GB standards timelines force parallel dossier preparation, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Silicate Market |
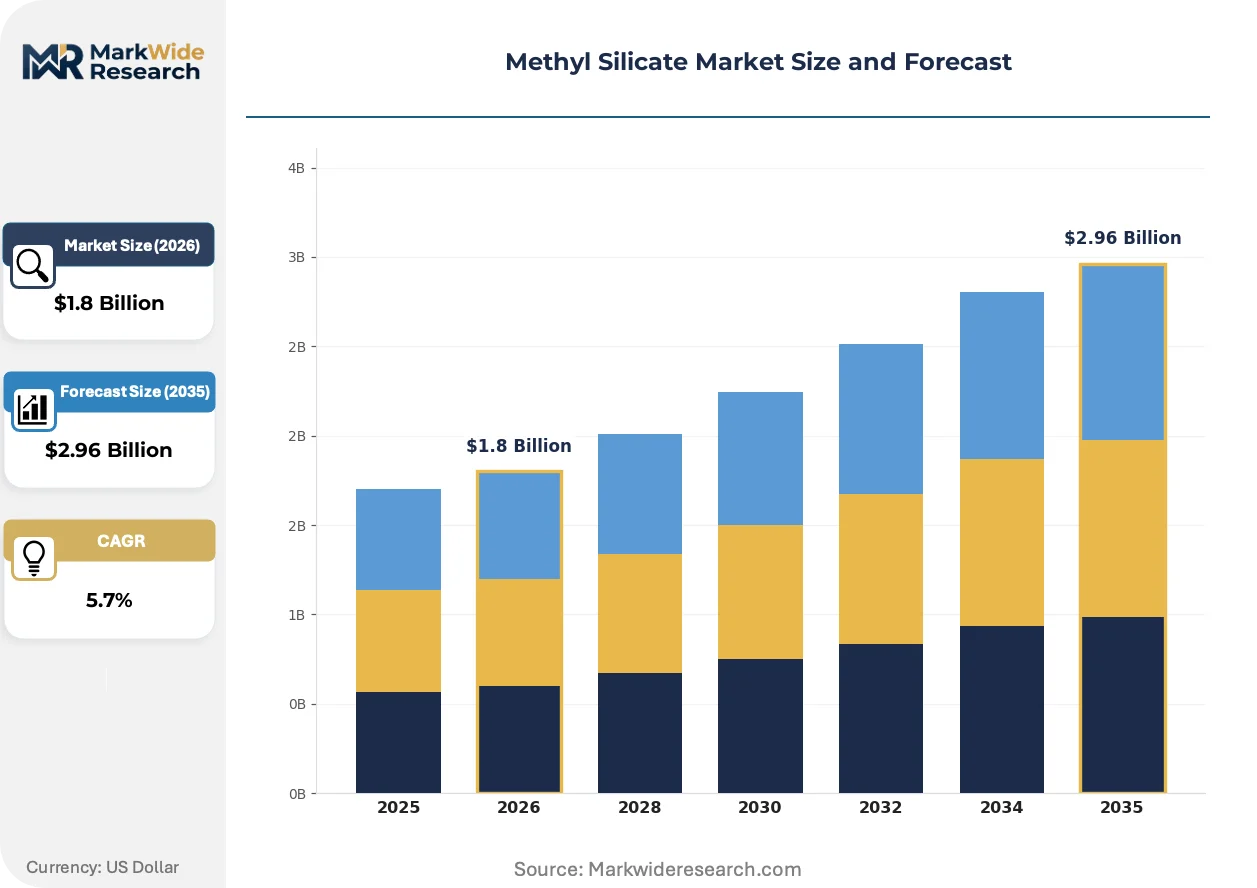
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
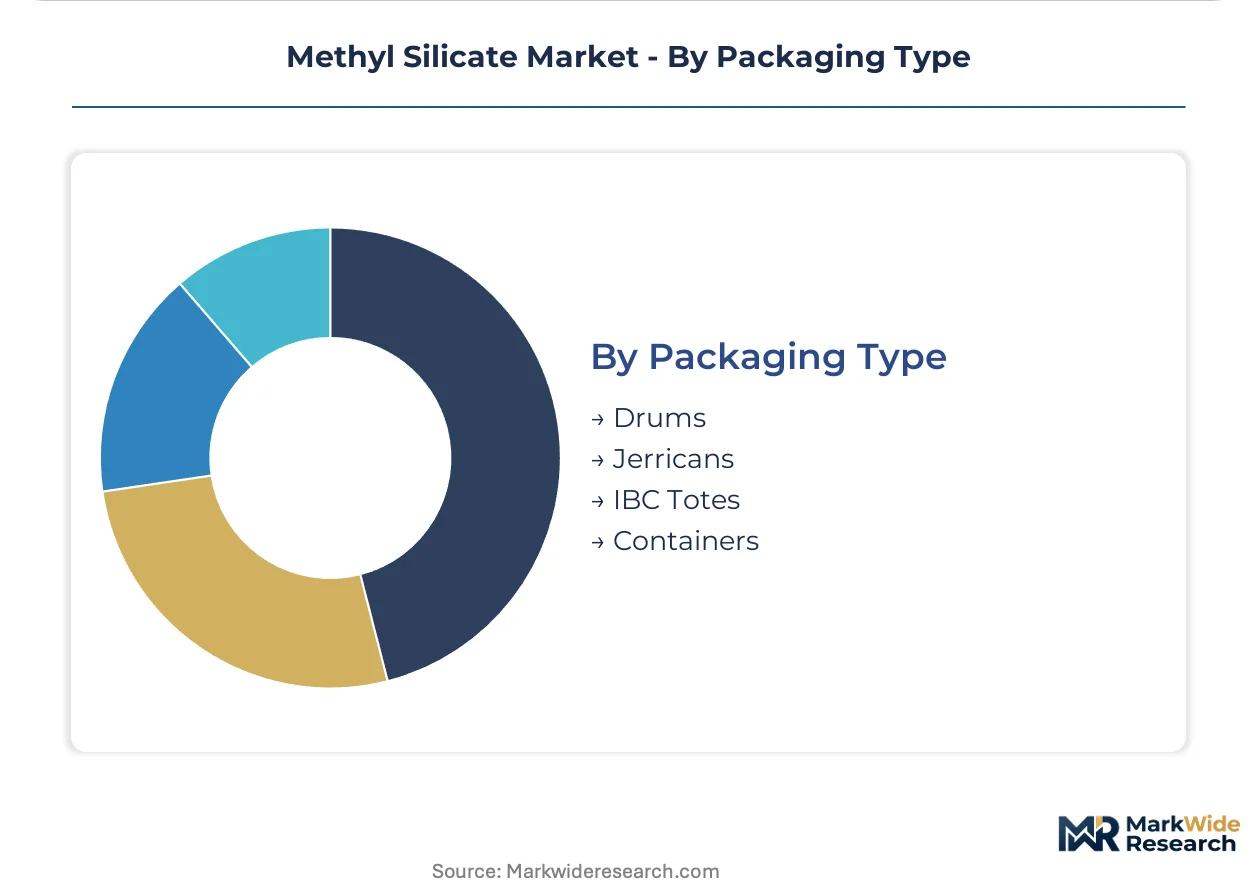
| Segmentation | Product Type: Methyl Trimethoxy Silane, Methyl Triacetoxysilane, Methyl Dimethoxy Silane, Methyl Silicate Application: Coatings, Adhesives, Sealants, Chemicals End User: Construction, Automotive, Electronics, Textile Packaging Type: Drums, Jerricans, IBC Totes, Containers |
| Companies Covered | BASF SE, Eastman Chemical Company, Mitsubishi Chemical Corporation, Solvay, SABIC, Huntsman Corporation, Wacker Chemie AG, Albemarle Corporation, Kraton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Silicate Market Shifts & Advancements
Silane chemistry convergence with sol-gel processing is redefining performance benchmarks across protective coatings, while regulatory chemistry restrictions and procurement centralization reshape how value flows through the supply chain.
Waterborne methyl silicate dispersions are supplanting solvent-based systems in architectural metal coatings. Building envelope specifiers in Germany and the northeastern United States now mandate low-VOC formulations for LEED-compliant projects. This transition compresses margins for legacy solvent producers while rewarding compounders with aqueous dispersion expertise and captive emulsification capacity.
REACH registration requirements now extend to full substance lifecycle documentation under the EU Green Deal's chemical sustainability framework. Industrial coatings manufacturers face extended qualification periods for new raw material sources. European formulators with established registration dossiers capture share from non-integrated importers lacking compliance infrastructure.
Automotive OEMs now consolidate methyl silicate procurement through direct silane producer relationships, bypassing specialty chemical distributors. Tier-one battery pack manufacturers in China and South Korea negotiate multi-year supply agreements specifying purity grades and moisture-cure kinetics. This channel compression squeezes distributor margins while transferring formulation technical service responsibilities to silane producers.
Methyl Silicate Market Segmentation
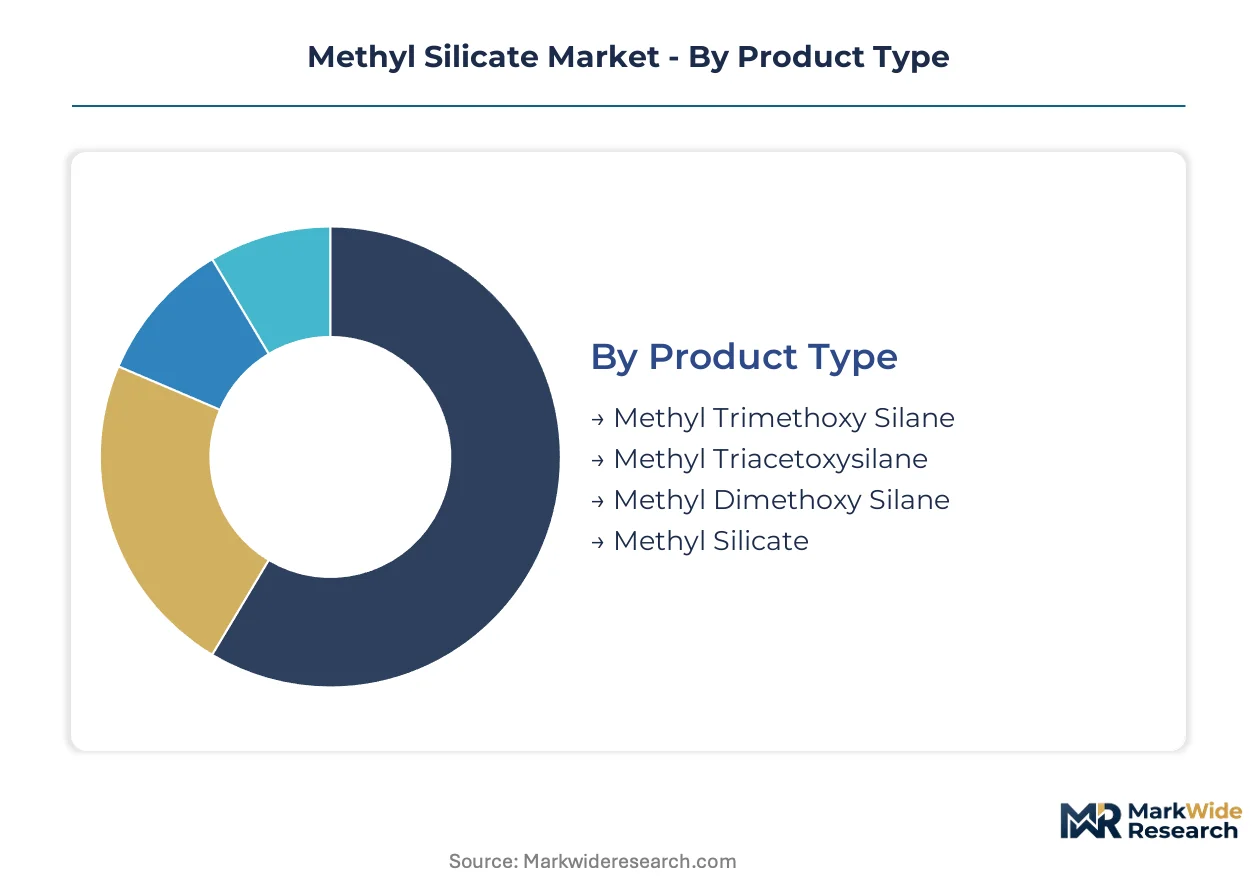
Methyl silicate formulations vary dramatically in reactivity profiles and purity specifications, creating distinct supply chains for commodity construction grades versus electronics-grade materials. Segmentation clarity enables buyers to match cure kinetics and contamination thresholds to specific manufacturing environments.
Product Type:
Export-led demand concentrates in Methyl Trimethoxy Silane and ultra-purity Methyl Triacetoxysilane for Asian semiconductor packaging, while domestic consumption in Germany and the United States favors standard grades for weatherproofing applications.
- Methyl Trimethoxy Silane:A three-methoxy substituted silane delivering balanced hydrolysis rates and 12-month ambient storage stability. Construction coating formulators in Germany specify this grade for sol-gel binders in building envelope systems, though moisture sensitivity during transport constrains long-haul export economics.
- Methyl Triacetoxysilane:Acetoxy-functional silane releasing acetic acid upon cure, prized for rapid condensation kinetics. Electronics sealant manufacturers in South Korea and Japan demand sub-ppm metal contamination specifications for lithium-ion battery pack encapsulation, with moisture-cure speed directly determining automated dispensing line throughput.
- Methyl Dimethoxy Silane:Reduced methoxy substitution yields slower hydrolysis for controlled-release formulations.
- Methyl Silicate:Tetramethyl orthosilicate base chemistry serving as silica precursor in specialized sol-gel research applications.
Methyl Trimethoxy Silane holds the largest share; momentum sits with Methyl Triacetoxysilane as battery thermal management specifications tighten.
Application:
Cost tier stratification separates high-value sealant formulations from commodity coating binders, with adhesives commanding formulation service premiums that coatings margins cannot support.
- Coatings:Sol-gel derived silica networks deposited from alkoxide solutions create abrasion-resistant barriers on aluminum architectural panels. EPA Clean Air Act enforcement in the United States has compressed solvent-based system viability, pushing formulators toward higher-solids silane architectures that retain substrate wetting without volatile organic compound penalties.
- Adhesives:Silane coupling agents bridge inorganic fillers to organic polymer matrices in structural bonding systems. Automotive OEMs in China specify methyl silicate primers for composite-to-metal joints in electric vehicle chassis assemblies, where thermal cycling resistance outweighs per-kilogram material cost.
- Sealants:Room-temperature vulcanizing formulations dominate electronics encapsulation demand.
- Chemicals:Intermediate applications in silica synthesis and specialty reagent production.
Coatings generates the highest absolute volume; sealants for battery packs are climbing the fastest.
End User:
Customer type fragmentation splits procurement between specification-driven automotive engineers and price-sensitive construction contractors, with electronics buyers occupying a middle ground of technical negotiation.
- Construction:Weather-resistant building envelope specifications in Germany and the northeastern United States drive sol-gel coating demand for LEED-compliant commercial structures.
- Automotive:Electric vehicle battery pack manufacturers specify flame-retardant methyl silicate encapsulants for cell array thermal management.
- Electronics:Semiconductor packaging houses in Japan require ultra-purity grades with sub-ppm contamination thresholds.
- Textile:Fabric finishing applications employ silane treatments for water repellency and dimensional stability.
Construction absorbs the greatest tonnage; automotive applications are expanding most quickly.
Packaging Type:
Supply concentration in chlorosilane feedstock regions shapes packaging logistics, with integrated producers favoring bulk formats that minimize handling costs across ocean freight lanes.
- Drums:Standard 200-liter steel drums serve mid-volume coating formulators requiring frequent material rotation.
- Jerricans:20-25 liter polyethylene containers suit laboratory-scale electronics developers and specialty adhesive compounders.
- IBC Totes:Intermediate bulk containers capture architectural coatings demand from large German and United States formulators with automated dispensing systems.
- Containers:ISO tank configurations enable efficient ocean freight from Chinese manufacturing clusters to European and North American port destinations.
Drums dominate current procurement patterns; IBC Totes are gaining share fastest as coatings formulators consolidate purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes methyl silicate predominantly for electronics-grade sealants, whereas Germany and the United States prioritize construction coatings and automotive applications. This demand-mix differential shapes distinct regulatory compliance burdens and supply chain configurations across consuming geographies.
China
Semiconductor packaging houses in Jiangsu and Shanghai provinces drive ultra-purity methyl triacetoxysilane consumption for lithium-ion battery encapsulation. GB standards under MIIT oversight tighten volatile organic compound thresholds for industrial coatings, accelerating waterborne silane system adoption. The Yangtze River Delta manufacturing cluster concentrates domestic production capacity alongside chlorosilane feedstock integration.
Germany
Weather-resistant building envelope specifications in North Rhine-Westphalia and Bavaria sustain sol-gel coating demand from commercial construction developers. REACH registration requirements and EU Green Deal chemical sustainability targets impose full lifecycle documentation obligations on formulators. The Cologne-Düsseldorf industrial corridor hosts backward-integrated silane producers with captive silicon metal supply.
United States
EPA Clean Air Act enforcement compresses solvent-based coating viability in the Northeast and Pacific Coast states, pushing formulators toward higher-solids methyl silicate architectures. Electric vehicle battery manufacturers in Michigan and California specify flame-retardant sealants for thermal management systems. The Houston-Gulf Coast petrochemical corridor handles bulk import logistics from Asian manufacturing nodes.
Japan
Semiconductor encapsulation houses in Kyushu and the Kanto region demand sub-ppm contamination specifications for advanced packaging applications. METI industrial standards govern silane purity grades for electronics manufacturing. Osaka-based R&D centers specialize in moisture-cure kinetic optimization for automated dispensing line throughput.
South Korea
Battery pack manufacturers in Gyeonggi Province negotiate multi-year methyl silicate supply agreements specifying cure speed and purity thresholds. MFDS chemical safety assessments apply to sealants used in consumer-facing electronics applications. The Busan-Ulsan industrial complex anchors import distribution for chlorosilane-derived feedstocks.
Methyl Silicate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where feedstock control separates margin sustainability from commodity vulnerability. German and Chinese producers with captive silicon metal supply dominate volume positions, while Japanese and US specialists capture premium tiers through purity certification. Three archetypes define competitive positioning: backward-integrated chemical conglomerates, silane-dedicated R&D specialists, and diversified coating-binder formulators. Capacity expansion in Asian manufacturing nodes and strategic partnerships for fluoropolymer displacement formulations constitute the dominant competitive moves.
Among European-integrated chemical conglomerates, BASF SE and Wacker Chemie AG occupy positions exemplifying feedstock-backed cost leadership and broad formulation expertise respectively. Mitsubishi Chemical Corporation represents the specialist archetype, anchoring ultra-purity grade development through dedicated silane R&D infrastructure. These three entities illustrate how geographic concentration of chlorosilane production and divergent end-market priorities—construction coatings versus semiconductor encapsulation—segment competitive advantage across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Mitsubishi Chemical Corporation |
| Solvay |
| SABIC |
| Huntsman Corporation |
| Wacker Chemie AG |
| Albemarle Corporation |
| Kraton Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Chinese chlorosilane producers and German coatings formulators lock in supply access while anchoring price visibility across volatile silicon metal feedstock markets. These contracts insulate integrated players from spot market swings while forcing non-integrated compounders into higher-cost procurement channels.
Pricing Analysis
Contract-based long-term offtake dominates methyl silicate procurement, with three-tier pricing structure across electronics-grade, industrial-grade, and commodity construction grades. Price differentiation rests on purity certification and volume scale, with sub-ppm semiconductor specifications commanding substantial premiums over sol-gel coating binders. Cost compression in standard construction grades is intensifying because REACH registration barriers squeeze non-integrated importers. Construction contractors exhibit highest price sensitivity, while battery pack manufacturers prioritize cure kinetics over per-kilogram economics.
Supply Chain Analysis
Chlorosilane feedstock concentration in China, Germany, and the United States shapes global methyl silicate availability. Production draws from silicon metal smelters, methanol supply contracts, and captive chlorosilane synthesis capacity. Single-source vulnerability runs through Yangtze River Delta manufacturing clusters where MIIT environmental inspections can constrain output. Distribution feeds from integrated producers directly to automotive OEMs and battery manufacturers, bypassing traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among automotive OEMs and battery pack manufacturers has shifted bargaining power toward large-volume buyers, fragmenting pricing leverage for smaller coatings formulators.
For Market Incumbents: Compound backward integration advantages by securing captive silicon metal supply in Germany and China while expanding aqueous dispersion capacity for EPA-compliant architectural coatings. Defend against fluoropolymer displacement partnerships by accelerating silane-alternative R&D with building envelope specifiers. Prioritize REACH dossier maintenance as ECHA restrictions tighten impurity thresholds. For New Entrants and Emerging Players: Lead with waterborne silane system expertise targeting LEED-compliant commercial construction in the northeastern United States and Bavaria. White-space opportunity sits with mid-volume coating formulators lacking captive emulsification capacity. Go-to-market angle: technical service partnerships that transfer formulation support responsibilities from distributors to producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated producers with established registration infrastructure. Long-term viability over the next decade rests on feedstock control and compliance dossier depth. Acquisition target archetype: regional silane compounders with aqueous dispersion technology and EPA registration pathways. Signal to watch: fluoropolymer phase-out acceleration in architectural coatings specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Wacker Chemie AG secures cost leadership across European and Asian manufacturing nodes. |
| Waterborne Silane System Development | Formulators capture EPA Clean Air Act compliance premiums in architectural metal coatings. |
| Long-term Supply Agreement | Battery manufacturers in South Korea lock in purity grades and moisture-cure specifications. |
| Joint Venture for Fluoropolymer Alternatives | Partnerships with building envelope specifiers accelerate silane-based coating adoption. |
| Capacity Expansion in Ultra-Purity Grades | Japanese R&D centers capture semiconductor encapsulation demand from Kyushu packaging houses. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, Cefic industry reports, and ECHA registration dossiers. Interviews with chlorosilane plant managers, coatings procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors informed supply-side and demand-side assessments. Bottom-up volume modeling triangulates against top-down value estimates across product grades and end-use segments.
Segmentation dimensions modeled include product type tier, application end-use, packaging format, and regional production hub across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating electric vehicle battery thermal management specifications and fluoropolymer displacement timelines. Industry-specific inputs capture REACH compliance cost pass-through and EPA enforcement intensity variations by state.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment and stable regulatory enforcement trajectories would require recalibration. Forecasts reflect documented assumptions about chlorosilane feedstock availability and silane-alternative formulation adoption rates. Practitioners should keep alternative scenarios live as ECHA Substances of Very High Concern restrictions and MIIT environmental inspection protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Quartz Powder Market
Ceramics
Ceramic Substrate Market
Ceramics
Ceramic Pigments Market
Ceramics
Europe Activated Alumina Market
Ceramics
High Temperature Ceramics Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Calcined Kaolin Market
Ceramics
Potassium Feldspar Market
Ceramics
Global Ceramic Coating Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Global Magnesium Silicate Market
Ceramics
North America Activated Alumina Market
Ceramics
Strontium Carbonate Market
Ceramics
Global Ceramic Tube Market
Ceramics
Ceramic Solid End Mills Market