
 Cement Castables Market | 2026-2036
Cement Castables Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Castables Market Analytics
EU Green Deal carbon border adjustments is pivoting the cost structure for cement castables sold into European steel and energy end users. RHI Magnesita leverages its vertical integration in magnesia raw materials to sustain margin stability under these compliance costs. Vesuvius competes through specialized mold-making formulations that anchor its position in automotive casting applications. Krosaki Harima dominates Asia-Pacific supply through dense castables production with controlled permeability specifications.
Cement castables are hydraulic-setting refractory concretes composed of high-alumina aggregates, calcium aluminate cement binders, and functional additives, formulated for installation by casting, gunning, or ramming to form monolithic linings that withstand thermal shock and chemical attack above 1,400°C. Low-cement and ultra-low-cement formulations contain reduced CaO content, which minimizes low-melting-point phase formation and extends lining life in aggressive slag environments. Dense castables command the highest performance tier in steel ladle and blast furnace applications where erosion resistance determines replacement cycles. Refractory linings as an application category absorbs the majority of volume, though mold making in automotive and aerospace casting delivers premium pricing due to dimensional precision requirements.
EPA emissions standards for steelmaking and foundry operations in the United States drive demand for longer-lasting linings that reduce relining frequency and associated downtime emissions. REACH chemical registration in Europe restricts certain binder chemistries, pushing reformulation toward ultra-low-cement systems with reduced chromite and crystalline silica content. China's MEE enforces stricter industrial air quality rules that favor monolithic refractories over brick constructions for easier installation and lower particulate generation during maintenance. Stakeholders must monitor how carbon border mechanisms reshape raw material sourcing decisions and whether regional certification divergence fragments product portfolios.
Market Dynamics
Blast furnace rebuild cycles in China's Hebei province are compressing replacement timelines, while the EU Green Deal's carbon border adjustments force European steelmakers to prioritize lining longevity over upfront material costs.
Growth Catalysts
- MEE air quality enforcement:China's Ministry of Ecology and Environment mandates stricter particulate controls that favor monolithic castables over brick constructions for faster installation and reduced maintenance emissions.
- Steel ladle relining automation:Indian integrated steel producers accelerate monolithic refractory adoption to cut vessel turnaround time from 72 hours to sub-48-hour cycles.
- Calcium aluminate cement advances:Low-CaO binder chemistries extend campaign life in aggressive slag environments, reducing replacement frequency in basic oxygen furnace runners.
Market Restraints
- Fused alumina supply concentration:Brazilian and Guinean bauxite processing bottlenecks create raw material vulnerability for high-alumina aggregate formulations.
- REACH chemical registration friction:ECHA restrictions on chromite and crystalline silica content force costly reformulation of ultra-low-cement systems for European foundry customers.
- Magnesia price volatility:Electric arc furnace dust recycling disruptions and Chinese environmental shutdowns spike fused magnesia costs unpredictably.
Strategic Opportunities
- Indonesian nickel smelter buildout:Pyrometallurgical rotary kiln and electric furnace installations create unmet demand for spinel-forming castables in Southeast Asian greenfield projects.
- EU carbon border adjustment mechanism:CBAM compliance costs on imported refractories incentivize local European production of longer-life lining materials.
- Digital gunning robotics:Automated shotcreting systems converge with real-time thickness monitoring to enable precision installation in steel mill maintenance windows.
Industry Challenges
- Refractory engineer scarcity:Specialized knowledge of thermal cycling behavior and slag penetration mechanics retires faster than vocational programs replace it.
- ISO 9001:2015 certification timelines:Extended audit cycles for quality management systems delay market entry for new ultra-low-cement product lines.
- Legacy brick-to-monolithic conversion:Steel mill maintenance crews resist casting installation techniques, requiring retraining investment that compresses contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Castables Market |
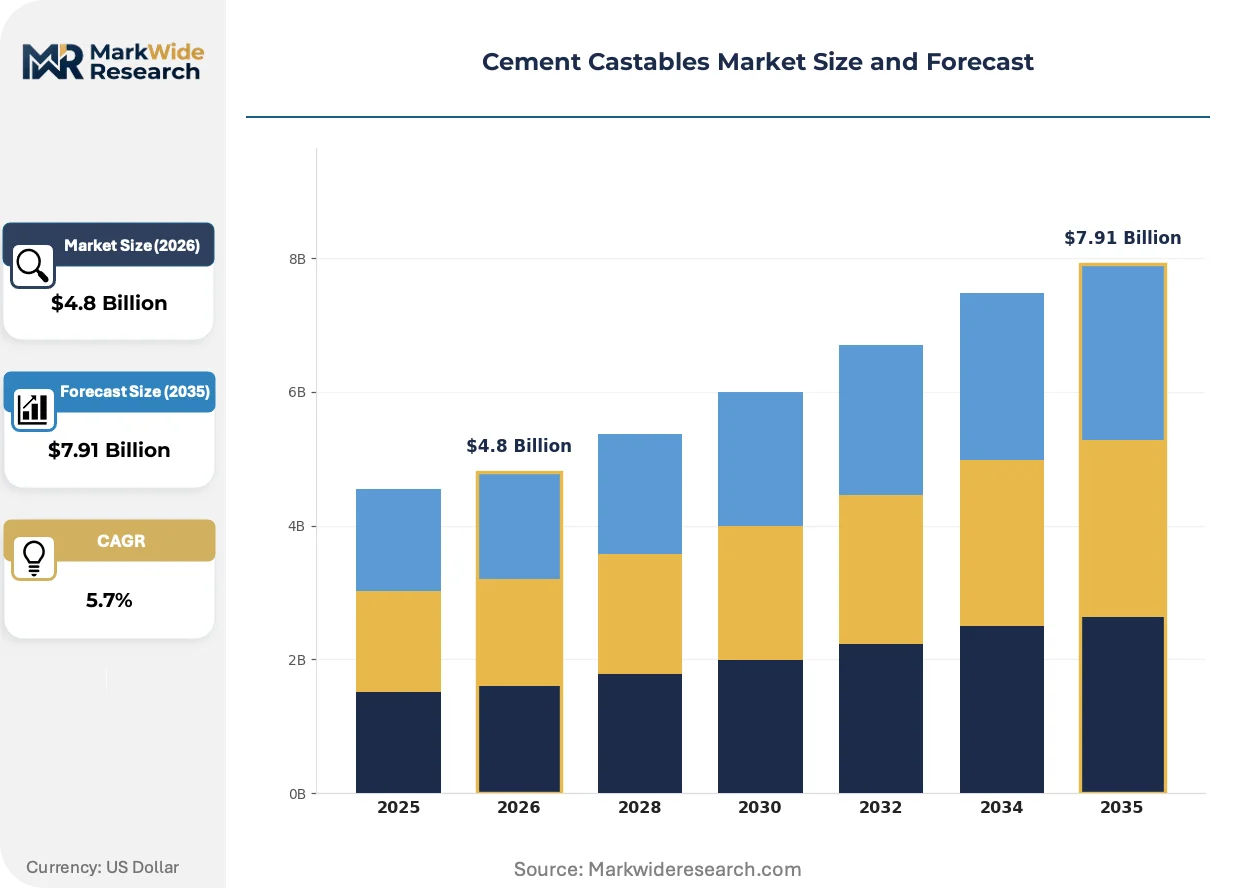
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Low-Cement, Ultra-Low-Cement, Dense End User: Steel, Energy, Automotive, Aerospace Application: Refractory Linings, Mold Making, Casting, Insulation Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | RHI Magnesita, Vesuvius, Saint-Gobain, Krosaki Harima, Shinagawa Refractories, HarbisonWalker International, Morgan Advanced Materials, Imerys, IFGL Refractories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Castables Market Evolving Landscape
Digital installation monitoring and predictive lining analytics are compressing maintenance windows. Formulation chemistry advances target slag resistance without chromite content. Supply chain regionalization accelerates as carbon accounting reshapes sourcing decisions.
Nano-engineered calcium aluminate binders with sub-micron particle distribution are converging with self-flow casting techniques to enable complex ladle bottom profiles without vibration equipment. Japanese specialty steel producers adopt these systems for ultra-clean steel grades. The technology is converging with robotic gunning platforms to eliminate human variability in thickness control.
REACH Annex XVII restrictions on chromium VI compounds force elimination of chromite-containing castables from European foundry supply chains by 2026. Refractory manufacturers reformulate with magnesium aluminate spinel aggregates to maintain corrosion resistance. Foundries in Germany and Italy face the steepest compliance curves due to existing chromite-heavy inventory positions.
Steel mill procurement departments unbundle refractory supply from installation services, awarding separate contracts to specialized applicators. This disintermediation pressures traditional full-service refractory houses to defend margin on material-only sales. The shift is most advanced in South Korean POSCO-affiliated mills and is spreading to Tata Steel European operations.
Cement Castables Market Segmentation
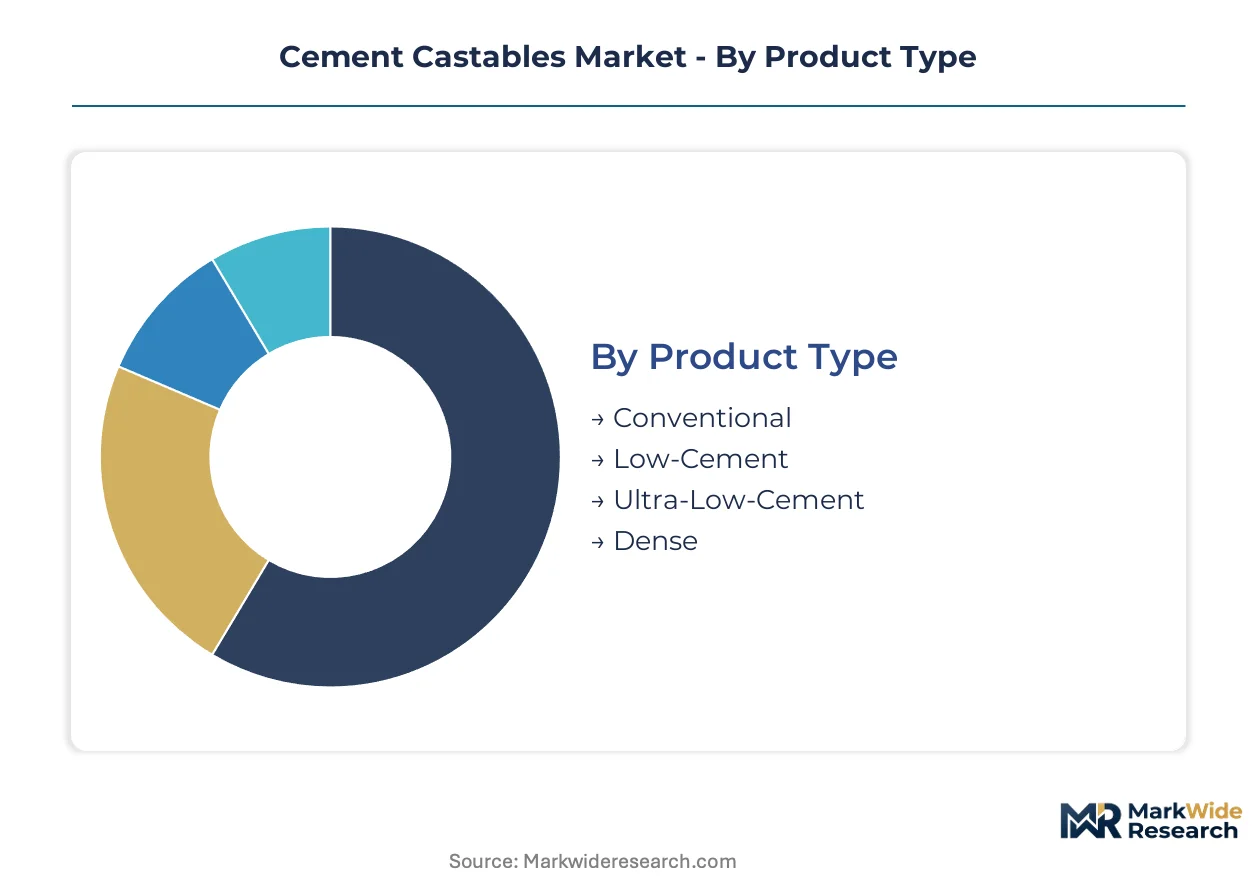
Segmentation in cement castables reveals how formulation chemistry, end-use thermal severity, and installation method interact to determine procurement priorities. Buyers trade upfront material cost against campaign life, maintenance labor, and regulatory compliance across distinct application environments.
Product Type:
Buyers select cement castable grades based on the thermal aggressiveness of their process environment and the erosion resistance required for campaign duration targets.
- Dense:These formulations achieve maximum bulk density through optimized particle packing and reduced porosity, delivering superior slag penetration resistance in blast furnace hearths and steel ladle impact pads. Demand concentrates in China's Hebei province where blast furnace rebuild cycles are compressing, driven by MEE air quality mandates that penalize frequent relining downtime.
- Ultra-Low-Cement:Containing under 1% CaO content, these systems minimize low-melting-point phase formation and extend lining life in basic oxygen furnace runners exposed to aggressive slag chemistries. European foundries pivot toward these formulations as REACH Annex XVII restrictions on chromite and crystalline silica force binder chemistry reformulation.
- Low-Cement:Intermediate CaO levels balance installation rheology with performance, serving secondary steelmaking vessels and aluminum melting furnaces where thermal cycling dominates wear mechanisms.
- Conventional:Higher cement content formulations retain cost advantage for lower-temperature applications in heat treatment furnaces and incineration units where slag attack remains moderate.
Volume sits with Conventional grades in maintenance-heavy industries; growth tilts toward Ultra-Low-Cement as regulatory pressure intensifies in Europe and China.
End User:
End-use thermal profiles and relining economics create divergent specification requirements across heavy industry verticals.
- Steel:Integrated producers and mini-mills consume the dominant share, with Indian operators accelerating monolithic adoption to compress vessel turnaround from 72 hours below 48 hours. Ladle lining, tundish flow control, and blast furnace stack repair drive specification diversity.
- Energy:Power generation and waste-to-energy facilities demand thermal shock resistance in cyclically operated boiler linings and incinerator combustion chambers.
- Automotive:Foundry mold making and pouring refractories require dimensional precision for engine block and transmission casting, with premium pricing attached to surface finish consistency.
- Aerospace:Superalloy investment casting and directional solidification processes impose extreme purity requirements, with titanium and nickel alloy foundries specifying ultra-low-iron content systems.
Steel commands installed base volume; aerospace and automotive foundry applications capture the steepest expansion trajectory through precision-grade premiumization.
Application:
Installation method and functional performance requirements segment demand across distinct refractory system architectures.
- Refractory Linings:Monolithic installations in steel vessels, non-ferrous smelters, and cement kilns absorb the majority of volume, with gunning and casting techniques displacing brick construction in maintenance-intensive environments.
- Mold Making:Foundry mold and core production for automotive and aerospace casting delivers premium pricing due to dimensional tolerance requirements and surface finish specifications.
- Casting:Direct pouring refractories for molten metal transfer and distribution systems in steel mills and foundries.
- Insulation:Backup lining systems and thermal barrier applications where heat loss reduction outweighs mechanical wear resistance.
Refractory Linings anchor volume throughput; Mold Making gains share fastest as automotive lightweighting intensifies casting complexity.
Distribution Channel:
Procurement channel selection reflects order scale, technical service requirements, and supply chain reliability priorities.
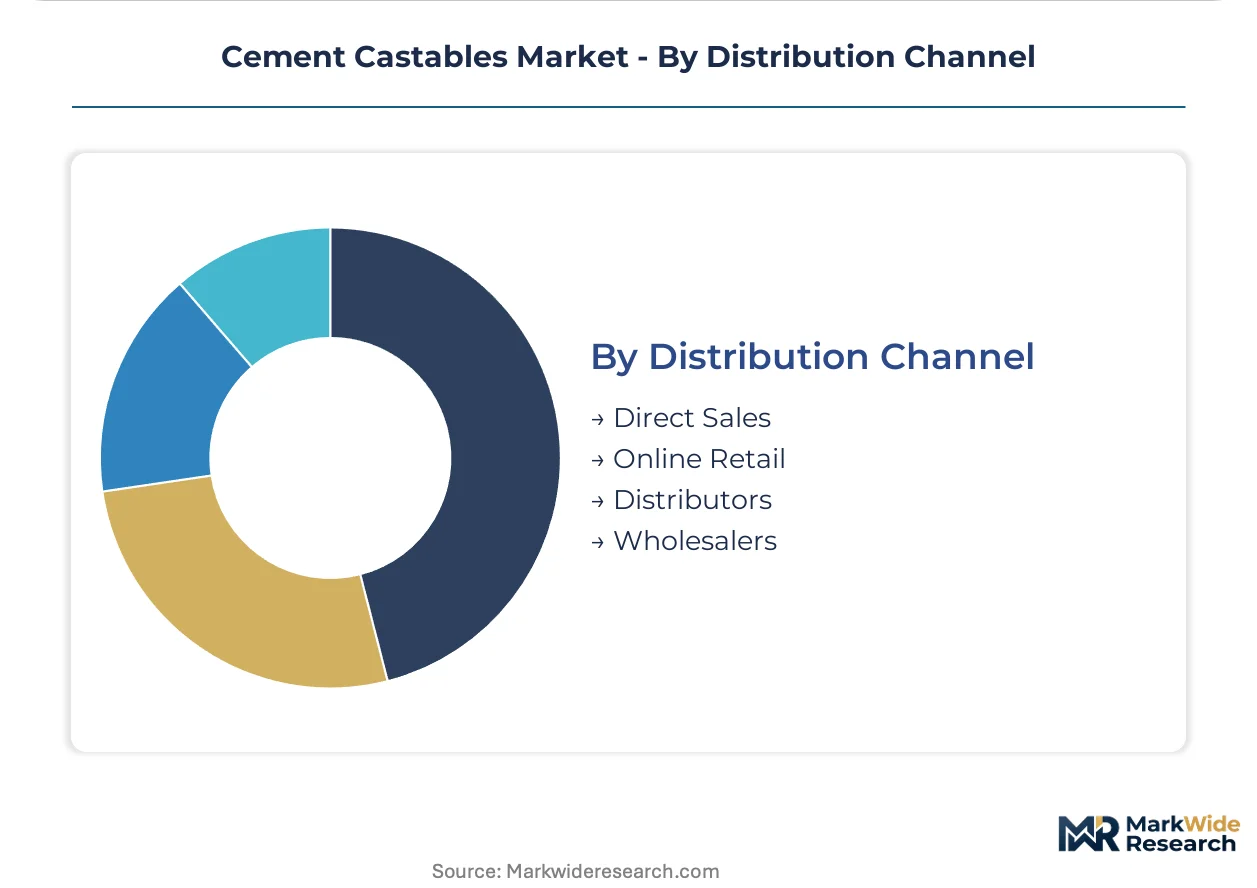
- Direct Sales:Large steel mills and integrated foundries negotiate direct supply agreements with refractory manufacturers, bundling material provision with installation supervision and campaign performance guarantees.
- Distributors:Regional stocking distributors serve mid-tier foundries and maintenance contractors with fragmented demand patterns, providing technical consultation and just-in-time delivery.
- Wholesalers:Volume aggregation for smaller end users and repair contractors in geographically dispersed industrial clusters.
- Online Retail:Emerging channel for standardized grades, technical documentation, and small-lot procurement in maintenance-repair-operations segments.
Direct Sales holds volume concentration; Distributors expand most quickly as procurement departments unbundle material supply from installation services across Asian and European steel mills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hebei province operates as a concentrated demand zone where MEE air quality mandates accelerate blast furnace rebuild cycles and monolithic refractory adoption.
China
Hebei province steel mills compress vessel turnaround timelines under MEE particulate enforcement. The Ministry of Ecology and Environment mandates reduced maintenance emissions. Tangshan and Handan industrial clusters drive dense castable consumption for blast furnace hearth rebuilds.
India
Integrated steel producers in Odisha and Jharkhand adopt monolithic systems to cut relining downtime below 48 hours. The PLI scheme for specialty steel incentivizes lining longevity investments. Rourkela and Jamshedpur steel corridors anchor ultra-low-cement formulation demand.
Germany
Foundries in the Ruhr region reformulate away from chromite content under REACH Annex XVII restrictions. ECHA chemical registration forces binder chemistry shifts. Düsseldorf industrial basin specialists pivot toward magnesium aluminate spinel aggregates.
United States
EPA emissions standards for steelmaking drive longer-lasting lining specifications to reduce relining frequency. Integrated mills in the Great Lakes region optimize campaign life. Gary and Cleveland steel corridors concentrate demand for erosion-resistant castable systems.
Indonesia
Nickel smelter buildout in Sulawesi and Maluku creates unmet demand for spinel-forming castables in pyrometallurgical installations. The national mineral processing expansion program accelerates rotary kiln construction. Morowali Industrial Park anchors greenfield refractory procurement.
Cement Castables Market Competitive Landscape
European producers anchor one tier; Asia-Pacific specialists hold volume concentration in dense castable supply. The market structures around three strategic archetypes: vertically integrated raw material owners, formulation specialists, and installation-integrated service providers. M&A activity concentrates in captive magnesia supply access. Technology licensing agreements proliferate for low-CaO binder systems.
Within the integrated materials tier, RHI Magnesita and Krosaki Harima occupy positions shaped by upstream control over refractory mineral supply. Vesuvius represents the specialized formulation archetype, with its company name signaling focus on molten metal flow control applications. These three entities exemplify how competitive positioning diverges between raw material security and application-specific technical performance.
| Leading Market Players |
|---|
| RHI Magnesita |
| Vesuvius |
| Saint-Gobain |
| Krosaki Harima |
| Shinagawa Refractories |
| HarbisonWalker International |
| Morgan Advanced Materials |
| Imerys |
| IFGL Refractories |
| Others |
Value Network & Pricing Analysis
Fused alumina price indices cascade through cement castable supply chains, compressing margins on high-alumina formulations while rewarding producers with captive bauxite processing in Brazil and Guinea. Buyers in European foundries absorb REACH-driven reformulation costs through premium pricing for ultra-low-cement grades, while Indian steel mills negotiate volume discounts on dense castables for blast furnace rebuilds.
Pricing Analysis
Short lead-time premiums dominate spot procurement for dense castables in China's Hebei province, where MEE-mandated rebuild cycles compress vessel turnaround windows. Three-tier pricing structure across premium, standard, and economy levels reflects CaO content gradation and certification tier. Cost compression in conventional grades intensifies because Brazilian bauxite export bottlenecks elevate aggregate input costs. Mini-mill procurement teams exhibit highest price sensitivity; aerospace foundry buyers prioritize dimensional tolerance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from POSCO-affiliated mills and Tata Steel European operations force qualification of at least two ultra-low-cement suppliers per plant. Geographic supply concentrates in China, Brazil, and India for calcined bauxite and fused alumina aggregates. Raw material dependencies rest on Guinean bauxite, Chinese fused magnesia, and synthetic spinel precursors. Single-source vulnerability from Chinese environmental shutdowns disrupts magnesia availability unpredictably. Distribution runs through direct sales agreements with integrated steel producers and regional distributors serving fragmented foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cement castables constitute a vertical-integration race where control over magnesia and bauxite feedstocks determines margin stability under carbon border compliance costs. Players are pursuing backward integration into refractory mineral mining and processing assets.
For Market Incumbents: Acquire captive magnesia fusion capacity in Liaoning province or Brazilian bauxite processing infrastructure. Consolidate formulation IP around chromite-free spinel systems before REACH Annex XVII deadlines eliminate competitors with legacy inventories. Defend against specialized applicators disintermediating full-service contracts by embedding installation robotics capabilities. For New Entrants and Emerging Players: Begin with Indonesian nickel smelter greenfield projects in Morowali Industrial Park, where unmet demand for spinel-forming castables outstrips established supply relationships. Target Southeast Asian pyrometallurgical installations with technical service bundling that incumbent distributors cannot match. White-space exists in digital gunning robotics integration for precision thickness control. For Investors and Strategic Acquirers: The window for entry favors mid-tier formulation specialists with proven ultra-low-cement chemistry and regional distributor networks. Long-term viability hinges on carbon accounting capabilities that satisfy EU CBAM documentation requirements. Watch for inflection when Indonesian nickel processing capacity triggers sustained import substitution in Asian dense castable demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Secures fused alumina supply continuity against Guinean export bottlenecks and Brazilian logistics constraints. |
| Chromite-Free Formulation Development | Anticipates REACH Annex XVII enforcement eliminating legacy binder chemistries from European foundry supply chains. |
| Digital Gunning Robotics Deployment | Converges with real-time thickness monitoring to compress steel mill maintenance windows below 48-hour targets. |
| Indonesian Greenfield Capacity Buildout | Captures unmet demand from nickel smelter rotary kiln construction in Sulawesi and Maluku provinces. |
| Installation Service Unbundling | Responds to procurement department trends at POSCO-affiliated mills separating material supply from applicator contracts. |
Research Methodology
Independent corroboration across refractory plant managers, steel mill procurement leads, foundry technical directors, and distribution channel partners underwrites the qualitative findings. Primary interviews with R&D directors at formulation specialists and maintenance supervisors at integrated steel producers combined with secondary validation from customs trade data, SEC filings of listed refractory manufacturers, and MEE enforcement disclosures. Bottom-up demand modeling triangulates against top-down industry association aggregates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include product type tier, end-use industry vertical, installation method, and regional production cluster. CAGRs derive from weighted average of historical replacement cycle compression and regulatory-driven specification upgrades. Forecast inputs incorporate blast furnace rebuild schedules in Hebei province and Indonesian nickel smelter commissioning timelines.
Underlying measurement precision varies by segment; steel end-use demand carries tighter precision than aerospace foundry applications due to consolidated customer concentration. Forecasts reflect assumptions around MEE enforcement continuity, REACH implementation timelines, and bauxite supply chain stability. Deviation in Chinese environmental policy stringency or Indonesian smelter construction pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Solid-Ion Conductors Market
Ceramics
Wollastonite Market
Ceramics
Active Calcium Silicate Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Industrial Ceramics Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
China Ceramic Market
Ceramics
Zirconia Ceramics Market
Ceramics
Advanced Ceramics Market
Ceramics
Stoneware Market
Ceramics
Potassium Feldspar Market
Ceramics
Titanates Market
Ceramics
Ceramic Pigments Market
Ceramics
Mexico Ceramic Tiles Market