
 UAE Ceramic Tiles Market | 2026-2036
UAE Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Ceramic Tiles Market Analytics
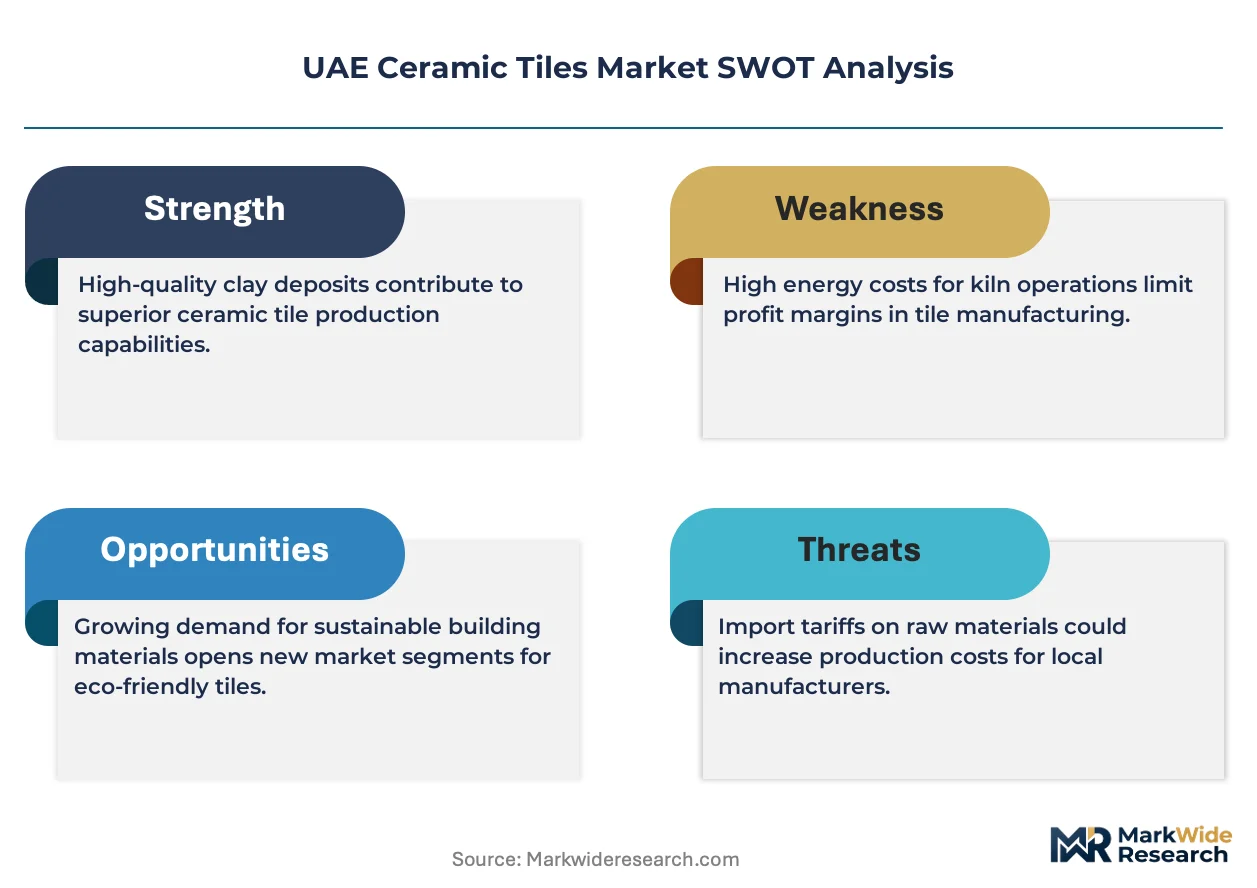
MOHAP building material safety standards is restructuring compliance costs for new entrants while elevating quality benchmarks across the UAE. RAK Ceramics leverages integrated manufacturing from raw material extraction through distribution to sustain margin control across the Gulf. Emirates Ceramics anchors its position through showroom density in Dubai and Sharjah trade corridors. Al Anwar Ceramic specializes in high-volume porcelain production for government infrastructure tenders.
UAE ceramic tiles are flat, thin slabs formed from clay, silica, and flux minerals, fired at temperatures between 1,000°C and 1,400°C to achieve specified water absorption rates below 0.5% for porcelain grades. These materials provide durable, chemically resistant surfaces for interior and exterior architectural applications. Porcelain commands the dominant value share due to its density and through-body color consistency demanded in commercial specifications. Flooring applications generate the largest volume pull from residential tower developments across Dubai's outer districts. Wall cladding in hospitality and retail fit-outs represents the fastest-expanding application segment as developers prioritize aesthetic differentiation.
BIS alignment requirements for imported tiles and Emirates Authority for Standardization and Metrology (ESMA) quality mark enforcement shape product entry protocols and testing expenditure for overseas suppliers. Dubai Municipality green building regulations and Abu Dhabi Quality and Conformity Council (QCC) specifications further segment compliance obligations by emirate. Stakeholders must monitor evolving sustainability mandates and local content thresholds that will determine supplier eligibility for federal project pipelines.
Market Dynamics
MOHAP's escalating building material safety standards are compressing supplier margins while consolidating procurement authority among certified manufacturers with captive testing infrastructure.
Growth Catalysts
- Dubai mega-project pipeline:Downtown Dubai to Dubai South corridor generates sustained specification-grade tile demand from hospitality and residential tower developments.
- ESMA quality mark enforcement:Mandatory third-party testing for imported tiles elevates compliance barriers that favor established domestic producers with in-house certification capabilities.
- Porcelain through-body technology:Superior density and color consistency specifications from commercial architects are displacing glazed ceramic in high-traffic flooring applications.
Market Restraints
- Feldspar and kaolin import dependency:Raw material sourcing concentrates in specific overseas jurisdictions, exposing margins to freight volatility and currency fluctuation.
- Natural stone substitution:Travertine and marble alternatives retain preference in ultra-premium hospitality lobbies where tactile authenticity commands specification priority.
- Abu Dhabi QCC divergent standards:Emirate-specific testing protocols force dual certification expenditure for suppliers serving both Dubai and Abu Dhabi project pipelines.
Strategic Opportunities
- Al Ain and Northern Emirates penetration:Sharjah and Ras Al Khaimah construction permits are accelerating faster than Dubai saturation, opening distribution whitespace for early movers.
- Dubai Municipality green building integration:Sustainability scoring mandates for new developments create specification pathways for low-carbon certified tile products.
- Digital specification platforms:BIM-integrated material libraries are compressing architect decision cycles and enabling direct manufacturer-to-designer engagement bypassing traditional distributor intermediation.
Industry Challenges
- MOHAP certification timeline compression:Accelerated product approval windows strain testing laboratory capacity and delay project mobilization schedules.
- Kiln energy transition capex:Natural gas-to-electric firing conversion requirements demand substantial furnace retrofit investment with uncertain payback periods.
- Legacy distributor inventory integration:Showroom-level stock-keeping unit proliferation complicates real-time availability synchronization with project scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Ceramic Tiles Market |
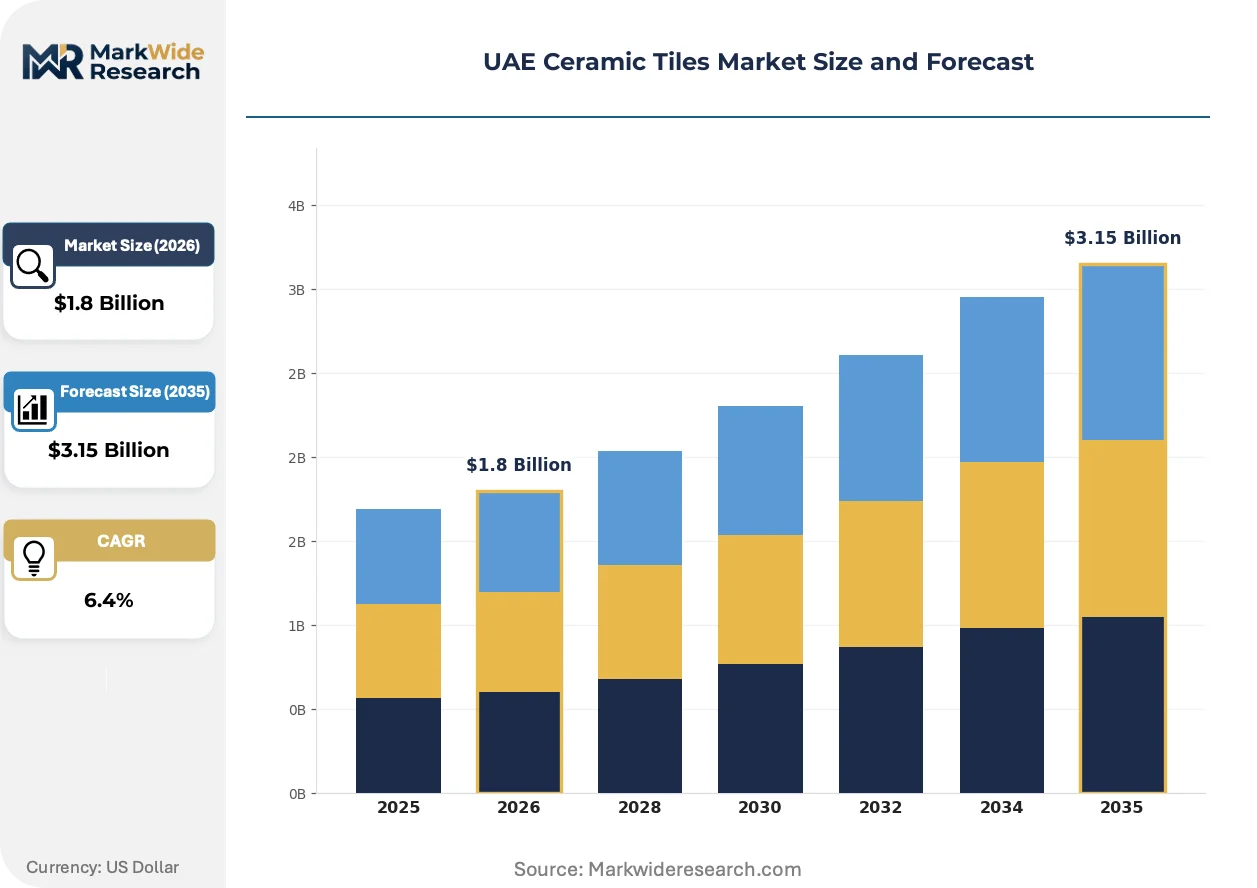
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Non-Glazed, Porcelain, Stoneware End User: Residential, Commercial, Industrial, Outdoor Application: Flooring, Wall Cladding, Countertops, Backsplashes Distribution Channel: Online Retail, Showrooms, Wholesale, Direct Sales |
| Companies Covered | Al Anwar Ceramic, Emirates Ceramics, RAK Ceramics, Abu Dhabi National Tiles, Future Ceramic, Al Khaleej Ceramics, Al Maha Ceramics, Sanipex Group, Porcellan Co. LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Ceramic Tiles Market Evolving Landscape
Digital manufacturing integration and regulatory sustainability mandates are compressing traditional production cycles while enabling mass-customization capabilities previously confined to artisan workshops.
Large-format sintered stone technology is converging with traditional porcelain manufacturing, enabling slab dimensions exceeding 1600x3200mm that eliminate grout lines in luxury hospitality fit-outs. Dubai-based specification consultants are specifying these surfaces for seamless reception desk and wall cladding applications. The structural consequence is compressing demand for traditional cut-to-size stone fabrication and shifting margin capture toward tile manufacturers with continuous pressing lines.
MOHAP's 2024 building material safety protocol amendments have introduced mandatory heavy metal leaching tests for all interior-grade ceramic surfaces. Manufacturers must now submit batch-level test reports rather than annual type-approvals. Small-format wall tile imports from non-GCC origins face the steepest compliance cost escalation as testing expenditure disproportionately impacts lower-value shipment economics.
Architects and interior designers are consolidating specification authority through centralized procurement platforms that aggregate volume across multiple concurrent projects. Traditional distributor relationships are fragmentating as developer procurement teams negotiate direct manufacturer agreements with project-specific pricing. This concentration is most visible in Dubai's hospitality sector where Emaar and Aldar development arms have established preferred supplier frameworks with volume commitment thresholds.
UAE Ceramic Tiles Market Segmentation
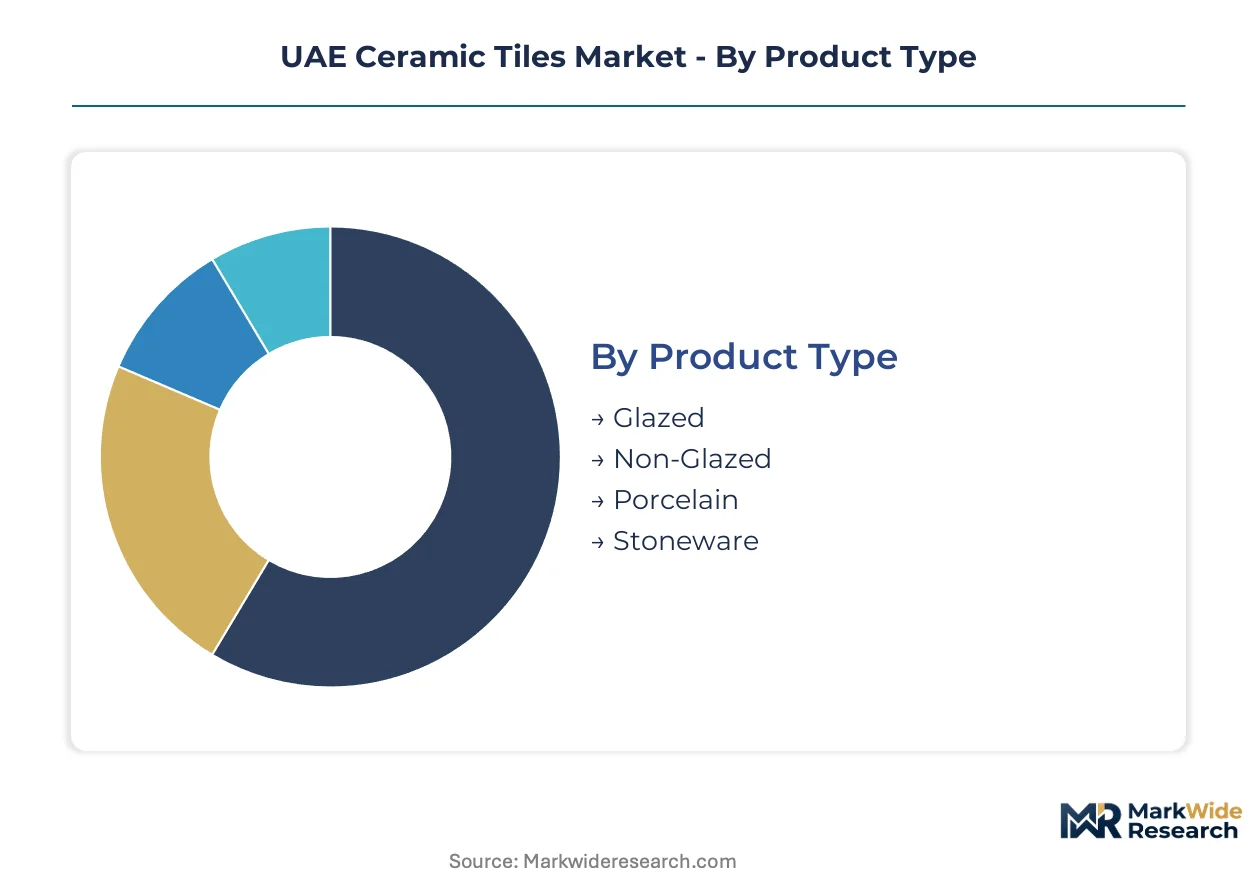
UAE ceramic tile procurement diverges sharply across project types, with hospitality developers demanding through-body porcelain while residential towers prioritize cost-optimized glazed alternatives. Specification authority concentrates with architects and procurement platforms, compressing traditional distributor influence. Understanding segment boundaries reveals where margin capture shifts between manufacturers, intermediaries, and direct channels.
Product Type:
Integration depth separates porcelain and stoneware, which embed structural performance specifications into material chemistry, from surface-dependent glazed and non-glazed alternatives whose durability relies on applied coatings.
- Glazed:Clay body coated with glass-forming minerals fired at lower temperatures, creating decorative surfaces with moderate abrasion resistance. Demand concentrates in Dubai's outer residential districts where budget-conscious developers specify glazed ceramic for apartment flooring in mid-market towers. MOHAP's heavy metal leaching mandates have escalated testing costs disproportionately for this lower-value category.
- Porcelain:Fired above 1,200°C at densities below 0.5% water absorption, achieving through-body color consistency and frost resistance. Dubai's luxury hospitality corridor from Downtown to Dubai South specifies porcelain for high-traffic lobbies and seamless reception desks where structural integrity commands premium positioning.
- Non-Glazed:Unglazed clay surfaces rely on natural vitrification for durability, common in industrial and exterior applications. RAK Ceramics and Emirates Ceramics dominate this segment through captive quarry access.
- Stoneware:Intermediate density between earthenware and porcelain, offering moisture resistance at moderate cost. Specified for covered outdoor terraces in Abu Dhabi residential compounds.
Porcelain leads volumes today; glazed alternatives are gaining share fastest in Sharjah and Northern Emirates cost-sensitive developments.
End User:
Cost tier stratification separates institutional procurement with extended payment terms from residential cash-flow dynamics and industrial maintenance cycles.
- Residential:Individual homeowners and developer bulk purchases for apartment fit-outs. Dubai South and Al Ain construction permits are accelerating residential tower completions, pulling standard-format glazed and porcelain volumes through showroom networks.
- Commercial:Hospitality, retail, and office fit-outs with architect-led specification. Wall cladding in Dubai's luxury hotel pipeline represents the fastest-expanding demand pool as Emaar and Aldar procurement teams negotiate direct manufacturer frameworks.
- Industrial:Manufacturing facilities and warehouses requiring chemical-resistant, heavy-load flooring. Non-glazed and stoneware grades dominate this specification tier.
- Outdoor:Exterior paving, pool decks, and facade applications exposed to thermal cycling and salt air. Through-body porcelain commands this segment due to frost resistance requirements in Abu Dhabi and Dubai coastal zones.
Commercial applications generate the highest value per square meter; residential drives aggregate volume tonnage.
Application:
Volume concentration separates flooring as the dominant surface area from wall cladding's accelerating specification complexity and countertop niche positioning.
- Flooring:Largest surface area application across all end-use categories. Dubai's residential tower pipeline specifies porcelain for high-traffic common areas and glazed ceramic for apartment interiors.
- Wall Cladding:Vertical surfaces in hospitality lobbies, retail facades, and feature walls. Large-format sintered stone technology exceeding 1600x3200mm is displacing traditional cut-to-size stone in luxury fit-outs.
- Countertops:Kitchen and vanity surfaces requiring stain and scratch resistance. Porcelain slab formats are penetrating this segment previously dominated by natural stone and engineered quartz.
- Backsplashes:Small-format decorative wall tiles in residential kitchens and bathrooms. Imports from non-GCC origins face steepest MOHAP compliance cost escalation due to batch-level testing requirements.
Flooring maintains volume leadership; wall cladding demonstrates the steepest expansion trajectory among specification-grade applications.
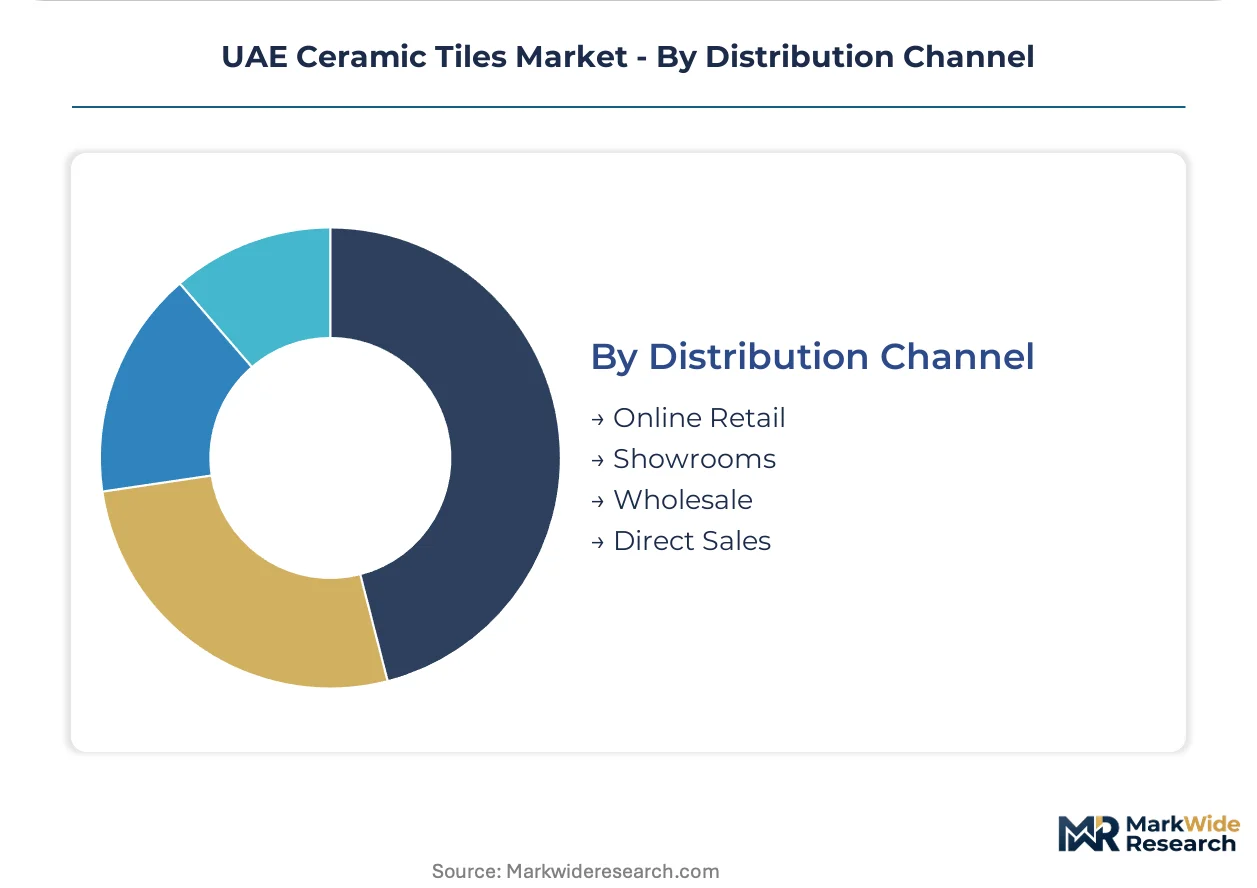
Distribution Channel:
Customer type fragmentation separates project-direct procurement from retail walk-in traffic and wholesale inventory aggregation.
- Showrooms:Physical display spaces where architects and homeowners evaluate material samples. Emirates Ceramics anchors market position through density in Dubai and Sharjah trade corridors.
- Direct Sales:Manufacturer-to-developer agreements bypassing distributor markup. Emaar and Aldar hospitality procurement teams have established preferred supplier frameworks with volume commitment thresholds.
- Wholesale:Inventory aggregation for contractor and retailer resale. Legacy distributor networks face pressure from real-time availability demands in project scheduling software.
- Online Retail:Digital catalog and specification platforms. BIM-integrated material libraries are compressing architect decision cycles and enabling manufacturer-to-designer engagement.
Showrooms retain specification influence for complex projects; direct sales channels are expanding most quickly among mega-project developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled ceramic engineering talent concentrates in Ras Al Khaimah's industrial corridor and Dubai's specification consulting clusters, anchoring production and design authority for Gulf-wide distribution.
Dubai
Downtown Dubai to Dubai South mega-projects drive specification-grade porcelain demand for luxury hospitality fit-outs. Dubai Municipality green building regulations mandate sustainability scoring for new developments, compressing supplier qualification timelines. Jebel Ali industrial zone hosts captive testing infrastructure serving manufacturers seeking ESMA quality mark compliance.
Abu Dhabi
Aldar development pipelines and government infrastructure tenders pull high-volume porcelain and stoneware specifications. Abu Dhabi Quality and Conformity Council maintains divergent testing protocols from Dubai, forcing dual certification expenditure for multi-emirate suppliers. Khalifa Industrial Zone concentrates logistics capacity for Northern Emirates distribution.
Sharjah
Accelerating construction permits in mid-market residential towers outpace Dubai saturation, opening distribution whitespace for cost-optimized glazed ceramic. Sharjah trade corridors anchor showroom density for architect specification sampling. Industrial City Sharjah hosts secondary manufacturing capacity serving price-sensitive Northern Emirates demand.
Ras Al Khaimah
RAK Ceramics anchors integrated manufacturing from raw material extraction through distribution, leveraging captive quarry access for margin control. Saqr Port proximity reduces freight exposure for Gulf export volumes. Al Hamra and Mina Al Arab hospitality developments generate local specification pull for through-body porcelain.
Northern Emirates
Fujairah and Umm Al Quwain construction acceleration lags Dubai and Abu Dhabi, creating early-mover distribution opportunities. Federal infrastructure spending on east coast logistics corridors improves supply chain access. Al Ain residential permits accelerate demand for standard-format glazed tiles through wholesale channels.
UAE Ceramic Tiles Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive raw material access and in-house certification infrastructure. Three player archetypes dominate: vertically integrated producers controlling quarry-to-distribution pipelines, specification-focused specialists serving architect-led hospitality procurement, and volume-driven fabricators competing for government infrastructure tenders. Consolidation pressure intensifies as MOHAP compliance costs disproportionately burden smaller importers lacking batch-level testing capacity. Strategic moves center on showroom network expansion in secondary emirates and direct procurement framework negotiations with mega-project developers.
Among UAE-based integrated manufacturers, RAK Ceramics, Emirates Ceramics, and Al Anwar Ceramic exemplify distinct positioning archetypes. RAK Ceramics occupies the upstream-integrated position with captive raw material extraction. Emirates Ceramics anchors specification influence through trade corridor showroom density. Al Anwar Ceramic represents the volume-specialist archetype targeting government tender pipelines. Each structure reflects different margin defense strategies against escalating regulatory compliance and raw material import dependency.
| Leading Market Players |
|---|
| Al Anwar Ceramic |
| Emirates Ceramics |
| RAK Ceramics |
| Abu Dhabi National Tiles |
| Future Ceramic |
| Al Khaleej Ceramics |
| Al Maha Ceramics |
| Sanipex Group |
| Porcellan Co. LLC |
| Others |
Value Network & Pricing Analysis
Emaar and Aldar procurement teams concentrate volume commitment across Dubai's hospitality pipeline, anchoring project-based contract pricing with tiered performance specifications. This buyer concentration compresses spot-market liquidity and elevates negotiation leverage for certified domestic manufacturers with captive testing infrastructure.
Pricing Analysis
Project-based contract pricing dominates specification-grade porcelain, separating bundled certification-and-delivery packages from unbundled material-only transactions. Price differentiation hinges on MOHAP compliance tier and volume scale, with batch-level testing costs disproportionately burdening small-format imports. Cost compression in glazed ceramic intensifies because Sharjah and Northern Emirates developers prioritize economy specifications. Government infrastructure tenders exhibit highest price sensitivity; luxury hospitality procurement teams demonstrate lowest sensitivity to per-square-meter rates.
Supply Chain Analysis
Freight volatility from feldspar and kaolin origins in India, China, and Turkey exposes margin stability to Red Sea routing disruptions and currency fluctuation. UAE manufacturers draw from concentrated overseas jurisdictions for flux minerals, while captive quarry access in Ras Al Khaimah anchors domestic porcelain production. Single-source vulnerability concentrates in specialty glaze formulations from European suppliers. Distribution runs through manufacturer-direct frameworks for mega-projects, with showroom networks retaining influence for residential specification sampling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's 2024 building material safety protocol amendments compound procurement authority among certified manufacturers, accelerating consolidation pressure on import-dependent competitors. This regulatory milestone elevates compliance infrastructure to primary competitive differentiator.
For Market Incumbents: Deploy captive testing laboratory expansion to compress certification timelines and capture procurement authority from developers facing MOHAP approval bottlenecks. Defensive consolidation moves center on acquiring distributors with established showroom density in Sharjah and Northern Emirates corridors. Capacity addition in Al Ain addresses whitespace acceleration in federal infrastructure pipelines. For New Entrants and Emerging Players: Enter via digital specification platforms that bypass legacy distributor intermediation and enable direct architect engagement with BIM-integrated material libraries. White-space targets concentrate in Al Ain residential permits and Fujairah construction acceleration. The most penetrable segment is mid-market glazed ceramic for cost-sensitive Northern Emirates developers, approached through wholesale channel partnerships rather than showroom capital expenditure. For Investors and Strategic Acquirers: Building materials conglomerates with Gulf distribution footprints are the most active acquirer in this space, seeking certification-capable manufacturing assets. Long-term viability rests on regulatory compliance infrastructure as durable competitive moat. Acquisition target archetype: integrated manufacturers with captive raw material access and ESMA quality mark capabilities. The signal to watch is MOHAP protocol expansion to additional product categories, which would amplify compliance cost advantages for scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Extraction | Captive feldspar and kaolin supply in Ras Al Khaimah insulates margin control from freight volatility. |
| ESMA Quality Mark Certification Investment | In-house testing infrastructure compresses approval timelines and elevates barrier to import competition. |
| Showroom Network Expansion in Secondary Emirates | Sharjah and Al Ain trade corridor density captures architect specification authority ahead of saturation. |
| Direct Procurement Framework Negotiation | Manufacturer-to-developer agreements with Emaar and Aldar procurement teams displace distributor markup. |
| Digital Specification Platform Integration | BIM-embedded material libraries compress architect decision cycles and enable designer-direct engagement. |
Research Methodology
Direct dialogue with ceramic plant managers, procurement leads at Emaar and Aldar development arms, MOHAP certification officers, and Sharjah-based distributor principals grounded qualitative assessment. Secondary validation drew from ESMA quality mark registries, Dubai Municipality building permit databases, Ras Al Khaimah customs export records, and Abu Dhabi QCC testing protocols. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment were triangulated against trade flow data.
Bottom-up volume modeling tracked emirate-level construction permits by project type and specification tier, while top-down analysis validated against reported production capacity at integrated manufacturing facilities. Segmentation dimensions spanned product density grade, end-use vertical, application surface, and distribution channel structure. CAGRs were derived from demand elasticity to hospitality and residential completion schedules, with inputs from kiln energy transition capex cycles and raw material import dependency ratios.
Inputs from MOHAP protocol amendments and ESMA enforcement calendars were available through the study window; gaps in batch-level testing cost disclosure for non-GCC imports introduce uncertainty bands around compliance expenditure forecasts. Forecasts reflect assumptions regarding sustained mega-project pipeline velocity and stable regulatory enforcement intensity. A model refresh is warranted upon material change in MOHAP certification timeline compression or kiln fuel transition mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Technical Ceramics Market
Ceramics
High Temperature Ceramics Market
Ceramics
Zeolite 4A Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Cordierite Market
Ceramics
Kaolin Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Vaterite Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Stoneware Market
Ceramics
India Kaolin Market
Ceramics
Co-Fired Ceramic Market