
 Global Supplementary Cementitious Materials Market | 2026-2036
Global Supplementary Cementitious Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Supplementary Cementitious Materials Market Foresight
Calcined clay activation is tilting binder formulation away from pure Portland cement toward ternary and quaternary blends. Heidelberg Materials AG anchors European supply through integrated calcined clay production at its Belgian and German kilns. Charah Solutions Inc. leverages its North American fly ash beneficiation network to sustain utility-derived material flows as coal retirements accelerate. Sika AG competes through admixture-SCM compatibility systems that extend contractor flexibility across varying regional cement qualities.
Supplementary cementitious materials are pozzolanic or hydraulic mineral additives—typically fly ash, ground granulated blast-furnace slag, silica fume, or metakaolin—that partially replace Portland cement clinker to enhance concrete durability, reduce permeability, and lower embodied carbon. These materials react with calcium hydroxide during hydration to form additional calcium silicate hydrate, improving long-term strength and chemical resistance. Slag cement dominates volume globally due to steel industry coproduction economics and established standards acceptance, while metakaolin commands premium positioning in marine and chemically aggressive exposure classes where porosity reduction justifies higher unit costs. Fly ash faces structural supply pressure from coal plant closures in North America and Europe, though beneficiation technologies are reopening previously landfilled inventories as specification-grade material.
The US EPA coal ash regulations, EU REACH framework for construction product constituents, and India's BIS IS 3812 fly ash standards collectively shape material qualification pathways and cross-border trade eligibility. China's GB standards for mineral admixtures and MEE enforcement of industrial waste utilization quotas further constrain how producers source and classify SCM outputs. Stakeholders must monitor calcined clay capacity buildouts, slag availability tied to electric arc furnace steel transitions, and evolving prescriptive versus performance-based concrete standards that determine which materials gain specification traction in priority markets.
Market Dynamics
The Global Supplementary Cementitious Materials Market is being fundamentally restructured by the EU Green Deal's embodied carbon thresholds, which are forcing specification decisions away from pure Portland cement toward lower-clinker binders. Steel industry transitions to electric arc furnace production are simultaneously reshaping slag availability curves across major producing regions.
Growth Catalysts
- EU Green Deal thresholds:The EU Green Deal's embodied carbon mandates are redirecting infrastructure procurement toward ternary and quaternary cement blends that incorporate fly ash, slag, and calcined clay.
- India's western corridor buildout:Megaprojects along the Mumbai-Ahmedabad corridor are concentrating bulk demand for fly ash and silica fume in Gujarat and Maharashtra states.
- Calcined clay activation:Kiln retrofitting for clay calcination is enabling cement producers to formulate high-performance binders with 40-50% clinker reduction.
Market Restraints
- Coal plant retirement curves:Accelerated coal retirements in North America and Europe are structurally compressing fly ash supply pools and forcing reliance on beneficiated landfill stocks.
- Slag availability fragmentation:Steel production shifts toward electric arc furnace routes in Germany and Japan are reducing blast furnace slag coproduction volumes.
- Metakaolin cost premiums:High-purity kaolin feedstock requirements and energy-intensive calcination keep metakaolin prices 3-4x above standard SCM benchmarks.
Strategic Opportunities
- Vietnam infrastructure pipeline:National green building code adoption and expressway construction are opening specification pathways for imported slag and locally sourced pozzolans.
- Beneficiation technology diffusion:Charah Solutions' North American fly ash beneficiation model is replicable for reopening landfilled ash inventories in Poland and the Czech Republic.
- Admixture-SCM convergence:Compatibility systems linking superplasticizers with variable SCM chemistries are creating new value capture for chemical suppliers.
Industry Challenges
- Performance-based standards transition:Moving from prescriptive clinker-content limits to performance-based concrete specifications requires extensive testing protocols and contractor retraining.
- Supply chain reconfiguration:Sourcing calcined clay from Belgium and Germany while securing slag from integrated steel complexes demands multi-origin logistics coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Supplementary Cementitious Materials Market |
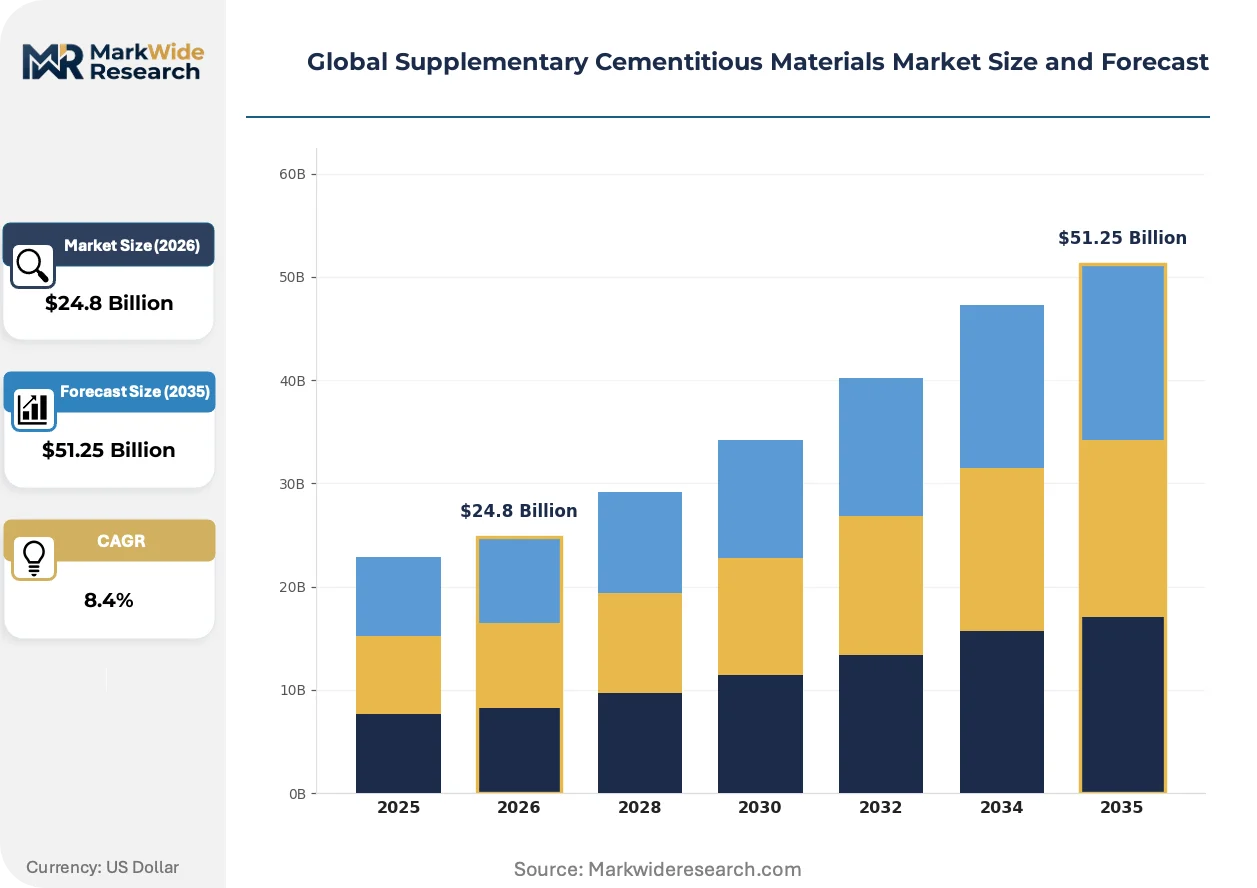
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
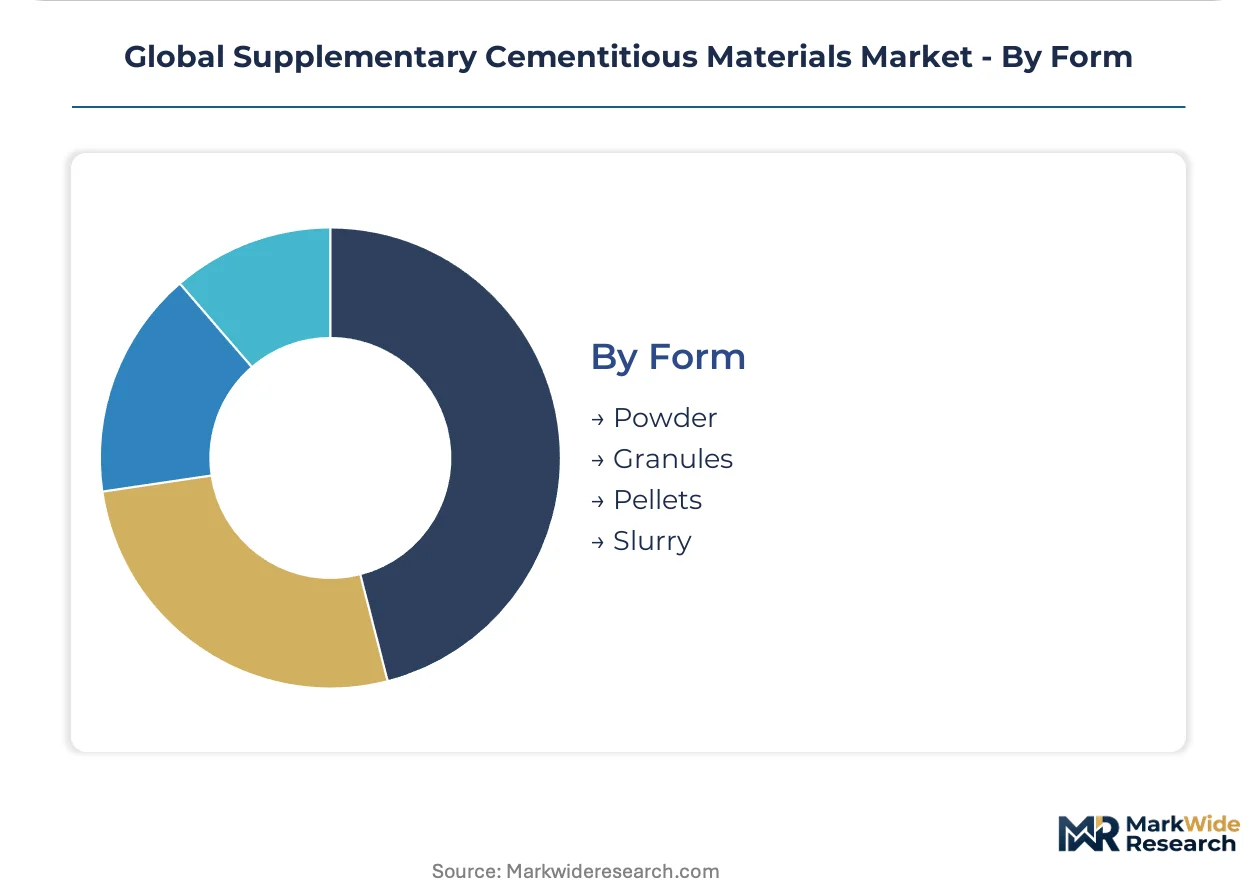
| Segmentation | Material Type: Fly Ash, Slag Cement, Silica Fume, Rice Husk Ash, Metakaolin Application: Concrete, Mortar, Grouts, Precast Products, Oil Well Cementing End User: Construction Companies, Infrastructure Developers, Ready-Mix Producers, Precast Manufacturers Form: Powder, Granules, Pellets, Slurry |
| Companies Covered | BASF SE, Sika AG, Holcim Ltd., ArcelorMittal SA, Tata Steel Ltd., Heidelberg Materials AG, CRH Plc, Charah Solutions Inc., CEMEX SAB de CV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Supplementary Cementitious Materials Market Shifts & Advancements
Digital formulation platforms are compressing the trial-and-error cycle for SCM blend optimization, while regulatory carbon accounting is embedding itself into procurement specifications. These forces are converging to reward suppliers with integrated material-testing capabilities.
LC3 (Limestone Calcined Clay Cement) technology is virtualizing traditional binder formulation by enabling clinker factors below 50% without strength penalties. European cement majors are deploying LC3 across Belgian and German production lines. This technology is virtualizing the competitive landscape by decoupling cement performance from clinker intensity.
REACH framework amendments for construction product constituents are tightening traceability requirements for SCM imports into EU member states. Industrial users must now document supply chain carbon intensity and chemical composition across batch records. Marine exposure class specifications in the Netherlands and Denmark are responding fastest, with port infrastructure projects mandating EPD-verified SCM content.
Contractor procurement patterns are consolidating around pre-blended binder systems rather than site-dosed SCM additions. Ready-mix operators in Southeast Asia are shifting toward mill-certified ternary blends that guarantee consistent performance. This behavioral shift is most visible in Thailand and Indonesia, where national infrastructure agencies have standardized on pre-qualified supplier lists for major highway and rail contracts.
Global Supplementary Cementitious Materials Market Segmentation
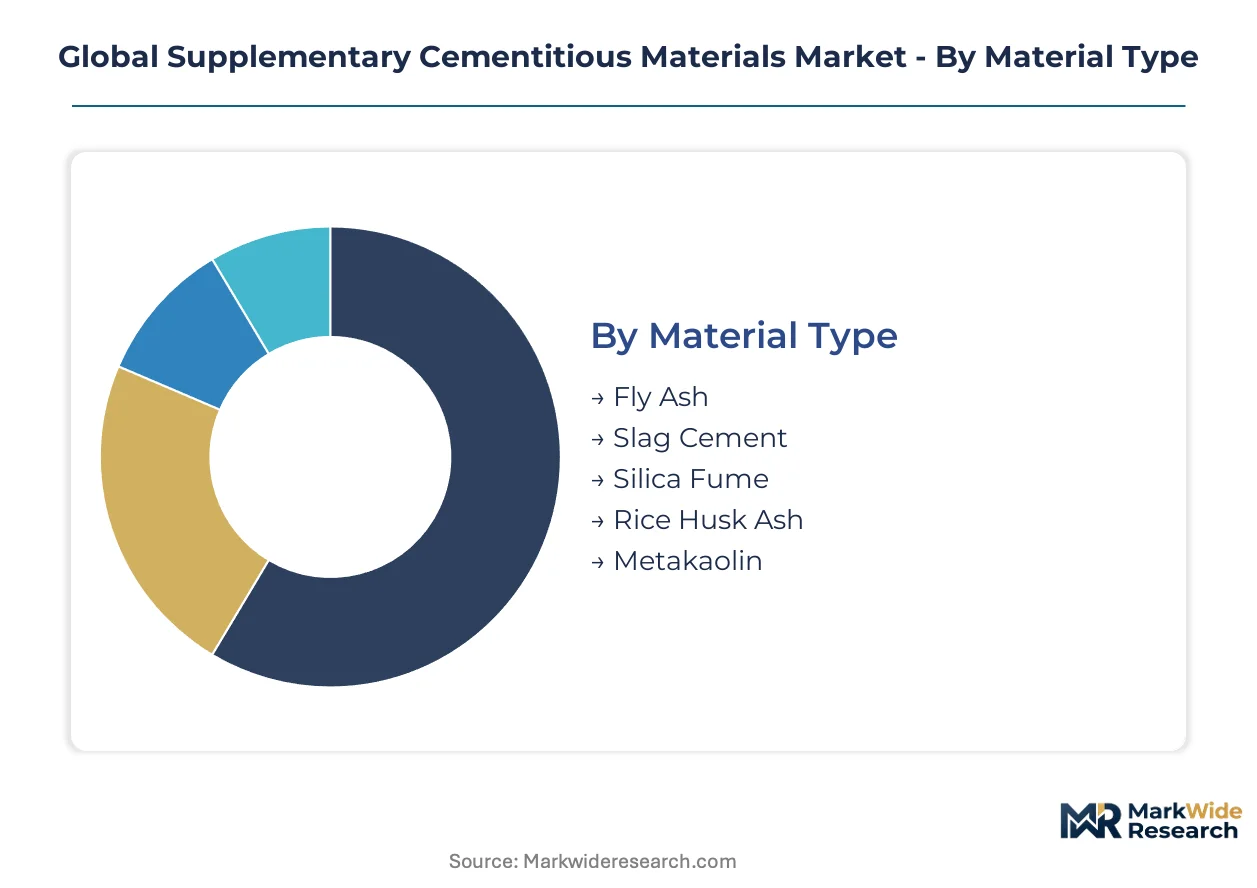
SCM procurement patterns diverge sharply across material chemistries, construction applications, and supply chain configurations. Specification-grade requirements and regional availability constraints create distinct competitive arenas within each segment dimension.
Material Type:
Mature industrial coproducts dominate volume positions while engineered alternatives capture premium specification niches.
- Fly Ash:Coal combustion residue classified by LOI and fineness under ASTM C618 and EN 450 standards. Western Indian megaprojects along the Mumbai-Ahmedabad corridor consume bulk volumes as BIS IS 3812 compliance tightens beneficiation requirements.
- Slag Cement:Ground granulated blast-furnace slag activated by calcium hydroxide to form supplementary C-S-H phases. German and Japanese steel industry transitions to electric arc furnace routes are structurally compressing blast furnace slag availability curves.
- Silica Fume:Amorphous silicon dioxide from ferrosilicon smelting with extreme surface area enabling ultra-low permeability concrete. Norwegian and Icelandic hydroelectric projects specify silica fume for chloride exposure resistance.
- Rice Husk Ash:Agricultural residue combustion yielding high-reactivity pozzolan with cellular silica structure. Vietnamese and Thai infrastructure agencies are qualifying domestic RHA for green building code compliance.
- Metakaolin:Dehydroxylated kaolin clay requiring 700-850°C calcination temperatures and premium feedstock purity. North Sea offshore platforms and Dutch marine infrastructure absorb metakaolin volumes despite 3-4x cost premiums over standard SCM benchmarks.
Slag cement retains volume leadership; metakaolin holds the steepest expansion curve.
Application:
Specification intensity varies directly with exposure class severity and structural performance requirements.
- Concrete:Mass placement and structural elements incorporating SCMs for heat-of-hydration control and long-term strength gain. EU Green Deal embodied carbon thresholds are redirecting public procurement toward ternary and quaternary blends in Belgium, Germany, and the Netherlands.
- Mortar:Bedding and rendering applications requiring workability retention and sulfate resistance. Heritage restoration projects in Italy and Spain specify natural pozzolan-lime mortars under conservation protocols.
- Grouts:High-fluidity cementitious systems for void filling and ground improvement. Singapore and Hong Kong tunneling contractors demand silica fume-enhanced grouts for seawater exposure.
- Precast Products:Factory-controlled curing enabling aggressive SCM substitution without field variability risks. Thai and Indonesian ready-mix operators are consolidating procurement around mill-certified ternary blends for highway and rail contracts.
- Oil Well Cementing:Geothermal and deep-well applications requiring CO2 resistance and thermal stability. North Sea and Gulf of Mexico operators specify API Class G cements with 35-50% SCM content for well integrity.
Concrete commands absolute volume; oil well cementing offers the highest value-per-tonne realization.
End User:
Procurement sophistication tracks project scale and specification authority concentration.
- Construction Companies:General contractors balancing material cost against warranty exposure and schedule risk. Large French and German construction groups are centralizing SCM procurement through corporate sustainability targets.
- Infrastructure Developers:State agencies and concessionaires with mandate-driven low-carbon procurement. India's National Highways Authority is embedding fly ash minimums into western corridor contract specifications.
- Ready-Mix Producers:Batch plant operators requiring consistent SCM supply for performance-guaranteed mixes. Southeast Asian ready-mix consolidation is shifting procurement toward pre-qualified supplier lists.
- Precast Manufacturers:Cured-product specialists exploiting controlled environments for high-SCM formulation. Belgian and German precasters are deploying LC3 technology for clinker factors below 50%.
Infrastructure developers drive specification standards; ready-mix producers intermediate the largest transaction volumes.
Form:
Physical state determines logistics economics and site handling requirements.
- Powder:Standard pulverized material requiring pneumatic transport and silo storage. Dry powder dominates European and North American bulk handling infrastructure.
- Granules:Agglomerated particles reducing dust emission and improving flow characteristics. Japanese slag processors granulate blast furnace output for maritime shipping efficiency.
- Pellets:Densified spheres enabling mechanical conveying without pneumatic systems. Pelletized fly ash serves remote Australian and Canadian construction sites lacking bulk infrastructure.
- Slurry:Pre-mixed aqueous suspensions eliminating dust exposure and enabling precise dosing. Slurry systems predominate in US Gulf Coast and UK coastal markets with waterway access.
Powder retains logistics dominance; slurry is gaining share fastest in coastal markets with barge delivery options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium exports calcined clay to Germany and the Netherlands as EU Green Deal procurement rules tighten. German infrastructure agencies specify LC3 blends for federal highway contracts. Indian fly ash moves westward to Gujarat and Maharashtra megaproject sites.
Belgium
Heidelberg Materials operates integrated calcined clay kilns serving Benelux and German markets. The EU Green Deal embodied carbon thresholds redirect public procurement toward lower-clinker binders. Antwerp-Rotterdam port clusters handle slag import logistics for coastal concrete plants.
Germany
Federal transport infrastructure contracts mandate EPD-verified SCM content for bridge and tunnel projects. REACH framework amendments tighten traceability for construction product constituents. North Rhine-Westphalia steel complexes supply blast furnace slag to Ruhr Valley precast manufacturers.
India
National Highways Authority specifications embed fly ash minimums into western corridor contracts. BIS IS 3812 standards tighten beneficiation requirements for specification-grade material. Gujarat and Maharashtra states concentrate bulk consumption along the Mumbai-Ahmedabad infrastructure belt.
Vietnam
National green building code adoption accelerates specification pathways for imported slag. Expressway construction under the Ministry of Transport drives pozzolan demand growth. Ho Chi Minh City and Hanoi metro projects qualify domestic rice husk ash for concrete procurement.
United States
EPA coal ash regulations shape material qualification pathways for beneficiated landfill inventories. Charah Solutions' processing network sustains utility-derived fly ash flows as coal retirements accelerate. Texas and Florida coastal markets deploy slurry systems for barge-delivered SCM logistics.
Global Supplementary Cementitious Materials Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Integrated cement majors dominate calcined clay and slag cement supply through captive kiln and steel coproduction assets. Chemical admixture suppliers capture value through compatibility systems that bridge variable SCM chemistries. Beneficiation specialists reopen landfilled material inventories as primary fly ash sources contract. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure multi-origin logistics networks.
Within the integrated cement tier, Heidelberg Materials AG and Holcim Ltd. exemplify producers with calcined clay kiln control and slag sourcing relationships. Sika AG occupies a position among chemical specialists linking superplasticizer formulations to SCM variability. Charah Solutions Inc. represents the beneficiation archetype, processing previously landfilled ash inventories as coal plant retirements compress primary supply pools.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Holcim Ltd. |
| ArcelorMittal SA |
| Tata Steel Ltd. |
| Heidelberg Materials AG |
| CRH Plc |
| Charah Solutions Inc. |
| CEMEX SAB de CV |
| Others |
Supply & Pricing Matrix
Antwerp-Rotterdam barge corridors carry calcined clay and slag cement across Benelux and German hinterlands, with freight cost differentials of 15-25% separating coastal plants from inland concrete batchers. This logistics gradient concentrates pricing power with integrated producers controlling kiln and port assets, while forcing smaller blenders to absorb transport premiums or cede specification-grade markets.
Pricing Analysis
Cost-plus contracts indexed to clinker and energy benchmarks dominate long-term offtake agreements between cement majors and infrastructure developers. Price differentiation rests on certification grade under EN 450 and BIS IS 3812 standards and on volume scale, with megaproject procurement securing 12-18% discounts over spot volumes. Cost compression in fly ash is intensifying as coal retirements force reliance on beneficiated landfill stocks with higher processing overhead. Ready-mix producers exhibit highest price sensitivity due to margin-thin operations, while oil well cementing contractors absorb premiums for metakaolin's performance guarantees.
Supply Chain Analysis
Contract manufacturing concentration sits with Heidelberg Materials' Belgian and German calcined clay kilns, Charah Solutions' North American beneficiation network, and integrated steel complexes in India and Japan for blast furnace slag. Geographic supply concentrates in Belgium, Germany, and India for specification-grade outputs. Raw material dependencies draw from kaolin deposits, coal combustion residues, and blast furnace coproduction. Single-source vulnerability runs through electric arc furnace transitions compressing slag availability. Distribution runs through mill-certified pre-blended systems rather than site-dosed additions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure developer consolidation along India's western corridor and Southeast Asian expressway programs is shifting procurement leverage toward buyers capable of multi-year volume commitments.
For Market Incumbents: Build captive calcined clay capacity as the defensive moat against slag supply erosion from steel industry decarbonization. Secure long-term kaolin feedstock agreements in Belgium and Germany. Add beneficiation lines in Poland and Czech Republic to reopen landfilled fly ash inventories before Charah Solutions replicates its North American model across EU markets. For New Entrants and Emerging Players: Build out rice husk ash processing in Vietnam and Thailand where agricultural residue streams meet green building code adoption. Target precast concrete manufacturers in Indonesia seeking EPD-verified SCM content for highway contracts. Lead with slurry logistics capabilities in coastal markets lacking pneumatic infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors beneficiation technology owners over raw material extractors as primary fly ash pools contract. Five-to-ten year viability rests on control of processing IP rather than mineral reserves. Watch for EU REACH enforcement actions on traceability documentation as the inflection signal separating compliant from excluded suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Kiln Retrofit | Heidelberg Materials' Belgian deployment enables 40-50% clinker reduction in LC3 blends. |
| Fly Ash Beneficiation Scale-Up | Charah Solutions' landfill processing model sustains utility-derived material flows amid coal retirements. |
| Admixture-SCM Compatibility Systems | Sika AG's superplasticizer formulations bridge variable regional cement chemistries for contractors. |
| Long-Term Slag Supply Agreement | ArcelorMittal and Tata Steel secure blast furnace output for precast manufacturers before EAF transitions. |
| EPD Certification Program | Holcim and CEMEX embed embodied carbon verification into EU Green Deal-compliant procurement. |
Research Methodology
A spread of perspectives from cement plant technical directors, ready-mix procurement managers, infrastructure agency specification engineers, and steel industry coproduct specialists converged on the working assumptions. Primary interviews combined with secondary validation against EU EPD databases, BIS certification registries, SEC filings from Heidelberg Materials and Holcim, and trade flow data from Eurostat and Indian customs. Bottom-up volume estimates triangulated against top-down cement consumption models.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry grade, application exposure class, end-user procurement sophistication, and physical form logistics configuration. CAGRs derived from curve-fitting historical substitution rates against regulatory threshold implementation timelines. Industry-specific inputs incorporated electric arc furnace transition schedules and coal plant retirement curves.
Stress conditions across slag availability compression, calcined clay kiln ramp delays, and REACH traceability enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on clinker factor reduction trajectories and green building code adoption rates. Cross-checking against IEA cement sector decarbonization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Barium Fluoride Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Jesmonite Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Fumed Silica Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market