
 Germany Ceramic Tiles Market | 2026-2036
Germany Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Ceramic Tiles Market Foresight
Buyer concentration among German housing cooperatives and institutional developers is consolidating procurement volumes toward fewer, larger contracts. Villeroy & Boch leverages its heritage brand equity and showroom network to anchor premium positioning in residential bathrooms. Deutsche Steinzeug Cremer & Breuer AG sustains manufacturing scale across multiple German production sites, competing on logistics responsiveness for commercial flooring projects. Porcelaingres GmbH specializes in large-format porcelain slabs, differentiating through technical performance in industrial and heavy-traffic applications.
Ceramic tiles are fired clay or porcelain slabs, typically measuring 300x300mm to 600x1200mm, with water absorption rates below 0.5% for porcelain grades, serving as surfacing materials for floors and walls across residential, commercial, and industrial environments. Porcelain commands the dominant share of value given its density and frost resistance, while glazed variants retain strong share in interior residential walls where aesthetic flexibility outweighs structural loading requirements. Modern and contemporary design styles are capturing incremental share as German architects specify minimal-joint installations and matte finishes for healthcare and hospitality interiors.
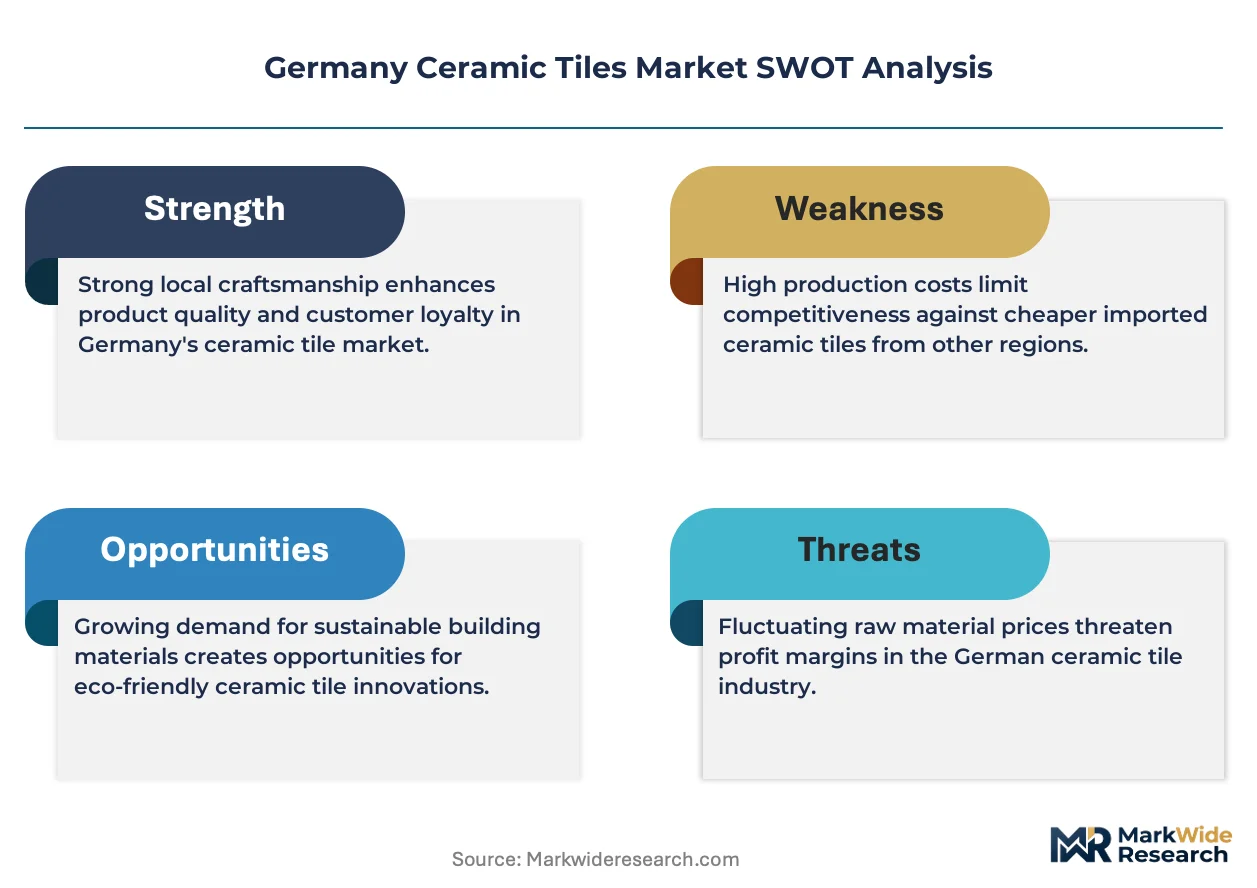
KBA building codes and DIN 51130 slip-resistance standards shape product certification requirements for commercial and public installations, while REACH compliance governs glaze chemistry and heavy-metal content in imported raw materials. The EU Green Deal's carbon border adjustments will intensify documentation burdens for non-European suppliers, advantaging domestic manufacturers with verified lifecycle data. Stakeholders must monitor how the EU AI Act's emerging requirements for automated quality inspection systems will reshape capital investment timelines and supplier qualification criteria.
Market Dynamics
EU Green Deal embodied carbon requirements are redirecting procurement toward German-manufactured ceramic products with verified lifecycle data, consolidating contract volumes among housing cooperatives with sustainability mandates.
Growth Catalysts
- Energy retrofit mandates:KBA building codes and DIN 51130 standards sustain replacement cycles across Bavaria and Baden-Württemberg's aging housing stock.
- REACH compliance advantage:Domestic manufacturers leverage verified glaze chemistry documentation to displace imports facing intensified EU carbon border adjustment burdens.
- Large-format porcelain technology:Technical performance specifications for heavy-traffic commercial flooring are expanding addressable project scale.
Market Restraints
- Natural gas price volatility:Kiln firing energy costs constrain margin flexibility for producers without captive renewable generation.
- Raw material import concentration:Kaolin and feldspar supply dependence on specific non-EU deposits creates documentation and pricing friction.
- Slip-resistance certification bottlenecks:DIN 51130 testing capacity limitations delay commercial project approvals.
Strategic Opportunities
- Healthcare specification expansion:Matte-finish minimal-joint installations are penetrating hospital and clinic renovation budgets.
- EU AI Act quality inspection:Automated defect detection systems create first-mover advantage for capital-ready domestic producers.
- Hospitality channel development:Design-direct relationships with boutique hotel developers bypass traditional distributor markups.
Industry Challenges
- Digital kiln control expertise:Talent scarcity in automated firing curve optimization constrains production yield improvements.
- Legacy ERP integration:Carbon accounting software deployment faces data architecture friction with established inventory systems.
- REACH documentation timelines:Heavy-metal content verification for imported raw materials extends procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Ceramic Tiles Market |
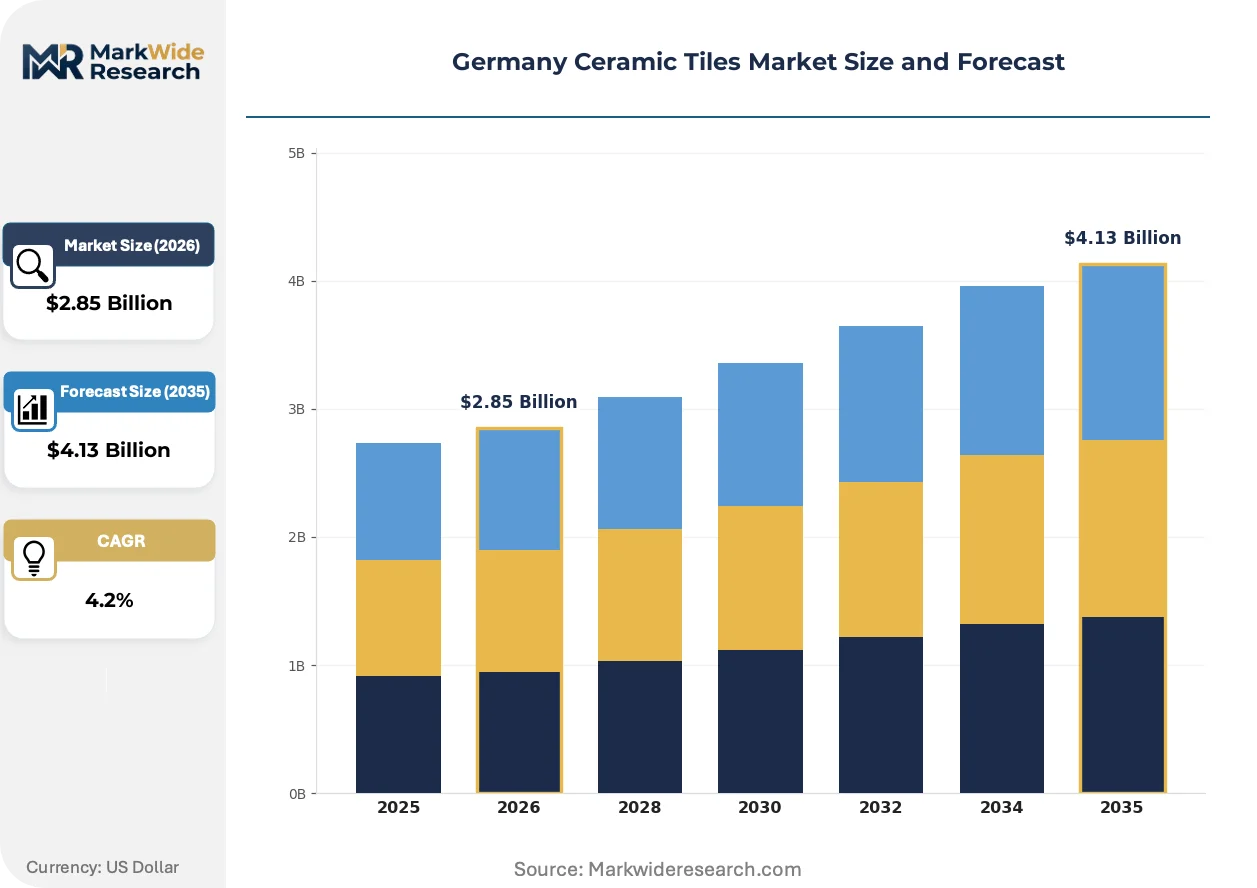
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Terracotta Application: Residential, Commercial, Industrial, Outdoor Distribution Channel: Online, Retail Stores, Showrooms, Wholesale Design Style: Traditional, Modern, Rustic, Contemporary |
| Companies Covered | Agrob Buchtal, Steuler Fliesen GmbH, Villeroy & Boch, Refratechnik Ceramics GmbH, Argelith, Deutsche Steinzeug Cremer & Breuer AG, Porcelaingres GmbH, Golem, Marazzi Group Germany, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Ceramic Tiles Market Shifts & Advancements
Digital specification tools and automated production systems are compressing design-to-installation timelines while elevating technical performance requirements for commercial-grade porcelain.
Large-format thin porcelain slabs is unifying floor and wall surfacing specifications into single-source contracts. Healthcare architects in Stuttgart and Munich are specifying 1600x3200mm formats at accelerating rates. This unifying product architecture is compressing contractor bid complexity and elevating technical performance barriers for smaller competitors.
EU Green Deal carbon border adjustments are restructuring import documentation requirements for non-European ceramic suppliers. German procurement officers now require embodied carbon declarations backed by third-party verification. Southern Germany's metropolitan housing cooperatives are screening suppliers most aggressively, redirecting volume toward domestic manufacturers with established Environmental Product Declarations.
Buyer concentration among institutional developers is consolidating specification authority into centralized sustainability teams. Traditional distributor relationships are fragmenting as large housing cooperatives establish direct manufacturer partnerships with certified carbon performance. This pattern concentrates most visibly in Bavaria's cooperative renovation programs, where procurement committees now mandate local manufacturing verification.
Germany Ceramic Tiles Market Segmentation
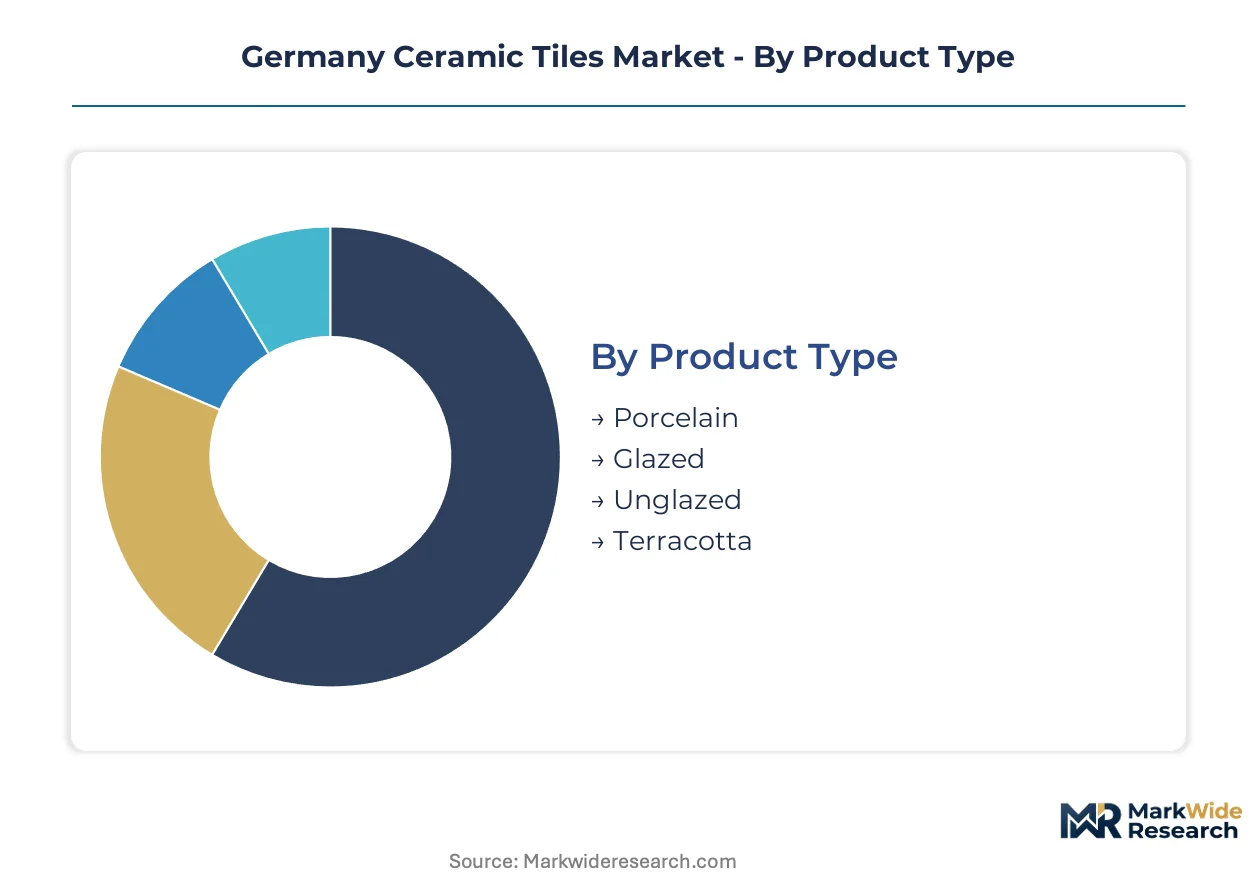
German ceramic tile procurement concentrates in distinct technical and aesthetic clusters that reshape competitive positioning. Specification authority flows through housing cooperatives and institutional developers who prioritize verified carbon performance alongside surface performance metrics.
Product Type:
Porcelain commands premium positioning through density and frost resistance, while glazed variants anchor volume through residential interior flexibility.
- Porcelain:Fired at higher temperatures with water absorption below 0.5%, delivering structural integrity for heavy-traffic commercial floors. Bavarian healthcare renovators specify 1600x3200mm formats for minimal-joint installations in Stuttgart and Munich hospital corridors, driven by DIN 51130 slip-resistance mandates and KBA energy retrofit timelines.
- Glazed:Surface-coated clay bodies offering aesthetic versatility through color and texture variation. Baden-Württemberg housing cooperatives favor glazed tiles for bathroom and kitchen renovations where moisture resistance requirements are moderate and budget constraints dominate procurement decisions.
- Unglazed:Dense, matte-finish surfaces specified for industrial flooring where mechanical abrasion resistance outweighs decorative considerations.
- Terracotta:Porous, low-fired clay products retaining traditional reddish-brown tones for heritage restoration and rustic residential applications.
Mature deployment sits with glazed tiles across residential renovation stock. Newer deployment is concentrated in large-format porcelain for healthcare and commercial specifications.
Application:
End-use concentration follows Germany's metropolitan corridor geography and regulatory enforcement intensity.
- Residential:Floor and wall surfacing across single-family homes, apartments, and cooperative housing units. Southern Germany's aging building stock in Bavaria and Baden-Württemberg sustains replacement cycles through KBA-mandated energy retrofits requiring interior finish updates alongside thermal envelope improvements.
- Commercial:Office, retail, hospitality, and public building installations where traffic loading and maintenance durability drive specification. Stuttgart and Munich architects specify matte-finish porcelain for boutique hotel developments, bypassing traditional distributor channels through design-direct manufacturer relationships.
- Industrial:Heavy-traffic manufacturing and warehouse floors requiring abrasion resistance and chemical spill tolerance.
- Outdoor:Frost-resistant pavers and facade cladding subject to DIN standards for weathering performance and slip resistance in public spaces.
Procurement volume concentrates in residential channels. Specification value is climbing fastest in commercial healthcare and hospitality segments.
Distribution Channel:
Channel structure is fragmenting as buyer concentration among housing cooperatives redirects volume away from traditional intermediaries.
- Online:Digital specification platforms and direct-to-contractor ordering systems compressing design-to-installation timelines for standardized product lines.
- Retail Stores:Big-box home improvement outlets serving DIY renovators and small-scale residential contractors with immediate inventory availability.
- Showrooms:Manufacturer-controlled display spaces where Villeroy & Boch leverages heritage brand equity to anchor premium bathroom specifications through tactile product experience.
- Wholesale:Distributor networks facing margin pressure as institutional developers consolidate procurement into direct manufacturer partnerships with verified Environmental Product Declarations.
Established volume flows through wholesale and retail infrastructure. Channel expansion is concentrating in showroom direct partnerships and digital specification tools.
Design Style:
Aesthetic preference is shifting toward surface minimalism that aligns with healthcare hygiene requirements and contemporary architectural vocabulary.
- Modern:Clean lines, neutral palettes, and large-format installations dominating Stuttgart and Munich commercial specifications where joint minimization supports infection control protocols.
- Contemporary:Evolving interpretations of minimalism incorporating textured surfaces and matte finishes for hospitality interiors seeking differentiated ambiance without ornate detailing.
- Traditional:Classic patterns and ornamental borders retaining share in heritage property restoration and conservative residential preferences.
- Rustic:Weathered textures and earthy tones for rural properties and farmhouse-style renovations in Bavaria's smaller municipalities.
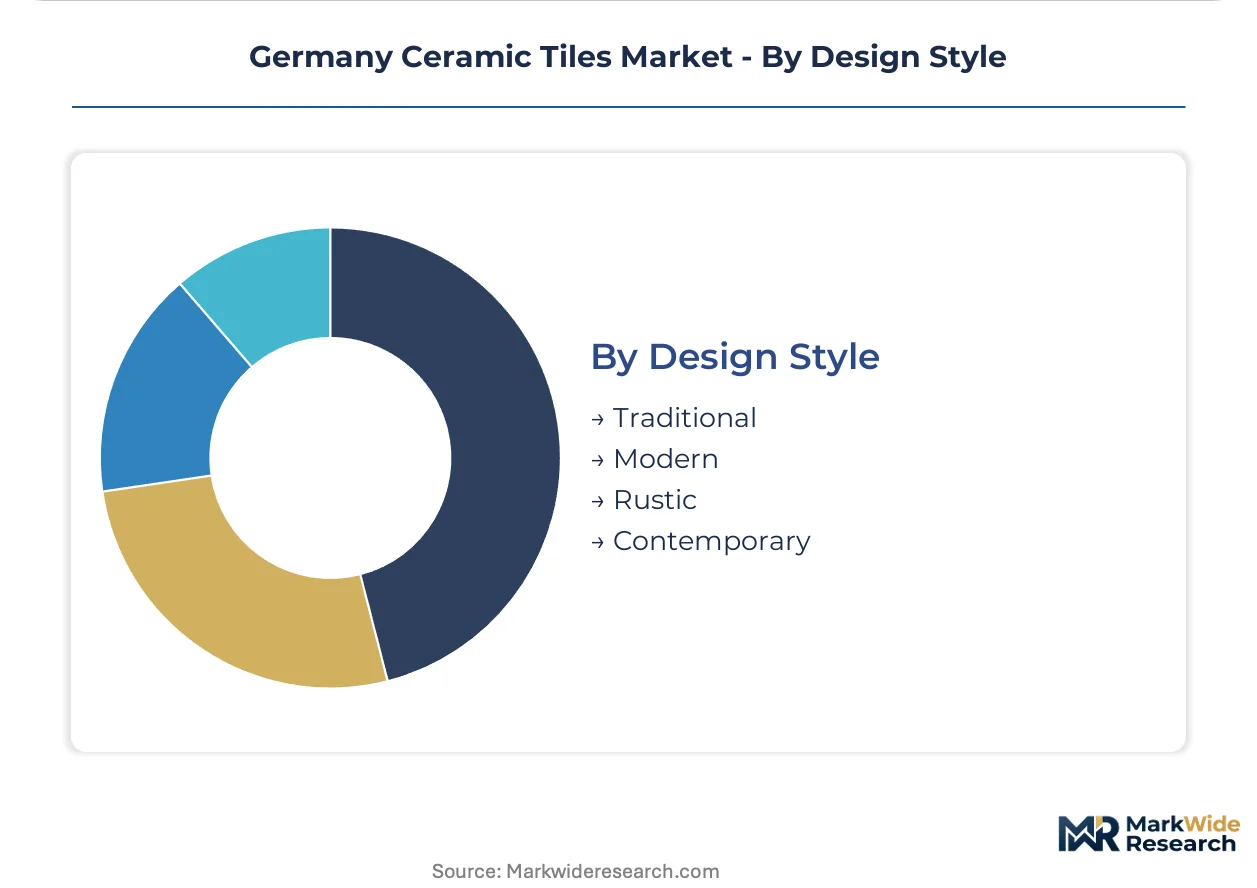
Traditional styling retains installed base across older housing stock. Contemporary and modern aesthetics are gaining specification share fastest in metropolitan commercial and healthcare projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among housing cooperatives and institutional developers is redirecting specification authority toward southern Germany's metropolitan corridors, where KBA energy retrofit mandates sustain replacement cycles across aging building stock.
Bavaria
Munich and Nuremberg housing cooperatives are consolidating renovation contracts into direct manufacturer partnerships with verified Environmental Product Declarations. KBA building codes mandate thermal envelope improvements that trigger interior finish updates. Stuttgart's healthcare architects specify 1600x3200mm porcelain formats for minimal-joint hospital corridor installations.
Baden-Württemberg
Stuttgart's boutique hotel developers are establishing design-direct relationships that bypass traditional distributor channels. DIN 51130 slip-resistance certification requirements shape commercial flooring specifications. Karlsruhe's institutional developers are screening suppliers most aggressively for EU Green Deal carbon performance verification.
North Rhine-Westphalia
Cologne and Düsseldorf commercial property managers prioritize logistics responsiveness for large-format porcelain in heavy-traffic retail environments. REACH compliance documentation governs glaze chemistry verification for imported raw materials. The Rhine-Ruhr industrial corridor sustains demand for abrasion-resistant unglazed tiles in manufacturing facilities.
Hesse
Frankfurt's financial district office renovations specify matte-finish porcelain for contemporary interior standards. The EU AI Act's emerging quality inspection requirements are reshaping capital investment timelines for regional distributors. Wiesbaden's public building procurement mandates local manufacturing verification for carbon border adjustment compliance.
Lower Saxony
Hanover's municipal housing authorities are consolidating procurement volumes toward fewer contracts with sustainability mandates. Natural gas price volatility constrains margin flexibility for producers without captive renewable generation. Braunschweig's industrial flooring contractors specify dense porcelain for chemical spill tolerance in warehouse applications.
Germany Ceramic Tiles Market Competitive Landscape
German producers anchor the premium tier with verified lifecycle data and showroom networks; Italian and Spanish specialists hold volume positions through logistics scale and design breadth. The vendor base clusters around heritage brand equity, manufacturing scale, and technical specialization archetypes. Consolidation pressures are intensifying as housing cooperatives consolidate procurement into direct partnerships. Competitive moves center on carbon certification documentation and automated quality inspection system deployment.
Within the heritage-brand tier, Villeroy & Boch occupies a position exemplifying premium bathroom specification authority through tactile showroom experiences. Deutsche Steinzeug Cremer & Breuer AG represents manufacturing-scale archetypes with multi-site German production and logistics responsiveness for commercial flooring. Porcelaingres GmbH exemplifies technical-specialist positioning in large-format porcelain slabs for heavy-traffic applications.
| Leading Market Players |
|---|
| Agrob Buchtal |
| Steuler Fliesen GmbH |
| Villeroy & Boch |
| Refratechnik Ceramics GmbH |
| Argelith |
| Deutsche Steinzeug Cremer & Breuer AG |
| Porcelaingres GmbH |
| Golem |
| Marazzi Group Germany |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EPD-verified domestic porcelain and import-dependent glazed ceramics manifests in both margin structures and procurement channel configurations across German housing cooperatives and institutional developers. Premium positioning rests on carbon border adjustment documentation while commodity tiers absorb logistics volatility from non-EU raw material dependencies.
Pricing Analysis
Volume-margins split sharply between large-format porcelain contracts and standard glazed residential tiles. Three-tier pricing structure across premium, standard, and economy levels reflects EPD certification status, DIN 51130 slip-resistance grading, and volume scale from housing cooperative procurement committees. Pricing pressure stems from natural gas kiln firing costs constraining producer flexibility. DIY retail channels exhibit highest price sensitivity while healthcare architects demonstrate lowest sensitivity given infection control mandates.
Supply Chain Analysis
Regional distribution centers in Bavaria and Baden-Württemberg operate hub-and-spoke patterns feeding Stuttgart and Munich metropolitan corridors. Manufacturing concentrates in Germany, Italy, and Spain with raw material dependencies on Ukrainian kaolin deposits, Turkish feldspar, and Nordic alumina. Single-source vulnerability sits with kaolin supply disruptions from eastern European extraction sites. Distribution runs through manufacturer-direct partnerships consolidating alongside traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German ceramic tile supply is tightening around verified carbon performance documentation, with DIN 51130 testing capacity bottlenecks propping pricing power for certified domestic producers.
For Market Incumbents: Hedge against import displacement by accelerating Environmental Product Declaration coverage across full product portfolios. Capture backward integration into captive renewable kiln energy generation to offset natural gas price volatility threatening margin sustainability. Deepen direct procurement relationships with Bavarian housing cooperatives before carbon border adjustments intensify documentation advantages. For New Entrants and Emerging Players: Boutique hotel developers represent the most penetrable channel partner type given design-direct specification authority bypassing established distributor markouts. Target healthcare renovation white-space in Stuttgart and Munich where 1600x3200mm porcelain formats face minimal-joint installation demand acceleration. Pursue digital specification platform partnerships as primary go-to-market angle compressing traditional showroom dependency. For Investors and Strategic Acquirers: Re-rating potential sits with technical-specialist manufacturers given EU AI Act quality inspection automation requirements reshaping capital deployment timelines. Long-term viability favors producers with multi-site German manufacturing footprints and established REACH glaze chemistry documentation. Monitor DIN 51130 testing capacity expansion announcements as inflection indicator for commercial project approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Program | EPD verification secures procurement preference from KBA-mandated housing cooperatives in Bavaria. |
| Automated Quality Inspection Deployment | EU AI Act compliance creates first-mover barrier against Italian and Spanish import competition. |
| Large-Format Capacity Expansion | 1600x3200mm porcelain production captures healthcare specification share in Stuttgart corridors. |
| Direct Channel Partnership | Design-direct relationships with boutique hotel developers eliminate wholesale margin extraction. |
| Renewable Energy Integration | Captive solar or biogas kiln supply hedges against natural gas price volatility eroding margins. |
Research Methodology
Trade association filings, customs import records, and building permit databases formed the secondary backbone validating market sizing assumptions. Primary interviews with procurement directors at housing cooperatives, technical specification architects, kiln operations managers, and distributor inventory planners combined with bottom-up production capacity tallies and top-down construction spending allocation models. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of ceramic tile consumption per housing unit renovation and commercial square meter completions informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, application end-use, distribution channel, and design style dimensions with regional regulatory cluster overlays. CAGRs derived from regression-adjusted growth rates applied to verified baseline consumption patterns, with EU Green Deal implementation timelines and KBA retrofit mandate enforcement intensity as key forecast inputs.
Several conditions sit outside the modeled scope, including potential REACH regulatory amendments affecting glaze chemistry thresholds and unanticipated natural gas supply disruptions altering kiln economics. Forecasts reflect documented assumptions regarding carbon border adjustment implementation pacing and housing cooperative procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
United States Ceramic Tiles Market
Ceramics
China Ceramic Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Glazed Bricks Market
Ceramics
Engineering Ceramics Market
Ceramics
Automotive Ceramics Market
Ceramics
Aragonite Market
Ceramics
Alumina Slurry Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Industrial Ceramics Market
Ceramics
Stoneware Market
Ceramics
Lithium Zirconate Market
Ceramics
Cement Castables Market
Ceramics
Activated Alumina Market
Ceramics
Ceramic Frit Market
Ceramics
Sodium Aluminum Silicate Market