
 Jib Crane Market | 2026-2036
Jib Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Jib Crane Market Analytics
Modular crane packages that bundle hoist, trolley, and control systems into single-SKU offerings is consolidating procurement decisions for mid-sized manufacturing plants. Konecranes leverages its aftermarket service network to capture recurring revenue from installed base maintenance. Gorbel specializes in ergonomic workstation crane configurations that reduce operator fatigue in repetitive assembly tasks. Columbus McKinnon Corporation anchors its position through vertical integration into hoist and rigging component manufacturing.
A jib crane is a type of overhead lifting device featuring a horizontal boom (jib) mounted to a vertical support, with load capacities typically spanning 0.5 to 10 tons and rotation arcs ranging from 180 to 360 degrees, designed for localized material handling within a defined work envelope. Floor-mounted articulating jib configurations dominate light-capacity applications where obstacle avoidance and precise load positioning matter most, while fixed jib variants sustain margin pools in heavy-process industries due to simpler mechanical construction and lower lifetime service requirements. Wall-mounted installations are gaining share in space-constrained warehousing environments where floor obstruction elimination carries operational value.
OSHA crane and derrick standards, ASME B30.2 overhead and gantry crane specifications, and ISO 4301-1 classification systems collectively shape product design, inspection protocols, and market access thresholds for equipment suppliers. Compliance documentation burdens favor established manufacturers with dedicated certification engineering staff over smaller fabricators. Stakeholders must monitor evolving state-level crane operator licensing requirements and assess whether regional inspection frequency changes will accelerate replacement cycles in aging installed bases.
Market Dynamics
OSHA crane inspection mandates and ASME B30 compliance requirements are compressing procurement timelines and disqualifying uncertified fabricators from specification lists across United States industrial corridors.
Growth Catalysts
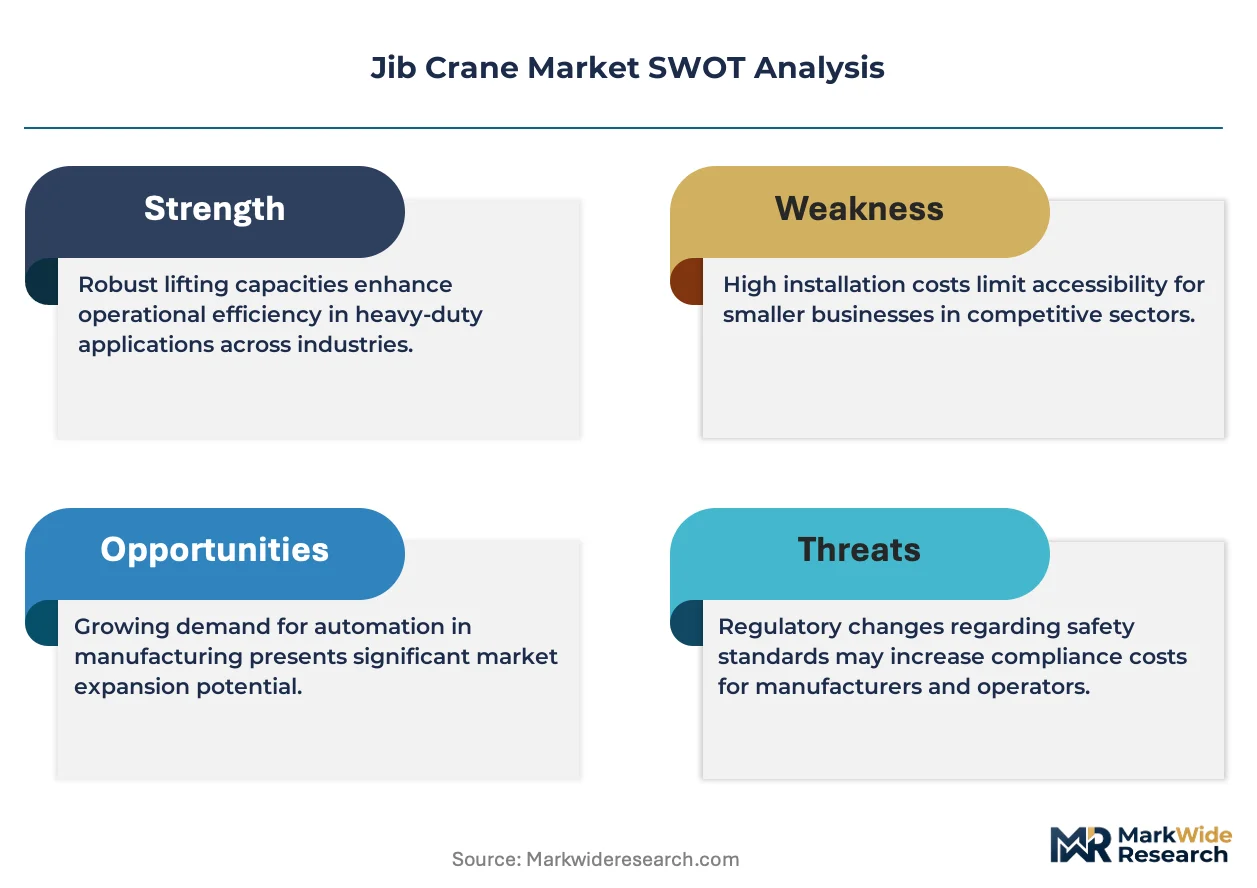
- OSHA 1910.179 Inspection Mandates:Aging installed bases in Gulf Coast petrochemical facilities require documented compliance, forcing replacement cycles and certified equipment specification.
- E-commerce Fulfillment Velocity:Warehousing operators in Great Lakes distribution hubs are expanding jib crane fleets to support same-day processing throughput.
- Articulating Jib Configurations:Floor-mounted pivot designs are displacing fixed gantries in light-capacity assembly cells where obstacle avoidance determines line efficiency.
Market Restraints
- Structural Steel Input Volatility:Boom and mast fabrication costs fluctuate with hot-rolled coil pricing, compressing margin pools for fixed-price contract manufacturers.
- Certification Documentation Burden:ASME B30.2 and ISO 4301-1 compliance engineering requirements favor established suppliers with dedicated staff, raising barriers for regional fabricators.
- Overhead Gantry Substitution:Bridge crane systems retain preference in heavy-process industries requiring 10+ ton capacities across extended bay spans.
Strategic Opportunities
- Workstation Ergonomics Integration:Force-sensing pendant controls and variable-frequency drive hoists are converging to reduce repetitive strain injury exposure in automotive assembly plants.
- Wall-Mounted Configuration Expansion:Space-constrained warehousing environments in urban logistics corridors are eliminating floor obstructions through cantilevered jib mounting.
- State-Level Operator Licensing:California and Washington crane certification requirements are creating specification pull for training-bundled equipment packages.
Industry Challenges
- Certified Inspector Talent Scarcity:OSHA-qualified crane inspectors are concentrated in legacy manufacturing belts, creating inspection backlogs in emerging logistics markets.
- Legacy Control System Integration:Variable-frequency drive retrofits on existing jib installations require electrical coordination with plant-wide automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jib Crane Market |
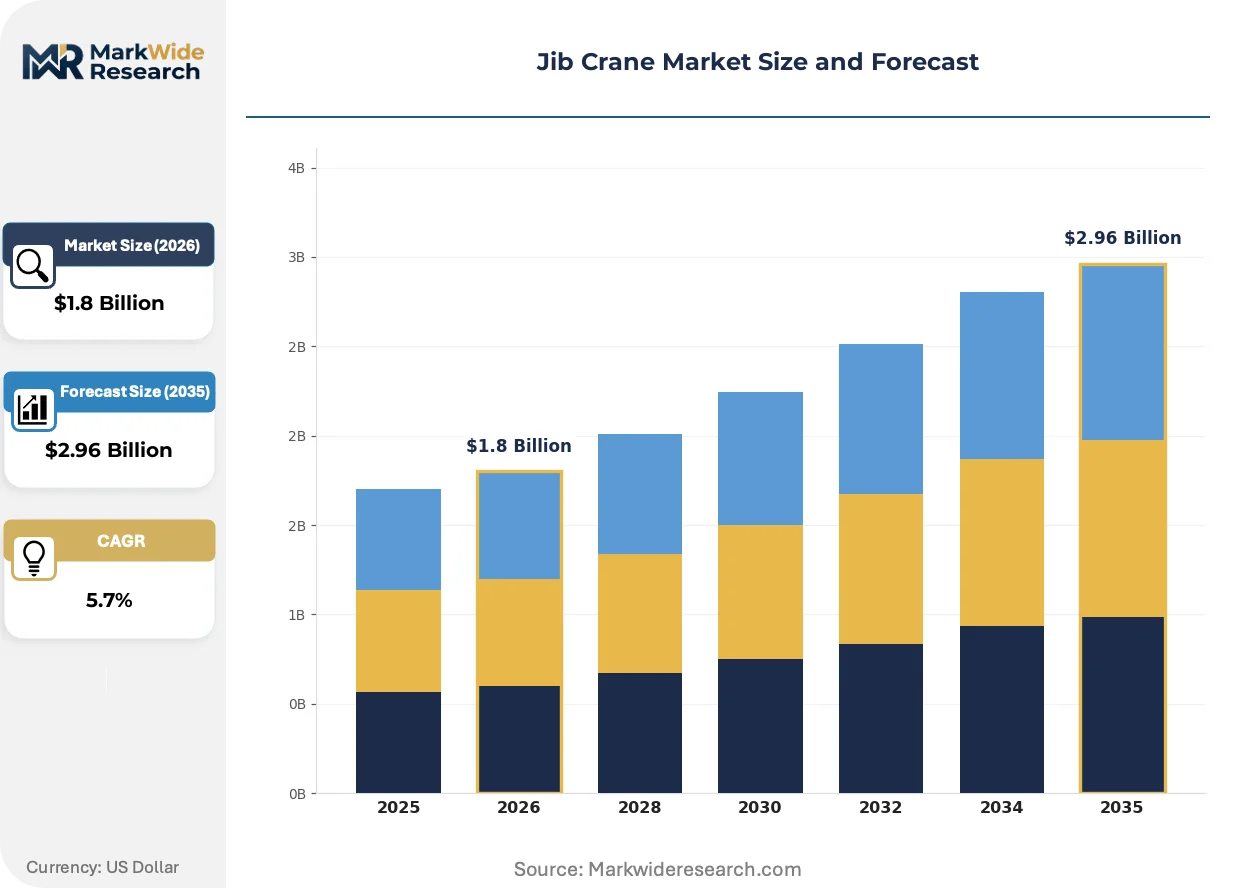
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulating Jib, Fixed Jib, Wall-Mounted Jib, Slewing Jib Capacity: 1 Ton, 2 Ton, 5 Ton, 10 Ton Mounting Type: Floor-Mounted, Ceiling-Mounted, Truck-Mounted, Portable End User: Construction, Manufacturing, Warehousing, Maritime |
| Companies Covered | Konecranes, Demag Cranes & Components, Columbus McKinnon Corporation, ABUS Kransysteme, Terex Corporation, Gorbel, Mitsubishi Logisnext, Street CraneXpress, Verlinde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jib Crane Market Evolving Landscape
Modular crane packages and digitized maintenance protocols are compressing procurement cycles and reshaping aftermarket revenue structures across material handling equipment.
Plug-and-play hoist-trolley-control bundles are modularizing procurement decisions for mid-sized manufacturing plants. Plant engineers in Ohio and Michigan automotive supplier networks are specifying single-SKU crane packages to compress vendor management overhead. This standardization is modularizing the traditional multi-source procurement process into consolidated supplier relationships.
REACH substance restrictions and EU machinery directive updates are tightening documentation requirements for European-sourced components. Component suppliers serving Netherlands and German port equipment markets are accelerating material certification workflows to maintain specification eligibility. Wall-mounted jib configurations with European-sourced electric chain hoists face extended compliance timelines compared to domestic alternatives.
Maintenance contract unbundling is fragmenting aftermarket revenue streams between OEM service networks and third-party inspection providers. Fleet operators in Texas and Louisiana petrochemical corridors are separating preventive maintenance from corrective repair spend, compressing OEM service attachment rates. This disaggregation is most visible in multi-site manufacturing groups with centralized procurement functions negotiating inspection-only contracts.
Jib Crane Market Segmentation
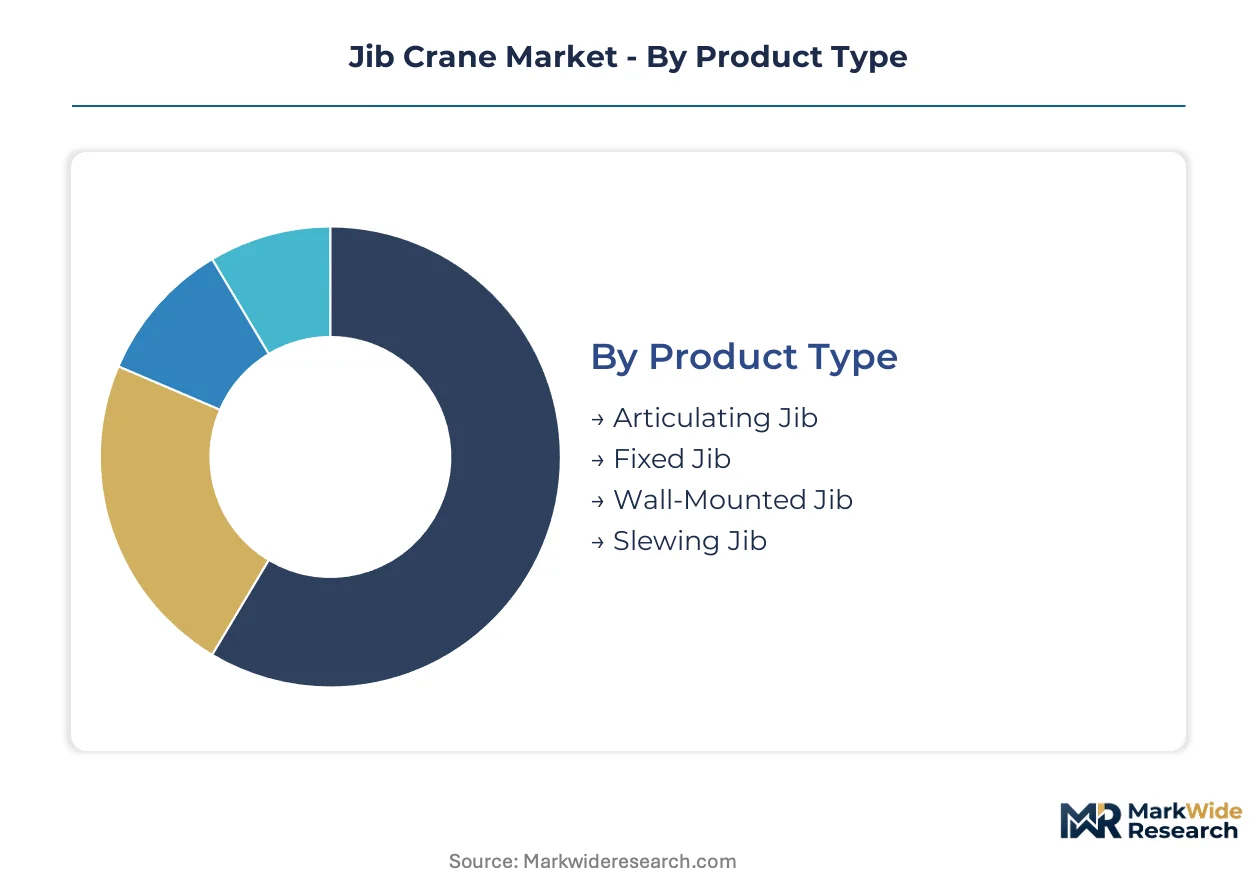
Jib crane procurement patterns diverge sharply by operational environment, with petrochemical corridors demanding certified heavy-capacity installations while urban logistics networks prioritize space-efficient configurations. Understanding these segment boundaries clarifies specification priorities across disparate buyer ecosystems.
Product Type:
Buyers in this category differentiate primarily by obstacle density and precision requirements within their work envelopes.
- Articulating Jib:Floor-mounted pivot designs with multiple jointed segments enable load positioning around machinery obstructions. Demand concentrates in Ohio and Michigan automotive assembly plants where line density limits fixed-gantry deployment. OSHA ergonomic mandates are accelerating specification of force-sensing pendant variants.
- Fixed Jib:Single-boom configurations with 180-360 degree rotation sustain margin pools through simpler mechanical construction. Gulf Coast petrochemical facilities in Texas and Louisiana specify these for 5-10 ton repetitive lifting cycles where downtime minimization outweighs positioning flexibility.
- Wall-Mounted Jib:Cantilevered designs eliminate floor obstructions in space-constrained warehousing environments.
- Slewing Jib:Rotating mast configurations serve maritime loading operations requiring continuous boom repositioning.
Fixed jib leads volumes today; articulating jib is gaining share fastest.
Capacity:
Specification thresholds in this category map directly to ASME B30.2 inspection frequency requirements and operator licensing tiers.
- 1 Ton:Light-capacity electric chain hoists dominate workstation ergonomics applications. Great Lakes distribution hubs specify these for e-commerce parcel handling where single-operator efficiency determines throughput.
- 5 Ton:Mid-range capacities capture manufacturing maintenance bays and tool-die handling operations. California automotive suppliers favor this tier for its balance between load coverage and ceiling structural requirements.
- 2 Ton:Compact configurations serve light assembly cells with intermittent duty cycles.
- 10 Ton:Heavy-process specifications concentrate in Gulf Coast chemical processing and primary metals operations.
Five-ton installations anchor current procurement volumes; one-ton workstation configurations are expanding most quickly.
Mounting Type:
Structural integration decisions in this category hinge on floor load capacity and ceiling height constraints within existing facilities.
- Floor-Mounted:Freestanding mast designs with embedded foundation bolts sustain the highest load ratings. Texas petrochemical refineries prefer these for 10-ton process equipment maintenance where soil-bearing capacity permits heavy foundations.
- Ceiling-Mounted:Suspended configurations from existing overhead structures eliminate floor penetration. Washington state aerospace manufacturing clusters specify these for cleanroom environments where floor contamination carries regulatory risk.
- Truck-Mounted:Mobile boom configurations serve construction sites with distributed material handling requirements.
- Portable:Counterweighted base designs enable rapid redeployment across multi-bay manufacturing facilities.
Floor-mounted systems dominate installed base; ceiling-mounted variants are climbing the fastest as urban logistics facilities prioritize floor space recovery.
End User:
Industry-specific duty cycles and compliance burdens create distinct specification patterns across vertical markets.
- Manufacturing:Repetitive assembly operations demand ergonomic configurations with variable-frequency drive hoists. Michigan automotive supplier networks are unbundling maintenance contracts from equipment procurement, compressing OEM service attachment rates.
- Warehousing:Same-day fulfillment velocity is expanding fleet purchases in Illinois and Ohio distribution corridors. Wall-mounted articulating configurations are displacing fixed gantries where aisle width constraints limit overhead coverage.
- Construction:Temporary installations with rapid mobilization requirements favor truck-mounted and portable configurations.
- Maritime:Corrosion-resistant specifications with extended rotation arcs serve port cargo handling operations.
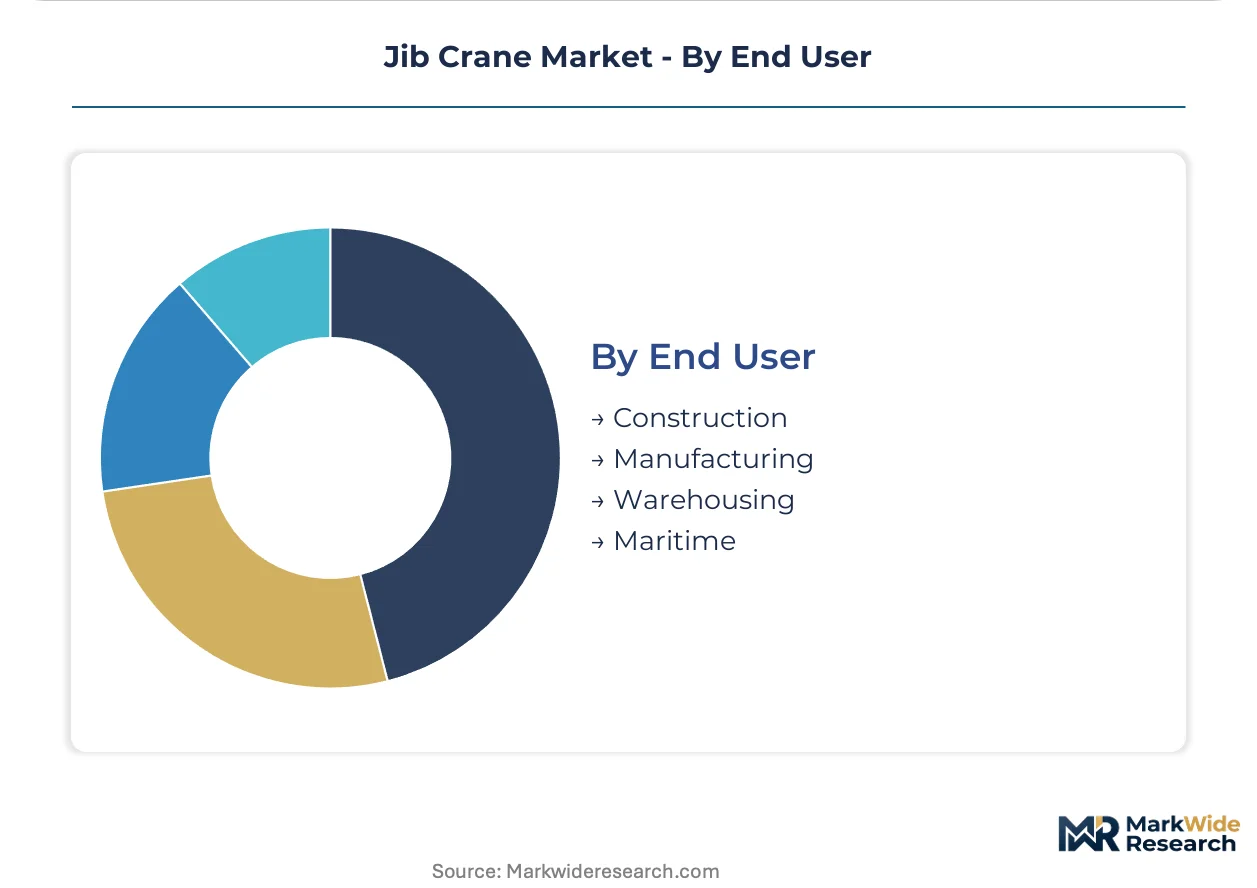
Manufacturing anchors current demand volumes; warehousing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jib crane manufacturing originated in the industrial heartlands of Germany and the United States during the early twentieth century, with German engineering firms pioneering standardized overhead lifting designs that spread through European heavy industry. Today, demand concentrates in petrochemical corridors, automotive manufacturing belts, and e-commerce distribution hubs across five major economies.
United States
Gulf Coast petrochemical facilities and Great Lakes automotive supplier networks drive replacement cycles for certified overhead lifting equipment. OSHA crane inspection mandates under 1910.179 and ASME B30.2 compliance requirements compress procurement timelines toward documented suppliers. Houston and Lake Charles industrial corridors specify floor-mounted fixed jib configurations for 5-10 ton process maintenance cycles.
Germany
Automotive assembly plants in Baden-Württemberg and Bavaria demand ergonomic workstation crane configurations with force-sensing pendant controls. REACH substance restrictions and EU machinery directive updates tighten documentation requirements for electric chain hoist components. Stuttgart and Munich manufacturing clusters prioritize modular crane packages that bundle hoist, trolley, and control systems into single-SKU offerings.
China
Yangtze River Delta port operations and Pearl River Delta electronics assembly drive demand for corrosion-resistant slewing jib configurations. GB standards and MIIT industrial safety regulations shape product certification workflows for domestic and export markets. Shanghai and Ningbo maritime terminals specify extended rotation arc designs for continuous cargo repositioning.
Japan
Kanto region automotive plants and Chubu precision manufacturing clusters prioritize variable-frequency drive hoists for repetitive assembly operations. METI energy efficiency guidelines and JIS standards influence control system specifications. Toyota City and Nagoya industrial corridors favor ceiling-mounted installations in cleanroom environments where floor contamination carries regulatory risk.
India
Maharashtra and Gujarat manufacturing hubs expand jib crane fleets for maintenance bay operations and tool-die handling. BIS certification requirements and state-level factory inspectorate mandates accelerate specification of documented equipment suppliers. Pune and Ahmedabad automotive supplier networks favor 2-5 ton capacity tiers balancing load coverage with ceiling structural requirements.
Jib Crane Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification documentation and aftermarket service attachment rates. The vendor base organizes into three tiers: integrated overhead lifting specialists with captive hoist manufacturing, regional fabricators serving single-country procurement lists, and workstation ergonomics specialists focused on force-sensing control integration. Consolidation pressure favors suppliers with dedicated ASME B30.2 engineering staff over smaller fabricators. Dominant competitive moves include aftermarket service contract expansion and modular package standardization.
Among integrated overhead lifting specialists, Konecranes and Columbus McKinnon Corporation exemplify archetypes built on vertical control over hoist and rigging component supply. Gorbel occupies a position within the workstation ergonomics tier, representing specialists in articulated jib configurations for repetitive assembly environments. Demag Cranes & Components anchors the German engineering tradition, while ABUS Kransysteme sits within the mid-market regional fabricator tier serving European procurement specifications.
| Leading Market Players |
|---|
| Konecranes |
| Demag Cranes & Components |
| Columbus McKinnon Corporation |
| ABUS Kransysteme |
| Terex Corporation |
| Gorbel |
| Mitsubishi Logisnext |
| Street CraneXpress |
| Verlinde |
| Others |
Value Network & Pricing Analysis
OSHA-certified crane inspector concentrations in the Texas-Louisiana Gulf Coast corridor create labor-cost differentials that widen pricing spreads between premium certified installations and economy-tier fabricator offerings. This workforce geography compresses margins for uncertified suppliers while rewarding documented manufacturers with pricing power in compliance-heavy petrochemical maintenance contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with premium tiers commanding spreads based on ASME B30.2 certification documentation and aftermarket service bundling. Price differentiation hinges on inspection-ready documentation packages and captive hoist manufacturing versus outsourced component sourcing. Cost compression in the economy tier intensifies because structural steel input volatility squeezes fixed-price contract manufacturers. Fleet operators in Great Lakes distribution hubs exhibit highest price sensitivity, while Gulf Coast petrochemical facilities prioritize compliance assurance over procurement cost minimization.
Supply Chain Analysis
Freight cost differentials between domestic structural steel mills and European electric hoist component suppliers shape landed cost structures for wall-mounted configurations. Supply concentrates in the United States, Germany, and China for boom fabrication, electric chain hoists, and control system assemblies respectively. Raw material dependencies rest on hot-rolled steel coil, copper windings, and semiconductor-based variable-frequency drives. Single-source vulnerability in European-sourced REACH-compliant components creates specification delays for warehouse operators. Distribution runs through OEM-direct sales for large petrochemical accounts and industrial distribution channels for mid-sized manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Jib Crane Market functions as a stable compounder anchored by regulatory replacement cycles that perpetuate demand regardless of industrial capacity expansion rates. OSHA inspection mandates create non-discretionary procurement events that sustain equipment turnover through compliance-driven refresh schedules.
For Market Incumbents: Anchor market position through backward integration into hoist and rigging component manufacturing, mirroring Columbus McKinnon Corporation's captive supply strategy. Invest in dedicated ASME B30.2 certification engineering staff to disqualify regional fabricators from specification lists. Expand aftermarket service contract penetration to offset maintenance unbundling trends among multi-site manufacturing groups with centralized procurement functions.
For New Entrants and Emerging Players: Begin with wall-mounted articulating configurations in space-constrained urban logistics corridors where floor obstruction elimination commands specification priority. Target California and Washington state-level crane operator licensing requirements as regulatory entry points for training-bundled equipment packages. Pursue ergonomic workstation crane configurations for automotive assembly plants as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Industrial distribution conglomerates are the most active acquirer in this space, consolidating regional fabricators to build specification eligibility across state procurement lists. Long-term viability frames around installed base service attachment rates rather than equipment shipment volumes. Acquisition target archetypes include workstation ergonomics specialists with force-sensing control integration capabilities. Monitor state-level crane operator licensing expansion as the signal to watch for specification pull acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hoist Manufacturing | Columbus McKinnon Corporation's captive supply of rigging components insulates margin pools from component price volatility. |
| Modular Crane Package Standardization | Konecranes bundles hoist, trolley, and control systems into single-SKU offerings that compress procurement cycles for Ohio automotive suppliers. |
| Workstation Ergonomics Integration | Gorbel's force-sensing pendant controls reduce repetitive strain injury exposure in Michigan assembly plants per OSHA mandates. |
| Aftermarket Service Contract Expansion | Preventive maintenance unbundling from corrective repair spend fragments revenue streams between OEM networks and third-party inspectors. |
| State-Level Licensing Compliance Bundling | California and Washington certification requirements create specification pull for training-integrated equipment packages. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and plant engineers, secondary validation through SEC filings and customs data, and trade association documentation — were reconciled to construct market estimates. Stakeholder conversations included aftermarket service heads at OEM networks, procurement teams at Gulf Coast petrochemical facilities, and industrial distribution channel partners. Secondary sources encompassed OSHA enforcement databases, ASME B30 standard revision records, and steel price indices. Bottom-up triangulation across equipment shipment volumes and top-down reconciliation against end-user capital expenditure patterns anchored value estimates.
Data-stream reconciliation across product type, capacity tier, mounting configuration, and end-use industry dimensions shaped the analytical framework. Segmentation modeling captured articulating versus fixed jib demand splits, 1-ton through 10-ton capacity bands, and manufacturing versus warehousing vertical distinctions. CAGRs derived from regression analysis against industrial production indices and e-commerce fulfillment velocity metrics. Forecast inputs included structural steel price trajectory assumptions and state-level crane operator licensing adoption curves.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement shifts, tariff modifications on European electric hoist components, and abrupt commodity price dislocations. Forecasts reflect assumptions about inspection frequency continuity and replacement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Scaffold Technology Market
Construction Equipment
Boring Bar Market
Construction Equipment
Rotomolding Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Tower Crane Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Australia Mobile Cranes Rental Market