
 Rough Terrain Crane Market | 2026-2036
Rough Terrain Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Rough Terrain Crane Market Analysis
ISO 4301-1 crane classification and EN 13000 mobile crane conformity assessment is redrawing competitive boundaries for rough terrain crane suppliers. Liebherr Group leverages its in-house component manufacturing to control delivery timelines for high-capacity models. Tadano Ltd. anchors its position through advanced telematics integration and operator-assist technologies. Xuzhou Construction Machinery Group sustains cost competitiveness via captive supply of structural steel and hydraulic systems.
Rough terrain cranes are self-propelled, all-wheel-drive lifting machines designed for off-highway operations on unimproved surfaces, typically featuring four-wheel steering, oscillating axles, and boom systems rated from 20 to over 150 tons lifting capacity; their primary purpose is to execute heavy lifts in remote construction, energy, and resource extraction sites where conventional truck-mounted or all-terrain cranes cannot access. Hydraulic cranes dominate unit shipments due to mature service infrastructure and operator familiarity, though electrical crane variants are gaining traction in noise-restricted urban infrastructure zones. Above 50 tons capacity units command disproportionate margin pools as rental fleets prioritize utilization rates on long-duration wind and petrochemical projects.
FAA obstruction lighting requirements intersect with OSHA crane operator certification mandates to shape product specification sheets and aftermarket retrofit demand in United States deployments. EPA Tier 4 Final and corresponding EU Stage V emissions frameworks are accelerating powertrain redevelopment cycles, with OEMs absorbing compliance costs or passing them through to rental channel partners. Stakeholders must monitor how regional emissions enforcement variance between North American and European jurisdictions affects fleet standardization strategies and residual value forecasting.
Market Dynamics
EPA Tier 4 Final emissions mandates are compressing powertrain redevelopment cycles, forcing OEMs to absorb compliance costs or pass them through rental channels while simultaneously accelerating diesel-electric hybrid adoption in above-fifty-ton fleet orders.
Growth Catalysts
- Offshore wind installation:North Sea and US Atlantic coast projects are expanding orders for high-capacity units capable of handling turbine nacelle lifts in marshy foundation zones.
- EPA Tier 4 Final:US emissions compliance deadlines are pulling forward fleet replacement cycles among rental companies operating in Texas shale patch and Gulf Coast petrochemical corridors.
- Telematics integration:Real-time load monitoring and predictive maintenance systems are reducing downtime for operators on remote construction sites.
Market Restraints
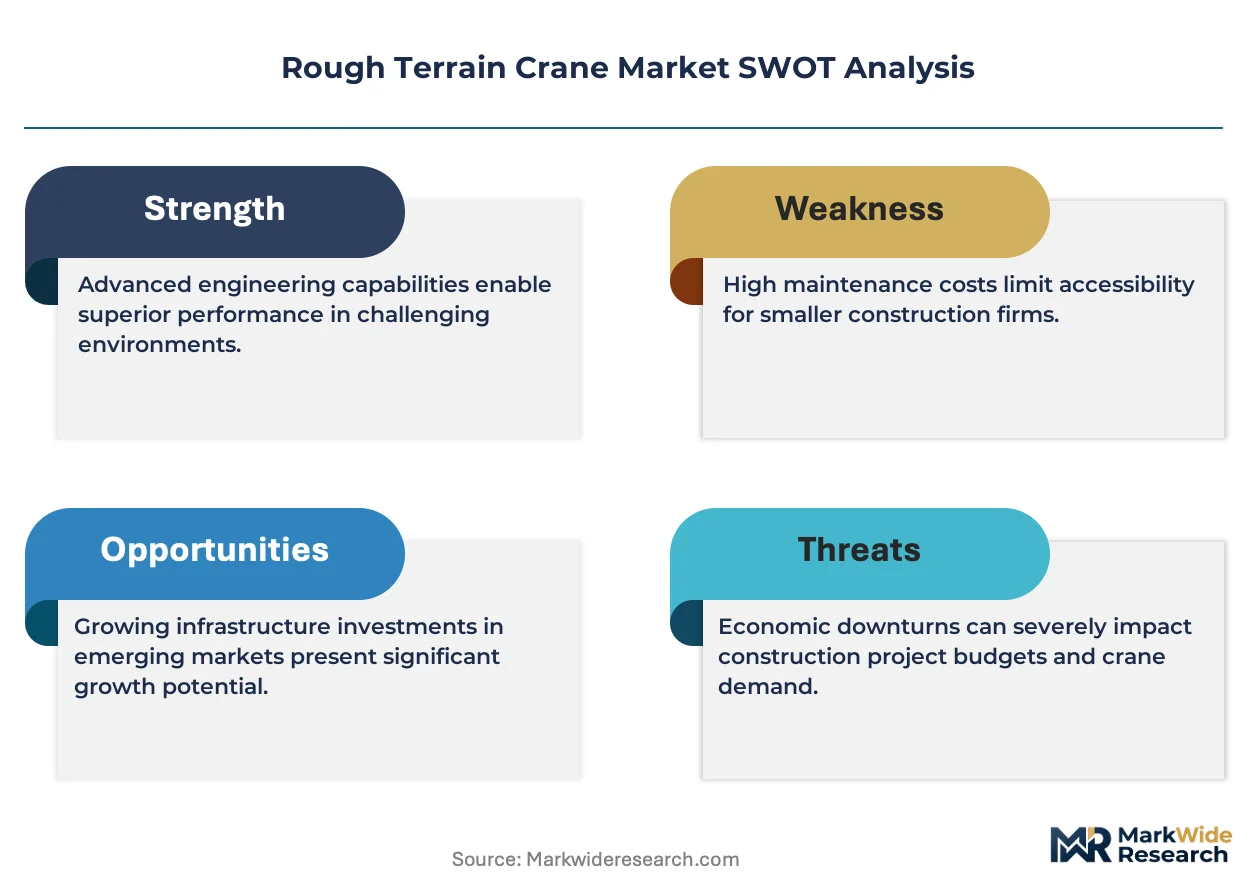
- Structural steel volatility:Fluctuating commodity prices for high-strength plate steel directly impact manufacturing cost bases for boom fabrication.
- Hydraulic component concentration:German and Japanese precision pump and valve suppliers create single-source vulnerability for Tier 1 OEM assembly lines.
- Electric range limitations:Battery energy density constraints restrict all-electric crane deployment to sub-fifty-ton categories and short-duty cycles.
Strategic Opportunities
- India infrastructure buildout:National highway and renewable energy projects present underpenetrated demand for mid-capacity rough terrain units in Rajasthan and Gujarat states.
- Carbon border adjustments:EU CBAM implementation creates competitive opening for manufacturers with verified low-carbon steel sourcing and hybrid powertrain certification.
- Subscription-based fleet access:Equipment-as-a-service platforms are emerging as alternative channels for contractor customers seeking utilization flexibility without capital commitment.
Industry Challenges
- OSHA crane operator certification:Extended training timelines and examination backlogs are constraining qualified labor availability for specialized rough terrain deployments.
- ISO 4301-1 classification alignment:Harmonizing legacy fleet ratings with updated load chart standards requires costly engineering documentation and aftermarket retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rough Terrain Crane Market |
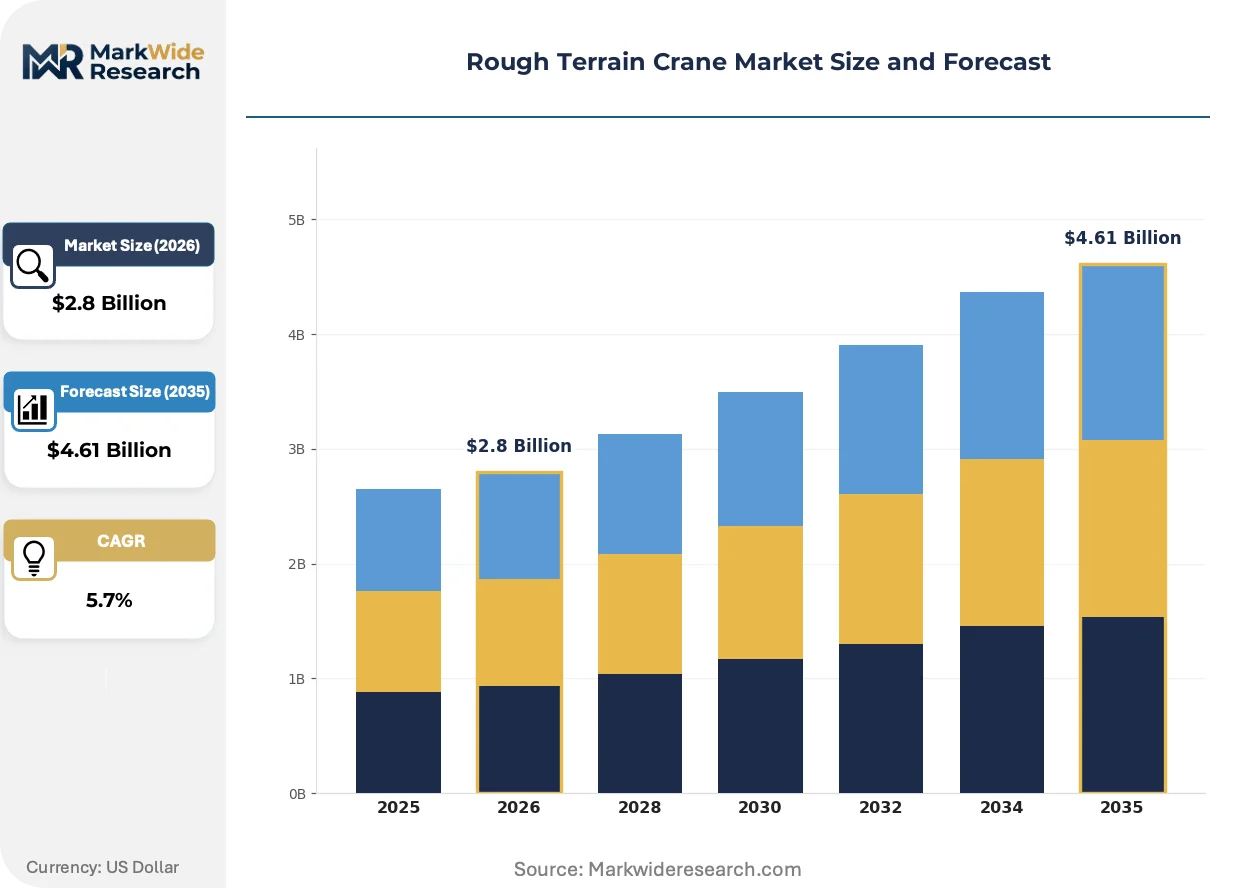
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Cranes, Electrical Cranes, Telehanders, Crawler Cranes End User: Construction, Mining, Oil & Gas, Forestry Capacity: 20-30 Tons, 30-40 Tons, 40-50 Tons, Above 50 Tons Application: Infrastructure, Heavy Lifting, Material Handling, Site Preparation |
| Companies Covered | Liebherr Group, Terex Corporation, The Manitowoc Company, Inc., Tadano Ltd., Xuzhou Construction Machinery Group Co., Ltd., SANY Group, KATO WORKS CO., LTD, Zoomlion Heavy Industry Science & Technology Co. Ltd., Link-Belt Construction Equipment Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rough Terrain Crane Market Emerging Trajectories
Powertrain electrification and digital load management systems are converging to redefine equipment specifications, with regulatory pressure and operational efficiency demands pulling innovation in parallel directions rather than sequential waves.
Variable displacement hydraulic pump technology is miniaturizing. Compact electro-hydraulic actuators now integrate directly into boom sections, eliminating external hose routing and reducing leak points. Wind farm contractors in Denmark and Germany are specifying these configurations for salt-air corrosion resistance. The technology is miniaturizing auxiliary power unit footprints, freeing chassis space for battery packs without compromising lift capacity.
EU Stage V non-road mobile machinery regulations are tightening particulate matter and NOx limits beyond EPA Tier 4 Final thresholds. OEMs serving dual jurisdictions face divergent certification costs and engineering validation timelines. Above-seventy-five-ton capacity models destined for German and French rental fleets absorb disproportionate compliance investment, compressing margin pools on smaller units.
Rental fleet managers are unbundling maintenance contracts from base equipment leases, treating predictive service as separately negotiable. Independent service providers in Texas and Louisiana are capturing this spend through remote diagnostics subscriptions. The shift is most visible in petrochemical corridor operations where uptime guarantees outweigh capital cost considerations in vendor selection criteria.
Rough Terrain Crane Market Segmentation
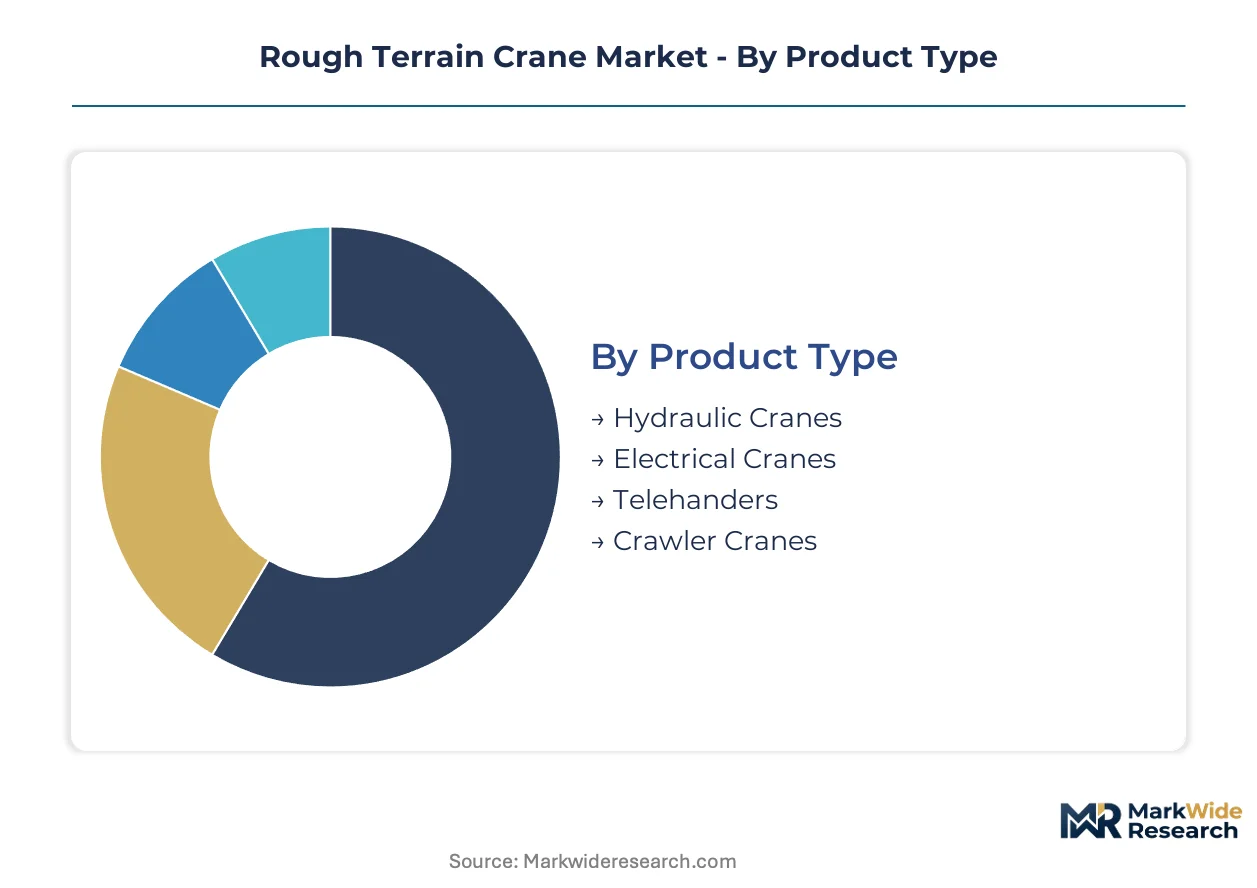
Rough terrain crane procurement channels vary sharply by segment, with rental fleets dominating above-fifty-ton capacity while contractor direct purchases concentrate in mid-capacity hydraulic units. Segmentation discipline reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Channel mix splits between rental fleet procurement for premium hydraulic units and direct contractor acquisition of specialized electrical variants, with telehandlers flowing through equipment dealer networks and crawler cranes anchoring long-term project leases.
- Hydraulic Cranes:Mature pump-and-cylinder architectures dominate rental fleet rotations, with four-wheel steering and oscillating axle configurations standard. Demand concentrates in Texas Permian Basin shale operations and Gulf Coast petrochemical corridor projects where EPA Tier 4 Final compliance deadlines accelerate replacement cycles.
- Electrical Cranes:Battery-electric and diesel-electric hybrid powertrains eliminate hydraulic fluid leak risks in sensitive environments. Above-fifty-ton hybrid variants from Danish and German wind farm contractors absorb disproportionate engineering investment as EU Stage V particulate limits tighten beyond EPA thresholds.
- Telehandlers:Compact rough terrain forklifts with telescopic booms serve material placement tasks below full crane duty cycles.
- Crawler Cranes:Tracked undercarriage variants sacrifice highway mobility for load-bearing capacity on unimproved foundation sites.
Hydraulic cranes dominate installed base. Electrical cranes are where expansion concentrates.
End User:
Application maturity varies by sector, with oil and gas contractors demanding highest uptime guarantees while construction procurement emphasizes capital efficiency.
- Construction:General contractors and specialty trade contractors deploy units for commercial building erection and highway interchange construction. Demand clusters in India national highway projects across Rajasthan and Gujarat states where mid-capacity units face underpenetrated competition.
- Mining:Surface extraction operations require corrosion-resistant specifications for high-salinity environments. Australian iron ore and Chilean copper belt operators specify enhanced boom coatings and sealed electrical systems.
- Oil & Gas:Upstream drilling support and downstream refinery turnaround maintenance drive premium pricing for guaranteed availability contracts.
- Forestry:Logging operations and biomass processing facilities utilize lighter-capacity units for roadside processing and loading tasks.
Construction commands unit volume. Oil and gas generates margin concentration.
Capacity:
Cost tier stratification separates rental fleet standardization around fifty-ton breakpoints from project-specific procurement of specialized high-capacity units.
- 20-30 Tons:Entry-level rough terrain units serve utility maintenance and light commercial construction. Urban infrastructure contractors in noise-restricted zones specify this bracket for electrical conversion feasibility.
- 30-40 Tons:Mid-capacity workhorses balance mobility and lift capability for general building trades.
- 40-50 Tons:Upper-mid bracket captures petrochemical maintenance and wind turbine component staging where reach requirements outgrow lighter units.
- Above 50 Tons:High-capacity models with extended boom systems and auxiliary lifting attachments command disproportionate margin pools. North Sea and US Atlantic coast offshore wind installation fleets expand orders for nacelle and blade handling in marshy foundation zones.
Above 50 tons captures value concentration. 30-40 tons maintains volume leadership.
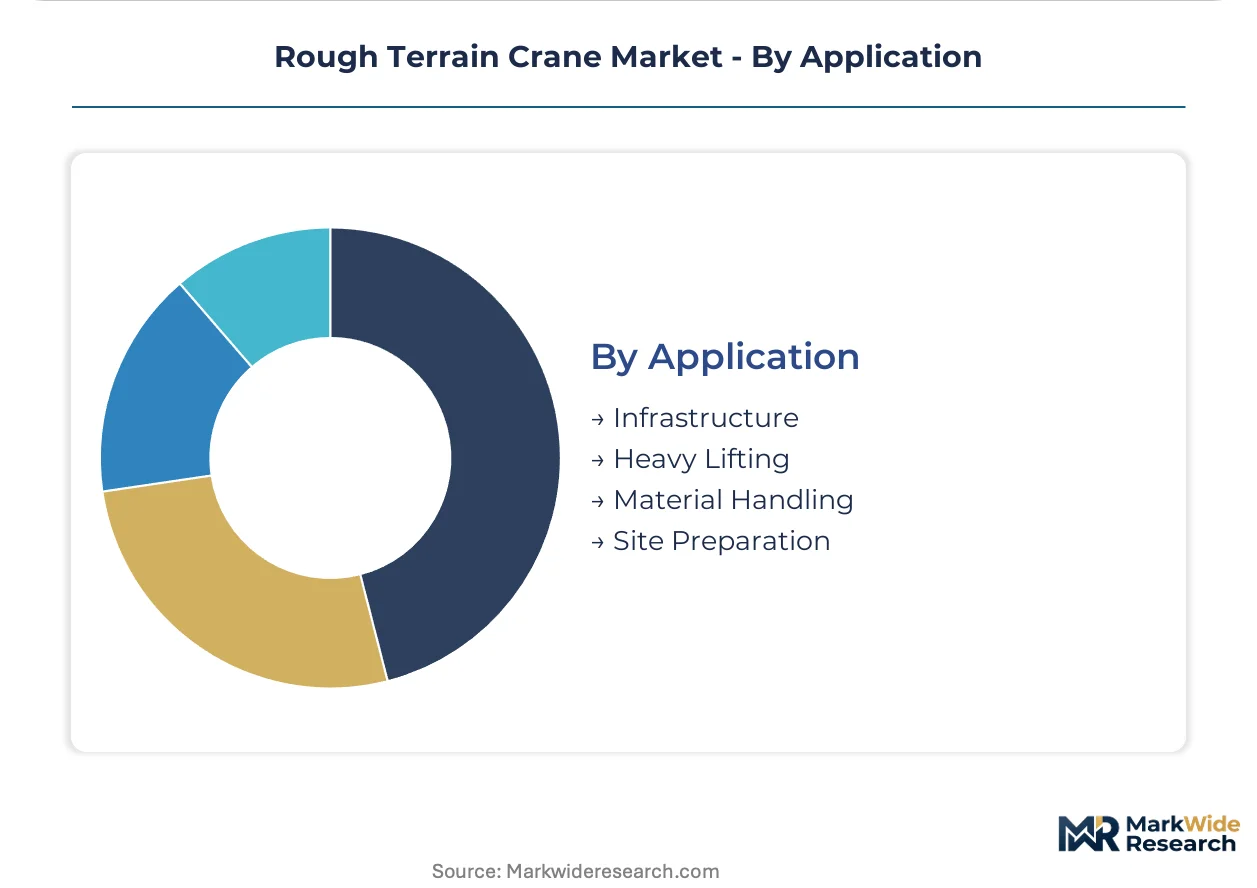
Application:
Customer type segmentation separates capital-project procurement from operational maintenance spending, with infrastructure agencies driving standardization while heavy lifting contractors seek differentiation.
- Infrastructure:Public agency procurement emphasizes interoperability and certification compliance for bridge construction and highway development. FAA obstruction lighting requirements intersect with OSHA crane operator certification mandates to shape specification sheets.
- Heavy Lifting:Specialized contractors executing turbine installation, refinery vessel placement, and modular construction demand engineered solutions with real-time load monitoring. Predictive maintenance telematics integration reduces downtime premiums in remote site deployments.
- Material Handling:General logistics and yard operations prioritize cycle speed over precision positioning.
- Site Preparation:Grading and foundation contractors utilize crane-mounted attachments for pile driving and excavation support.
Infrastructure standardizes procurement. Heavy lifting drives technology premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final deadlines and EU Stage V compliance timelines are accelerating fleet replacement cycles across multiple jurisdictions. Government infrastructure programs in India and offshore wind procurement mandates in Northern Europe are pulling demand forward for high-capacity units.
United States
Texas shale patch operations and Gulf Coast petrochemical corridor projects dominate procurement volumes. OSHA crane operator certification mandates intersect with FAA obstruction lighting requirements to shape specification sheets for bridge construction and wind farm installations. Houston and Corpus Christi anchor rental fleet concentrations serving refinery turnaround maintenance.
Germany
North Sea offshore wind installation fleets are expanding orders for above-seventy-five-ton capacity models capable of nacelle lifts in marshy foundation zones. EU Stage V particulate matter and NOx limits tighten beyond EPA Tier 4 Final thresholds, absorbing disproportionate compliance investment. Bremerhaven and Hamburg harbor clusters concentrate manufacturing and service infrastructure for Baltic and North Sea contractors.
India
National highway projects across Rajasthan and Gujarat states present underpenetrated demand for mid-capacity rough terrain units. BIS certification alignment with ISO 4301-1 crane classification is redrawing competitive boundaries for imported equipment. Mumbai-Pune industrial corridor and Delhi-Mumbai freight corridor construction sites are scaling rough terrain crane deployment for interchange and viaduct erection.
China
Domestic infrastructure buildout and Belt and Road project exports sustain manufacturing scale for structural steel and hydraulic system suppliers. MIIT equipment certification and GB standards alignment shape export readiness for high-capacity models. Xuzhou and Changsha industrial clusters concentrate OEM assembly capacity and captive supply chain integration.
United Kingdom
North Sea decommissioning and Irish Sea offshore wind development are pulling specialized high-reach unit orders. Health and Safety Executive lifting equipment regulations intersect with EU-derived machinery directives for post-Brexit conformity assessment. Aberdeen and Great Yarmouth anchor energy sector fleet concentrations serving North Sea oil, gas, and emerging floating wind projects.
Rough Terrain Crane Market Vendor Landscape
Player mix skews toward vertically integrated heavy machinery conglomerates with captive component manufacturing. Market structure concentrates around three to five dominant OEMs controlling above-fifty-ton capacity segments, with mid-capacity brackets exhibiting more fragmented competition. Strategic archetypes separate in-house steel and hydraulic producers from assembly-focused specialists and telematics-integrated solution providers. Competitive moves center on diesel-electric hybrid powertrain certification and predictive maintenance platform deployment.
Within the integrated-manufacturing tier, Liebherr Group and Xuzhou Construction Machinery Group Co., Ltd. exemplify archetypes anchored by captive supply of structural steel and hydraulic systems. Tadano Ltd. occupies a position representing telematics-integrated specialists advancing operator-assist technologies. These three entities collectively illustrate how component control, digital service layers, and regional manufacturing scale define competitive positioning in emission-constrained procurement environments.
| Leading Market Players |
|---|
| Liebherr Group |
| Terex Corporation |
| The Manitowoc Company, Inc. |
| Tadano Ltd. |
| Xuzhou Construction Machinery Group Co., Ltd. |
| SANY Group |
| KATO WORKS CO., LTD |
| Zoomlion Heavy Industry Science & Technology Co. Ltd. |
| Link-Belt Construction Equipment Co. |
| Others |
Supply Flow & Price Mechanics
Ninety-day hydraulic component lead times from German and Japanese precision pump suppliers concentrate pricing power in above-fifty-ton capacity segments, while EPA Tier 4 Final compliance costs compress margin pools on standard hydraulic units below this threshold. Rental fleet procurement contracts absorb disproportionate engineering investment through bundled predictive maintenance subscriptions, redirecting aftermarket service spend toward independent telematics providers in Texas and Louisiana petrochemical corridors.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 4301-1 crane classification and EN 13000 mobile crane conformity assessment commanding fifteen-to-twenty percent premiums over legacy-rated equipment in European and North American rental channels. Project-based contract pricing dominates above-fifty-ton fleet orders, where guaranteed uptime clauses outweigh capital cost considerations in vendor selection. Price differentiation intensifies around EPA Tier 4 Final and EU Stage V compliance investment, with OEMs passing through emission-system costs to Gulf Coast and North Sea wind farm contractors. Oil and gas maintenance segments exhibit lowest price sensitivity due to downtime penalty structures, while general construction procurement in India highway projects concentrates volume-driven negotiation leverage.
Supply Chain Analysis
Ruhr Valley precision valve manufacturing and Osaka electro-hydraulic actuator production create single-source vulnerability for Tier 1 OEM assembly lines serving above-seventy-five-ton capacity models. Structural steel draws from Chinese Xuzhou industrial clusters and German Ruhr foundries, with high-strength plate steel commodity volatility directly transmitting to boom fabrication cost bases. Supply chain risk centers on hydraulic component concentration, where German and Japanese pump suppliers maintain eighteen-month qualification timelines for alternative sourcing. Distribution runs through rental fleet procurement channels for premium hydraulic units, with direct contractor acquisition flowing through specialized heavy-lifting equipment dealers in Texas shale patch and Bremerhaven harbor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
All-terrain crane substitution threatens rough terrain incumbents in marshy foundation zones where hybrid powertrain range limitations no longer constrain competitor equipment. Incumbents must navigate this threat through powertrain certification acceleration and telematics platform differentiation.
For Market Incumbents: Fortify captive supply positions in structural steel and hydraulic systems to compress delivery timelines for high-capacity models against emerging assembly-focused specialists. Accelerate diesel-electric hybrid powertrain certification ahead of EU Stage V enforcement divergence, preserving fleet standardization options for multinational rental operators. Deepen predictive maintenance platform integration to capture unbundled service contracts from base equipment leases in petrochemical corridor operations. For New Entrants and Emerging Players: BIS certification fast-track alignment with ISO 4301-1 crane classification opens procurement access to India national highway projects across Rajasthan and Gujarat states. Target mid-capacity hydraulic units in underpenetrated infrastructure segments where incumbent concentration above fifty tons leaves volume tiers exposed. Deploy equipment-as-a-service subscription models to contractor customers seeking utilization flexibility without capital commitment in volatile shale patch operations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized rough terrain crane divisions lacking telematics integration or hybrid powertrain development pipelines. Long-term viability hinges on emission-compliant technology transition completion and aftermarket service platform scale. Monitor EU Carbon Border Adjustment Mechanism enforcement variance as inflection indicator for low-carbon steel sourcing competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Diesel-Electric Hybrid Certification | EPA Tier 4 Final and EU Stage V compliance preserves fleet standardization for multinational rental operators. |
| Predictive Maintenance Platform Deployment | Remote diagnostics subscriptions capture unbundled service spend from petrochemical corridor maintenance contracts. |
| Captive Structural Steel Supply | In-house production of boom fabrication inputs insulates margin pools from commodity price volatility. |
| Telematics Integration Partnership | Real-time load monitoring reduces downtime premiums for remote wind farm and mining site deployments. |
| Equipment-as-a-Service Launch | Subscription-based fleet access addresses contractor demand for utilization flexibility without capital commitment. |
Methodological Framework
Desk research of customs trade databases, OEM technical documentation, and rental fleet procurement records preceded structured interviews with maintenance directors at Texas shale patch operators, plant engineers at Gulf Coast petrochemical facilities, aftermarket service heads at Bremerhaven harbor clusters, and procurement teams at North Sea wind farm contractors. Primary fieldwork combined with secondary validation against SEC 10-K filings, EU machinery directive implementation reports, and Indian BIS certification databases. Bottom-up unit shipment modeling and top-down value chain triangulation anchored market size estimation.
Variance decomposition across capacity tier, powertrain architecture, and regional regulatory cluster shaped analytical framework development over the projection horizon. Segmentation modeling incorporated product type, end-use sector, capacity bracket, and application intensity dimensions. CAGRs derived from historical replacement cycle analysis and fleet expansion trajectories in offshore wind and petrochemical corridors. Forecast inputs included EPA enforcement timeline assumptions, EU CBAM implementation pace, and India infrastructure allocation patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained shale patch activity and offshore wind procurement mandates; material deviation in commodity steel pricing or emission regulation enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as hydraulic component supply concentration and battery energy density constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
CNC Router Market