

3-Wheel Sit-Down Counterbalance Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
3-Wheel Sit-Down Counterbalance Forklift Market Insights
Dealer and direct-to-fleet sales channels for industrial trucks is fragmenting as OEMs build captive finance arms and online configurators. Toyota Material Handling leverages its captive leasing network to lock in multi-year fleet contracts with grocery and pharmaceutical distributors. Crown Equipment differentiates through vertical integration into motor and controller manufacturing at its Ohio campus. Jungheinrich specializes in modular battery architectures that let operators swap power packs across 1500 kg and 2000 kg load classes without tooling changes.
The 3-Wheel Sit-Down Counterbalance Forklift is a powered industrial truck with a seated operator position, a three-point wheel configuration that reduces turning radius versus four-wheel designs, and a counterweight at the rear to offset front-loaded cargo; manufacturers typically rate these units from 1000 kg to 2500 kg and engineer mast lift heights above four meters for high-density racking. Its primary purpose is horizontal transport and vertical stacking in environments where aisle width falls below 3.5 meters. Electric product types now lead order books in Europe and North America as lithium-ion cell costs compress total cost of ownership curves against LPG alternatives. Load capacity demand tilts toward 1500 kg and 2000 kg brackets where third-party logistics operators standardize fleets across mixed wholesale and fulfillment contracts.
OSHA workplace safety standards in the United States mandate operator training and equipment inspection protocols that elevate total ownership calculations for diesel fleets. The EU Green Deal and REACH chemical frameworks restrict internal combustion propulsion in enclosed logistics facilities, accelerating electric platform certification cycles. Japan's METI efficiency benchmarks for industrial equipment filter import eligibility and shape domestic manufacturer R&D priorities. Stakeholders must monitor how battery recycling mandates and emerging solid-state cell formats reshape chassis design standards and supplier qualification timelines.
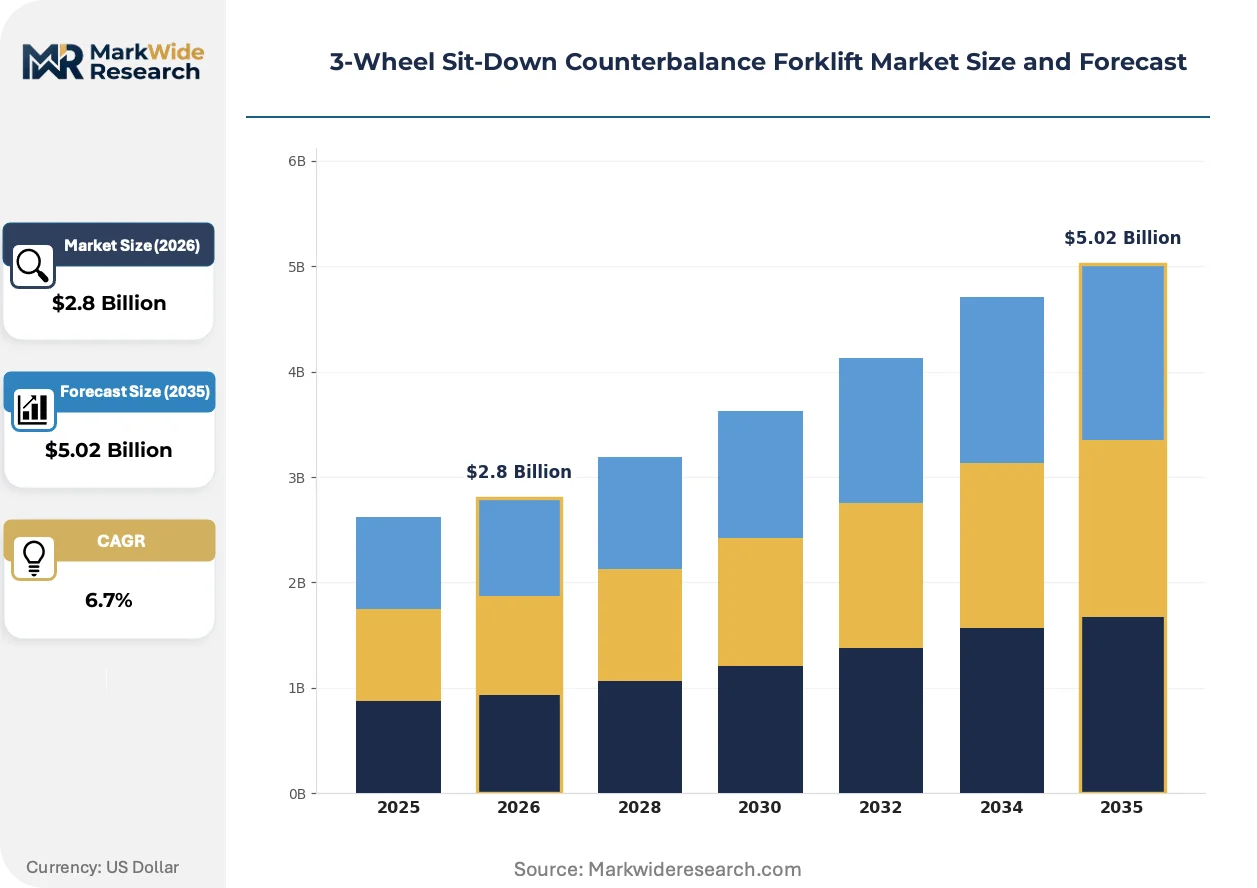
Market Dynamics
The EU Green Deal emissions benchmarks are redirecting procurement toward lithium-ion platforms, compressing total cost of ownership curves against internal combustion alternatives and forcing chassis redesigns around modular battery architectures.
Growth Catalysts
- E-commerce fulfillment densification:Warehouse operators in Germany and Japan are specifying 3-wheel configurations for aisles below 3.5 meters, prioritizing maneuverability over load capacity in last-mile distribution centers.
- OSHA workplace safety mandates:United States inspection protocols for industrial trucks elevate compliance costs for diesel fleets, tilting replacement cycles toward electric platforms with lower operator training liability.
- Lithium-ion cell cost compression:Battery chemistry improvements are narrowing the upfront price gap with LPG alternatives, accelerating payback periods for cold-chain logistics operators running multi-shift operations.
Market Restraints
- Critical mineral supply concentration:Lithium and cobalt refining capacity concentrates in China, exposing European and North American OEMs to geopolitical supply disruptions and forced stockpiling.
- Charging infrastructure capex:Fleet electrification requires depot-level electrical upgrades that third-party logistics operators defer during contract renewal cycles, delaying platform transitions.
- REACH chemical framework friction:EU restrictions on internal combustion propulsion in enclosed facilities compress certification timelines, forcing rushed product development cycles that strain engineering resources.
Strategic Opportunities
- India warehousing modernization:The country's PLI scheme for manufacturing automation is creating import substitution demand for compact electric forklifts as domestic cold-chain infrastructure expands.
- Solid-state battery convergence:Emerging cell formats with higher energy density are virtualizing chassis weight distributions, enabling lighter counterweights and redesigned mast geometries for higher lift capacities.
- Captive finance channel innovation:OEM-built leasing arms are locking in multi-year fleet contracts through usage-based pricing models that unbundle maintenance from equipment procurement.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion platform maintenance requires specialized electrical certification that existing diesel mechanic workforces lack, constraining service network expansion.
- Legacy warehouse management system integration:Electric fleet telematics data formats conflict with established ERP protocols, forcing middleware development that delays deployment timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Wheel Sit-Down Counterbalance Forklift Market Trends and Innovations
Battery virtualization and modular power architectures are compressing traditional equipment lifecycles, while regulatory emissions frameworks and procurement model fragmentation reshape competitive positioning across material handling.
Telematics-enabled predictive maintenance is virtualizing service contract structures. Grocery and pharmaceutical distributors in Germany are adopting usage-based maintenance subscriptions that replace fixed-interval servicing. This shift is compressing OEM aftermarket revenue streams while locking in longer equipment retention periods.
Japan's METI efficiency benchmarks for industrial equipment are filtering import eligibility and redirecting domestic manufacturer R&D priorities toward regenerative braking systems. Korean and Taiwanese component suppliers are accelerating controller firmware development to meet these thresholds. Cold-chain logistics operators now specify METI-compliant units as a procurement prerequisite.
Third-party logistics operators are consolidating fleet specifications around standardized 1500 kg and 2000 kg load classes. Mixed wholesale and fulfillment contracts drive this convergence, reducing spare parts inventory complexity. United States-based grocery distributors are leading this specification compression, pressuring OEMs to simplify product lineups.
3-Wheel Sit-Down Counterbalance Forklift Market Segmentation
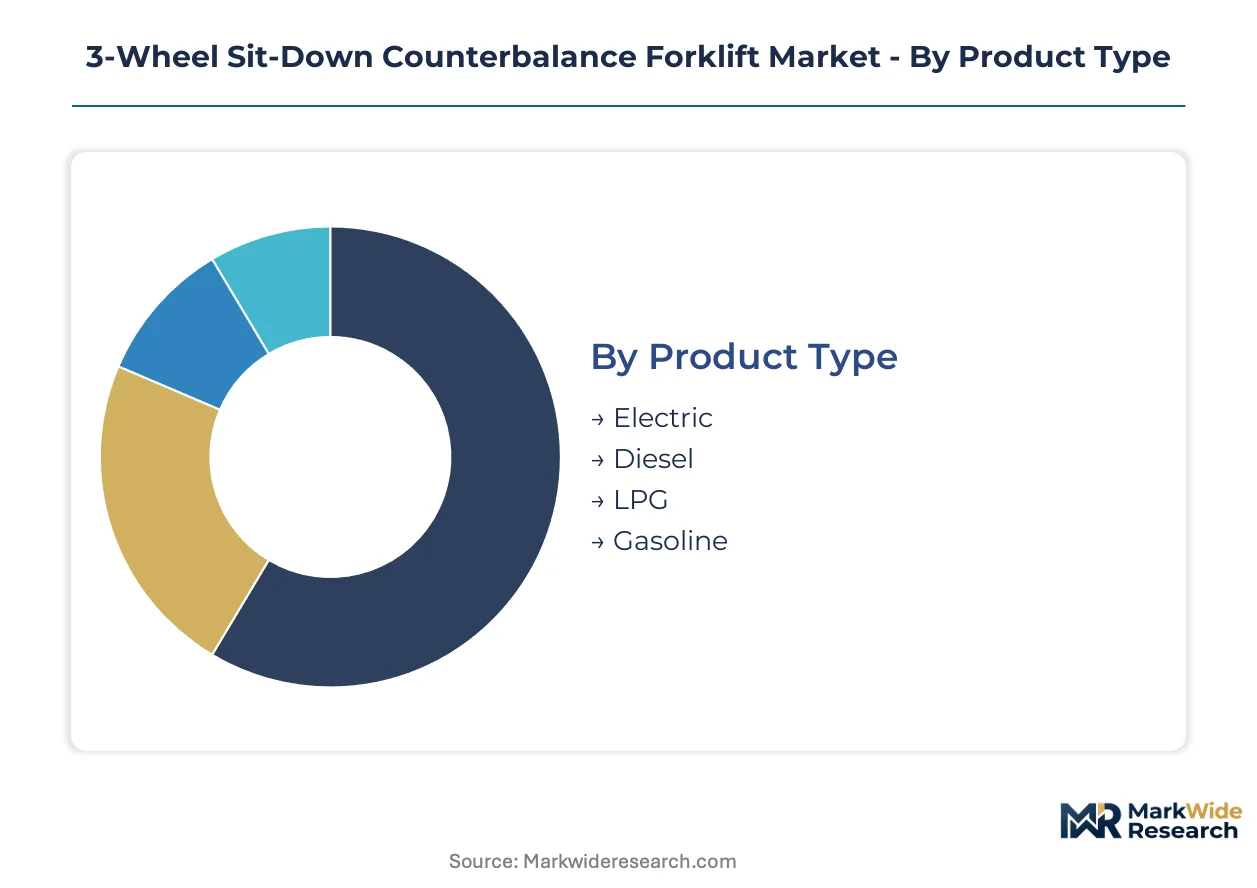
Segmentation in the 3-Wheel Sit-Down Counterbalance Forklift Market reveals how procurement priorities diverge across powertrains, load ratings, and facility types. Service intensity varies sharply between electric platforms requiring specialized technician certification and internal combustion units demanding emissions compliance protocols.
Product Type:
After-sales service intensity diverges most dramatically across powertrain categories, with electric platforms requiring high-voltage technician networks and combustion variants needing emissions testing infrastructure.
- Electric:Lithium-ion battery architectures dominate order books in Germany and Japan as EU Green Deal benchmarks compress total cost of ownership curves against LPG alternatives. Cold-chain logistics operators in the United States specify electric units for multi-shift operations where charging infrastructure supports continuous duty cycles.
- Diesel:Internal combustion platforms retain procurement share in outdoor yard operations and heavy manufacturing where refueling speed outweighs emissions constraints. OSHA inspection protocols elevate compliance costs, tilting replacement cycles toward electric alternatives in enclosed facilities.
- LPG:Propane-powered units serve transitional fleets balancing upfront capital constraints against electrification timelines, particularly in third-party logistics contracts with shorter renewal cycles.
- Gasoline:Petrol variants concentrate in emerging market warehousing with limited electrical infrastructure and minimal emissions enforcement.
Electric holds the largest share; momentum sits with LPG-to-electric conversions as battery chemistry improvements accelerate payback periods.
Load Capacity:
Cost tier stratification across load ratings determines fleet standardization patterns, with mid-capacity brackets enabling parts commonality that reduces inventory carrying costs.
- 1500 kg:This bracket anchors third-party logistics fleet specifications in the United States, where grocery distributors standardize across mixed wholesale and fulfillment contracts. Modular battery architectures from Jungheinrich allow power pack swapping without tooling changes, compressing downtime during shift transitions.
- 2000 kg:Cold-chain operators in Germany specify this capacity for high-density racking above four meters, where mast stability and counterweight distribution become critical. METI efficiency benchmarks in Japan filter import eligibility toward regenerative braking systems in this load class.
- 1000 kg:Compact units serve narrow-aisle e-commerce fulfillment centers where maneuverability outweighs lift capacity.
- 2500 kg:Heavy-duty configurations retain niche demand in manufacturing automation and packaging plants with palletized bulk goods.
1500 kg commands the dominant procurement volume; 2000 kg is climbing the fastest as cold-chain infrastructure densifies.
Application:
Volume concentration across facility types tracks e-commerce fulfillment densification, with last-mile distribution centers driving specification priorities over traditional manufacturing.
- Warehouse Handling:High-density storage operations in Japan specify 3-wheel configurations for aisles below 3.5 meters, prioritizing turning radius over absolute load capacity. Toyota Material Handling leverages captive leasing networks to lock multi-year contracts in this segment.
- Distribution Centers:Regional fulfillment hubs in Germany adopt telematics-enabled predictive maintenance that virtualizes service contract structures around usage-based subscriptions.
- Logistics Facilities:Cross-dock operations concentrate demand for rapid cycle times and standardized load classes that minimize equipment changeover.
- Manufacturing Units:Production-integrated material handling retains preference for diesel platforms in outdoor staging areas with limited electrification infrastructure.
Warehouse Handling generates the highest equipment density; Distribution Centers are gaining share fastest as e-commerce fulfillment networks expand.
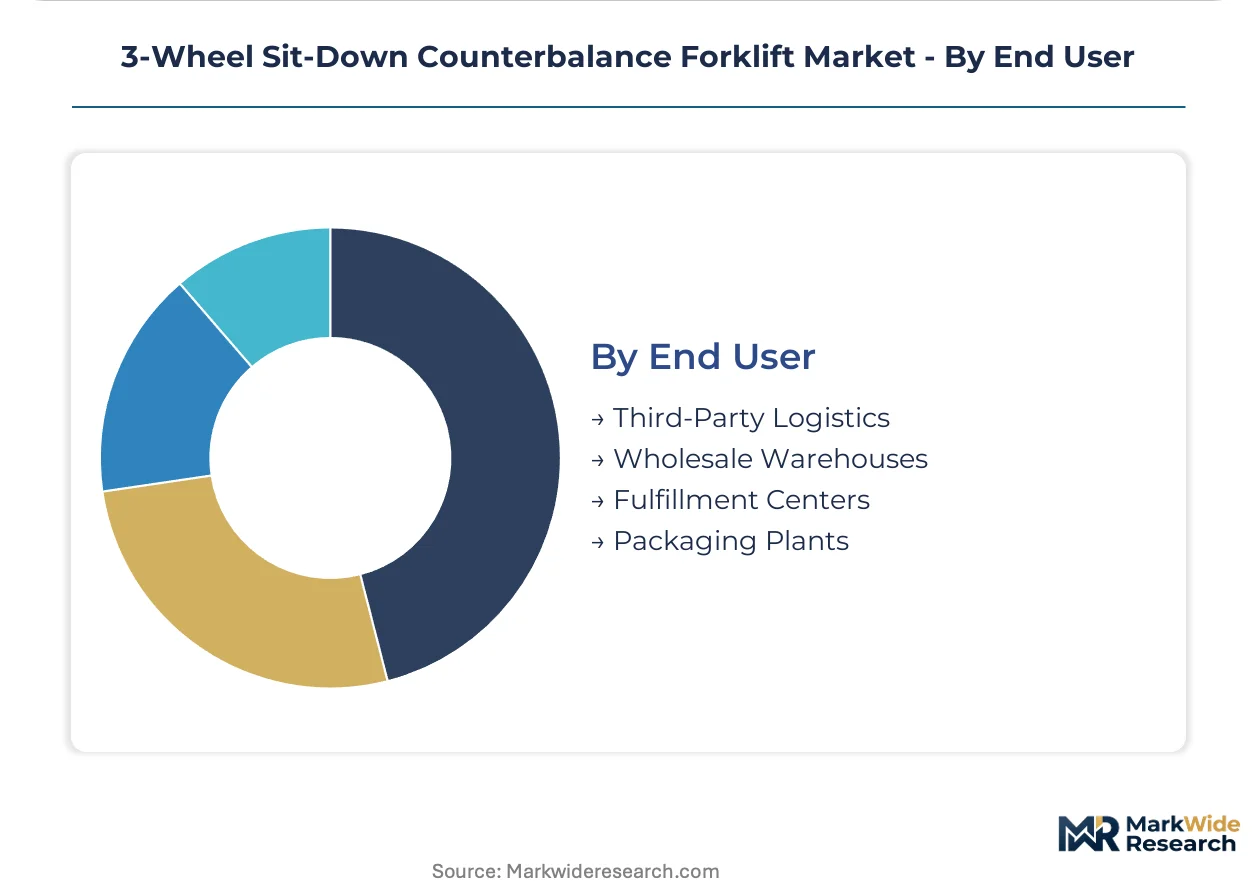
End User:
Customer type segmentation exposes procurement model fragmentation, with captive finance arms displacing traditional dealer channels among fleet-scale operators.
- Third-Party Logistics:3PL operators consolidate specifications around standardized 1500 kg and 2000 kg load classes to reduce spare parts complexity across mixed contract portfolios. Crown Equipment's vertical integration into motor manufacturing supports volume pricing for these fleet customers.
- Fulfillment Centers:E-commerce operators specify electric platforms with lithium-ion architectures to meet EU Green Deal emissions benchmarks in enclosed facilities.
- Wholesale Warehouses:Traditional distribution operations balance capital constraints against electrification timelines, often retaining LPG during contract renewal cycles.
- Packaging Plants:Manufacturing-integrated users prioritize uptime reliability and rapid service response over platform standardization.
Third-Party Logistics holds the largest fleet concentration; Fulfillment Centers show the steepest expansion trajectory as e-commerce penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites the Netherlands' role as Europe's logistics gateway, while Japan's Nagoya-Tokyo-Osaka manufacturing corridor anchors Asia-Pacific forklift demand density.
United States
E-commerce fulfillment densification across the Midwest and Southeast drives specification priorities for sub-3.5-meter aisle maneuverability. OSHA workplace safety mandates elevate compliance costs for diesel fleets, tilting replacement cycles toward electric platforms. Chicago and Dallas-Fort Worth logistics clusters concentrate multi-shift cold-chain operations requiring continuous-duty lithium-ion architectures.
Germany
High-density racking above four meters in Ruhr Valley distribution centers prioritizes mast stability and regenerative braking systems. EU Green Deal emissions benchmarks redirect procurement toward lithium-ion platforms, compressing total cost of ownership curves against LPG alternatives. Stuttgart and Munich automotive supplier parks standardize 1500 kg and 2000 kg load classes across mixed contract portfolios.
Japan
METI efficiency benchmarks for industrial equipment filter import eligibility and shape domestic manufacturer R&D priorities toward energy recovery systems. Kanto and Kansai logistics corridors specify 3-wheel configurations for narrow-aisle pharmaceutical and grocery distribution. Toyota City and Nagoya industrial clusters drive captive finance arm penetration for multi-year fleet contracts.
India
The PLI scheme for manufacturing automation creates import substitution demand for compact electric forklifts as domestic cold-chain infrastructure expands. BIS certification requirements and DGFT import regulations shape equipment qualification timelines for European and Japanese OEMs. Mumbai-Pune and Delhi-NCR warehousing clusters concentrate third-party logistics fleet standardization around mid-capacity load brackets.
South Korea
Busan-Ulsan port automation and Seoul Capital Area fulfillment center densification drive electric platform specification. MFDS pharmaceutical logistics standards and national industrial efficiency benchmarks filter procurement toward telematics-enabled predictive maintenance systems. Gyeonggi-do and Incheon free economic zones concentrate METI-compliant equipment deployment for export-oriented contract manufacturers.
3-Wheel Sit-Down Counterbalance Forklift Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying motors, controllers, and battery architectures. The vendor base organizes around three strategic archetypes: captive finance arms locking multi-year fleet contracts, vertically integrated manufacturers controlling motor and controller production, and modular battery specialists enabling cross-load-class power pack swapping. Competitive moves concentrate on backward integration into powertrain components and geographic expansion through regional assembly partnerships.
Among Japanese and German platform integrators, Toyota Material Handling and Jungheinrich occupy positions exemplifying captive finance and modular battery specialization respectively. Crown Equipment represents the vertically integrated archetype through in-house production of motors and controllers. These three anchors illustrate how competitive differentiation now flows from supply chain control rather than chassis engineering alone.
| Leading Market Players |
|---|
| Crown Equipment |
| Toyota Material Handling |
| KION Group |
| Jungheinrich |
| Hyster-Yale Materials Handling |
| Mitsubishi Logisnext |
| The Raymond Corporation |
| CLARK Material Handling |
| Hangcha Forklift |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's container throughput corridors transmit freight cost volatility directly into chassis pricing, compressing margins for European OEMs while amplifying price differentiation between lithium-ion and LPG platforms across German distribution networks.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement, with three-tier pricing separating METI-compliant premium units from standard electric configurations and economy-grade LPG holdovers. Price differentiation rests on certification grade and after-sales service bundling, where predictive maintenance subscriptions command premiums over fixed-interval contracts. Pricing pressure stems from lithium-ion cell cost compression narrowing upfront gaps with combustion alternatives. Third-party logistics operators exhibit highest price sensitivity due to contract renewal cycle pressures, while pharmaceutical distributors prioritize uptime reliability over acquisition cost.
Supply Chain Analysis
Supplier-financing facilities from Korean battery cell producers extend payment terms that ease working capital constraints for European chassis assemblers. Component sourcing concentrates in China, South Korea, and Japan for lithium cells, controllers, and rare-earth motors. Raw material dependencies center on cobalt, lithium carbonate, and copper windings. Single-source vulnerability in Chinese refining capacity exposes OEMs to forced stockpiling. Distribution runs through captive finance arms and authorized dealer networks, with direct-to-fleet channels gaining share among multi-contract operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins flatten as usage-based maintenance subscriptions and battery-as-a-service layers expand faster than equipment sales, reframing competitive advantage around recurring revenue capture.
For Market Incumbents: Build captive technician certification moats that lock out independent service providers. Deepen backward integration into motor and controller production to defend against Korean component suppliers. Expand high-voltage training infrastructure ahead of lithium-ion fleet penetration. METI efficiency benchmarks threaten import-dependent players lacking regenerative braking R&D.
For New Entrants and Emerging Players: India's PLI scheme subsidies create underpenetrated demand for compact electric units as domestic cold-chain infrastructure scales. Target Mumbai-Pune warehousing clusters with modular battery architectures that bypass Jungheinrich's tooling-change advantage. Partner with regional assembly facilities to navigate BIS certification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant material handling divisions lacking electrification roadmaps. Five-to-ten year viability favors specialists with captive finance arms and telematics platforms. Monitor solid-state battery pilot announcements as inflection signals for chassis weight redistribution enabling higher lift capacities.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Finance Arm Expansion | Toyota Material Handling locks multi-year grocery and pharmaceutical fleet contracts through usage-based pricing unbundling. |
| Backward Integration into Powertrain Components | Crown Equipment's in-house motor and controller production at its Ohio campus defends margin position against Korean suppliers. |
| Modular Battery Architecture Development | Jungheinrich enables cross-load-class power pack swapping without tooling changes, compressing downtime for 3PL operators. |
| Telematics Platform Integration | German distributors adopt predictive maintenance subscriptions that virtualize service contracts around usage metrics. |
| Regional Assembly Partnership Formation | European and Japanese OEMs navigate India's BIS certification and DGFT import regulations through local joint ventures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OEM financial disclosures, EU regulatory filings, and customs trade data. Interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads inform demand-side validation. Secondary sources include METI efficiency benchmark databases, OSHA enforcement records, and EU Green Deal implementation trackers. Bottom-up equipment shipment analysis triangulates against top-down logistics infrastructure investment flows.
Forecast inputs span powertrain architecture, load capacity tier, end-use facility type, and regional regulatory cluster across the analysis window. Segmentation dimensions model electric, diesel, LPG, and gasoline platforms against 1000 kg through 2500 kg ratings. CAGRs derive from logistic curve fitting of fleet replacement cycles and electrification penetration slopes. Cold-chain infrastructure buildout rates and lithium-ion cell cost trajectories serve as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state battery specialists or Chinese OEMs entering European markets would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.