
 Italy Construction Equipment Market | 2026-2036
Italy Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Construction Equipment Market Insights
Steel-reinforced composite booms is realigning cost structures for long-reach excavators and lattice cranes. Liebherr leverages its in-house steel fabrication to control boom supply chains from its Biberach plant. Komatsu anchors its position through integrated hydraulic component manufacturing. Volvo Construction Equipment differentiates via electrified compact loader architectures designed for urban emission zones.
Construction equipment comprises mobile and stationary machinery engineered for earthmoving, material handling, and structural assembly, with hydraulic systems operating at pressures exceeding 350 bar to generate breakout forces above 200 kN for excavation tasks. Excavators lead product type revenue as trenching and foundation work dominates Italian public works procurement. Electric technology claims the fastest expansion trajectory, constrained by battery energy density limits on machines above 20 metric tons. Diesel retains volume dominance in mining and heavy roadwork applications where continuous duty cycles exceed eight hours.
EU Stage V emissions standards enforced by the European Commission restrict particulate matter and nitrogen oxide outputs, compelling manufacturers to integrate selective catalytic reduction and diesel particulate filters. Italy's Ministry of Infrastructure and Transport ties concession financing to machinery age limits and telematics compliance for fleet visibility. BIS certification requirements for imported components add procedural steps for Asian suppliers entering through Trieste and Genoa ports. Stakeholders must weigh electrification capital commitments against residual value risk on diesel assets as municipal procurement rules tighten.
Market Dynamics
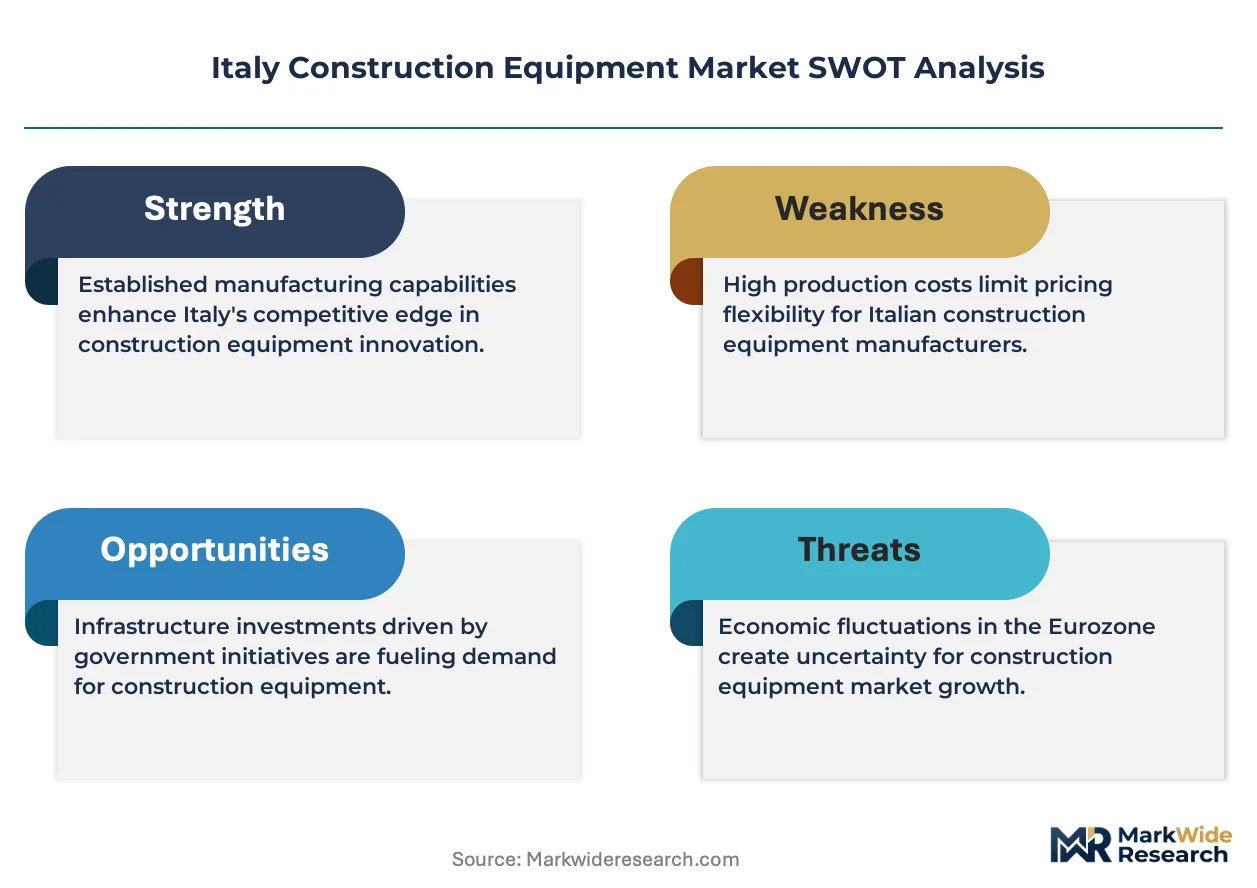
EU Green Deal emissions mandates are compressing diesel equipment residual values while forcing fleet operators toward electrified alternatives. The EU Stage V standards have eliminated the cost advantage of older machinery, creating a forced replacement cycle across Italian public works procurement.
Growth Catalysts
- EU Stage V compliance mandates:The European Commission's particulate matter and nitrogen oxide limits compel selective catalytic retrofits and new equipment purchases across municipal fleets.
- Northern industrial corridor tunneling demand:Highway modernization projects from Milan to Turin require specialized excavation platforms with extended reach specifications.
- Telematics-linked concession financing:Italy's Ministry of Infrastructure and Transport ties project funding to real-time fleet visibility systems, accelerating connected equipment adoption.
Market Restraints
- Battery energy density ceiling:Machines above 20 metric tons face eight-hour duty cycle limitations that diesel alternatives satisfy without interruption.
- Steel-reinforced composite boom supply concentration:In-house fabrication capabilities at German and Swiss plants limit third-party access to critical structural components.
- BIS certification friction for Asian imports:Bureau of Indian Standards procedural requirements add port clearance delays at Trieste and Genoa for non-EU component suppliers.
Strategic Opportunities
- Urban emission zone electrification:Compact loader architectures with zero-exhaust operation capture municipal procurement preference in Milan, Turin, and Bologna city centers.
- Telematics-as-a-service unbundling:Fleet operators now purchase equipment monitoring separately from hardware, opening recurring revenue streams for data analytics providers.
- PLI scheme component localization:India's production-linked incentive framework offers tariff advantages for hydraulic system manufacturers establishing domestic assembly.
Industry Challenges
- Electrification capex intensity:Battery pack integration and thermal management systems require 40-60% higher upfront investment versus conventional diesel platforms.
- Hydraulic technician scarcity:Specialized training for 350+ bar system maintenance lags equipment complexity, extending service response times in peripheral regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Construction Equipment Market |
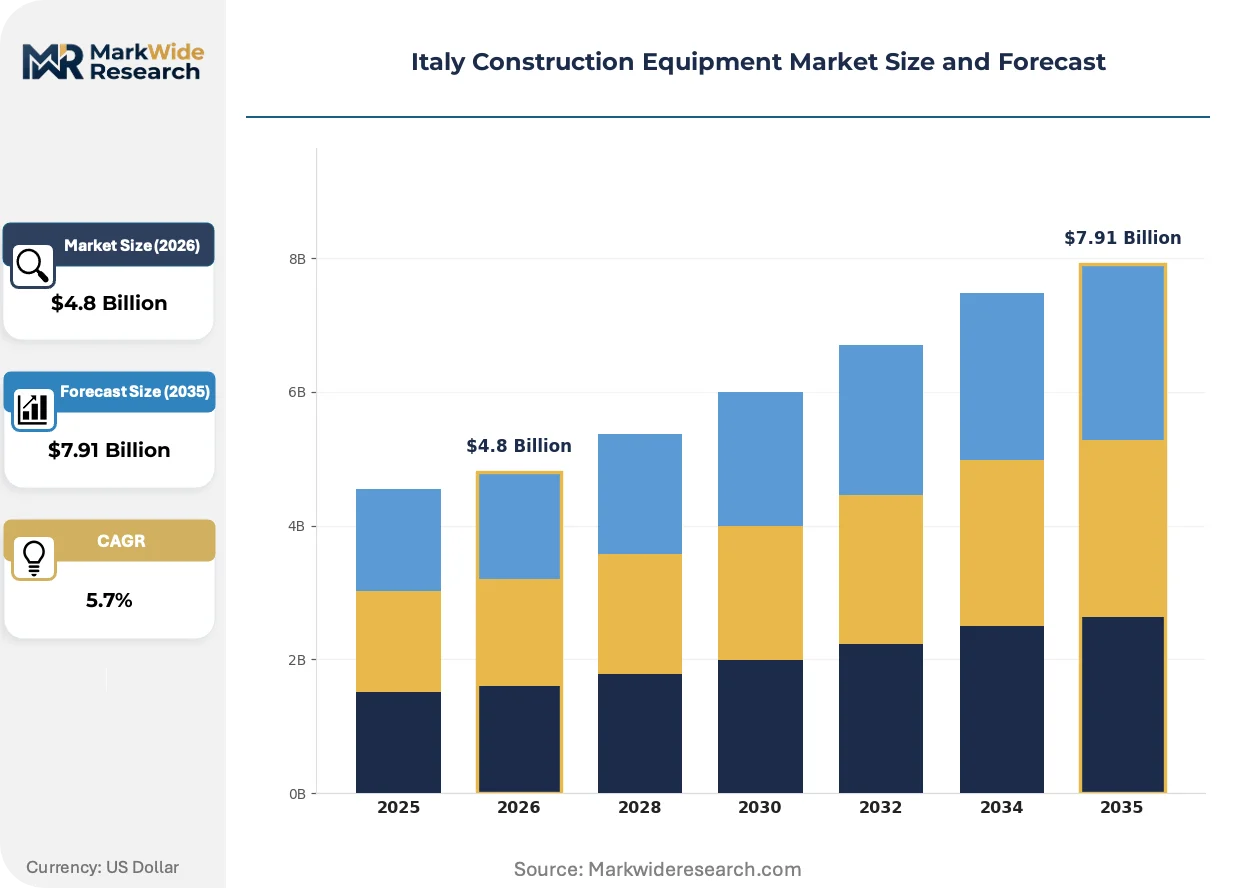
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Loaders Technology: Hydraulic, Electric, Pneumatic, Diesel End User: Contractors, Government, Infrastructure, Residential Application: Construction, Demolition, Mining, Roadwork |
| Companies Covered | Caterpillar, Liebherr, Hitachi Construction Machinery, Komatsu, JCB, Volvo Construction Equipment, CNH Industrial, SANY, XCMG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Construction Equipment Market Trends and Innovations
Equipment architecture is bifurcating between heavy diesel platforms for continuous mining duty and electrified compact systems for urban emission zones. This divergence is compressing the middle market for mid-size conventional machinery.
Electrified compact loader architectures are converging with urban emission zone mandates to reshape municipal procurement specifications. Milan and Turin public works departments now require zero-exhaust operation for street maintenance contracts. The technology is converging with battery swapping infrastructure to eliminate range anxiety for multi-shift operations.
EU Stage V emissions standards enforced by the European Commission restrict particulate matter outputs below 0.015 grams per kilowatt-hour. Manufacturers must integrate selective catalytic reduction and diesel particulate filters, adding €8,000-12,000 per unit in after-treatment costs. Heavy roadwork and mining applications absorb these premiums while urban operators migrate to electric alternatives.
Rental and leasing channels are displacing direct equipment purchases among mid-tier Italian contractors. Fleet operators now prioritize operational expenditure models that transfer residual value risk to lessors. This shift concentrates most visible in Lombardy and Veneto regions where project-based contracting dominates public works procurement.
Italy Construction Equipment Market Segmentation
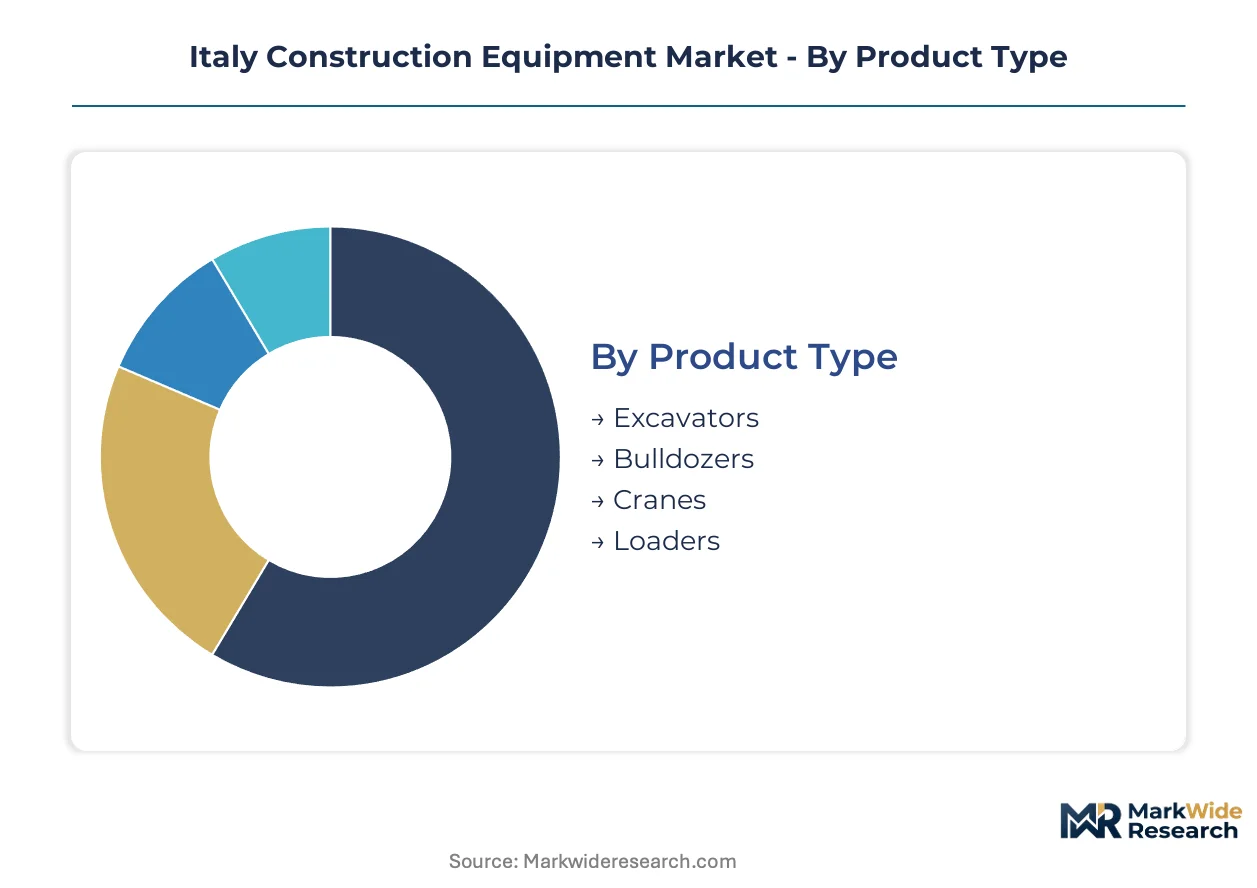
Equipment segmentation in Italy reflects divergent upgrade cycles across public works procurement. Municipal fleet managers prioritize electrification for urban contracts, while highway concessionaires extend diesel asset life through Stage V retrofits. Understanding these parallel replacement dynamics clarifies where manufacturers must align product portfolios with divergent customer economics.
Product Type:
Replacement cycles vary sharply by product category, with foundation-work platforms commanding priority investment in northern industrial corridors.
- Excavators:Hydraulic systems operating above 350 bar generate breakout forces exceeding 200 kN for trenching and foundation tasks. Demand concentrates in the Milan-Turin highway corridor where tunneling projects require extended-reach specifications and specialized boom architectures.
- Loaders:Compact loader designs with electrified architectures capture municipal procurement preference in Milan, Turin, and Bologna emission zones. Battery-swapping infrastructure is converging with these platforms to eliminate range anxiety for multi-shift street maintenance operations.
- Bulldozers:Continuous-duty mining and heavy roadwork applications sustain diesel dominance despite Stage V after-treatment premiums.
- Cranes:Steel-reinforced composite boom supply concentration limits third-party access to critical structural components from German and Swiss fabrication plants.
Excavators sit at the top of the volume ranking, with loaders climbing the fastest.
Technology:
Technology segmentation tracks capital intensity gradients, with premium electrification systems requiring 40-60% higher upfront investment than conventional platforms.
- Hydraulic:Integrated component manufacturing at pressures exceeding 350 bar defines competitive positioning for excavation and material handling tasks. Komatsu's captive hydraulic production anchors its supply chain control.
- Electric:Battery energy density ceilings constrain machines above 20 metric tons to sub-eight-hour duty cycles. Volvo Construction Equipment's compact loader architectures target urban emission zones where zero-exhaust operation is mandatory.
- Diesel:Selective catalytic reduction and particulate filter integration adds €8,000-12,000 per unit in after-treatment costs, compressing residual values on older assets.
- Pneumatic:Compressed air systems serve niche demolition applications where spark suppression requirements override efficiency considerations.
Diesel retains volume leadership, though electric platforms are gaining share fastest in municipal procurement.
End User:
Customer type segmentation reveals divergent procurement models, with rental channels displacing direct purchases among mid-tier contractors.
- Contractors:Project-based operators in Lombardy and Veneto prioritize operational expenditure models that transfer residual value risk to lessors.
- Government:Italy's Ministry of Infrastructure and Transport ties concession financing to telematics compliance and machinery age limits, accelerating connected equipment adoption.
- Infrastructure:Highway modernization projects from Milan to Turin require specialized excavation platforms with real-time fleet visibility systems.
- Residential:Smaller-scale developers face capital constraints that favor used equipment markets and short-term rental arrangements.
Infrastructure commands the largest equipment allocation, with government end-use expanding most quickly through concession-linked procurement mandates.
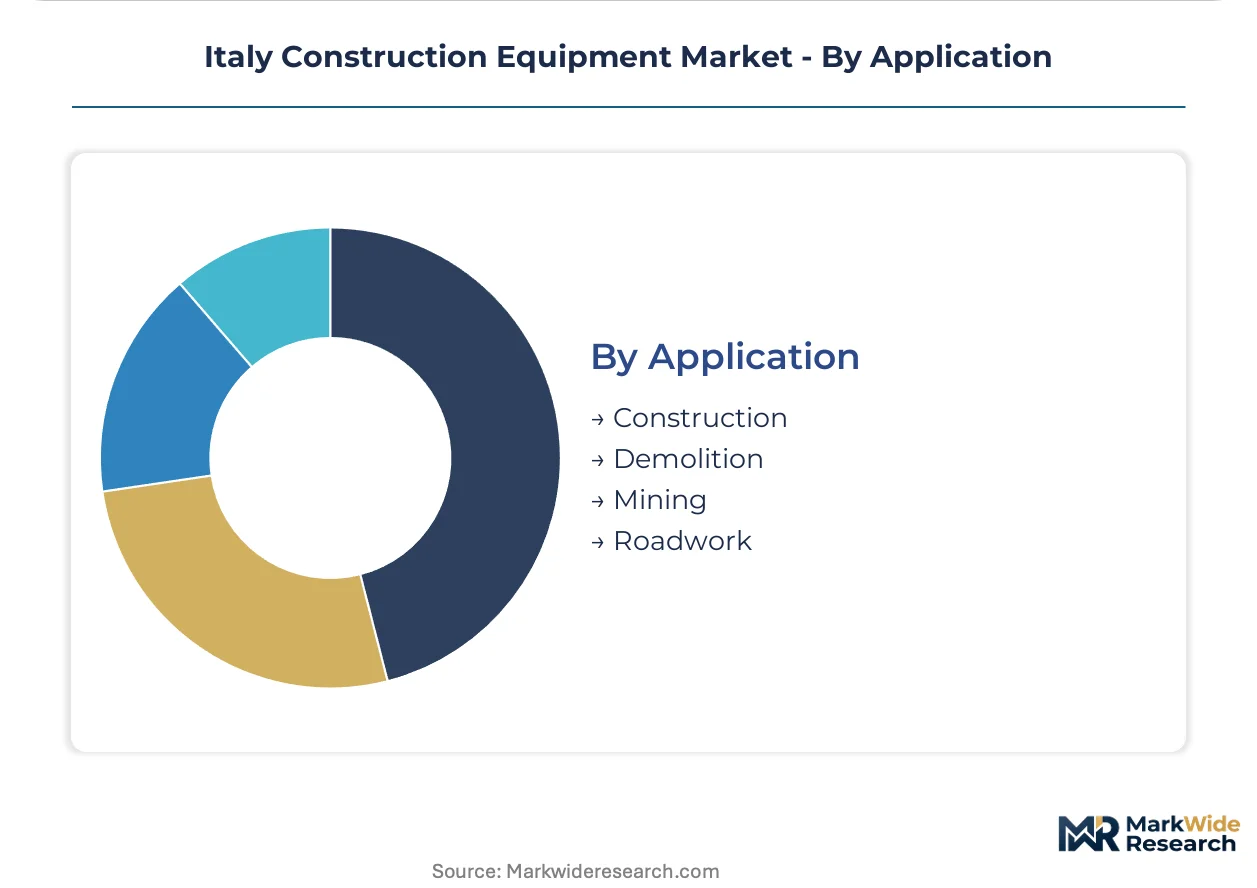
Application:
Application segmentation aligns with duty cycle characteristics that determine technology suitability and replacement timing.
- Construction:Foundation and structural assembly work dominates Italian public works procurement, with trenching specifications driving excavator demand.
- Roadwork:Continuous duty cycles exceeding eight hours sustain diesel platform economics despite Stage V compliance premiums.
- Mining:Heavy-duty extraction operations absorb after-treatment cost increases while resisting electrification due to energy density limitations.
- Demolition:Specialized pneumatic and hydraulic attachments serve controlled deconstruction tasks in dense urban environments.
Construction leads application-level volume, with roadwork showing the steepest expansion trajectory through northern corridor modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Milan-Turin industrial corridor anchors Italian construction equipment demand through tunneling and highway modernization projects. Northern regions concentrate fleet investments as EU Green Deal mandates accelerate equipment replacement cycles. Southern markets lag in electrification adoption due to infrastructure financing gaps.
Lombardy
Milan's metropolitan public works departments drive compact loader procurement for urban emission zone compliance. Italy's Ministry of Infrastructure and Transport ties concession financing to telematics compliance, accelerating connected equipment deployment. The Milan-Bergamo axis hosts the densest rental fleet concentration for project-based contracting.
Piedmont
Turin-based highway concessionaires sustain excavator demand for Alpine tunneling and corridor modernization. EU Stage V emissions standards enforced by the European Commission compel selective catalytic retrofits across diesel fleets. The Turin-Aosta corridor requires specialized extended-reach platforms for mountainous terrain excavation.
Veneto
Port infrastructure expansion at Venice and Trieste drives material handling equipment procurement. BIS certification requirements for imported components add procedural friction for Asian suppliers entering through Adriatic ports. The Verona-Vicenza industrial zone concentrates mid-tier contractors prioritizing operational expenditure models.
Emilia-Romagna
Bologna's municipal fleet electrification mandates reshape street maintenance procurement specifications. The region's agricultural machinery heritage supports hydraulic system maintenance capabilities for construction equipment servicing. Modena-Reggio Emilia hosts specialized boom fabrication subcontractors serving crane manufacturers.
Lazio
Rome's public works procurement concentrates on foundation equipment for heritage-sensitive urban excavation. Central government infrastructure spending flows through Lazio-based concessionaires with age-limit compliance requirements. The capital's rental market absorbs residual diesel assets displaced from northern emission zones.
Italy Construction Equipment Market Competitive Landscape
Global majors compete with regional champions across technology integration and supply chain control dimensions. The vendor base stratifies into three tiers: integrated hydraulic system manufacturers, electrification-focused platform specialists, and rental-channel-optimized volume players. Strategic differentiation centers on in-house steel fabrication capabilities and battery-swapping infrastructure partnerships. Consolidation pressure intensifies as EU Stage V compliance costs squeeze mid-scale fabricators without captive component supply.
Within the integrated manufacturing tier, Liebherr and Komatsu exemplify divergent approaches to supply chain control. Liebherr leverages its Biberach-based steel fabrication to anchor boom production internally. Komatsu's captive hydraulic component manufacturing secures system integration advantages. Volvo Construction Equipment occupies a position on the electrification vector through compact loader architectures. SANY and XCMG represent Chinese-scale manufacturers navigating BIS certification pathways into Italian ports.
| Leading Market Players |
|---|
| Caterpillar |
| Liebherr |
| Hitachi Construction Machinery |
| Komatsu |
| JCB |
| Volvo Construction Equipment |
| CNH Industrial |
| SANY |
| XCMG |
| Others |
Pricing and Supply Chain Analysis
EU Stage V emissions mandates for diesel particulate filters and selective catalytic reduction systems are forcing fleet operators toward electrified alternatives, compelling manufacturers to absorb €8,000-12,000 per unit in after-treatment costs while restructuring component sourcing around battery-swapping infrastructure partnerships.
Pricing Analysis
Input-cost pass-through from steel-reinforced composite booms and high-pressure hydraulic systems is stratifying equipment pricing across premium, standard, and economy tiers. Price differentiation rests on certification grade for EU Stage V compliance and captive in-house fabrication capabilities versus third-party component sourcing. Pricing pressure stems from electrification capex intensity requiring 40-60% higher upfront investment for battery-integrated platforms. Municipal procurement departments in Milan and Turin exhibit highest price sensitivity due to budget-constrained fleet renewal cycles, while highway concessionaires absorbing continuous-duty diesel premiums show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss steel fabrication plants controlling boom production for extended-reach excavators and lattice cranes. Geographic supply concentration centers on Germany for hydraulic system components, South Korea for battery cell technology, and China for steel-reinforced composite structural elements. Raw material dependencies include high-grade structural steel, lithium-ion battery packs, and specialized hydraulic fluids rated for 350+ bar operating pressures. Supply chain risk manifests as tariff exposure on Asian component imports through BIS certification delays at Trieste and Genoa ports. Distribution runs through rental and leasing channels displacing direct purchases among Lombardy and Veneto contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by municipal procurement departments mandating zero-exhaust operation for street maintenance contracts in Milan, Turin, and Bologna emission zones.
For Market Incumbents: Acquire battery-swapping infrastructure networks to anchor electrified compact loader positioning against emerging Asian scale manufacturers. Defensive consolidation must prioritize backward integration into high-pressure hydraulic component manufacturing to secure supply chain control as EU Stage V compliance costs squeeze mid-scale fabricators without captive production. Channel control through telematics-as-a-service unbundling creates recurring revenue insulation from residual value compression on diesel assets. For New Entrants and Emerging Players: Capture peripheral region service coverage gaps where hydraulic technician scarcity extends response times beyond acceptable thresholds for foundation-work contractors. White-space targets include Emilia-Romagna's agricultural machinery heritage zone for hydraulic system maintenance capabilities and Lazio's rental market absorption of residual diesel assets displaced from northern emission zones. Go-to-market execution should leverage India's PLI scheme component localization for tariff-advantaged hydraulic assembly entry through Adriatic ports. For Investors and Strategic Acquirers: Asymmetric upside sits with electrification-focused platform specialists possessing battery-swapping infrastructure partnerships and urban emission zone procurement relationships. Long-term viability over a 5-10 year window favors targets with proven municipal fleet conversion track records in Milan and Turin metropolitan areas. The signal to watch is concession financing approval velocity from Italy's Ministry of Infrastructure and Transport as an inflection indicator for connected equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Component Manufacturing | Komatsu's captive production model secures 350+ bar system supply chain control against third-party fabrication bottlenecks. |
| Battery-Swapping Infrastructure Partnership | Volvo Construction Equipment's compact loader architectures eliminate range anxiety for multi-shift municipal street maintenance operations. |
| Telematics-as-a-Service Unbundling | Fleet operators purchasing equipment monitoring separately from hardware open recurring revenue streams for data analytics providers. |
| PLI Scheme Component Localization | India's production-linked incentive framework offers tariff advantages for hydraulic system manufacturers establishing domestic assembly for Italian port entry. |
| Steel-Reinforced Composite Boom Fabrication Expansion | Liebherr's Biberach plant anchors internal boom supply chains against third-party access limitations from German and Swiss concentration. |
Research Methodology
Multiple input streams — primary interviews with fleet managers and maintenance directors, secondary validation through EU equipment registration databases and customs import records, and technical specification analysis from OEM product documentation — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed highway concession procurement officers, municipal public works directors, rental fleet operators, hydraulic system service technicians, and steel fabrication subcontractors. Secondary sources included Italy's Ministry of Infrastructure and Transport concession filings, European Commission emissions compliance registries, and port authority import clearance records from Trieste and Genoa.
Cross-referencing historical replacement cycle patterns against panel input from equipment procurement committees established the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user procurement model, and application duty cycle characteristics. CAGRs were derived through equipment unit deployment tracking and capital expenditure flow analysis. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and municipal electrification mandate adoption curves.
Regulatory enforcement delays, battery energy density breakthrough timing, and concession financing approval velocity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about emissions standard adherence and infrastructure spending authorization flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Jackhammer Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Smart Crane Market
Construction Equipment
Utility Locator Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Foundry Sand Cleaning Machine Market