
 Remote Patient Monitoring Software and Services Market | 2026-2036
Remote Patient Monitoring Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Patient Monitoring Software and Services Market Intelligence
North America is reshaping competitive dynamics in remote patient monitoring as health systems scale connected care infrastructure. Teladoc Health leverages its virtual care platform to anchor chronic disease management programs across integrated delivery networks. Medtronic Plc. sustains technology leadership through its FDA-cleared cardiac implantable devices with embedded remote transmission capabilities. Philips Healthcare dominates hospital-grade monitoring with centralized command centers that aggregate multi-parameter patient data streams.
Remote patient monitoring software and services encompass digital platforms, wearable-integrated applications, and clinician-facing dashboards that collect, transmit, and analyze physiological data outside traditional care settings. These systems rely on Bluetooth Low Energy and cellular modems to push biometric readings to cloud architectures, enabling real-time alerting and longitudinal trend analysis for chronic condition management. Cloud-based solutions lead deployment architecture as health systems prioritize scalable infrastructure with HIPAA-compliant data residency controls. AI analytics represents the fastest-expanding technology segment, with machine learning classifiers reducing false-positive alert burdens by processing multi-modal biometric inputs. Wearable devices anchor hardware attachment rates, though software platforms capture disproportionate recurring revenue through per-patient-per-month licensing models.
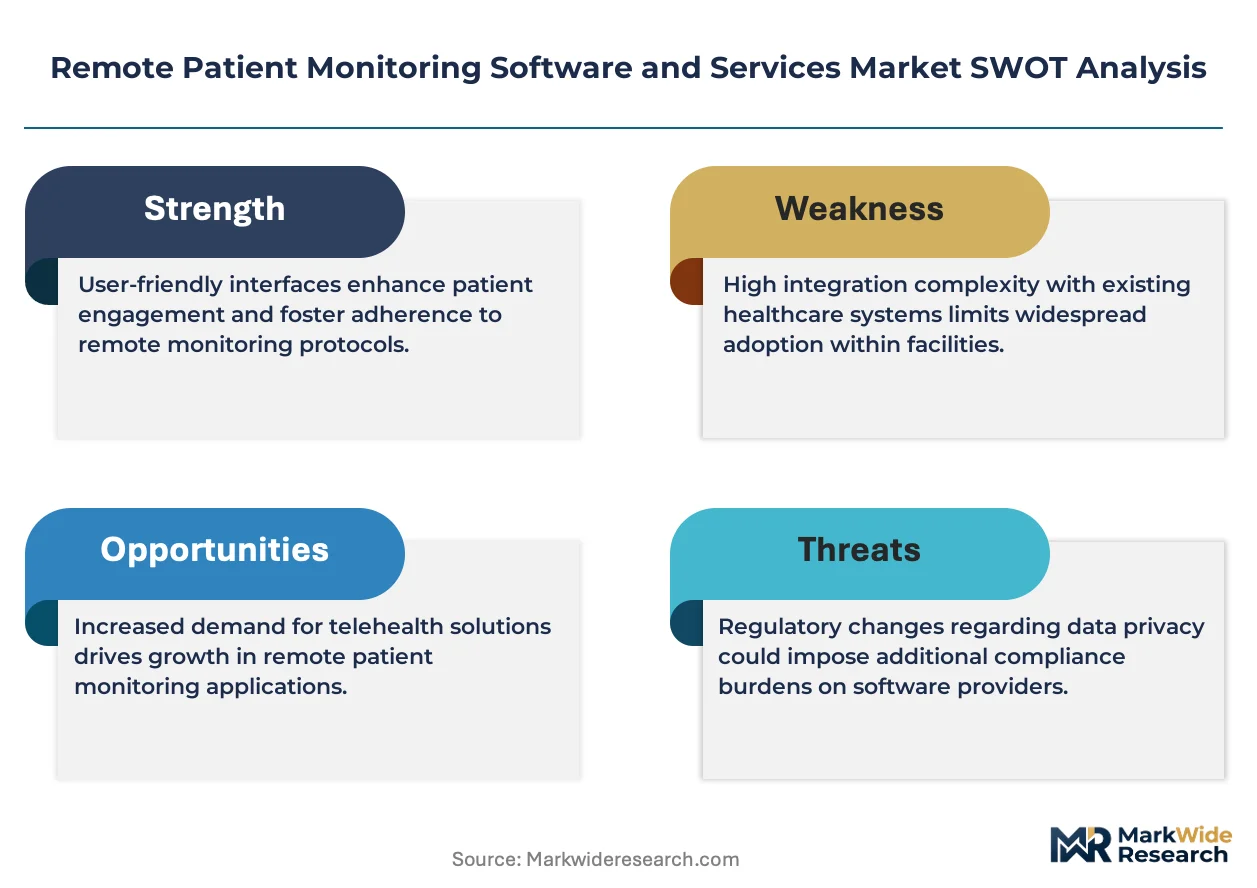
FDA premarket clearance pathways and CMS remote therapeutic monitoring reimbursement codes shape product development timelines and go-to-market economics for vendors. HIPAA security rule enforcement and state-level telehealth parity laws create compliance complexity that favors established platforms with dedicated regulatory affairs functions. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms as the agency transitions toward predetermined change control plans for machine learning-based software as a medical device.
Market Dynamics
CMS reimbursement expansions for remote therapeutic monitoring codes are restructuring provider procurement economics, shifting capital allocation toward per-patient-per-month software licensing over episodic hardware purchases. This payment model transformation is compressing vendor sales cycles while elevating platform stickiness as the primary competitive battleground.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for AI-enabled cardiac monitors compress time-to-revenue for algorithm developers, channeling venture funding toward predicate-cleared platform extensions.
- Integrated Delivery Networks:Health systems spanning multiple states deploy enterprise-wide remote monitoring infrastructure to capture shared savings under value-based care contracts, creating consolidated procurement demand.
- Bluetooth Low Energy:Low-power wireless protocols enable continuous biometric streaming from wearable patches without patient smartphone dependency, expanding addressable populations to elderly and rural demographics.
Market Restraints
- HIPAA Security Rule Enforcement:State attorney general actions against cloud data residency violations impose multimillion-dollar penalties that disproportionately burden mid-sized platform vendors lacking dedicated compliance infrastructure.
- Cellular Modem Supply Concentration:Dependency on single-source LTE-M chipset suppliers creates hardware production bottlenecks during semiconductor allocation cycles, extending device lead times.
- Clinical Validation Burden:Peer-reviewed evidence requirements for algorithm performance claims slow FDA 510(k) clearance timelines, consuming 18-24 months of premarket clinical data collection.
Strategic Opportunities
- Acute Care Discharge Protocols:Hospital-at-home programs in the United States mandate post-discharge monitoring bundles, opening per-episode reimbursement streams distinct from chronic disease management.
- EU MDR Class IIa Pathways:European software-as-medical-device certifications create regulatory moats for platforms achieving notified body conformity, locking out non-compliant competitors.
- Machine Learning and Edge Computing Convergence:On-device inference reduces cloud transmission costs while enabling real-time arrhythmia detection without network latency, differentiating premium platform tiers.
Industry Challenges
- Interoperability Engineering Talent:Scarcity of developers fluent in HL7 FHIR and SMART on FHIR standards constrains health system integration timelines, extending implementation projects.
- False-Positive Alert Fatigue:Clinician workflow disruption from unfiltered algorithm outputs erodes platform adoption rates, requiring dedicated clinical informaticist resources for alert tuning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Patient Monitoring Software and Services Market |
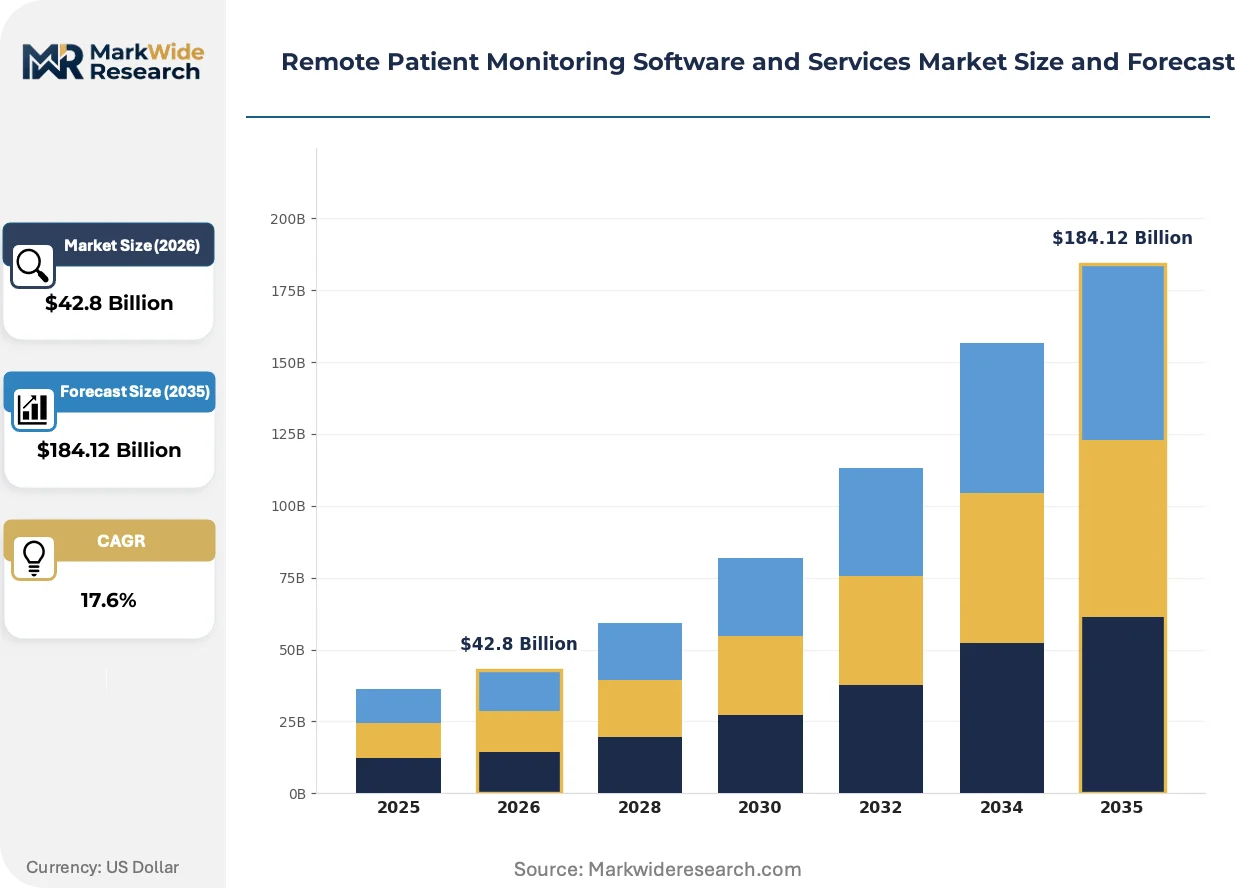
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $184.12 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
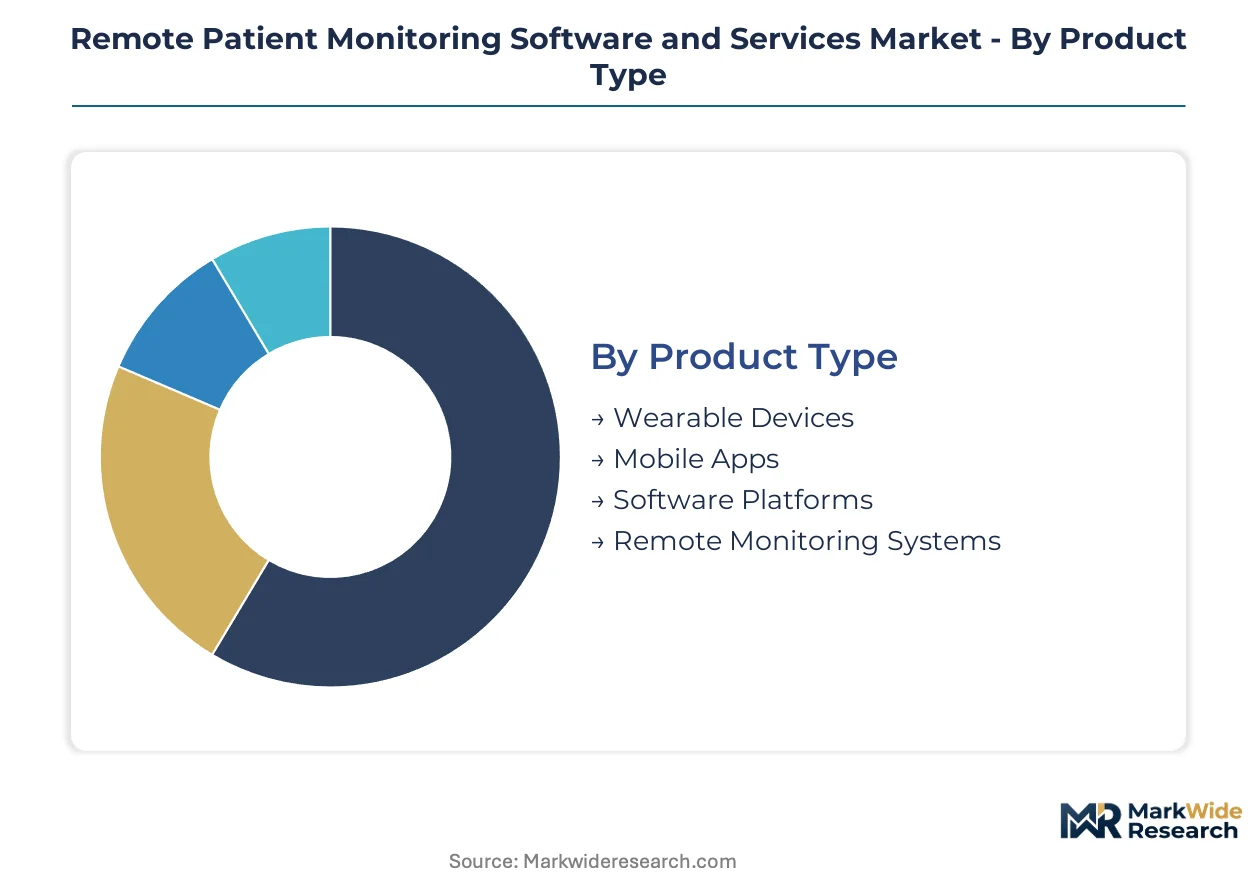
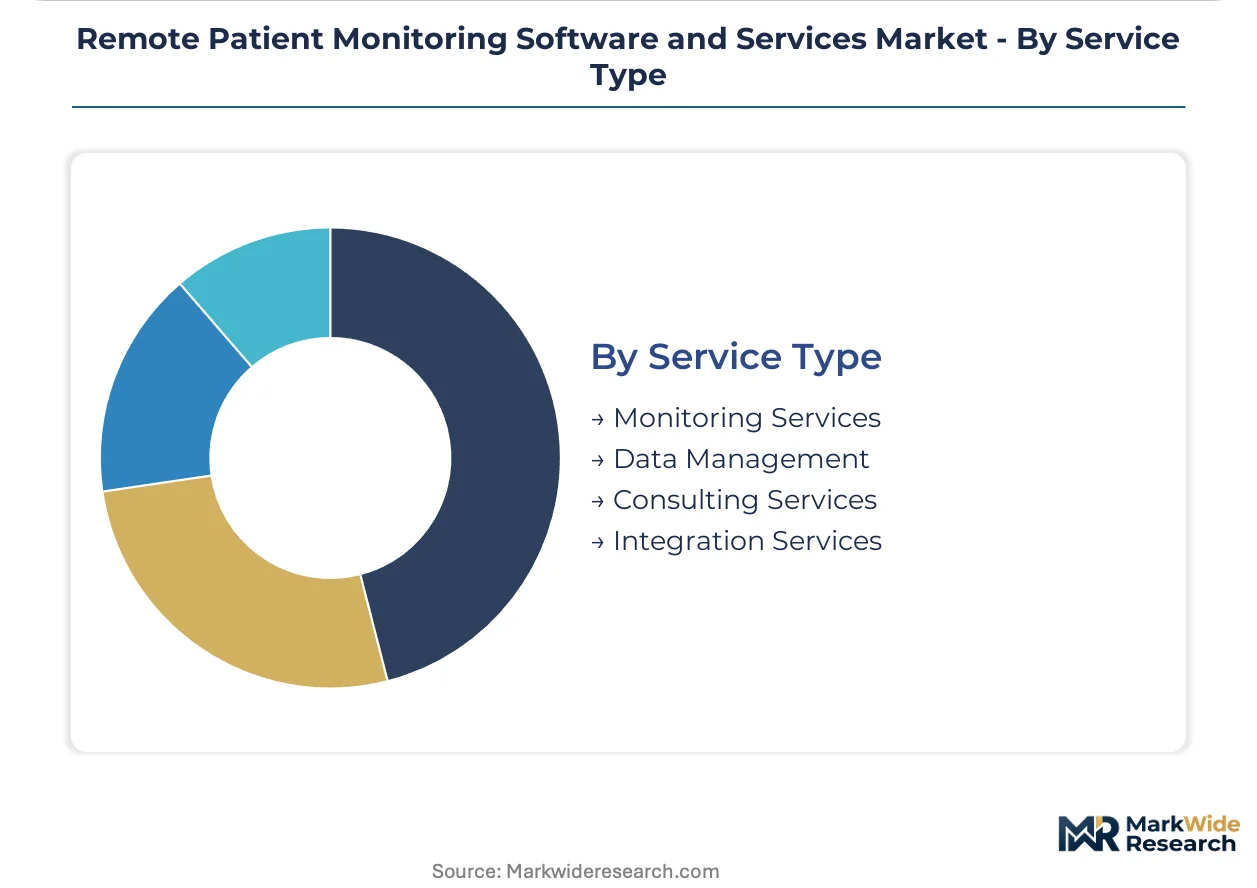
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Software Platforms, Remote Monitoring Systems End User: Patients, Healthcare Providers, Research Institutions, Caregivers Technology: Cloud-Based Solutions, IoT Devices, AI Analytics, Telehealth Solutions Service Type: Monitoring Services, Data Management, Consulting Services, Integration Services |
| Companies Covered | Teladoc Health, Inc., Medtronic Plc., GE Healthcare, Philips Healthcare, Siemens Healthineers AG, BioIntelliSense, OMRON Healthcare, Caretaker Medical, Biofourmis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Patient Monitoring Software and Services Market Strategic Shifts & Innovations
Artificial intelligence classifiers are compressing alert validation workflows while edge computing architectures redistribute processing loads away from centralized cloud infrastructure. These shifts are redefining platform architecture requirements and vendor capability investments.
Continuous glucose monitoring platforms with embedded predictive algorithms are rendering obsolete episodic fingerstick-based diabetes management protocols. Endocrinology practices affiliated with accountable care organizations deploy these systems at scale, capturing HbA1c reduction bonuses under Medicare Advantage contracts. The structural consequence is commoditization of hardware sensors while software analytics layers capture disproportionate margin expansion.
FDA guidance on predetermined change control plans for machine learning-based software as a medical device is formalizing post-market algorithm update pathways. Device manufacturers must now submit modification protocols during initial clearance, enabling iterative model improvement without supplemental 510(k) submissions. Cardiac monitoring platforms with embedded arrhythmia classifiers are first movers, leveraging this framework to compress competitive response cycles.
Health system procurement committees now mandate API-first architecture and health data exchange certification as table stakes for vendor qualification. Traditional point-solution vendors with closed data models face displacement by modular platforms enabling third-party analytics integration. This specification tightening is most visible in United States integrated delivery networks consolidating vendor panels under enterprise master service agreements.
Remote Patient Monitoring Software and Services Market Segmentation
Segmentation in remote patient monitoring reveals distinct technology maturity curves and reimbursement pathways that dictate vendor investment priorities. Cloud-native platforms and AI-enabled analytics command premium pricing while hardware commoditization pressures wearable margins. Understanding these segment boundaries enables precise positioning across health system procurement committees and payer contracting strategies.
Product Type:
Mature segments dominate current revenue flows while emerging categories reshape deployment architectures.
- Software Platforms:Centralized dashboards aggregate multi-parameter biometric streams from disparate device fleets, enabling longitudinal trend analysis and automated care escalation protocols. United States integrated delivery networks deploy these systems enterprise-wide to capture shared savings under Medicare Advantage value-based contracts, with per-patient-per-month licensing models displacing capital expenditure cycles.
- Wearable Devices:Bluetooth Low Energy-enabled patches and wrist-worn sensors provide continuous glucose, cardiac, and respiratory monitoring without smartphone dependency. Hardware attachment rates concentrate in elderly and rural demographics where cellular modem connectivity bypasses broadband gaps, though sensor commoditization compresses margins toward single-digit territory.
- Mobile Apps:Patient-facing interfaces deliver medication adherence prompts and symptom surveys with embedded FHIR data exchange capabilities.
- Remote Monitoring Systems:Hospital-grade telemetry units with centralized command centers aggregate intensive care-level monitoring for acute care discharge protocols.
Software Platforms handles the majority of throughput; AI Analytics within this category is expanding most quickly on share.
End User:
Customer archetypes span direct clinical deployment through intermediary research channels with diverging procurement authority.
- Healthcare Providers:Hospital systems and physician practices purchase enterprise licenses with mandatory API-first architecture and health data exchange certification. Accountable care organizations in the United States mandate these platforms for chronic disease management bonus capture, with procurement committees consolidating vendor panels under master service agreements.
- Patients:Direct-to-consumer channels bypass institutional procurement through wearable-integrated subscription services. Demand concentrates in diabetes and cardiac populations seeking continuous monitoring without clinic dependency, though out-of-pocket payment sensitivity limits addressable market penetration.
- Research Institutions:Academic medical centers license de-identified data streams for algorithm training and clinical validation studies.
- Caregivers:Family members and home health aides utilize simplified alert dashboards for dependent monitoring.
Healthcare Providers dominates current revenue; Patients represents the steepest expansion trajectory as direct-pay models mature.
Technology:
Deployment architecture choices determine scalability ceilings and regulatory compliance burdens across jurisdictions.
- Cloud-Based Solutions:HIPAA-compliant data residency controls with scalable infrastructure support multi-tenant health system deployments. United States hospital networks prioritize these architectures for disaster recovery and interoperability with existing EHR systems, though state attorney general enforcement actions impose multimillion-dollar penalties for residency violations.
- AI Analytics:Machine learning classifiers process multi-modal biometric inputs to reduce false-positive alert burdens and enable predictive deterioration detection. FDA predetermined change control plans for software as a medical device formalize post-market algorithm updates, compressing competitive response cycles for cardiac arrhythmia platforms.
- IoT Devices:Cellular modem-equipped sensors enable standalone operation without patient smartphone pairing.
- Telehealth Solutions:Synchronous video integration with asynchronous monitoring data creates hybrid care models.
Cloud-Based Solutions anchors current deployment volume; AI Analytics is gaining share fastest as health systems prioritize alert accuracy.
Service Type:
Revenue model differentiation separates recurring operational services from discrete implementation engagements.
- Monitoring Services:Continuous clinical oversight with registered nurse triage and physician escalation protocols operates on per-patient-per-month contracts. United States hospital-at-home programs mandate these bundles for post-discharge episodes, opening reimbursement streams distinct from chronic disease management under CMS remote therapeutic monitoring codes.
- Data Management:De-identification, warehousing, and analytics pipeline maintenance supports research and quality improvement initiatives. Academic medical centers concentrate demand for longitudinal cohort datasets, with HIPAA security rule compliance requirements favoring vendors with dedicated regulatory affairs infrastructure.
- Consulting Services:Workflow redesign and clinical informaticist training optimize alert tuning and adoption.
- Integration Services:HL7 FHIR and SMART on FHIR connectivity engineering connects disparate EHR systems.
Monitoring Services captures the majority of recurring revenue; Integration Services is climbing the fastest as interoperability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations and CMS reimbursement expansions anchor United States market leadership, while regulatory divergence across jurisdictions creates distinct competitive moats for vendors achieving multi-territory clearances.
United States
Integrated delivery networks spanning multiple states deploy enterprise-wide remote monitoring infrastructure to capture shared savings under Medicare Advantage value-based contracts. CMS remote therapeutic monitoring codes restructure procurement economics toward per-patient-per-month software licensing. Hospital-at-home programs in the Northeast Corridor and California mandate post-discharge monitoring bundles, opening distinct reimbursement streams from chronic disease management.
Germany
EU MDR Class IIa software-as-medical-device certifications create regulatory barriers favoring established platforms with dedicated notified body relationships. The country's statutory health insurance system pilots DiGA (Digital Health Applications) reimbursement for connected care solutions. Medical technology clusters in Bavaria and Baden-Württemberg concentrate algorithm development and clinical validation infrastructure.
United Kingdom
NHS England's virtual ward programs mandate remote monitoring for post-acute discharge, consolidating procurement through integrated care systems. MHRA streamlined pathways for software as a medical device accelerate clearance timelines relative to continental counterparts. London and Greater Manchester health innovation clusters anchor healthtech venture funding and pilot-to-scale deployment pipelines.
Japan
PMDA guidance on machine learning-based software as a medical device formalizes predetermined change control plans for algorithm updates. METI subsidies for aging-in-place technologies expand addressable populations beyond hospital-centric deployments. The Kanto region around Tokyo concentrates health system pilot programs and pharmaceutical partnership networks for chronic disease monitoring.
Australia
TGA software as a medical device framework aligns with IMDRF international convergence principles, reducing multi-territory compliance burdens for cleared platforms. The Medical Research Future Fund channels capital toward remote monitoring clinical trials in rural and Indigenous health settings. Sydney and Melbourne health innovation precincts aggregate digital health venture capital and academic medical center validation partnerships.
Remote Patient Monitoring Software and Services Market Key Industry Players
Virtual care platforms and implantable device manufacturers split the market between software-centric and hardware-integrated service models. The vendor base concentrates around three strategic archetypes: enterprise software platforms licensing per-patient-per-month, medical device incumbents embedding remote transmission in implantable hardware, and point-solution specialists targeting discrete clinical workflows. M&A activity focuses on algorithm capability acquisition, while strategic partnerships between device manufacturers and cloud infrastructure providers accelerate multi-tenant health system deployments.
Among United States-based platforms, Teladoc Health exemplifies the virtual care archetype with chronic disease management program anchoring across integrated delivery networks. Medtronic Plc. and Philips Healthcare represent divergent hardware-integrated strategies, with the former emphasizing implantable cardiac devices and the latter commanding hospital-grade centralized monitoring infrastructure. These three anchors illustrate the competitive tension between software recurring revenue models and device-plus-service bundled economics.
| Leading Market Players |
|---|
| Teladoc Health, Inc. |
| Medtronic Plc. |
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers AG |
| BioIntelliSense |
| OMRON Healthcare |
| Caretaker Medical |
| Biofourmis |
| Others |
Cost & Logistics Intelligence
Shenzhen's sensor manufacturing corridor dictates downstream pricing power for Bluetooth Low Energy modules, with capacity utilization swings transmitting directly into hardware margin compression for mid-tier wearable vendors.
Pricing Analysis
United States-European Union price spreads exceed forty percent for cloud-native platforms, reflecting HIPAA compliance overhead and FDA 510(k) clearance amortization. Three-tier pricing structure across premium, standard, and economy levels segments by AI analytics sophistication and alert tuning services. Pricing pressure stems from sensor commoditization in glucose monitoring patches. Direct-to-consumer subscribers exhibit highest price sensitivity; integrated delivery networks prioritize platform stickiness over unit cost.
Supply Chain Analysis
Cellular modem chipsets draw from Taiwan, South Korea, and United States fabrication facilities, with LTE-M baseband processors and MEMS biometric sensors anchoring bill-of-materials costs. Single-source dependency on TSMC advanced nodes for edge-AI inference chips concentrates vulnerability. Distribution runs through medical device distributors and direct health system contracting teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in remote patient monitoring hinge on FHIR-native interoperability, with health system procurement committees now mandating API-first architecture as table stakes for vendor qualification.
For Market Incumbents: Build regulatory moats through FDA predetermined change control plans for machine learning-based software as a medical device. Secure backward integration into cellular modem supply through long-term offtake agreements with Qualcomm and MediaTek. Defend against point-solution disintermediation by embedding third-party analytics marketplaces within core platforms. For New Entrants and Emerging Players: Build out hospital-at-home monitoring bundles for United States acute care discharge protocols, where per-episode reimbursement streams remain underpenetrated by established chronic disease vendors. Target direct-to-consumer cardiac monitoring subscriptions in Medicare Advantage populations. Pursue white-label AI analytics licensing to Tier 2 device manufacturers lacking in-house algorithm development. For Investors and Strategic Acquirers: Long-term, this sits as a data-network-effects play because platform value compounds with each additional health system node and longitudinal patient record. Prioritize acquisition targets with de-identified data repositories exceeding one million patient-years for algorithm training. Watch CMS remote therapeutic monitoring code expansions as reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Enables iterative algorithm updates without supplemental 510(k) filings for cardiac arrhythmia classifiers. |
| Hospital System Partnership | Locks in enterprise-wide deployment through Medicare Advantage shared savings contract alignment. |
| Platform Integration | Consolidates vendor panels under master service agreements via HL7 FHIR and SMART on FHIR certification. |
| Acquisition of Specialist Firm | Addresses interoperability engineering talent scarcity through targeted algorithm and integration capability purchases. |
| Reimbursement Strategy | Captures CMS remote therapeutic monitoring code economics through per-patient-per-month contracting models. |
Research Approach
Operator-level perspectives from hospital CIOs, biomedical engineers, GPO contracts managers, and clinical informaticists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and GPO contract repositories. Bottom-up patient-volume modeling and top-down health system IT spending analysis were triangulated for cross-verification.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions including deployment architecture, end-user type, technology tier, and service model. CAGRs derived from regression analysis of historical adoption curves and reimbursement policy trajectories. Algorithm performance validation requirements and cellular modem supply constraints served as industry-specific forecast inputs.
Stress conditions across FDA clearance timelines, CMS code reimbursement rates, and semiconductor allocation cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding health system consolidation pace and value-based contract penetration. Cross-checking against hospital capital expenditure surveys and digital health venture funding databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Asthma Monitoring Devices Market