
 Europe Respiratory Monitoring Market | 2026-2036
Europe Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Respiratory Monitoring Market Foresight
The EU Medical Device Regulation is restructuring the cost-of-entry calculus for respiratory monitoring manufacturers seeking CE marking across member states. Philips leverages its integrated diagnostics platform to sustain hospital loyalty across the Netherlands and Germany. Medtronic anchors its European position through specialized cardiac-respiratory convergence devices. Drägerwerk competes on manufacturing scale in critical-care ventilator segments where German engineering standards dominate procurement specifications.
Europe respiratory monitoring encompasses devices and systems that measure pulmonary function, gas exchange, and respiratory mechanics through sensors detecting airflow, pressure, oxygen saturation, and carbon dioxide levels with precision thresholds typically spanning 0-100 liters per minute for spirometry and 70-100% SpO2 accuracy ranges. These technologies serve chronic disease management, perioperative surveillance, and home-based rehabilitation by delivering real-time biometric streams to clinical decision-support systems. Wearable devices and ventilators capture divergent margin pools, with the former attracting digital health investment while the latter remains concentrated in long-term hospital service contracts. Cloud-based and mobile application technologies are expanding fastest among technology segments as reimbursement frameworks in France and Italy begin recognizing remote therapeutic monitoring codes.
EMA harmonization efforts and the EU AI Act are converging to reshape software-as-medical-device classifications for algorithmic respiratory diagnostics, while GDPR imposes strict data-localization requirements on cross-border patient monitoring networks. The F-Gas Regulation additionally constrains refrigerant-dependent respiratory gas analyzers, redirecting R&D toward solid-state sensor architectures. Stakeholders must monitor how notified body capacity constraints in Germany and France delay MDR certification timelines for novel monitoring platforms.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines for connected respiratory devices while simultaneously fragmenting certification pathways across notified body capacity constraints in Germany and France.
Growth Catalysts
- Remote Therapeutic Monitoring Reimbursement:France and Italy now recognize specific billing codes for home-based respiratory surveillance, accelerating hospital procurement of cloud-connected platforms for post-acute COPD management.
- F-Gas Regulation Phase-Down:The EU's refrigerant constraints on respiratory gas analyzers are redirecting R&D investment toward solid-state sensor architectures with lower maintenance profiles.
- Industrial Healthcare Cluster Density:Germany's university hospital networks in Baden-Württemberg and Bavaria pilot integrated respiratory monitoring platforms that standardize multi-site data interoperability.
Market Restraints
- Notified Body Bottlenecks:MDR certification delays in Germany and France extend commercialization timelines for novel algorithmic diagnostics by 12-18 months.
- GDPR Data Localization:Cross-border patient monitoring networks face architectural constraints requiring sovereign cloud infrastructure in each member state.
- Reimbursement Fragmentation:Divergent national health technology assessment processes between the UK, France, and Germany prevent unified pricing strategies for wearable respiratory devices.
Strategic Opportunities
- Post-Acute Care Integration:Hospital-at-home programs in the Netherlands and Belgium create demand for portable capnography and remote spirometry platforms with automated alert triage.
- EU AI Act Compliance Services:Software-as-medical-device manufacturers require third-party validation for algorithmic respiratory diagnostics, opening consultative revenue streams.
- Perioperative Surveillance Convergence:Cardiac-respiratory monitoring integration in German surgical suites creates specification pull-through for combined sensor platforms.
Industry Challenges
- Cybersecurity Validation Talent:MDR Annex I requirements for connected devices outpace the supply of clinical engineers with IEC 62304 and ISO 27001 dual competency.
- Legacy System Interoperability:Hospital information systems in France and Italy use non-standard data formats that resist direct API integration with cloud-based respiratory platforms.
- Clinical Evidence Generation Costs:Post-market surveillance obligations under MDR Article 83 require continuous patient registry maintenance that strains mid-cap manufacturer budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Respiratory Monitoring Market |
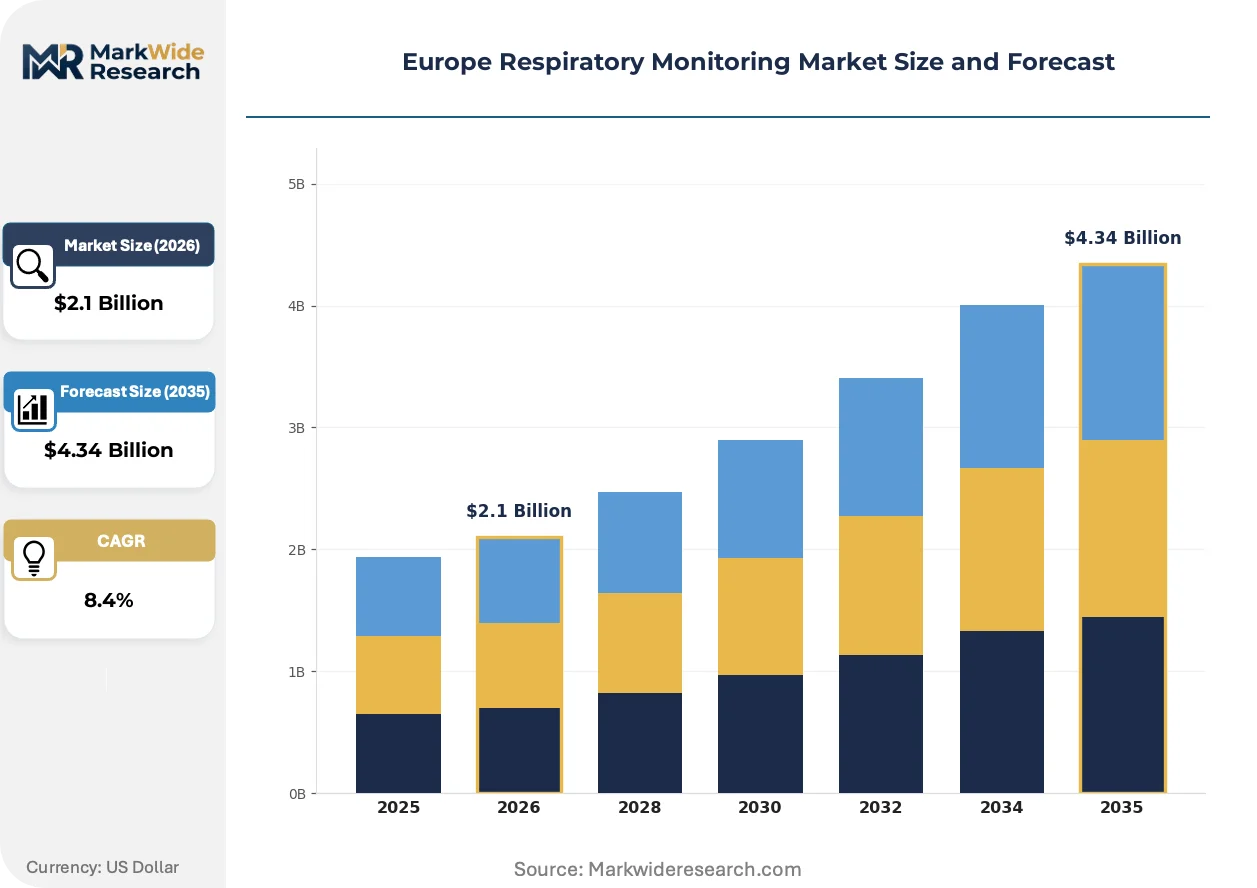
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Ventilators, Spirometers, Peak Flow Meters Technology: Bluetooth, Wi-Fi, Cloud-Based, Mobile Application End User: Clinics, Home Care Settings, Hospitals, Rehabilitation Centers Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Apnea, Lung Function Testing |
| Companies Covered | Koninklijke Philips N.V., Medtronic, GE Healthcare, Drägerwerk AG & Co. KGaA, ResMed, Getinge, Masimo, Nihon Kohden Corporation, COSMED, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Respiratory Monitoring Market Shifts & Advancements
Algorithmic diagnostics and solid-state sensing architectures are displacing legacy electrochemical and refrigerant-dependent measurement systems across European respiratory monitoring procurement specifications.
Photoplethysmography-based respiratory rate estimation is converging with pulse oximetry in wearable form factors. Dutch home care providers and German rehabilitation clinics are piloting these combined sensors for nocturnal hypoxemia surveillance. The technology is converging with existing remote patient monitoring contracts to reduce device count per patient while maintaining clinical-grade accuracy thresholds.
The EU AI Act's risk classification framework for software-as-medical-device is forcing algorithm developers to pre-validate training datasets across diverse European demographic cohorts. This regulatory pressure is compressing development timelines for machine-learning-based respiratory pattern recognition. French notified bodies are establishing specialized review pathways for high-risk AI diagnostics, creating first-mover certification advantages for compliant submitters.
Hospital procurement departments in Germany and the UK are unbundling device acquisition from long-term service agreements for ventilator platforms. Independent service organizations are capturing maintenance contracts previously held by original equipment manufacturers, particularly for devices outside warranty periods. This disintermediation is most visible in NHS England's framework agreements, where third-party technical service providers now qualify for critical-care equipment support contracts.
Europe Respiratory Monitoring Market Segmentation
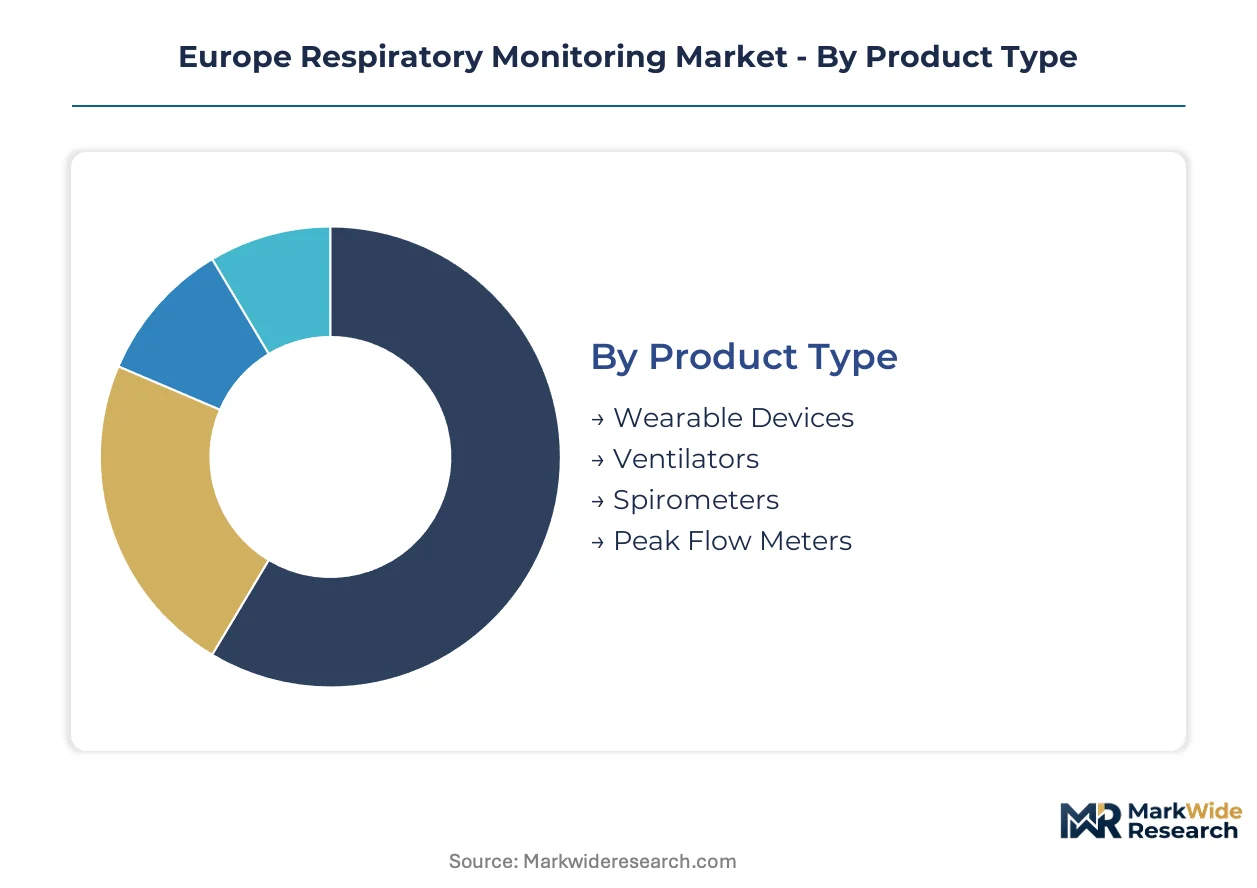
Respiratory monitoring procurement in Europe fragments across device sophistication tiers, connectivity protocols, and care setting economics. Understanding these divides reveals where MDR compliance costs concentrate and which segments attract cloud-platform investment.
Product Type:
Wearable devices command premium pricing through digital health channels while ventilators anchor hospital service contracts at volume scale.
- Wearable Devices:Photoplethysmography and accelerometer-based units estimate respiratory rate and oxygen saturation through wrist or chest-worn form factors. Dutch home care providers and German rehabilitation clinics pilot these for nocturnal hypoxemia surveillance, though reimbursement fragmentation across France, Italy, and the UK limits unified pricing strategies.
- Ventilators:Critical-care platforms incorporate flow sensors, pressure transducers, and capnography modules for mechanical ventilation management. German university hospital networks in Baden-Württemberg and Bavaria standardize procurement specifications around these devices, where engineering standards dominate multi-site tenders and long-term service agreements lock in manufacturer relationships.
- Spirometers:Handheld or desktop units measure forced expiratory volume and peak expiratory flow through pneumotachograph or turbine sensors.
- Peak Flow Meters:Mechanical or electronic devices track maximum airflow for asthma self-management in home and clinic settings.
Today's leader: Ventilators. Tomorrow's challenger: Wearable Devices.
Technology:
Cloud infrastructure investment separates high-margin platform plays from commodity connectivity modules.
- Cloud-Based:Centralized data architectures enable real-time biometric streaming to clinical decision-support systems across hospital networks. France and Italy now recognize specific remote therapeutic monitoring billing codes, accelerating hospital procurement of these platforms for post-acute COPD management despite GDPR data localization requirements forcing sovereign cloud infrastructure in each member state.
- Mobile Application:Software interfaces on iOS and Android devices display trends, generate alerts, and facilitate patient-clinician communication. The EU AI Act's risk classification framework forces algorithm developers to pre-validate training datasets across diverse European demographic cohorts, compressing development timelines for machine-learning-based respiratory pattern recognition in these interfaces.
- Bluetooth:Short-range wireless protocol connecting peripheral sensors to smartphones or bedside monitors.
- Wi-Fi:Higher-bandwidth connectivity for continuous streaming in hospital or residential settings with robust infrastructure.
Cloud-Based platforms capture the steepest expansion trajectory as reimbursement frameworks mature.
End User:
Acute care concentration in Germany and the Netherlands contrasts with fragmented home care demand across Southern Europe.
- Hospitals:Integrated respiratory monitoring platforms in surgical suites and intensive care units demand combined cardiac-respiratory sensor specifications. NHS England's framework agreements increasingly qualify independent service organizations for critical-care equipment support, unbundling device acquisition from long-term manufacturer service contracts.
- Home Care Settings:Portable capnography and remote spirometry platforms serve hospital-at-home programs in the Netherlands and Belgium with automated alert triage. F-Gas Regulation phase-down constraints on refrigerant-dependent gas analyzers redirect R&D toward solid-state sensor architectures with lower maintenance profiles for this dispersed deployment model.
- Clinics:Outpatient pulmonary function testing and diagnostic spirometry for chronic disease surveillance.
- Rehabilitation Centers:Post-acute respiratory therapy and weaning protocols for ventilator-dependent patients.
Hospitals dominate current procurement volume. Home Care Settings are climbing the fastest as post-acute integration accelerates.
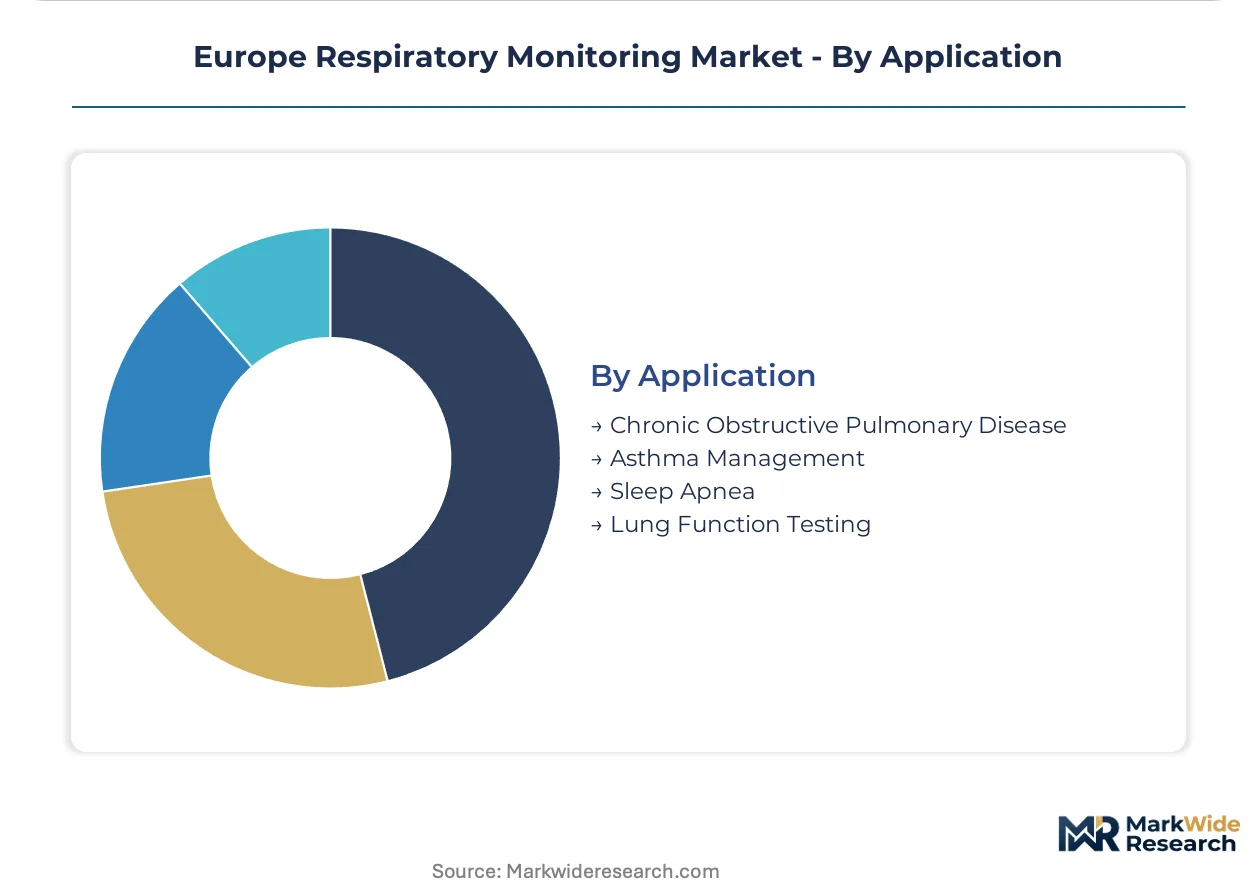
Application:
Chronic disease prevalence patterns across Northern and Southern Europe shape device specification requirements.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy titration, exacerbation detection, and rehabilitation progress monitoring drive demand for continuous pulse oximetry and nocturnal ventilation platforms. Germany's industrial healthcare clusters pilot integrated multi-site data interoperability specifically for COPD population management.
- Sleep Apnea:Polysomnography and home sleep testing require airflow, respiratory effort, and oxygen saturation monitoring with specific attention to hypopnea scoring algorithms. Notified body bottlenecks in Germany and France extend MDR certification timelines for novel algorithmic diagnostics in this segment by 12-18 months.
- Asthma Management:Peak flow monitoring, trigger identification, and medication adherence tracking for pediatric and adult populations.
- Lung Function Testing:Diagnostic spirometry, diffusion capacity measurement, and bronchial challenge testing for occupational and clinical assessment.
COPD applications anchor current revenue. Sleep Apnea diagnostics are gaining share fastest as home testing protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical engineers with dual IEC 62304 and ISO 27001 competency concentrate in Germany's industrial healthcare clusters, anchoring Europe's respiratory monitoring innovation pipeline. French notified bodies and Dutch hospital procurement departments compete for technical talent to navigate MDR certification bottlenecks. University hospital networks across the region pilot integrated platforms that demand specialized workforce density.
Germany
Baden-Württemberg and Bavaria host university hospital networks standardizing multi-site procurement specifications for critical-care ventilator platforms. The MDR's Annex I cybersecurity requirements compress commercialization timelines for connected devices. Engineering talent pools in Stuttgart and Munich anchor manufacturing scale advantages for precision flow sensors and pressure transducers.
France
ANSM and CNIL jointly oversee algorithmic diagnostic approvals and patient data localization for cloud-connected respiratory platforms. Remote therapeutic monitoring billing codes now reimburse home-based COPD surveillance, accelerating hospital procurement of portable capnography systems. The Paris-Saclay cluster concentrates AI validation expertise for software-as-medical-device submissions under the EU AI Act.
United Kingdom
NHS England's framework agreements unbundle device acquisition from long-term manufacturer service contracts, opening critical-care equipment support to independent service organizations. Post-Brexit regulatory divergence from MDR creates parallel certification pathways for ventilator and spirometer platforms. London and the Southeast concentrate digital health investment for wearable respiratory rate estimation technologies.
Netherlands
Hospital-at-home programs in Randstad cities generate demand for remote spirometry platforms with automated alert triage. GDPR-compliant sovereign cloud infrastructure requirements force data localization investments for cross-border patient monitoring networks. Eindhoven's health technology cluster specializes in photoplethysmography sensor integration for nocturnal hypoxemia surveillance.
Italy
Southern European reimbursement frameworks recognize remote therapeutic monitoring codes later than Northern counterparts, delaying wearable device penetration. Legacy hospital information systems in Milan and Rome resist direct API integration with cloud-based respiratory platforms. The F-Gas Regulation phase-down redirects R&D investment toward solid-state sensor architectures for dispersed home care deployment.
Europe Respiratory Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with integrated diagnostics platforms and specialized critical-care engineering firms. Hospital procurement departments favor vendors offering combined cardiac-respiratory sensor specifications and long-term service agreements. Two archetypes dominate: platform-integrated systems manufacturers and precision sensor engineering specialists. Competitive moves concentrate on M&A for algorithmic diagnostic capabilities and strategic partnerships for sovereign cloud infrastructure compliance.
Within the diversified health technology tier, Koninklijke Philips N.V. and GE Healthcare represent platform-integrated systems manufacturers with hospital network loyalty across Northwestern Europe. Medtronic exemplifies the cardiac-respiratory convergence specialist, while Drägerwerk AG & Co. KGaA occupies a position as a scale-driven critical-care engineering firm anchored in German manufacturing standards. ResMed and Masimo sit within the precision sensor and remote monitoring archetype, reflecting digital health investment flows toward wearable form factors and cloud-connected platforms.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| ResMed |
| Getinge |
| Masimo |
| Nihon Kohden Corporation |
| COSMED |
| Others |
Supply & Pricing Matrix
Backward integration into sensor manufacturing anchors supply positioning and pricing power for European respiratory monitoring vendors facing MDR Annex I cybersecurity validation requirements. German engineering clusters in Stuttgart and Munich concentrate precision flow sensor production, while cloud-platform providers absorb sovereign infrastructure costs across France, Italy, and the Netherlands to maintain hospital contract eligibility.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across ventilator and wearable segments. Critical-care platforms command contract-based long-term offtake pricing with maintenance bundled over five-to-seven-year horizons, while wearable devices face premium-mid-economy pricing differentiation driven by CE marking tier and clinical validation depth. Cost compression in the wearable tier intensifies because reimbursement fragmentation between France, Italy, and the UK prevents unified volume scaling. Hospital procurement departments in Germany and the Netherlands show lowest price sensitivity for integrated cardiac-respiratory platforms, whereas Southern European home care providers prioritize per-unit transactional models.
Supply Chain Analysis
Direct-to-hospital channels handle critical-care demand while distributor networks serve dispersed home care deployment across Belgium and the Netherlands. Manufacturing concentrates in Germany, Switzerland, and Ireland for precision pressure transducers and solid-state gas sensors. Component sourcing draws from Taiwanese semiconductor foundries for photoplethysmography chips and Dutch MEMS fabricators for accelerometer arrays. Single-source vulnerability in EU-notified body capacity creates certification bottlenecks that extend production lead times for novel algorithmic diagnostics. Distribution runs through specialized medical device logistics providers with GDP-compliant cold chain capabilities for portable capnography units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's respiratory monitoring sector functions as a regulatory compounder where MDR certification delays and EU AI Act risk classifications continuously reshape competitive access. The F-Gas Regulation phase-down accelerates demand for solid-state sensor architectures, creating procurement pull-through for compliant vendors.
For Market Incumbents: Extend platform integration depth to lock in German university hospital networks before independent service organizations capture maintenance contracts. Philips and Drägerwerk should accelerate backward integration into cybersecurity validation talent pools to offset IEC 62304 competency scarcity. Defensive patenting around algorithmic respiratory pattern recognition protects against software-as-medical-device entrants from Paris-Saclay AI clusters. For New Entrants and Emerging Players: Solid-state capnography sensors offer a technology-first wedge into Netherlands hospital-at-home programs where F-Gas constraints disqualify legacy refrigerant-dependent analyzers. Target Belgian and Dutch post-acute care settings with portable spirometry platforms featuring automated alert triage. Partner with French notified bodies early for EU AI Act pre-validation to compress MDR certification timelines for machine-learning diagnostics. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precision sensor specialists because GDPR data localization requirements fragment cloud-platform markets into member-state silos that favor regional scale over global reach. Target German and Swiss engineering firms with captive MEMS fabrication capabilities. Watch for ANSM and BfArM harmonization on algorithmic diagnostic review pathways as the inflection signal for software-as-medical-device valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex I cybersecurity requirements compress timelines for connected device submissions to German notified bodies. |
| Hospital System Partnership | Baden-Württemberg university networks standardize multi-site procurement specifications for integrated platforms. |
| Software Companion Development | EU AI Act risk classifications force pre-validation of training datasets across French demographic cohorts. |
| Reimbursement Strategy | Remote therapeutic monitoring codes in France and Italy accelerate cloud-connected platform adoption. |
| Backward Integration | Captive production of solid-state gas sensors insulates margins from F-Gas Regulation refrigerant constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and regulatory interpretation variance. Primary engagement included hospital purchasing committees in Germany, biomedical engineers in Dutch home care networks, GPO contracts managers in NHS England, and regulatory affairs leads navigating ANSM and BfArM submissions. Secondary validation drew from EMA harmonization documents, EU Medical Device Regulation guidance, hospital procurement databases, and notified body capacity reports. Bottom-up segment sizing triangulated against top-down macro healthcare expenditure trends.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity modeling. Segmentation dimensions included device sophistication tier, connectivity protocol, care setting economics, and application severity class. CAGRs derived from weighted average of segment growth rates adjusted for MDR certification timeline delays and reimbursement code expansion schedules. Forecast inputs incorporated F-Gas Regulation phase-down curves and EU AI Act implementation timelines.
The model holds under stable notified body capacity and continued remote therapeutic monitoring reimbursement expansion; deviation in MDR harmonization speed or GDPR enforcement intensity would shift trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market