
 Middle East and Africa Cardiac Monitoring Market | 2026-2036
Middle East and Africa Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cardiac Monitoring Market Foresight
Hospital procurement concentration across tertiary networks in the Middle East and Africa is hardening, with large health systems consolidating vendor contracts for cardiac monitoring suites. Medtronic PLC leverages its implantable loop recorder portfolio to anchor long-term service agreements with government hospital clusters. Abbott Laboratories differentiates through wireless patch platforms that reduce nursing workload in understaffed cardiac wards. GE Healthcare sustains installed-base dominance across North African public hospitals where capital replacement cycles lag Gulf timelines.
Middle East and Africa cardiac monitoring encompasses devices that capture, record, and transmit electrical cardiac activity through surface electrodes or implanted sensors, typically operating across bandwidths of 0.05 to 150 Hz for diagnostic-grade resolution. These systems serve to detect arrhythmias, ischemic events, and hemodynamic deterioration in acute and ambulatory settings. ECG Devices occupy the largest revenue pool given their ubiquity in emergency departments and preoperative screening protocols, while Wireless technology segments expand fastest as Gulf health systems deploy remote monitoring for postoperative cardiac surgery patients. Implantable Loop Recorders command premium margins due to specialized electrophysiologist implantation requirements and limited regional training capacity.
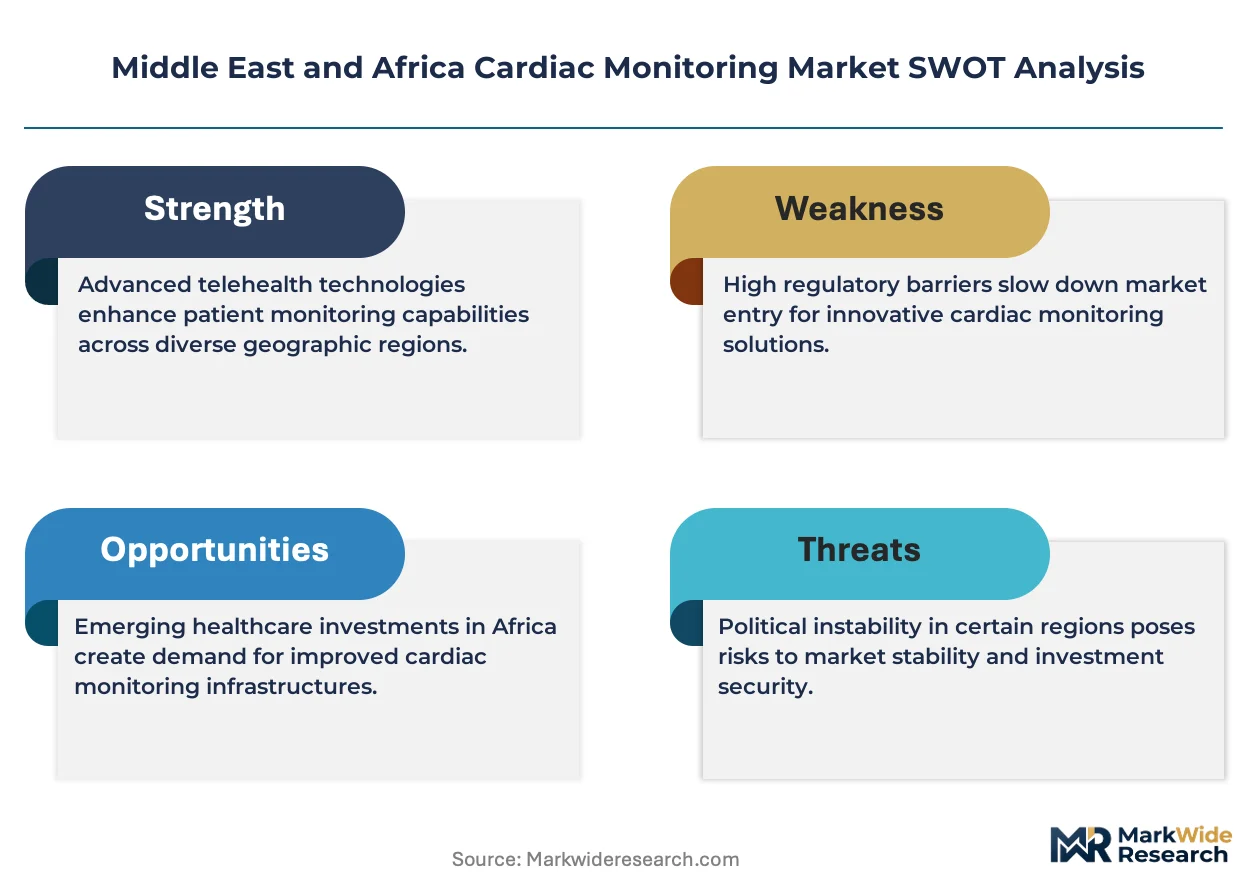
South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and UAE Ministry of Health and Prevention collectively enforce medical device registration, clinical evidence standards, and post-market surveillance that determine product eligibility across national tenders. These frameworks elevate compliance costs for smaller manufacturers while creating protected competitive corridors for established multinationals with dedicated regulatory affairs teams in Johannesburg, Riyadh, and Dubai. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks and pre-qualification pathway convergence that could reshape market access requirements.
Market Dynamics
Hospital procurement consolidation across tertiary care networks is hardening vendor selection criteria, compressing supplier lists to multinationals capable of delivering integrated cardiac monitoring suites with embedded service agreements.
Growth Catalysts
- Saudi Food and Drug Authority streamlining:Compressed medical device registration timelines accelerate product launches for cardiac monitoring systems in the Kingdom's hospital privatization pipeline.
- Remote monitoring protocols:Postoperative cardiac surgery programs in UAE tertiary centers deploy wireless telemetry to reduce nursing workload in understaffed wards.
- Electrophysiology training expansion:Dubai Healthcare City's cardiology hub development builds regional implantable loop recorder implantation capacity, unlocking premium device segments.
Market Restraints
- Capital replacement lag:North African public hospitals operate ECG systems beyond standard depreciation cycles, delaying technology refresh revenues.
- Regulatory fragmentation:Divergent registration requirements across South Africa's Health Products Regulatory Authority, Saudi FDA, and UAE MOHAP inflate compliance overhead for single-market entrants.
- Specialist scarcity:Limited electrophysiologist density across sub-Saharan markets constrains implantable device penetration regardless of product availability.
Strategic Opportunities
- Nigeria's diagnostic infrastructure gap:Underpenetrated cardiac monitoring capacity in West Africa's largest population center creates first-mover positioning for portable ECG platforms.
- Gulf Cooperation Council harmonization:Converging pre-qualification pathways could collapse redundant national registration costs into single-entry regional access.
- AI-enhanced arrhythmia detection:Machine learning algorithm integration with wireless patch systems enables automated preliminary diagnosis in resource-constrained settings.
Industry Challenges
- Biomedical engineering talent pipeline:Equipment maintenance and calibration expertise shortages across East African markets extend device downtime and compromise monitoring continuity.
- Legacy system interoperability:New wireless platforms face integration friction with existing hospital information systems in mature South African installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cardiac Monitoring Market |
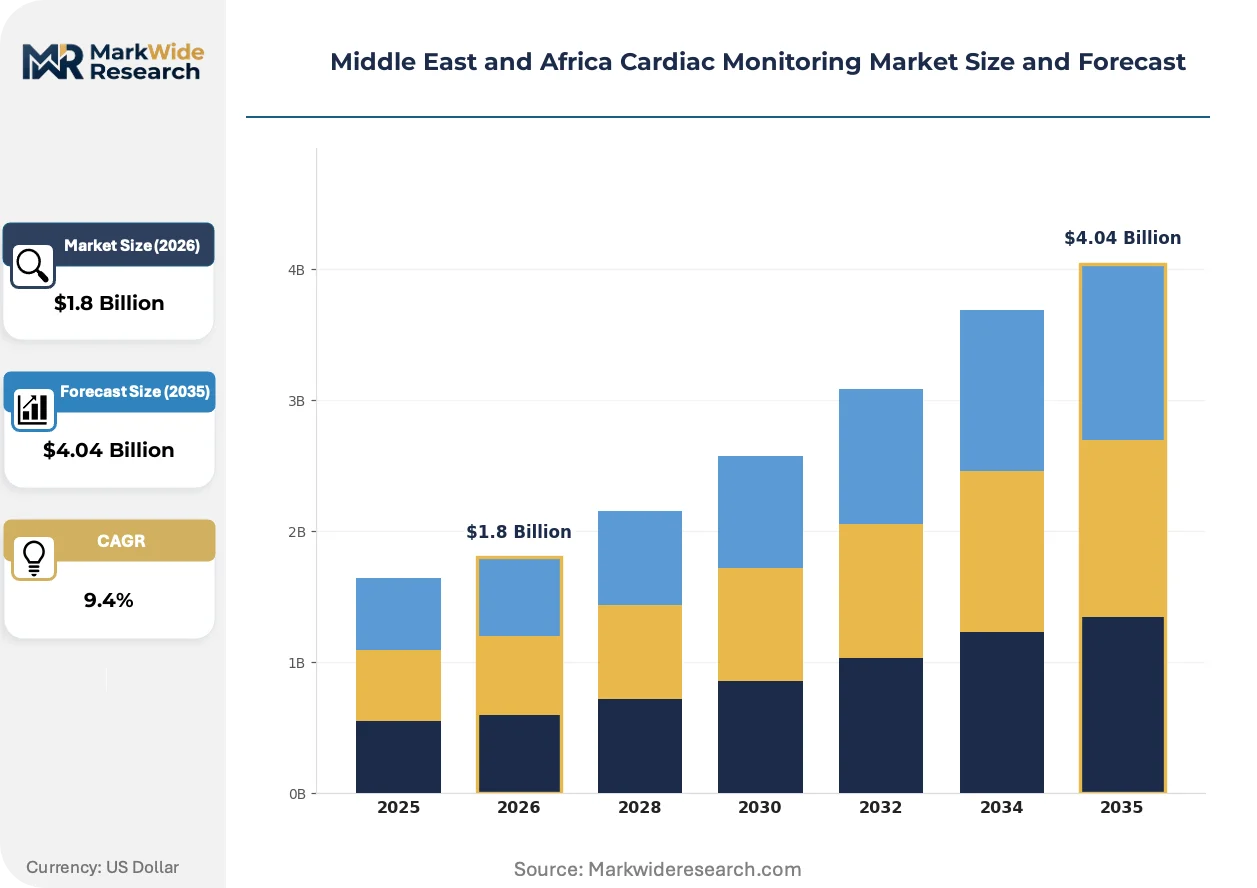
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitor, ECG Devices, Implantable Loop Recorders, Event Monitors Technology: Wireless, Wearable, Telemetry, Manual Monitoring End User: Hospitals, Clinics, Homecare, Diagnostic Centers Application: Arrhythmia Management, Heart Failure Management, Postoperative Monitoring, Preventive Screening |
| Companies Covered | Medtronic PLC, Abbott Laboratories, Boston Scientific Corporation, GE Healthcare, BIOTRONIK, iRhythm Technologies Inc, Baxter, Schiller AG, Philips Healthcare, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cardiac Monitoring Market Shifts & Advancements
Digital telemetry architectures are displacing bedside tethered systems across Middle East and Africa cardiac wards, reconfiguring capital deployment toward subscription-based remote monitoring platforms.
Artificial intelligence diagnostic modules are integrating with ambulatory ECG platforms to flag atrial fibrillation and ventricular arrhythmias without cardiologist review. Saudi Arabia's Ministry of Health pilot programs validate algorithm performance against specialist interpretation. This compression of diagnostic latency is integrating community clinics into formal cardiac care pathways previously restricted to tertiary centers.
South Africa's Health Products Regulatory Authority tightened clinical evidence standards for Class III cardiac devices, extending registration dossier requirements. Manufacturers now submit extended follow-up data from regional implant registries. Implantable loop recorder segments face the steepest compliance cost escalation as electrophysiology outcome documentation demands intensify.
Equipment leasing arrangements are displacing outright capital purchases in Egyptian and Moroccan public hospital networks. International distributors with local service subsidiaries capture multi-year contracts bundling devices, consumables, and preventive maintenance. This financing structure shift concentrates purchasing authority within ministry procurement offices and marginalizes smaller dealers lacking balance sheet capacity for extended receivables.
Middle East and Africa Cardiac Monitoring Market Segmentation
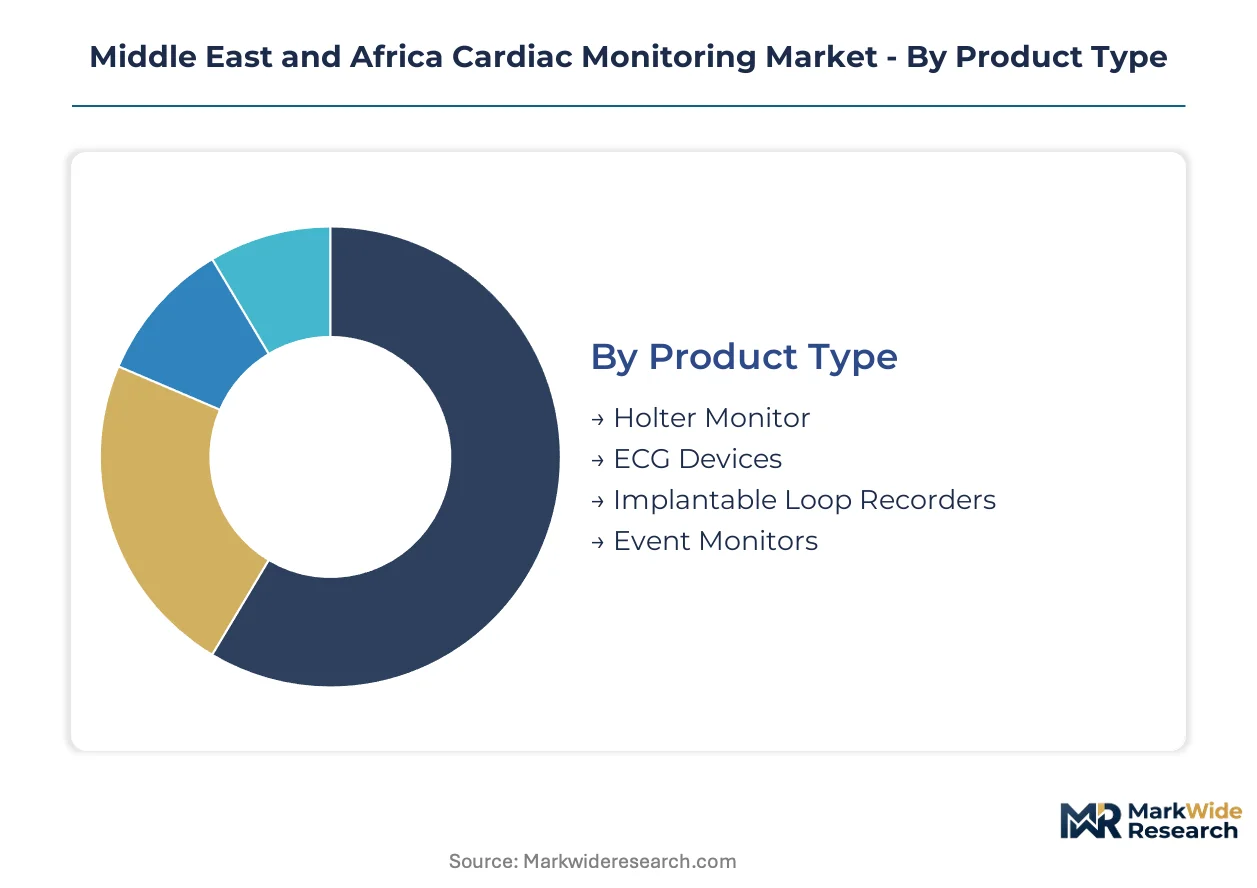
Cardiac monitoring procurement in the Middle East and Africa fragments across acute care hierarchies, ambulatory migration patterns, and reimbursement bandwidth constraints. Segmentation reveals where capital concentrates versus where subscription models displace outright purchase.
Product Type:
Customization intensity varies sharply—from standardized bedside ECG systems to patient-matched implantable configurations requiring electrophysiologist involvement.
- ECG Devices:Surface electrode systems operating across 0.05 to 150 Hz bandwidth dominate emergency department and preoperative screening protocols. Saudi Arabia's hospital privatization pipeline and UAE tertiary networks concentrate demand for 12-lead diagnostic-grade units with embedded arrhythmia detection algorithms.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life capture asymptomatic arrhythmias through single-lead electrogram storage. Dubai Healthcare City's electrophysiology hub expansion unlocks premium segment penetration despite limited regional implantation capacity constraining volume growth.
- Holter Monitor:24- to 48-hour ambulatory systems with solid-state memory capture transient rhythm disturbances during daily activity.
- Event Monitors:Patient-activated or auto-triggered devices record symptomatic episodes across weeks-long monitoring windows.
Leading the category by volume: ECG Devices. Growing fastest: Implantable Loop Recorders.
Technology:
Cost tier stratification separates capital-intensive installed-base systems from lower-entry subscription telemetry platforms.
- Wireless:Bluetooth and cellular-enabled patches transmit real-time ECG streams to centralized monitoring stations without bedside tethering. UAE postoperative cardiac surgery programs deploy these systems to reduce nursing workload in understaffed wards, with Saudi pilots validating AI-enhanced arrhythmia flagging.
- Telemetry:Radiofrequency-based continuous monitoring architectures support step-down unit and coronary care ward surveillance. North African public hospitals lag in telemetry refresh cycles, operating equipment beyond standard depreciation timelines and compressing near-term replacement revenue.
- Wearable:Consumer-grade and clinical-grade wrist or chest-worn sensors enable outpatient rhythm surveillance.
- Manual Monitoring:Technician-attended 12-lead acquisition remains standard for diagnostic confirmation in resource-constrained settings.
Dominating procurement value: Telemetry. Expanding most quickly: Wireless.
End User:
Customer type determines financing structure—ministry-level leasing versus point-of-care purchase authority.
- Hospitals:Tertiary care networks consolidate vendor contracts for integrated cardiac monitoring suites with embedded preventive maintenance agreements. Egypt and Moroccan public hospital networks increasingly favor equipment leasing arrangements that bundle devices, consumables, and service.
- Homecare:Remote monitoring protocols for postoperative cardiac surgery patients and chronic heart failure management shift monitoring location outside institutional walls. South African private insurance reimbursement patterns and Gulf health system digitization initiatives accelerate segment development.
- Clinics:Community-based facilities integrate into formal cardiac care pathways through AI-enhanced preliminary diagnosis capabilities.
- Diagnostic Centers:Specialized cardiac testing facilities concentrate preoperative screening and employment health examination volume.
Commanding capital allocation: Hospitals. Gaining share fastest: Homecare.
Application:
Maturity differentiation separates established acute care protocols from emerging preventive deployment models.
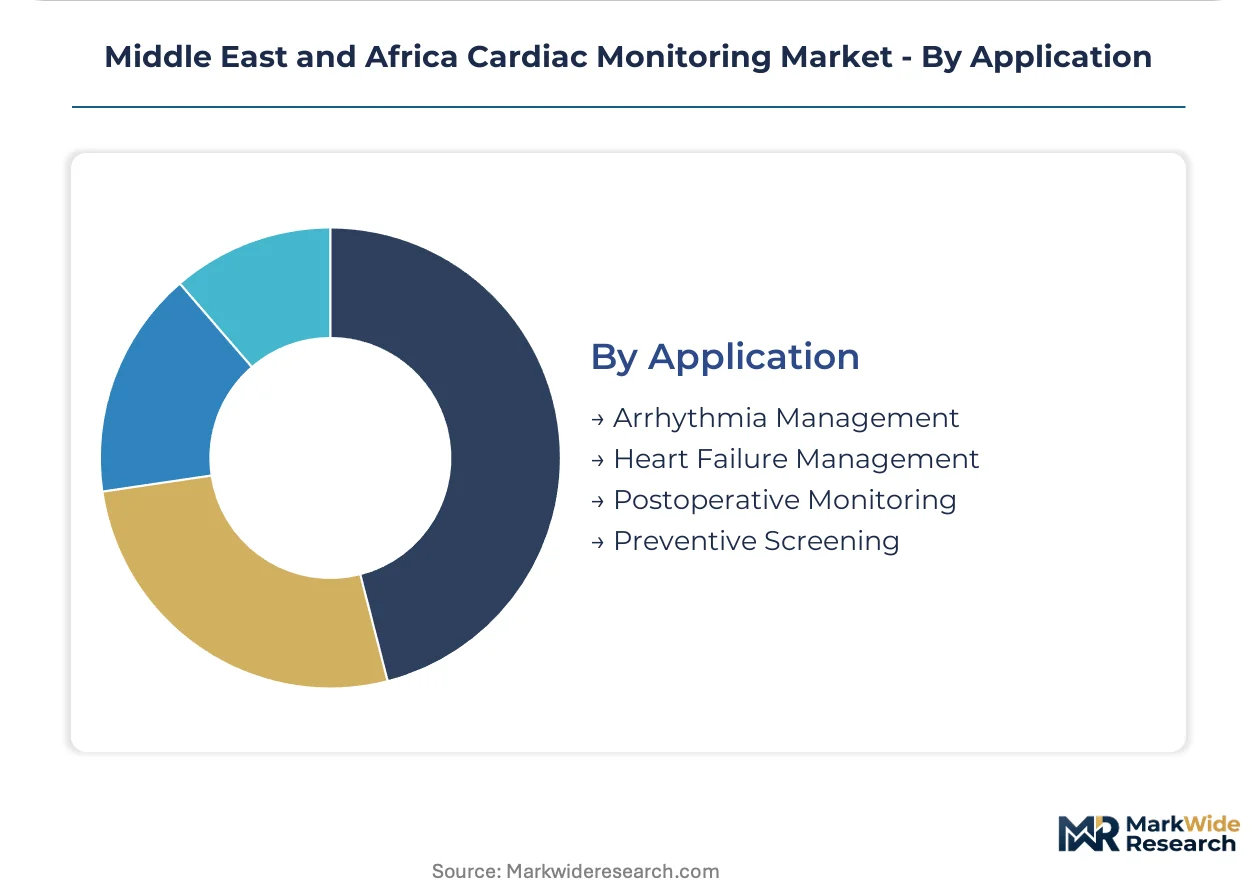
- Arrhythmia Management:Detection and characterization of atrial fibrillation, ventricular tachycardia, and conduction abnormalities drives continuous monitoring adoption. AI diagnostic modules now flag rhythm disturbances without mandatory cardiologist review, compressing diagnostic latency in Saudi Ministry of Health pilot programs.
- Postoperative Monitoring:Cardiac surgery recovery protocols mandate telemetry surveillance for hemodynamic deterioration detection. Wireless platform deployment in UAE tertiary centers exemplifies segment technology refresh patterns.
- Heart Failure Management:Hemodynamic monitoring and fluid status assessment through implantable sensors or external impedance methods supports decompensation prevention.
- Preventive Screening:Asymptomatic population rhythm assessment expands through occupational health and executive wellness programs.
Highest procedure attachment: Arrhythmia Management. Steepest expansion trajectory: Postoperative Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac monitoring procurement concentrates in Gulf health systems upgrading tertiary networks, while North African and sub-Saharan markets lag capital refresh cycles. Saudi Arabia's hospital privatization pipeline and UAE hub development anchor near-term demand expansion.
Saudi Arabia
Hospital privatization programs drive demand for integrated cardiac monitoring suites across tertiary networks. Saudi Food and Drug Authority compressed registration timelines accelerate vendor qualification for multinationals. Riyadh's King Faisal Specialist Hospital anchors electrophysiology capacity expansion, deploying implantable loop recorders for cryptogenic stroke protocols.
United Arab Emirates
Dubai Healthcare City's cardiology hub expansion concentrates postoperative monitoring technology procurement. Ministry of Health and Prevention digitization initiatives validate AI-enhanced arrhythmia detection algorithms in pilot programs. Abu Dhabi's Cleveland Clinic Abu Dhabi deploys wireless telemetry to reduce nursing workload in cardiac surgery recovery wards.
South Africa
Private insurance reimbursement patterns sustain premium device segments despite public sector capital constraints. Health Products Regulatory Authority tightened clinical evidence standards for Class III cardiac devices, extending registration dossier requirements. Johannesburg's Netcare cardiac hospitals concentrate implantable device volumes, while public hospitals operate ECG systems beyond standard depreciation timelines.
Egypt
Equipment leasing arrangements displace outright capital purchases in public hospital networks. Ministry of Health and Population procurement offices consolidate vendor contracts for bundled device-service offerings. Cairo's tertiary cardiac centers concentrate diagnostic ECG volume, though capital replacement cycles lag Gulf timelines by several years.
Nigeria
Underpenetrated diagnostic infrastructure creates positioning opportunities for portable ECG platforms in West Africa's largest population center. National Agency for Food and Drug Administration and Control medical device registration frameworks elevate compliance costs for smaller manufacturers. Lagos private hospital clusters drive demand for wireless monitoring systems, while public sector procurement remains fragmented across state-level purchasing authorities.
Middle East and Africa Cardiac Monitoring Market Competitive Landscape
United States and European multinationals anchor the premium device tier; regional distributors and service subsidiaries hold procurement gateway positions. Market structure concentrates around established players with dedicated regulatory affairs teams in Johannesburg, Riyadh, and Dubai. Three archetypes dominate: integrated suite providers bundling hardware with long-term service agreements, wireless platform specialists reducing nursing workload, and implantable device manufacturers building electrophysiologist training networks. Competitive moves center on ministry-level leasing contract capture and AI diagnostic module integration partnerships.
Within the integrated suite tier, Medtronic PLC and Abbott Laboratories exemplify multinational positioning. Medtronic leverages implantable loop recorder portfolios to anchor government hospital cluster agreements. Abbott differentiates through wireless patch platforms targeting understaffed cardiac wards. GE Healthcare sustains installed-base relationships across North African public hospitals where capital replacement cycles extend beyond Gulf timelines. These three companies represent distinct strategic postures: implantable device premiumization, wireless workflow optimization, and legacy system continuity.
| Leading Market Players |
|---|
| Medtronic PLC |
| Abbott Laboratories |
| Boston Scientific Corporation |
| GE Healthcare |
| BIOTRONIK |
| iRhythm Technologies Inc |
| Baxter |
| Schiller AG |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation across implantable loop recorders, wireless telemetry platforms, and diagnostic ECG systems manifests in divergent supply chain configurations. Gulf health systems command bundled service agreements with embedded preventive maintenance, while North African public hospitals source through extended leasing structures that shift inventory risk to distributor balance sheets.
Pricing Analysis
Volume-vs-margin split separates high-unit ECG device sales from premium implantable segments where electrophysiologist training scarcity sustains pricing power. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under Saudi FDA and UAE MOHAP pathways. Cost compression in wireless telemetry is intensifying because ministry procurement offices consolidate vendor lists to multinationals with dedicated regional service subsidiaries. Public hospital networks in Egypt and Morocco exhibit highest price sensitivity, while Dubai Healthcare City tertiary centers prioritize workflow optimization over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with semiconductor component suppliers concentrated in Taiwan, South Korea, and Germany for ECG acquisition modules and telemetry transmission chipsets. Manufacturing draws from Malaysia, Ireland, and Costa Rica for final device assembly and sterilization packaging. Regulatory restriction risk escalates as South Africa's Health Products Regulatory Authority extends Class III cardiac device registration timelines. Distribution runs through Johannesburg, Riyadh, and Dubai-based regional subsidiaries that control ministry tender access and biomedical engineering service capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across tertiary networks is forcing smaller distributors and single-product manufacturers toward exit or acquisition, compressing viable competitive set to integrated suite providers with regional regulatory affairs infrastructure.
For Market Incumbents: Cement government hospital cluster relationships through multi-year service agreements bundling implantable devices with electrophysiologist training programs. Anchor installed-base positions in North African public hospitals ahead of eventual capital refresh cycles, while defending against wireless platform specialists through AI diagnostic module integration partnerships with Saudi Ministry of Health pilot programs. For New Entrants and Emerging Players: AI-enhanced arrhythmia detection algorithms offer a technology-first wedge into community clinic networks previously excluded from formal cardiac care pathways. Target Nigeria's underpenetrated diagnostic infrastructure with portable ECG platforms suited to fragmented state-level procurement. Pursue Cleveland Clinic Abu Dhabi and King Faisal Specialist Hospital reference installations to unlock broader Gulf Cooperation Council ministry access. For Investors and Strategic Acquirers: Re-rating potential sits with wireless telemetry platform specialists given Dubai Healthcare City hub expansion and Saudi hospital privatization catalysts. Long-term viability favors targets with demonstrated AI algorithm validation and existing SFDA or MOHAP registration dossiers. Watch Gulf Cooperation Council harmonization talks as inflection signal for regional access cost collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Ministry-level leasing contracts in Egypt and Morocco consolidate purchasing authority within procurement offices. |
| Software Companion Development | AI diagnostic modules integrated with wireless patches reduce nursing workload in understaffed Saudi wards. |
| CE Marking Pathway | European certification accelerates Saudi FDA and UAE MOHAP registration through mutual recognition frameworks. |
| Reimbursement Strategy | South African private insurance patterns validate homecare remote monitoring for postoperative cardiac surgery. |
| Biomedical Engineering Training | Electrophysiologist capacity expansion in Dubai Healthcare City unlocks implantable loop recorder premium segments. |
Research Methodology
Hospital procurement databases, GPO contracts, and Saudi FDA registration filings formed the secondary backbone, supplemented by customs records tracking device imports through Jeddah and Dubai ports. Primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers across Johannesburg, Riyadh, and Dubai validated demand assumptions and pricing structures. Bottom-up and top-down triangulation reconciled unit shipment estimates with ministry budget allocation data across the analysis window.
Bottom-up modeling aggregated country-level tender awards and hospital procurement announcements by product type, technology, and end-user segment. Top-down validation cross-checked aggregate market size against health expenditure patterns and cardiac surgery volume projections. Segmentation dimensions included device category, connectivity architecture, care setting, and application protocol. CAGRs were derived from fitted growth curves applied to normalized base-year estimates, with electrophysiology training expansion rates and hospital privatization pipeline velocity serving as key demand drivers.
Several conditions sit outside the modeled scope, including geopolitical disruption to Red Sea shipping lanes, abrupt currency devaluation in Egyptian or Nigerian markets, and rapid Gulf Cooperation Council regulatory harmonization that collapses national registration timelines faster than projected. Forecasts reflect documented assumptions about ministry procurement centralization and AI diagnostic reimbursement acceptance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market