
 ICU ECG Patient Monitor Market | 2026-2036
ICU ECG Patient Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
ICU ECG Patient Monitor Market Insights
Long-term care facilities are redrawing procurement patterns in the ICU ECG patient monitor space, shifting volume away from traditional hospital-centric purchasing. Philips Healthcare anchors its position through backward integration into sensor technology and proprietary algorithm development. GE Healthcare competes on manufacturing scale across North American and European production networks. Mindray leverages cost-optimized digital platforms to extend its footprint in emerging hospital systems.
An ICU ECG patient monitor is a bedside or portable diagnostic instrument that captures, amplifies, and displays electrical cardiac activity through 3- to 12-lead configurations, with sampling rates typically exceeding 250 Hz to resolve ST-segment deviations and arrhythmia onset. The device serves critical care units by enabling continuous hemodynamic surveillance, reducing response latency to lethal rhythm disturbances. Portable monitors and wireless technology segments are capturing the fastest expansion as hospitals decentralize monitoring beyond traditional ICU footprints. Bedside monitors retain the largest installed base and associated service revenue pools. Central station monitors face consolidation pressure from cloud-integrated distributed architectures.
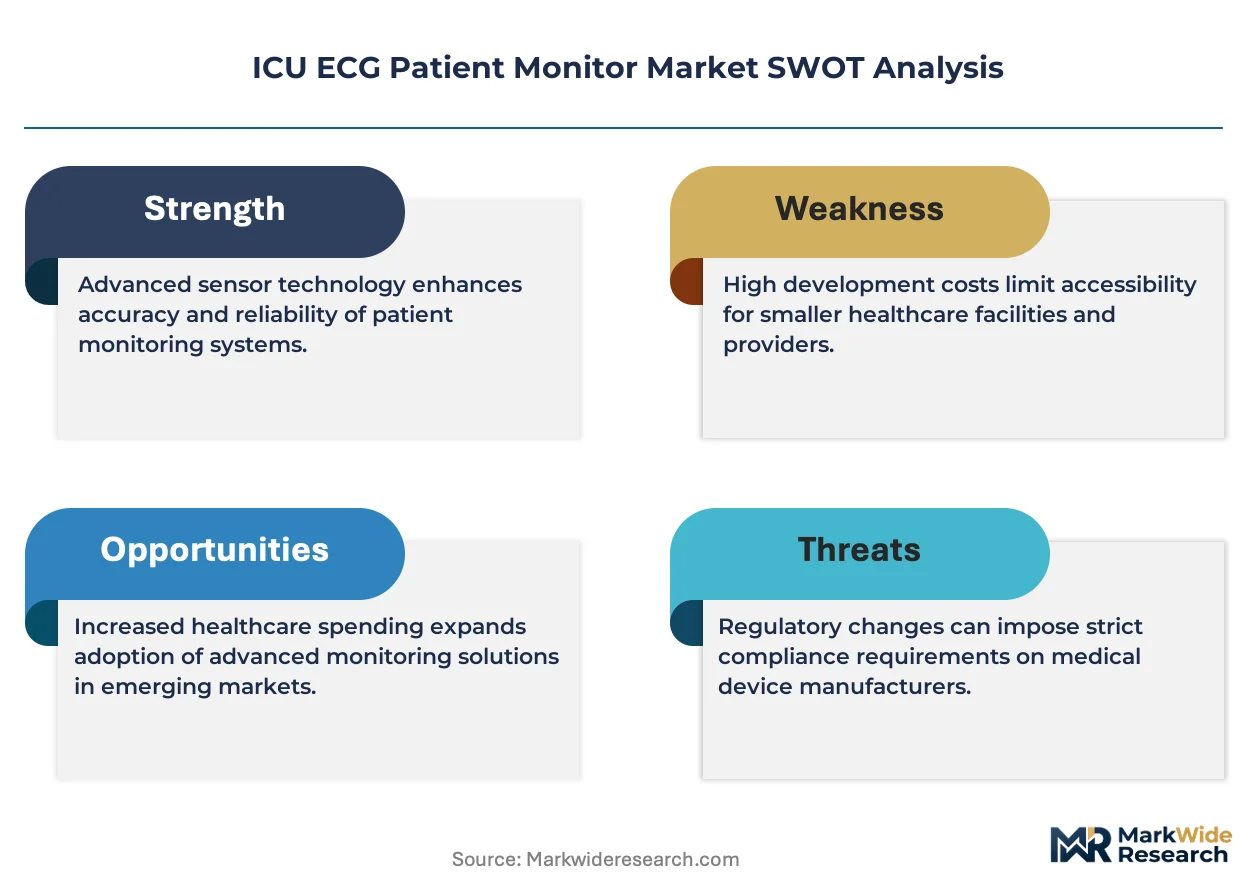
FDA 510(k) premarket notification and EU MDR Class IIa/IIb conformity requirements govern device safety and clinical performance validation for arrhythmia detection claims. The EPA regulates disposal of lead-containing components and lithium battery waste from monitor fleets. Stakeholders must weigh regulatory compliance costs against the margin compression from wireless technology commoditization and software-as-a-service telemetry models.
Market Dynamics
Wireless telemetry architectures and cloud-integrated distributed monitoring systems are compressing traditional central station monitor deployments, forcing incumbent manufacturers to restructure hardware-service revenue mixes around software-as-a-service telemetry models.
Growth Catalysts
- ICU Bed Expansion in China:Provincial health commissions in Sichuan and Guangdong are funding 15-20% increases in critical care capacity, creating immediate demand for multi-parameter bedside systems with arrhythmia detection algorithms.
- FDA 510(k) Pathway Streamlining:Predicate device clearance for algorithm-upgraded monitors accelerates time-to-market for ST-segment analysis enhancements, reducing validation burdens for manufacturers with existing platform approvals.
- Leadless ECG Sensor Miniaturization:Advances in dry electrode materials and flexible printed circuit manufacturing enable disposable patch monitors that extend continuous monitoring beyond traditional bedside footprints into step-down units.
Market Restraints
- EU MDR Class IIb Clinical Evidence Requirements:Stricter conformity assessment procedures for arrhythmia detection claims demand expanded patient cohort studies, extending certification timelines and inflating regulatory compliance costs.
- Lithium Battery Supply Concentration:Portable monitor fleets depend on cylindrical cell supplies from East Asian manufacturers, exposing procurement to export control volatility and forced labor due diligence mandates.
- Algorithm Validation Burden:FDA guidance on artificial intelligence-enabled arrhythmia classification requires locked algorithm versions with predetermined change control plans, constraining machine learning model updates.
Strategic Opportunities
- Rural Hospital Telemetry in India:District hospital networks under the National Health Mission lack centralized monitoring infrastructure, creating white space for cloud-integrated wireless systems with hub-and-spoke architectures.
- ISO 13485:2016 Quality Management Alignment:Harmonized medical device quality standards reduce audit duplication across export markets, lowering barrier costs for mid-scale manufacturers seeking multi-territory expansion.
- Interoperability with Electronic Health Records:HL7 FHIR interface standardization enables seamless data exchange with Epic and Cerner deployments, differentiating monitors in health system procurement evaluations.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Health systems face acute shortages of technicians trained on 12-lead ECG troubleshooting and network security hardening for wireless monitor fleets.
- Legacy Central Station Integration:Decentralized telemetry architectures must coexist with installed Philips and GE central monitoring infrastructure, requiring costly middleware development and dual-system training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICU ECG Patient Monitor Market |
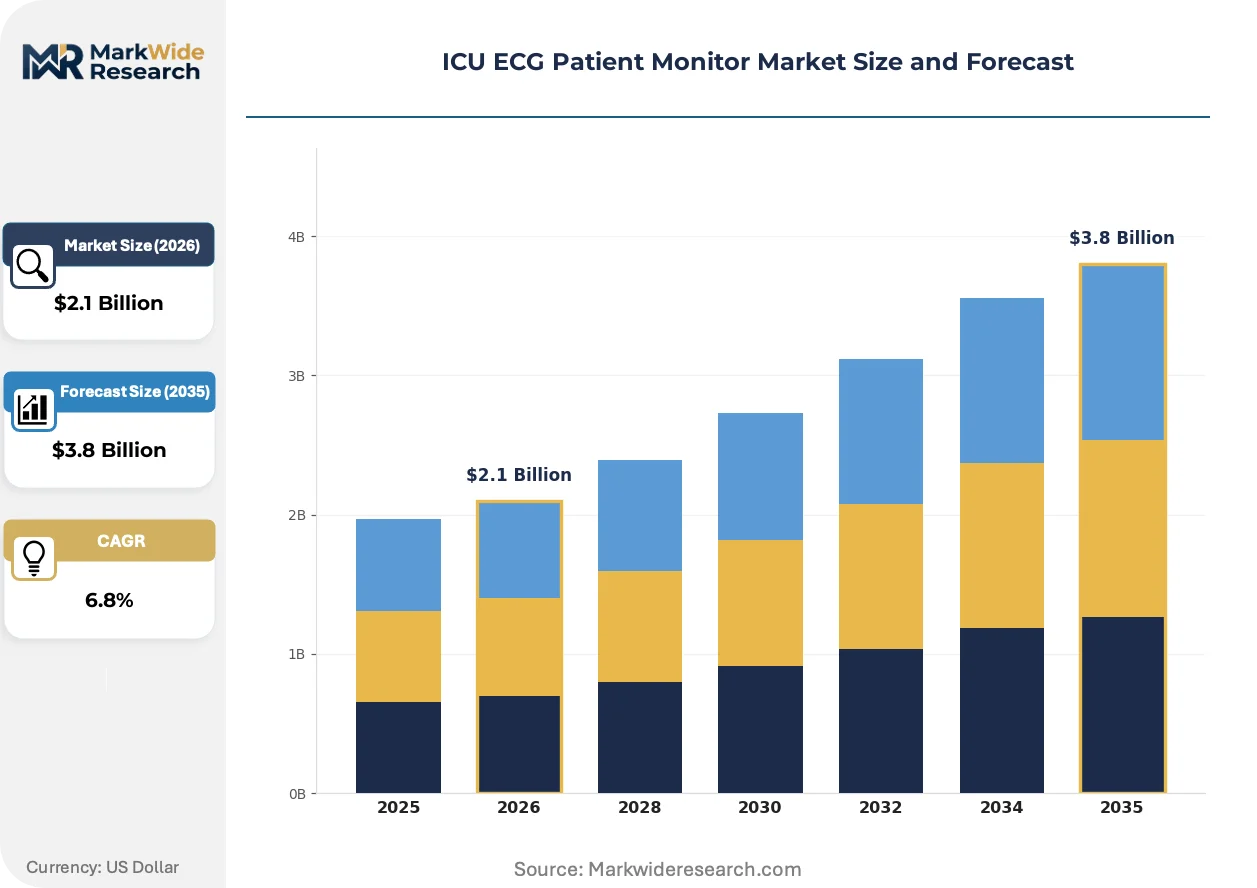
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Bedside Monitors, Central Station Monitors, Wireless Monitors End User: Hospitals, Long-term Care Facilities, Emergency Medical Services, Home Care Providers Technology: Digital Monitoring, Wireless Technology, Analog Monitoring, Hybrid Systems Installation: Fixed Installation, Mobile Units, Standalone Units, Integrated Systems |
| Companies Covered | Philips Healthcare, GE Healthcare, Siemens Healthineers, Mindray, Nihon Kohden, Medtronic, Zoll Medical, Schiller, Drägerwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICU ECG Patient Monitor Market Trends and Innovations
Algorithm-driven diagnostic augmentation and modular hardware platforms are fragmenting traditional product categories, enabling software-defined feature differentiation that decouples monitor capabilities from physical hardware generations.
Artificial intelligence-enabled arrhythmia classification is bifurcating competitive positioning between locked-algorithm predicate devices and adaptive machine learning systems. Tertiary care hospitals in Germany and the United States are piloting neural network-based detection for atrial fibrillation onset, though FDA predetermined change control plans constrain model update frequency. This technology compression is forcing manufacturers to choose between regulatory certainty and diagnostic performance evolution.
EU MDR post-market surveillance requirements now mandate periodic safety update reports for Class IIb monitors with arrhythmia detection claims. Manufacturers must establish systematic procedures for collecting and analyzing clinical data from deployed devices, with notified bodies conducting unannounced audits of quality management systems. High-acuity units in France and the Netherlands are prioritizing MDR-certified devices in procurement specifications, accelerating replacement cycles for pre-2021 installations.
Subscription-based telemetry service models are displacing capital equipment purchases in US health system procurement. Hospital networks in Texas and Florida are unbundling hardware acquisition from continuous monitoring services, paying per-monitored-patient-day fees that shift total cost of ownership calculations. This consumption-pattern shift favors manufacturers with cloud-native platform architectures over legacy central station vendors.
ICU ECG Patient Monitor Market Segmentation
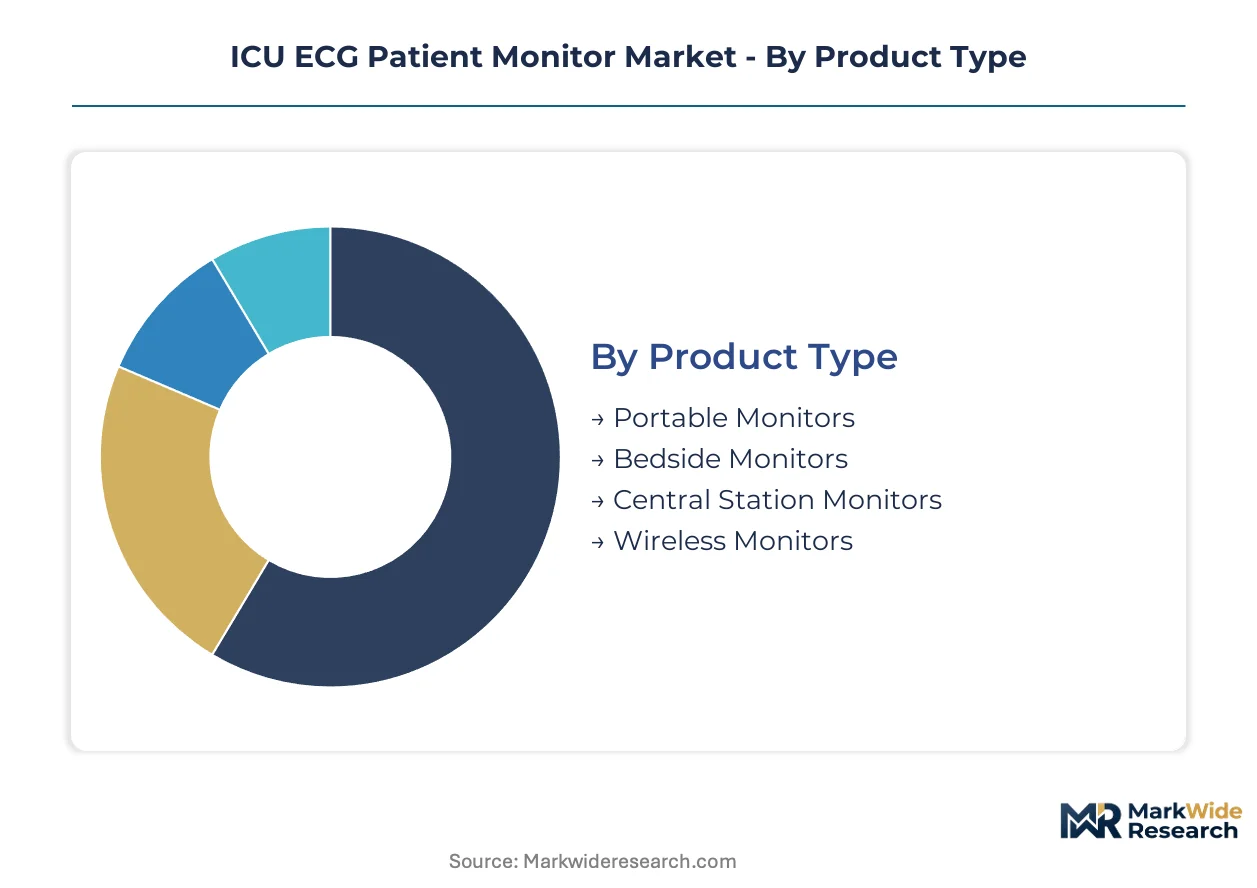
Segmentation in the ICU ECG patient monitor market reveals how substitution pressures and technology transitions redistribute procurement budgets across hardware categories. Product architecture choices determine whether health systems lock into centralized infrastructure or migrate toward distributed telemetry models.
Product Type:
Wireless telemetry architectures exert the strongest substitution pressure on traditional central station deployments, compressing hardware margins and forcing incumbents toward service-based revenue models.
- Portable Monitors:Battery-powered units with lithium cylindrical cells enable patient mobility during intra-hospital transport and step-down unit transfers. Demand concentrates in US health systems decentralizing monitoring beyond traditional ICU footprints, driven by subscription telemetry contracts replacing capital purchases. Portable monitors represent the steepest expansion trajectory.
- Bedside Monitors:Fixed 3- to 12-lead configurations with sampling rates exceeding 250 Hz serve high-acuity hemodynamic surveillance. Procurement dominates tertiary care hospitals in Germany and China expanding critical care capacity, constrained by FDA 510(k) validation timelines for algorithm-upgraded platforms. Bedside monitors retain volume leadership.
- Central Station Monitors:Legacy hub architectures face consolidation from cloud-integrated distributed systems. Demand persists where Philips and GE installed bases require middleware coexistence.
- Wireless Monitors:Disposable patch-based dry electrode systems extend continuous monitoring into general wards. Adoption accelerates in French and Dutch hospitals prioritizing MDR-certified devices.
Bedside monitors retain volume leadership; portable monitors hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich hospital networks from budget-constrained alternative care settings with diverging procurement mechanisms.
- Hospitals:Tertiary care institutions in Sichuan and Guangdong provinces drive multi-parameter system procurement through provincial health commission funding. ICU bed expansion mandates create immediate demand for arrhythmia detection algorithms validated under FDA and MDR pathways.
- Long-term Care Facilities:Skilled nursing and post-acute settings redraw procurement patterns away from hospital-centric purchasing. Texas and Florida networks unbundle hardware from per-patient-day telemetry services.
- Emergency Medical Services:Pre-hospital transport requires ruggedized portable units with extended battery life. Procurement concentrates in municipal ambulance fleets.
- Home Care Providers:Remote patient monitoring programs demand cloud-native platforms with HL7 FHIR interoperability. Indian district hospital networks under the National Health Mission create white space for hub-and-spoke architectures.
Hospitals dominate absolute procurement volume; long-term care facilities are gaining share fastest.
Technology:
Application-specific performance requirements separate high-fidelity diagnostic platforms from cost-optimized monitoring solutions with diverging regulatory burdens.
- Digital Monitoring:High-resolution signal processing with locked algorithm versions enables ST-segment deviation detection. German tertiary hospitals pilot neural network-based atrial fibrillation classification constrained by FDA predetermined change control plans.
- Wireless Technology:Cloud-integrated telemetry with FHIR standardization differentiates procurement evaluations against Epic and Cerner deployments. Mindray leverages cost-optimized digital platforms in emerging hospital systems.
- Analog Monitoring:Legacy amplifier architectures persist in price-sensitive installations with minimal algorithm dependencies. Replacement cycles accelerate as MDR post-market surveillance mandates tighten.
- Hybrid Systems:Combined analog-digital signal paths bridge installed base compatibility with enhanced arrhythmia detection. Philips anchors positioning through backward integration into sensor technology.
Digital monitoring commands the premium tier; wireless technology expands most quickly.
Installation:
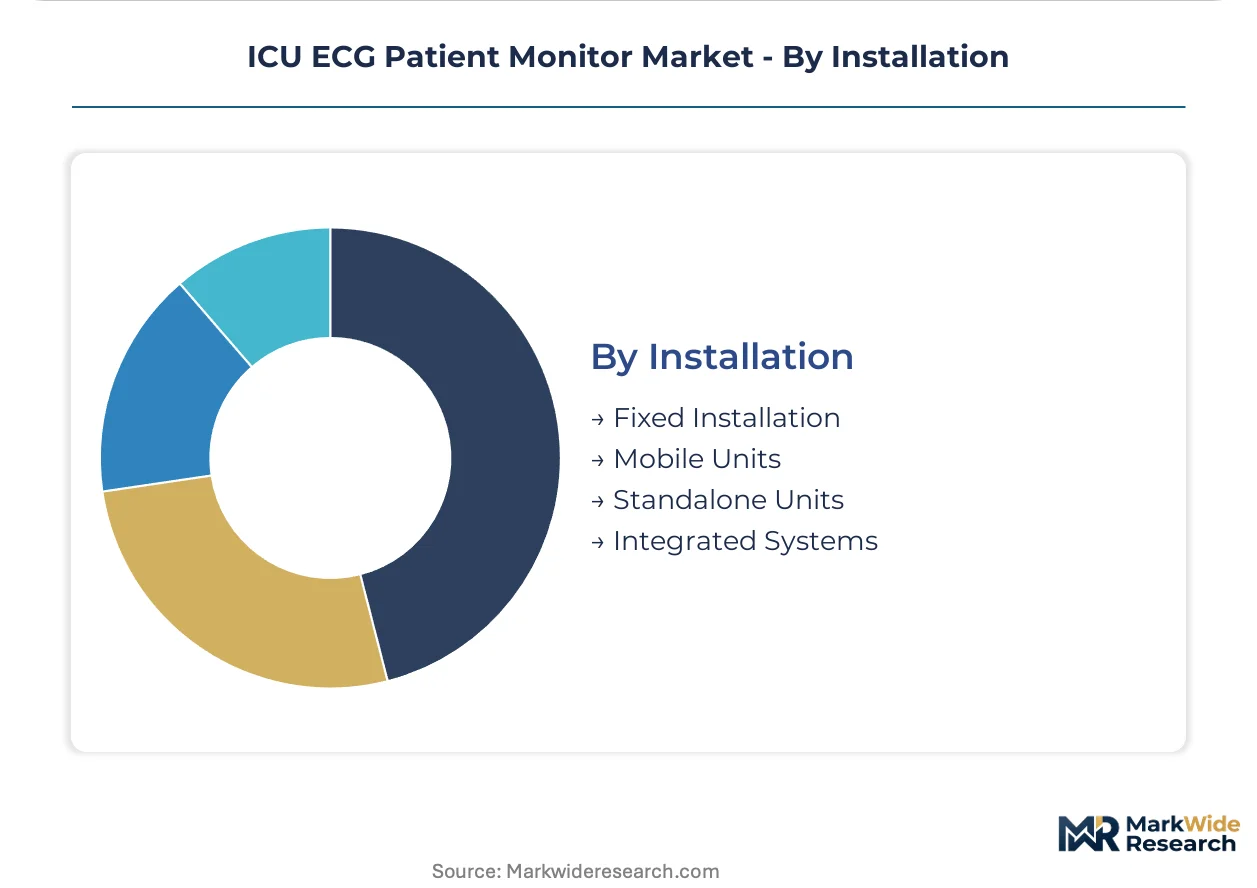
Customer type and infrastructure maturity determine whether procurement favors permanent integration or flexible deployment models.
- Fixed Installation:Hardwired bedside configurations with dedicated power and network infrastructure serve high-acuity units requiring 24/7 surveillance. GE Healthcare competes on manufacturing scale across North American and European production networks.
- Mobile Units:Cart-based or wearable deployments enable rapid redeployment across clinical zones. Demand concentrates in emergency departments and procedural suites.
- Standalone Units:Self-contained monitors with local display and storage operate without central station dependency. Rural hospital networks in India lack centralized infrastructure for distributed architectures.
- Integrated Systems:Enterprise-wide monitoring with EHR interoperability and networked alarm management commands health system procurement. Biomedical engineer talent scarcity constrains deployment velocity for network security hardening.
Fixed installation maintains the largest installed base; integrated systems show the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Beijing high-speed rail corridor enables rapid distribution of multi-parameter monitoring systems across China's hospital network, while Frankfurt Airport's cargo hub anchors European medical device logistics for ICU equipment.
United States
Texas and Florida health networks unbundle hardware from per-patient-day telemetry subscriptions, shifting procurement toward cloud-native platforms. FDA 510(k) predicate device clearances accelerate algorithm-upgraded monitor approvals. The Greater Boston biomedical cluster hosts pilot programs for neural network-based atrial fibrillation detection in tertiary care settings.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia pilot AI-enabled arrhythmia classification under constrained FDA predetermined change control plans. EU MDR Class IIb certification mandates tighten post-market surveillance with periodic safety update reports. The Baden-Württemberg medical technology corridor concentrates manufacturing scale for bedside monitor production.
China
Provincial health commissions in Sichuan and Guangdong fund 15-20% ICU bed expansion, creating immediate demand for arrhythmia detection algorithms. NMPA regulatory pathways govern multi-parameter system approvals for critical care capacity builds. The Yangtze River Delta manufacturing belt supplies lithium cylindrical cells for portable monitor fleets.
India
District hospital networks under the National Health Mission lack centralized monitoring infrastructure, opening white space for hub-and-spoke telemetry architectures. CDSCO medical device regulations require import license compliance for foreign-manufactured monitors. The Karnataka medical device cluster in Bengaluru assembles cost-optimized digital platforms for emerging hospital systems.
France
High-acuity units in Paris and the Netherlands prioritize MDR-certified devices, accelerating replacement cycles for pre-2021 installations. ANSM post-market surveillance aligns with EU-wide safety reporting for Class IIb arrhythmia detection claims. The Île-de-France healthcare procurement hub consolidates multi-hospital telemetry service contracts.
ICU ECG Patient Monitor Market Competitive Landscape
Listed leaders compete with private specialists across algorithm development and sensor integration capabilities. The market structures around three tiers: diversified conglomerates with backward integration into proprietary components, mid-scale manufacturers leveraging cost-optimized production networks, and niche specialists focused on disposable patch-based systems. Strategic moves concentrate on M&A for algorithm portfolios and capacity expansion in lithium battery supply chains.
Within the diversified medical technology tier, Philips Healthcare and GE Healthcare exemplify archetypes with captive sensor technology and manufacturing scale across North American and European production networks. Mindray occupies a position representing cost-optimized digital platform specialists extending into emerging hospital systems. Siemens Healthineers anchors the European-based tier with quality management alignment across ISO 13485:2016 harmonized standards.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| Mindray |
| Nihon Kohden |
| Medtronic |
| Zoll Medical |
| Schiller |
| Drägerwerk |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale in the Yangtze River Delta and Baden-Württemberg corridors anchors cost floors for multi-parameter bedside systems, concentrating supply-side leverage among producers with captive sensor technology and algorithm development capabilities. This scale asymmetry forces mid-tier competitors toward subscription telemetry models that trade hardware margins for recurring revenue streams, compressing upfront price points while extending customer lifetime value capture.
Pricing Analysis
Volume-discount tiering structures separate procurement for tertiary care networks purchasing 500-plus unit fleets from district hospital orders below fifty units, with the former commanding 15-25% effective price reductions through multi-year service bundling. Pricing stratifies across FDA 510(k)-cleared premium tiers, MDR-certified standard tiers, and pre-certified economy tiers for emerging markets. Cost compression in the wireless telemetry segment is intensifying because Mindray and emerging Asian manufacturers are exporting cost-optimized digital platforms at 40% below incumbent landed costs. Long-term care facilities in Texas and Florida exhibit highest price sensitivity through per-patient-day telemetry contracts, while German tertiary hospitals demonstrate lowest sensitivity due to algorithm performance requirements and MDR compliance mandates.
Supply Chain Analysis
Inventory lead times for lithium cylindrical cells extended from six to fourteen weeks during recent export control volatility, exposing portable monitor fleets to production scheduling disruptions. Manufacturing concentrates in China for lithium battery assembly and flexible printed circuit fabrication, in Germany for precision amplifier components, and in the United States for FDA-validated algorithm processing modules. Raw material dependencies include lithium carbonate from South American salares, dry electrode silver-silver chloride inks from Japanese chemical specialists, and medical-grade ABS housings from Korean petrochemical networks. Single-source vulnerability in East Asian cylindrical cell supply chains feeds from forced labor due diligence mandates and export licensing unpredictability. Distribution runs through health system GPO contracts in the United States, provincial health commission tenders in China, and hospital federation frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICU ECG patient monitor adoption sits in early-cycle expansion as wireless telemetry architectures displace legacy central station deployments and cloud-integrated distributed systems penetrate step-down units and long-term care facilities previously unserved by continuous cardiac monitoring.
For Market Incumbents: Shield installed base revenue through backward integration into disposable dry electrode manufacturing and proprietary ST-segment algorithm development that locks hospital networks into consumable-dependent platforms. Accelerate FDA 510(k) predicate clearances for algorithm-upgraded monitors to compress emerging competitor time-to-market advantages. Consolidate middleware development capabilities for seamless coexistence with legacy Philips and GE central station infrastructure, reducing customer switching incentives toward greenfield cloud-native deployments. For New Entrants and Emerging Players: Cloud-integrated telemetry service gaps in Indian district hospital networks under the National Health Mission offer immediate white-space penetration through hub-and-spoke architectures that bypass centralized infrastructure requirements. Rural hospital telemetry in Sichuan and Guangdong provinces presents secondary penetration vectors alongside provincial health commission funding flows for ICU bed expansion. Target cost-optimized digital platforms with HL7 FHIR interoperability as the primary go-to-market angle, differentiating against legacy hardware-centric procurement in health system evaluations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with cloud-native platform architectures and per-patient-day telemetry contracts, positioning these archetypes for premium valuation multiples over hardware-dependent competitors. Long-term viability across the five-to-ten year window hinges on algorithm portfolio depth and MDR certification breadth rather than manufacturing scale alone. Acquisition targets should demonstrate locked-algorithm FDA clearances with predetermined change control plans or disposable patch-based monitor portfolios. Monitor EU MDR post-market surveillance enforcement intensity as the critical inflection signal for replacement cycle acceleration among pre-2021 installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIb Certification Investment | Accelerates hospital procurement in France and Netherlands where MDR compliance is mandatory. |
| Disposable Patch Monitor Development | Extends continuous monitoring beyond ICU into general wards and step-down units. |
| Cloud-Native Platform Architecture | Enables per-patient-day telemetry subscriptions displacing capital equipment purchases. |
| Algorithm Portfolio Acquisition | Consolidates ST-segment and atrial fibrillation detection capabilities under single quality management systems. |
| Lithium Battery Supply Diversification | Reduces forced labor due diligence exposure and export control vulnerability in cylindrical cell procurement. |
Research Methodology
A standing panel of critical care clinicians, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at FDA-notified bodies provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body certification registries, hospital procurement databases tracking multi-parameter monitor tenders, CMS Medicare reimbursement filings for remote patient monitoring, and NMPA medical device approval announcements. Bottom-up unit demand estimates triangulated against top-down healthcare expenditure allocations for critical care infrastructure.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled dimensions spanning product architecture, end-user setting, signal processing technology, and installation type alongside regional regulatory cluster differentiation. CAGRs were derived from fitted adoption curves incorporating ICU bed expansion mandates, algorithm validation timeline constraints, and telemetry service contract penetration rates. Industry-specific forecast inputs included lithium battery supply lead time volatility and MDR post-market surveillance enforcement intensity.
Material uncertainties — regulatory timeline delays, supply chain disruption severity, and algorithm performance validation outcomes — sit outside the modeled envelope. Forecasts reflect assumptions regarding health system procurement mechanism evolution and wireless technology commoditization pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Portable Multi-Parameter Monitors Market