
 Germany Patient Care Monitoring Equipment Market | 2026-2036
Germany Patient Care Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Patient Care Monitoring Equipment Market Foresight
Equipment leasing and pay-per-use financing is fragmenting competitive access across German healthcare procurement. Siemens Healthineers leverages its domestic manufacturing footprint to sustain service contracts with major hospital networks. Draegerwerk AG anchors its position through specialized anesthesia and ventilation monitoring integration. Koninklijke Philips NV competes by extending its cloud-connected patient monitoring platforms into ambulatory settings.
Germany Patient Care Monitoring Equipment encompasses bedside terminals, wearable biosensors, and networked central stations that track vital signs through continuous multi-parameter acquisition, typically sampling ECG, SpO2, and invasive pressures at 250-500 Hz for real-time alarm generation. These systems serve primarily to reduce unplanned ICU admissions and enable earlier clinical intervention in acute care workflows. Wireless monitors lead installed base value due to their role in flexible ward configurations, while IoT-enabled devices represent the fastest-expanding technology segment as hospitals pursue interoperability with electronic health records. Homecare settings emerge as a concentrated margin pool where remote monitoring subscriptions offset capital equipment commoditization.
The EU Medical Device Regulation and Germany's Federal Institute for Drugs and Medical Devices enforce escalating clinical evidence requirements for software-as-a-medical-device functionalities, compelling manufacturers to revalidate algorithm updates through notified bodies. BSI Group and TÜV SÜD serve as primary conformity assessment entities for German market access, with CE marking timelines extending for novel sensor fusion products. Stakeholders must weigh regulatory certification costs against the strategic imperative to deploy AI-augmented monitoring before reimbursement pathways solidify.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product development timelines while Bavaria's university hospital clusters concentrate procurement power, creating a bifurcated market where compliance costs favor incumbent manufacturers with established notified body relationships.
Growth Catalysts
- EU MDR compliance mandates:The Medical Device Regulation's software-as-a-medical-device classification accelerates validation investments for AI-augmented monitoring algorithms, locking in early-mover advantages for manufacturers with BSI Group or TÜV SÜD certification pathways.
- Bavaria hospital network consolidation:University hospital clusters in Munich and Erlangen are standardizing on interoperable central station architectures, creating anchor demand that pulls through ward-level device procurement across southern Germany.
- IoT-enabled remote monitoring:Wireless biosensors with EHR-integrated data streams are displacing hardwired bedside terminals in flexible ward configurations, enabling real-time patient surveillance without fixed infrastructure investments.
Market Restraints
- CE marking timeline extension:The EU MDR's clinical evidence requirements for novel sensor fusion products have stretched notified body review periods, delaying market entry for algorithm-dependent monitoring innovations.
- Semiconductor supply concentration:Custom ASICs for high-frequency vital sign acquisition depend on concentrated East Asian foundry capacity, exposing German manufacturers to input volatility and extended lead times for 250-500 Hz sampling chipsets.
- Capital equipment commoditization:Standard multi-parameter monitors face price pressure from Asian contract manufacturers, compressing margins on hardware sales and forcing reliance on service contract renewals for profitability.
Strategic Opportunities
- Homecare subscription models:Remote patient monitoring services for post-acute cardiac and respiratory patients represent underpenetrated recurring revenue streams, offsetting capital equipment margin erosion through SaaS-style billing.
- Baden-Württemberg ambulatory expansion:Stuttgart's integrated care networks are piloting cloud-connected monitoring platforms in outpatient settings, creating template contracts replicable across southwestern Germany's statutory health insurance regions.
- AI Act compliance pre-positioning:Germany's Federal Institute for Drugs and Medical Devices is aligning with EU AI Act risk classification frameworks, enabling first-movers to secure preferred reimbursement status for algorithm-augmented diagnostic monitoring.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time 250-500 Hz signal processing requires specialized expertise in medical-grade embedded Linux, with talent concentrated among Siemens Healthineers and Draegerwerk AG engineering alumni.
- Legacy device interoperability:Hospital networks in North Rhine-Westphalia operate heterogeneous installed bases spanning three decades of proprietary communication protocols, complicating centralized alarm management and data aggregation.
- Notified body capacity bottlenecks:BSI Group and TÜV SÜD face surging MDR certification demand, creating 12-18 month queues for software update revalidation that conflict with agile algorithm development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Patient Care Monitoring Equipment Market |
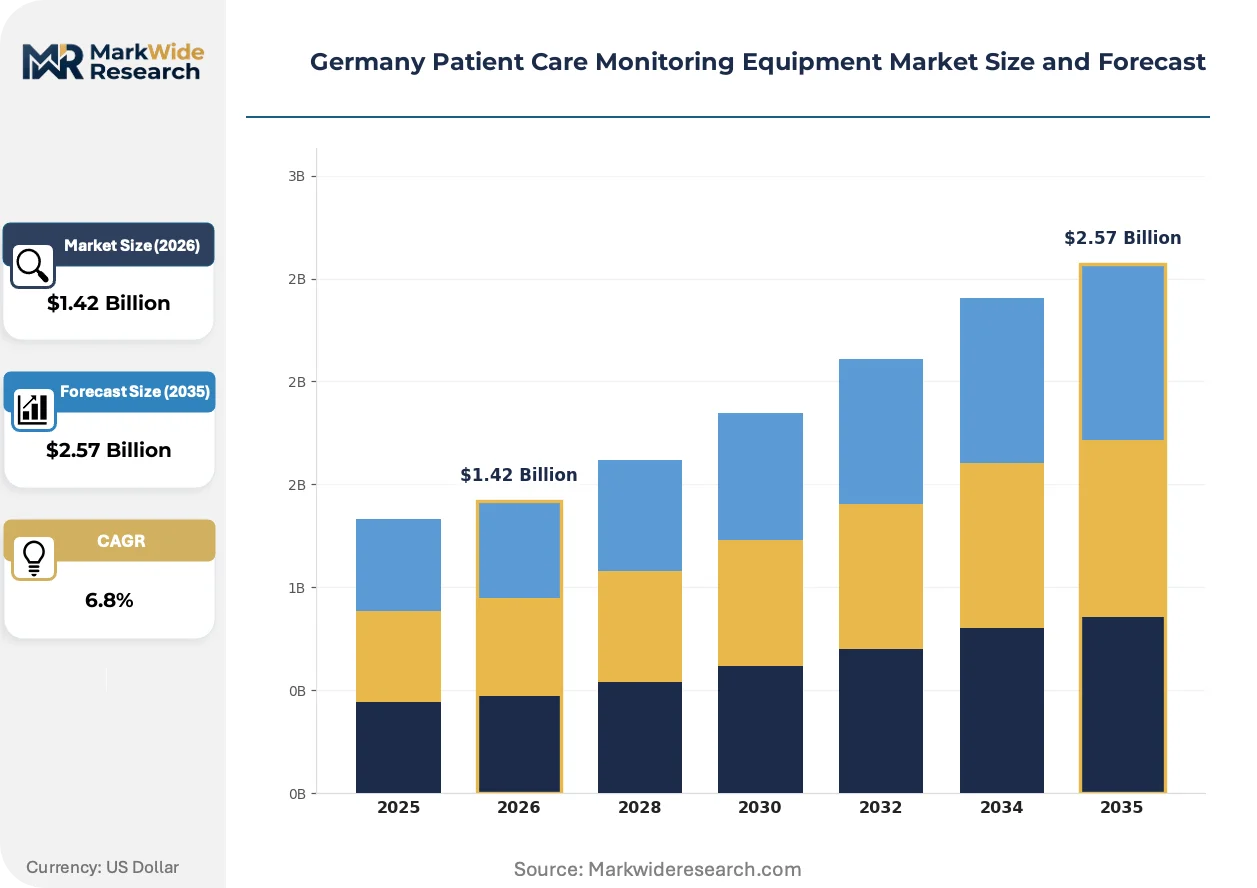
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Monitors, Wearable Devices, Bedside Monitors, Central Monitoring Systems Application: Heart Rate Monitoring, Respiratory Monitoring, Temperature Management, Blood Pressure Monitoring End User: Hospitals, Homecare Settings, Rehabilitation Centers, Urgent Care Clinics Technology: Telehealth, IoT-Enabled Devices, Cloud-Based Solutions, Mobile Health Apps |
| Companies Covered | Draegerwerk AG, Siemens Healthineers, Koninklijke Philips NV, GE Healthcare, Medtronic Plc, Abbott Laboratories, B. Braun Melsungen AG, BIOTRONIK, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Patient Care Monitoring Equipment Market Shifts & Advancements
Edge computing architectures and federated learning frameworks are redistributing data processing from hospital servers to bedside devices, compressing latency for clinical decision support while complicating cybersecurity postures.
Sensor fusion chipsets integrating photoplethysmography with impedance cardiography are collapsing the distinction between continuous monitoring and diagnostic-grade measurement, enabling single-device deployment across general wards and step-down units. Charité Berlin and Heidelberg University Hospital are piloting these platforms in mixed-acuity settings, eliminating the capital expense of separate telemetry systems for intermediate-care patients.
The EU AI Act's risk-based classification system is mandating conformity assessments for machine-learning-enabled alarm suppression algorithms, forcing manufacturers to document training data provenance and performance drift monitoring. Germany's Federal Institute for Drugs and Medical Devices is interpreting these requirements through MDR lens, creating dual-track compliance that favors established players with dedicated regulatory affairs functions over venture-stage entrants.
Hospital procurement consortia in Lower Saxony and Hamburg are unbundling device acquisition from multi-year service agreements, shifting vendor relationships toward transactional hardware sales paired with competitive third-party maintenance contracts. This disaggregation pressures manufacturers to defend margin through software subscription attach rates rather than captive service revenue, with the trend most visible among mid-sized municipal hospital networks seeking budget flexibility.
Germany Patient Care Monitoring Equipment Market Segmentation
Segmentation reveals distinct service contract profiles across German procurement channels. Equipment categories demand differentiated field engineering density, while application types drive calibration frequency and consumable attach rates. Understanding these patterns enables targeted margin defense against third-party maintenance disaggregation.
Product Type:
After-sales-service intensity varies dramatically across hardware categories, with centralized architectures demanding continuous firmware stewardship and distributed wearables requiring battery logistics networks.
- Wireless Monitors:Battery-powered bedside units transmit ECG, SpO2, and invasive pressures at 250-500 Hz through hospital WiFi mesh networks. Bavaria's university hospital clusters in Munich and Erlangen are standardizing on these flexible ward configurations to eliminate hardwired infrastructure costs during facility renovations.
- Wearable Devices:Patch-form biosensors with multi-day adhesive attachment enable ambulatory telemetry for intermediate-acuity patients. Stuttgart's integrated care networks in Baden-Württemberg are piloting these for post-acute cardiac surveillance, creating template contracts replicable across statutory health insurance regions.
- Bedside Monitors:Fixed-location multi-parameter terminals with integrated alarm management serve traditional ICU and step-down unit deployments.
- Central Monitoring Systems:Server-integrated architectures aggregate ward-level data streams for centralized alarm surveillance and clinical decision support.
Wireless Monitors holds the largest share; momentum sits with Wearable Devices.
Application:
Application-specific calibration protocols create diverging margin profiles, with continuous modalities requiring more frequent sensor replacement than intermittent spot-check measurements.
- Heart Rate Monitoring:Continuous ECG acquisition with arrhythmia detection algorithms dominates telemetry service revenue. North Rhine-Westphalia hospital networks operate heterogeneous installed bases spanning three decades of proprietary protocols, complicating centralized alarm management for cardiac surveillance.
- Respiratory Monitoring:Capnography and pulse oximetry integration enables early detection of respiratory depression in post-surgical wards. Charité Berlin and Heidelberg University Hospital are piloting combined cardiac-respiratory sensor fusion platforms in mixed-acuity settings, eliminating separate telemetry capital expenses.
- Temperature Management:Continuous core temperature tracking supports perioperative hypothermia prevention and sepsis detection protocols.
- Blood Pressure Monitoring:Non-invasive oscillometric and invasive arterial line modalities serve distinct acuity tiers across general wards and ICUs.
Heart Rate Monitoring anchors installed base value; Respiratory Monitoring is climbing the fastest as sensor fusion collapses diagnostic boundaries.
End User:
Customer-type concentration determines contract structure, with hospital networks favoring multi-year service agreements and homecare channels shifting toward subscription billing models.
- Hospitals:Acute care networks drive capital equipment procurement with attached multi-year maintenance contracts. Lower Saxony and Hamburg procurement consortia are unbundling device acquisition from service agreements, shifting relationships toward transactional hardware sales with competitive third-party maintenance.
- Homecare Settings:Post-acute cardiac and respiratory patients represent concentrated margin pools where remote monitoring subscriptions offset capital equipment commoditization. Homecare emerges as the fastest-expanding customer segment as statutory insurers pilot reimbursement for ambulatory telemetry.
- Rehabilitation Centers:Step-down facilities require intermediate-acuity monitoring during patient recovery transitions.
- Urgent Care Clinics:Freestanding emergency departments demand rapid-deployment monitoring for episodic high-acuity presentations.
Hospitals retain dominant procurement volume; Homecare Settings show the steepest expansion trajectory.
Technology:
Technology architecture determines regulatory pathway complexity, with cloud-connected platforms facing dual MDR and AI Act compliance obligations that favor established notified body relationships.
- Telehealth:Synchronous video consultation platforms with integrated vital sign streaming enable remote specialist consultation. TÜV SÜD and BSI Group certification queues for software-as-a-medical-device functionalities are extending CE marking timelines, delaying market entry for algorithm-dependent telehealth innovations.
- IoT-Enabled Devices:Sensor networks with EHR-integrated data streams represent the fastest-expanding technology segment as hospitals pursue interoperability with electronic health records. Edge computing architectures are redistributing processing from hospital servers to bedside devices, compressing latency while complicating cybersecurity postures.
- Cloud-Based Solutions:Centralized data aggregation platforms enable multi-site alarm management and predictive analytics deployment.
- Mobile Health Apps:Smartphone-integrated patient-facing interfaces support self-monitoring and medication adherence protocols.
Telehealth holds mature installed base share; IoT-Enabled Devices are gaining share fastest through flexible ward configuration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Institute for Drugs and Medical Devices enforces escalating EU MDR compliance requirements that reshape procurement patterns across federal states. Hospital network consolidation and university hospital cluster standardization drive divergent demand profiles.
Bavaria
University hospital clusters in Munich and Erlangen anchor southern Germany's procurement power, standardizing on interoperable central station architectures. These networks pull through ward-level device procurement decisions across affiliated municipal hospitals. The state's dense concentration of medical engineering graduates feeds embedded systems talent into local manufacturers.
North Rhine-Westphalia
Legacy device heterogeneity complicates centralized alarm management across hospital networks operating three decades of proprietary protocols. Procurement consortia in Lower Saxony and Hamburg are unbundling device acquisition from multi-year service agreements. Cologne and Düsseldorf hospital systems drive transactional hardware sales with competitive third-party maintenance contracts.
Baden-Württemberg
Stuttgart's integrated care networks pilot cloud-connected monitoring platforms in outpatient settings, creating template contracts replicable across statutory health insurance regions. The state's automotive electronics ecosystem supplies embedded engineering expertise for real-time signal processing firmware. Mannheim and Karlsruhe medical device suppliers cluster around university hospital procurement channels.
Berlin-Brandenburg
Charité Berlin pilots sensor fusion platforms in mixed-acuity settings, eliminating separate telemetry capital expenses for intermediate-care patients. The capital region's research hospitals attract early-stage device validation partnerships with notified bodies. Potsdam health technology startups cluster around telehealth platform development.
Hamburg
Procurement consortia in this northern port city unbundle device acquisition from service agreements, shifting vendor relationships toward transactional hardware sales. The city's university hospital network standardizes on flexible ward configurations during facility renovations. Maritime medical supply logistics capabilities support battery logistics networks for wearable device distribution.
Germany Patient Care Monitoring Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around notified body relationships and domestic manufacturing footprints that compress compliance timelines for EU MDR certification. Three archetypes dominate: diversified health technology conglomerates with captive regulatory affairs functions, specialized anesthesia and ventilation monitoring integrators, and cloud platform extenders from adjacent diagnostic imaging segments. Competitive moves concentrate on service contract bundling to offset hardware margin compression, and strategic partnerships with university hospitals for algorithm validation.
Among Germany-based diversified health technology conglomerates, Siemens Healthineers and Draegerwerk AG exemplify contrasting strategic positions. Siemens Healthineers leverages its domestic manufacturing footprint to sustain service contracts with major hospital networks, while Draegerwerk AG anchors its position through specialized anesthesia and ventilation monitoring integration. Koninklijke Philips NV represents the cloud platform extender archetype, competing by extending connected patient monitoring platforms into ambulatory settings. These three players occupy positions that reflect divergent responses to procurement unbundling and subscription model emergence.
| Leading Market Players |
|---|
| Draegerwerk AG |
| Siemens Healthineers |
| Koninklijke Philips NV |
| GE Healthcare |
| Medtronic Plc |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| BIOTRONIK |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for 250-500 Hz sampling ASICs funnels margin pools toward manufacturers with captive firmware development and notified body pre-certification. German hospital procurement unbundling shifts pricing power from hardware markups to software subscription attach rates.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with BSI Group and TÜV SÜD MDR pathways commanding price premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm complexity and EHR interoperability depth. Pricing pressure stems from Asian contract manufacturer entry into multi-parameter monitor hardware. Municipal hospital networks in Lower Saxony exhibit highest price sensitivity, while Bavaria's university hospital clusters prioritize interoperability over unit cost.
Supply Chain Analysis
Extended payment terms from German hospital procurement consortia compress working capital for component suppliers upstream. Custom ASIC fabrication draws from Taiwan, South Korea, and Japan; adhesive biosensor materials rest on German chemical specialty suppliers. Single-source vulnerability concentrates in high-frequency signal processing chipsets. Distribution runs through regional medical device wholesalers with field engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's patient care monitoring market sits in early-cycle expansion as statutory insurers pilot reimbursement for ambulatory telemetry, creating runway for subscription revenue models before competitive saturation sets in.
For Market Incumbents: Build regulatory moats through BSI Group and TÜV SÜD pre-certification for AI-augmented algorithms ahead of EU AI Act implementation. Deepen firmware stewardship capabilities to defend service contract renewal rates against third-party maintenance disaggregation in North Rhine-Westphalia and Hamburg procurement consortia. For New Entrants and Emerging Players: Build out homecare subscription infrastructure targeting post-acute cardiac patients in Baden-Württemberg, where Stuttgart's integrated care networks seek cloud-connected platform partners. Partner with Potsdam health technology clusters for telehealth platform distribution into Berlin-Brandenburg research hospitals. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed IoT sensor developers holding MDR certification queues but lacking hospital network service infrastructure. Five-to-ten year viability hinges on reimbursement pathway solidification for algorithm-augmented monitoring. Watch BSI Group and TÜV SÜD capacity expansion as inflection signal for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | BSI Group and TÜV SÜD pre-certification compresses market entry timelines for algorithm updates. |
| Hospital System Partnership | Bavaria's university hospital clusters standardize procurement across affiliated municipal networks. |
| Software Companion Development | EHR-integrated data streams displace hardwired bedside terminals in flexible ward configurations. |
| Reimbursement Strategy | Statutory health insurance pilot programs in Baden-Württemberg create template contracts for ambulatory telemetry. |
| Backward Integration | In-house ASIC design capabilities reduce exposure to East Asian foundry lead time volatility. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies; and secondary validation through hospital procurement databases, GPO contract filings, BSI Group certification records, and CMS-equivalent German reimbursement data. Bottom-up equipment unit estimates triangulated against top-down healthcare capital expenditure flows.
Forecast inputs span product type, application modality, end-user channel, and technology architecture across the analysis window. CAGRs derive from segment-level adoption curves weighted by MDR compliance timeline assumptions and semiconductor supply elasticity. Homecare subscription penetration and AI Act risk classification implementation pace serve as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-platform entrants from diagnostic imaging would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Health Sensors Market