
 Holter Monitor Market | 2026-2036
Holter Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Holter Monitor Market Analytics
Multi-source procurement of electrocardiography sensors and data-acquisition chipsets is realigning how Holter monitor manufacturers secure component supply. Philips sustains broad geographic manufacturing for its ambulatory monitoring portfolio across European and Asian assembly sites. GE Healthcare leverages deep installed-base relationships with hospital systems to protect recurring service revenue streams. iRhythm Technologies specializes in pure-play algorithm-driven arrhythmia detection, bypassing conventional hardware-centric competition.
A Holter monitor is a portable electrocardiographic device that continuously records cardiac electrical activity over 24 to 48 hours—or up to 14 days in extended-wear configurations—using 3-lead or 12-lead electrode configurations to capture transient arrhythmias outside clinical settings. The primary purpose is diagnostic surveillance for intermittent rhythm disorders, myocardial ischemia, and medication response assessment in ambulatory patients. Wireless Holter systems now lead product-type preference as cardiac telemetry shifts toward patient-discrete form factors that minimize lifestyle disruption during extended monitoring. Home care represents the fastest-expanding end-user channel, propelled by reimbursement alignment for remote cardiac monitoring and patient preference for non-facility-based diagnostics.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked ambulatory ECG systems in Europe. Japan's PMDA enforces QMS conformity and localized clinical validation for imported cardiac monitoring devices, adding compliance cost layers for foreign entrants. Stakeholders must track evolving software-as-a-medical-device classifications as cloud-based arrhythmia algorithms attract heightened regulatory scrutiny across major jurisdictions.
Market Dynamics
Wireless Holter systems are consolidating diagnostic workflows around patient-discrete form factors, compressing hardware margins while elevating algorithmic differentiation as the primary value capture mechanism.
Growth Catalysts
- CMS Reimbursement Frameworks:Remote patient monitoring codes in the United States reimburse ambulatory electrocardiography at rates that accelerate outpatient clinic adoption. Cardiology practices expand program infrastructure to capture these revenue streams.
- Patient Mobility Prioritization:Germany's health technology assessment bodies now weight diagnostic yield per patient disruption hour, tilting procurement toward wearable patch configurations. Hospital systems respond with fleet conversions.
- Extended-Wear Electrode Materials:Hydrogel-silver chloride formulations enable 14-day continuous recording without skin irritation. Manufacturers secure supply agreements with specialty chemical producers.
Market Restraints
- Data-Acquisition Chipset Concentration:Three Asian foundries fabricate the analog-to-digital converters essential for multi-lead signal fidelity. Geographic supply risk constrains production scaling.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates prospective studies for algorithm-upgraded legacy devices. Certification timelines extend by 18-24 months for cloud-connected systems.
- Consumer Wearable Substitution:Apple Watch and Samsung Galaxy Watch irregular rhythm notifications capture low-acuity screening demand. Primary care referrals to formal Holter monitoring flatten.
Strategic Opportunities
- Home Care Channel Expansion:Japan's Ministry of Health, Labour and Welfare expands long-term care insurance coverage for domiciliary cardiac monitoring. Home health agencies build device deployment capabilities.
- AI-ECG Convergence:Deep learning models trained on million-scale arrhythmia databases now run on edge processors within patch electrodes. Algorithm developers partner with semiconductor foundries.
- Post-Acute Care Integration:Skilled nursing facilities in the United States adopt transitional care management protocols requiring 30-day cardiac surveillance. Device vendors configure rental programs for this channel.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:The intersection of electrophysiology expertise and embedded systems engineering commands premium compensation. Manufacturers compete with autonomous vehicle and aerospace sectors.
- Legacy EHR Integration Complexity:Hospital systems running Cerner and Epic installations require custom HL7 FHIR interfaces for cloud-based Holter data. Implementation costs erode margin on initial device sales.
- Software-as-Medical-Device Recertification:FDA 510(k) holders must resubmit when algorithm updates exceed predetermined change control plans. Continuous improvement cycles stall.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holter Monitor Market |
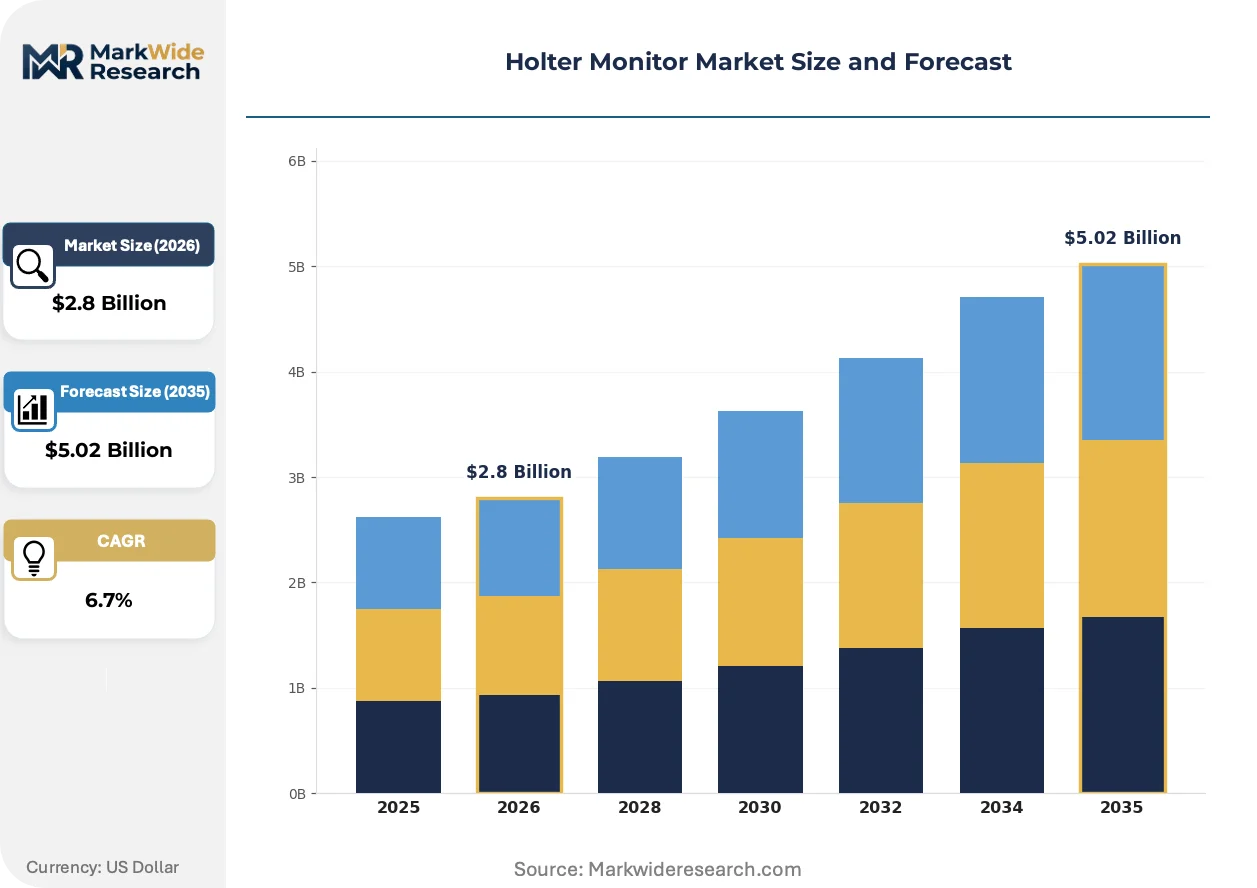
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Holter, Wired Holter, Mobile Holter, Wearable Holter End User: Hospitals, Cardiology Clinics, Home Care, Diagnostic Laboratories Technology: 3-Lead, 12-Lead, Digital Technology, Analog Technology Installation: Portable, Stationary, Center-based, Remote Monitoring |
| Companies Covered | Koninklijke Philips N.V., GE Healthcare, Hill-Rom Services, Inc. (Baxter), SCHILLER AG, Fukuda Denshi Co., Ltd., Nihon Kohden Corporation, Medtronic plc, BPL Medical Technologies, iRhythm Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holter Monitor Market Evolving Landscape
Holter monitor technology trajectories center on miniaturization, algorithmic autonomy, and reimbursement-driven channel migration. Three developments dominate current competitive positioning.
Patch-based electrode arrays are consolidating traditional wired Holter configurations into single-use disposable form factors. Outpatient cardiology clinics in Germany and Japan now specify 7-day and 14-day patch systems as default prescriptions. The technology is consolidating hardware revenue into consumable models while shifting value toward cloud-based interpretation services.
The EU Medical Device Regulation's software classification guidance is forcing algorithm developers to document clinical validation across intended use populations. Post-market surveillance requirements now capture real-world performance data from deployed devices. European notified bodies are prioritizing review resources toward cloud-connected systems, delaying clearance timelines for hardware-only submissions.
Hospital procurement departments are unbundling device acquisition from interpretation services, creating separate vendor relationships for hardware, software, and clinical reporting. Integrated delivery networks in the United States negotiate three-year managed service agreements that include device refresh cycles. This restructuring concentrates purchasing power among health system administrators and compresses unit economics for pure-play device manufacturers.
Holter Monitor Market Segmentation
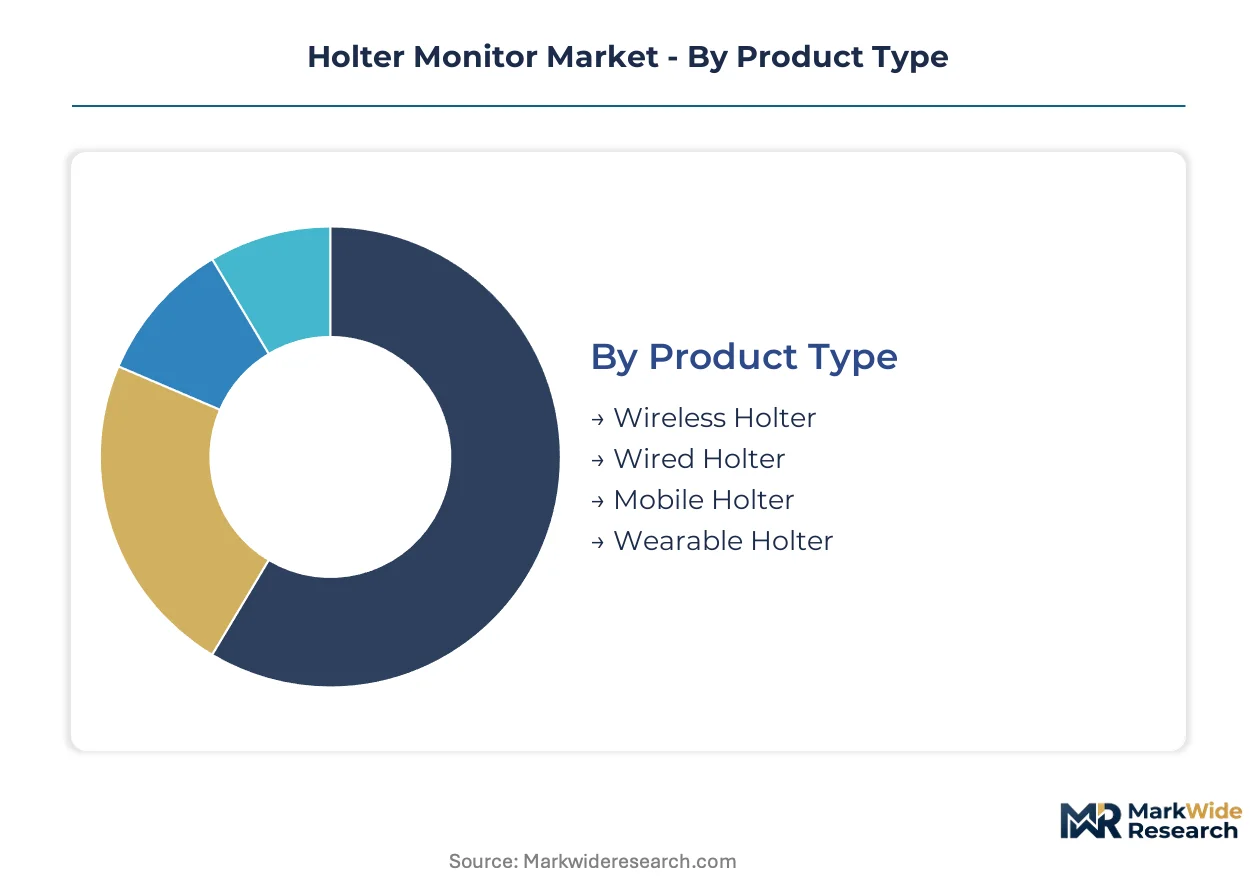
Holter monitor segmentation reveals divergent capital requirements across hardware configurations and service delivery models. Product architecture choices determine upfront R&D investment, while end-user channel selection shapes recurring revenue mechanics and regulatory compliance burdens.
Product Type:
Capital intensity peaks with wireless and wearable configurations demanding integrated semiconductor design, cloud infrastructure, and algorithm development. Wired systems require lower upfront engineering but face margin compression from commoditized components.
- Wireless Holter:Radio-frequency telemetry modules transmit ECG data to cloud platforms without patient-tethered recorders. US outpatient cardiology clinics prioritize these systems under CMS remote patient monitoring reimbursement codes. Philips and GE Healthcare allocate manufacturing capacity across European and Asian assembly sites to serve this segment.
- Wearable Holter:Patch-based disposable electrodes integrate analog-to-digital conversion directly on the skin-contact substrate. Germany's health technology assessment bodies now weight diagnostic yield per patient disruption hour, accelerating procurement shifts toward these patient-discrete form factors.
- Wired Holter:Traditional cable-connected electrode arrays with separate recording units.
- Mobile Holter:Smartphone-integrated systems leveraging consumer device processing power.
Wireless Holter absorbs the bulk of installed capacity; wearable Holter is expanding most quickly.
End User:
Customer type determines pricing power, contract duration, and service attachment rates. Hospital procurement departments negotiate multi-year managed service agreements, while home care channels demand flexible rental programs with rapid deployment logistics.
- Home Care:Domiciliary cardiac monitoring programs require logistics networks for device delivery, patient onboarding, and data transmission support. Japan's Ministry of Health, Labour and Welfare expanded long-term care insurance coverage for this channel, prompting home health agencies to build device deployment capabilities.
- Cardiology Clinics:Outpatient electrophysiology practices generate recurring revenue through interpretation services and device re-rental. US clinics expanded ambulatory electrocardiography programs to capture CMS reimbursement streams for extended arrhythmia surveillance.
- Hospitals:Acute care systems with integrated delivery networks.
- Diagnostic Laboratories:Centralized interpretation services unbundled from device provision.
Cardiology clinics command the highest service attachment rates; home care is climbing the fastest.
Technology:
Lead configuration and signal processing architecture determine component sourcing strategies and clinical validation requirements. Multi-lead systems demand specialized analog-to-digital converters from concentrated Asian foundry supply.
- 3-Lead:Standard ambulatory configuration capturing bipolar limb leads for rhythm analysis. Most wireless and wearable Holter systems deploy this reduced-lead approach to minimize power consumption and electrode count.
- 12-Lead:Full diagnostic electrocardiography enabling ST-segment analysis and localization of ischemic territories. Hospital-based stationary installations retain preference for this technology in pre-operative and post-acute cardiac surveillance protocols.
- Digital Technology:Software-defined signal processing with algorithm-upgradable firmware.
- Analog Technology:Hardware-fixed filtering and amplification circuits with lower flexibility.
3-Lead dominates ambulatory deployment volumes; 12-Lead retains premium positioning in acute settings.
Installation:
Physical deployment model shapes regulatory classification, reimbursement coding, and supply chain configuration. Portable and remote systems attract heightened FDA and EU MDR scrutiny for software-as-medical-device components.
- Remote Monitoring:Cloud-connected systems enabling real-time arrhythmia detection and clinician alerts. EU Medical Device Regulation mandates prospective clinical studies for algorithm-upgraded legacy devices in this category, extending certification timelines by 18-24 months.
- Portable:Patient-carried recorders with internal storage and periodic clinic download. This configuration balances mobility with regulatory simplicity, appealing to cardiology clinics navigating FDA 510(k) clearance pathways.
- Stationary:Fixed-installation systems in hospital telemetry units.
- Center-based:Hub-and-spoke models with centralized interpretation services.
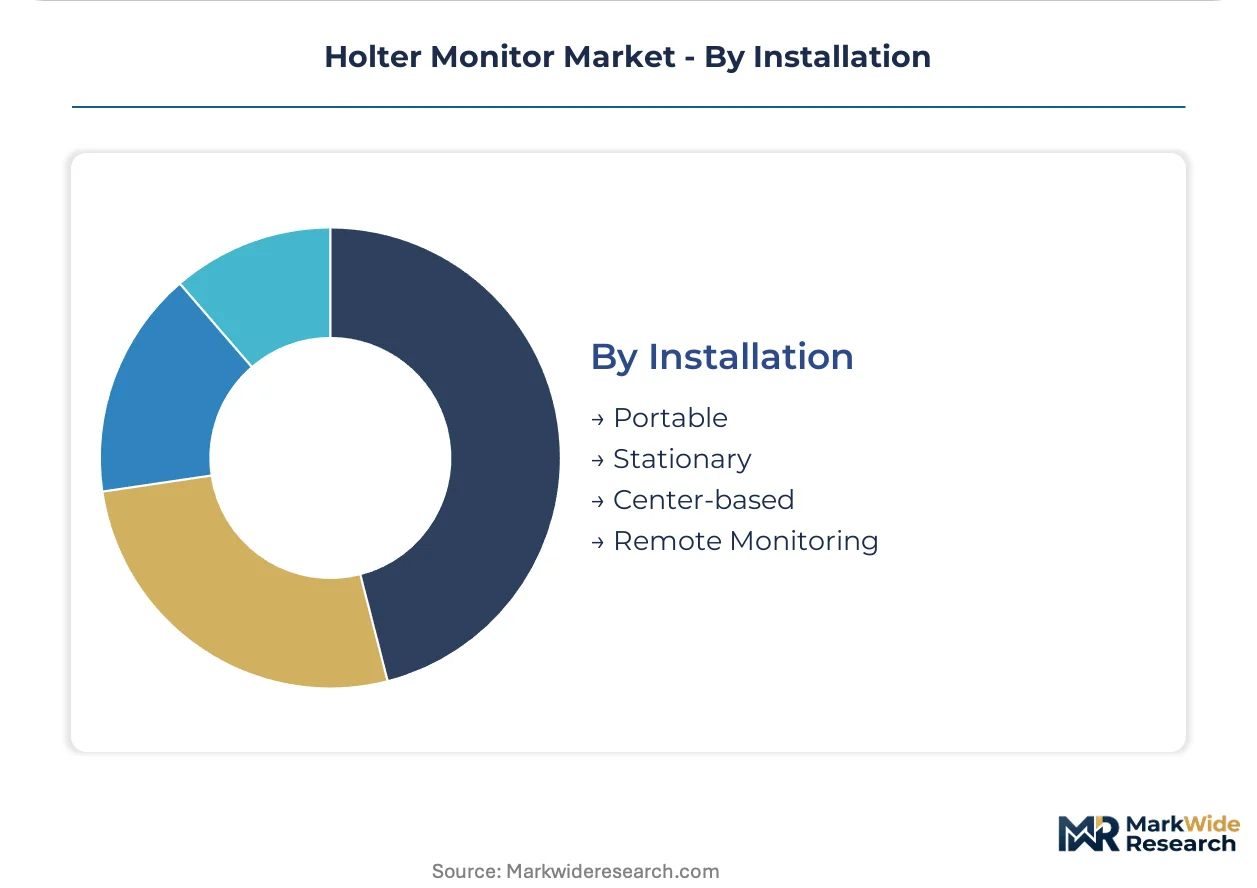
Portable systems anchor current installed base; remote monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac telemetry procurement concentrates in health systems with mature reimbursement frameworks for ambulatory monitoring. Germany, Japan, and the United States anchor installed capacity for wireless Holter systems, while emerging demand clusters form in India and Brazil around outpatient clinic expansion.
United States
Outpatient cardiology clinics drive volume through CMS remote patient monitoring reimbursement codes that cover extended arrhythmia surveillance. FDA 510(k) clearance pathways govern commercialization timelines for cloud-connected systems. The Minneapolis-St. Paul corridor hosts concentrated device manufacturing and algorithm development operations serving North American deployment.
Germany
Hospital procurement departments weight diagnostic yield per patient disruption hour under health technology assessment protocols, accelerating patch-based system adoption. EU Medical Device Regulation mandates prospective clinical studies for algorithm-upgraded devices, extending certification timelines. Baden-Württemberg's medical technology cluster anchors manufacturing for wearable electrode arrays distributed across European markets.
Japan
Ministry of Health, Labour and Welfare expanded long-term care insurance coverage for domiciliary cardiac monitoring, prompting home health agency infrastructure investment. PMDA enforces QMS conformity and localized clinical validation for imported devices, adding compliance cost layers for foreign entrants. The Kanto region around Tokyo concentrates hospital system purchasing power and distribution logistics for domestic manufacturers.
India
Private hospital chains in metropolitan centers deploy ambulatory electrocardiography programs to capture rising cardiovascular disease prevalence among urban populations. CDSCO regulates medical device imports under the Medical Devices Rules framework, with recent alignment toward harmonized international standards. Maharashtra's Mumbai-Pune corridor hosts emerging domestic manufacturing for 3-lead wired Holter systems serving price-sensitive clinic segments.
Brazil
Public health system procurement through SUS channels creates volume opportunity for portable Holter configurations in cardiology referral networks. ANVISA medical device registration requires in-country testing and Portuguese-language labeling, extending market entry timelines for foreign suppliers. São Paulo state's concentrated private hospital infrastructure drives premium-tier demand for wireless telemetry systems with cloud interpretation services.
Holter Monitor Market Competitive Landscape
Portfolio diversification dominates the current landscape as legacy device manufacturers expand algorithm capabilities and software-centric entrants build hardware partnerships. The vendor base stratifies across three tiers: diversified medical technology conglomerates with installed-base leverage, pure-play cardiac monitoring specialists with algorithmic differentiation, and regional fabricators serving price-sensitive procurement channels. Two strategic archetypes define competitive positioning: integrated device-service vendors capturing recurring interpretation revenue, and hardware-agnostic algorithm platforms licensing cloud-based arrhythmia detection. M&A activity concentrates on digital health capabilities, while strategic partnerships bridge semiconductor supply constraints for wireless system scaling.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and GE Healthcare exemplify installed-base protection strategies through multi-site manufacturing and hospital system service contracts. iRhythm Technologies, Inc. occupies a distinct position as a pure-play algorithm-driven arrhythmia detection specialist, bypassing conventional hardware-centric competition through cloud-interpretation service models. Fukuda Denshi Co., Ltd. and Nihon Kohden Corporation represent Japan-based manufacturers with domestic regulatory expertise and regional distribution density. Medtronic plc and Hill-Rom Services, Inc. (Baxter) anchor the medical device diversification archetype with cross-portfolio bundling leverage in integrated delivery networks.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE Healthcare |
| Hill-Rom Services, Inc. (Baxter) |
| SCHILLER AG |
| Fukuda Denshi Co., Ltd. |
| Nihon Kohden Corporation |
| Medtronic plc |
| BPL Medical Technologies |
| iRhythm Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Hydrogel-silver chloride electrode formulations travel from specialty chemical producers through tiered pricing structures that separate premium wearable patch systems from economy wired configurations. Raw material concentration in Asian semiconductor foundries compresses margins at the analog-to-digital conversion layer while elevating algorithmic interpretation services as the primary value capture mechanism.
Pricing Analysis
Volume concentrates in wired Holter systems with thin hardware margins, while margin concentrates in wearable patch configurations with attached cloud interpretation subscriptions. Price differentiation hinges on FDA 510(k) clearance tier and extended-wear electrode material grade. Pricing pressure stems from consumer wearable substitution flattening primary care referrals for low-acuity screening. Home care channels exhibit highest price sensitivity; hospital integrated delivery networks show lowest sensitivity under bundled managed service agreements.
Supply Chain Analysis
Direct-to-hospital procurement channels handle integrated delivery network demand, while distributor-mediated routes serve outpatient cardiology clinics and home health agencies. Component fabrication concentrates in Taiwan, South Korea, and Japan for analog-to-digital converters essential to multi-lead signal fidelity. Raw material dependencies include hydrogel-silver chloride electrode substrates, radio-frequency telemetry modules, and cloud infrastructure services. Single-source vulnerability at Asian foundry nodes constrains production scaling for wireless system manufacturers. Distribution runs through regional medical device distributors with GPO contract access in the United States and specialized cardiac monitoring distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analog-to-digital converter foundry capacity constraints in Asia anchor pricing power for component suppliers and compress hardware margins for device assemblers. This supply bottleneck sustains premium pricing for manufacturers with captive semiconductor relationships or algorithmic differentiation.
For Market Incumbents: Extend cloud interpretation service attach rates to offset hardware margin compression from wearable patch commoditization. Secure multi-year supply agreements with Taiwanese and South Korean foundries to defend against analog-to-digital converter allocation shortages. Invest in FDA 510(k) pre-submission pathways for algorithm-upgraded devices to preempt EU MDR clinical evidence delays.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium patch-based systems and economy wired Holter configurations offers entry space for smartphone-integrated mobile Holter architectures. Target India's private hospital chains in the Mumbai-Pune corridor with 3-lead wired configurations priced below imported wireless systems. Pursue CDSCO registration alignment with harmonized international standards to accelerate market entry timelines.
For Investors and Strategic Acquirers: PMDA QMS conformity enforcement for imported devices is the leading indicator that Japanese domestic manufacturers will command valuation premiums over foreign entrants lacking localized clinical validation. Frame long-term viability around algorithm-as-a-service revenue models with recurring interpretation fees rather than hardware transactional models. Target acquisition profiles emphasizing cloud-based arrhythmia detection platforms with edge AI capabilities. Monitor CMS remote patient monitoring reimbursement code expansions as the signal for outpatient clinic infrastructure investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Pathway | Accelerates algorithm-upgraded device clearance timelines ahead of EU MDR clinical evidence requirements. |
| Foundry Supply Agreement | Secures analog-to-digital converter allocation from Taiwanese and South Korean semiconductor fabricators. |
| Cloud Interpretation Platform Integration | Shifts revenue model from hardware transactional to recurring SaaS fees with higher lifetime value. |
| Home Health Agency Partnership | Captures Japan's expanded long-term care insurance reimbursement for domiciliary cardiac monitoring. |
| AI-ECG Algorithm Development | Enables edge processing on patch electrodes with deep learning models trained on million-scale arrhythmia databases. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body guidance, and CMS remote patient monitoring reimbursement code filings, complemented by interviews with biomedical engineers at outpatient cardiology clinics, hospital purchasing committee members, GPO contracts managers, and home health agency operations directors. Secondary validation drew from PMDA QMS conformity documentation, CDSCO Medical Devices Rules frameworks, and ANVISA registration requirements. Bottom-up demand modeling triangulated against top-down reimbursement code expenditure analysis.
Cross-referencing historical device shipment patterns with panel input from semiconductor foundry allocation managers and specialty chemical electrode suppliers anchored the projection framework. Segmentation dimensions modeled include product architecture (wireless, wearable, wired, mobile), end-user channel (home care, cardiology clinics, hospitals, diagnostic laboratories), lead configuration (3-lead, 12-lead), and installation type (remote monitoring, portable, stationary, center-based). CAGRs were derived from weighted average of demand elasticity coefficients and reimbursement expansion trajectories. Forecast inputs incorporated EU MDR certification timeline delays and CMS code valuation updates.
Inputs from PMDA conformity assessment bodies and EU notified bodies were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around wireless system production scaling assumptions. Forecasts reflect documented assumptions regarding reimbursement code stability and semiconductor supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market