
 AI in Remote Patient Monitoring Market | 2026-2036
AI in Remote Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Remote Patient Monitoring Market Insights
The gap between premium AI-native RPM platforms and commodity-connected devices is hardening. Medtronic leverages its deep vertical integration across sensors and algorithms to command premium positioning. Koninklijke Philips N.V. sustains broad channel control through its hospital-at-home and sleep therapy ecosystems. Abbott competes on glucose-specific AI specialization, anchoring its Libre ecosystem in real-time metabolic data streams.
AI in remote patient monitoring encompasses software and hardware systems that apply machine learning inference to physiologic data collected outside clinical settings, typically processing heart rate variability, blood glucose trends, or respiratory patterns through cloud-based pipelines with latencies under thirty seconds for critical alerts. The primary commercial purpose is to reduce acute events and hospital readmissions by enabling preemptive clinical intervention. Wearable devices dominate hardware shipment volumes, though clinical software captures disproportionate margin pools through recurring SaaS licensing. Chronic disease management leads application penetration due to sustained reimbursement visibility, while preventive healthcare represents the fastest-expanding addressable base as payors shift toward risk-based contracts.
FDA Software as a Medical Device frameworks and HIPAA security requirements shape product architecture and go-to-market timelines for US-focused vendors, while the EU AI Act and MDR impose additional conformity burdens for European market access. ISO 13485 quality management standards and IEC 62304 software lifecycle protocols serve as baseline gating criteria for OEM partnerships and hospital procurement. Stakeholders must monitor how CMS reimbursement code refinements for remote therapeutic monitoring reshape the economic viability of AI-augmented versus basic connected-care offerings.
Market Dynamics
The Medicare reimbursement structure for remote physiologic monitoring is compressing vendor margins while simultaneously expanding addressable patient populations, forcing platform economics toward SaaS recurring models over hardware sales.
Growth Catalysts
- CMS Remote Therapeutic Monitoring codes:The expanded reimbursement framework now covers musculoskeletal and respiratory conditions beyond traditional chronic disease categories, broadening clinical utility for AI-augmented platforms.
- Hospital-at-home programs:Health systems including Mayo Clinic and Kaiser Permanente are deploying AI-enabled RPM as core infrastructure for acute-level home care, replacing inpatient bed-days.
- Edge computing architectures:On-device inference is reducing alert latency from cloud-dependent pipelines, enabling real-time cardiac arrhythmia detection without continuous connectivity.
Market Restraints
- FDA 510(k) pathway congestion:The Software as a Medical Device framework imposes 12-18 month clearance timelines for algorithm updates, freezing product iteration cycles.
- Sensor supply concentration:Photoplethysmography and accelerometer modules concentrate among Taiwanese and South Korean contract manufacturers, creating single-source vulnerability.
- Clinical workflow integration friction:Electronic health record interoperability gaps force manual data reconciliation, consuming nursing time and depressing utilization rates.
Strategic Opportunities
- Preventive health risk contracts:Employer-sponsored plans and Medicare Advantage carriers are piloting AI-RPM for prediabetes and early cardiovascular risk, opening pre-disease revenue pools.
- EU AI Act conformity:Early compliance with high-risk system requirements creates competitive moat for vendors seeking European hospital procurement contracts.
- Retail pharmacy distribution:CVS Health and Walgreens are building RPM fulfillment networks, bypassing traditional durable medical equipment channels.
Industry Challenges
- Clinical validation workforce scarcity:Biostatisticians with FDA submission experience command premium compensation, constraining mid-cap vendor pipeline capacity.
- Algorithm drift monitoring:Continuous performance validation across demographic subgroups requires dedicated ML-ops infrastructure absent from legacy device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Remote Patient Monitoring Market |
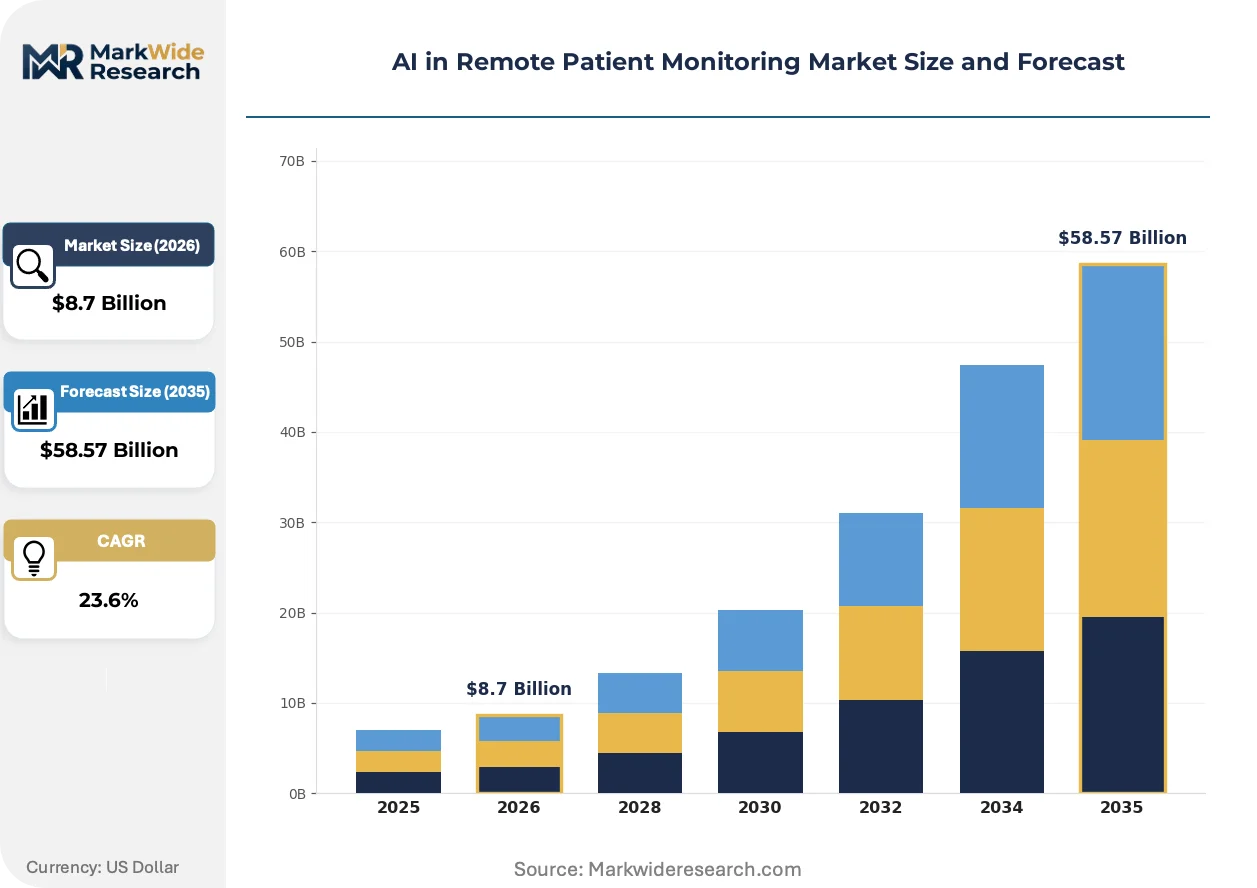
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
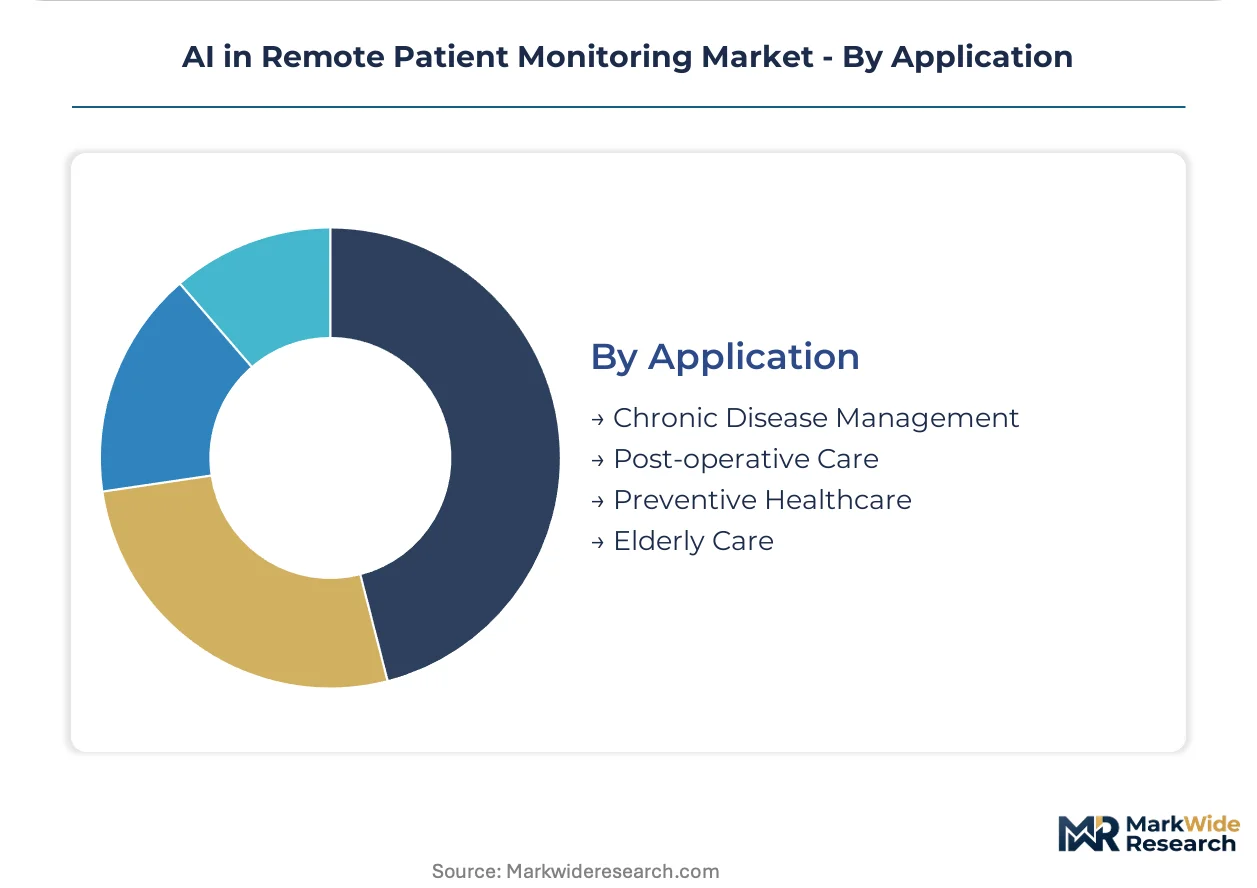
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Home Monitoring Systems, Clinical Software End User: Patients, Healthcare Providers, Caregivers, Telehealth Services Technology: Machine Learning, Data Analytics, Cloud Computing, IoT Application: Chronic Disease Management, Post-operative Care, Preventive Healthcare, Elderly Care |
| Companies Covered | Medtronic, Koninklijke Philips N.V., GE HealthCare, ResMed, Dexcom, Abbott, Roche, Siemens Healthineers, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Remote Patient Monitoring Market Trends and Innovations
Algorithmic personalization is displacing population-based risk scoring, while regulatory frameworks on both sides of the Atlantic are hardening compliance requirements for continuous learning systems.
Federated learning architectures are integrating distributed model training across hospital networks without centralizing protected health information. Academic medical centers including Johns Hopkins and Stanford Health are piloting these frameworks for multi-site cardiac prediction models. The approach is integrating privacy-preserving computation into standard procurement specifications for health system AI contracts.
The EU AI Act's high-risk system classification is mandating conformity assessments for diagnostic algorithms before European market entry. Device manufacturers must now maintain quality management systems exceeding ISO 13485 baseline requirements. Sleep apnea and arrhythmia detection modules face the strictest scrutiny, with notified body review timelines extending 8-14 months.
Hospital purchasing committees are consolidating vendor relationships around platforms with native electronic health record integration. Epic Systems and Cerner environments now dominate selection criteria, displacing standalone RPM portals. This concentration is most visible in United States health systems where IT security review boards block non-integrated solutions regardless of clinical performance metrics.
AI in Remote Patient Monitoring Market Segmentation
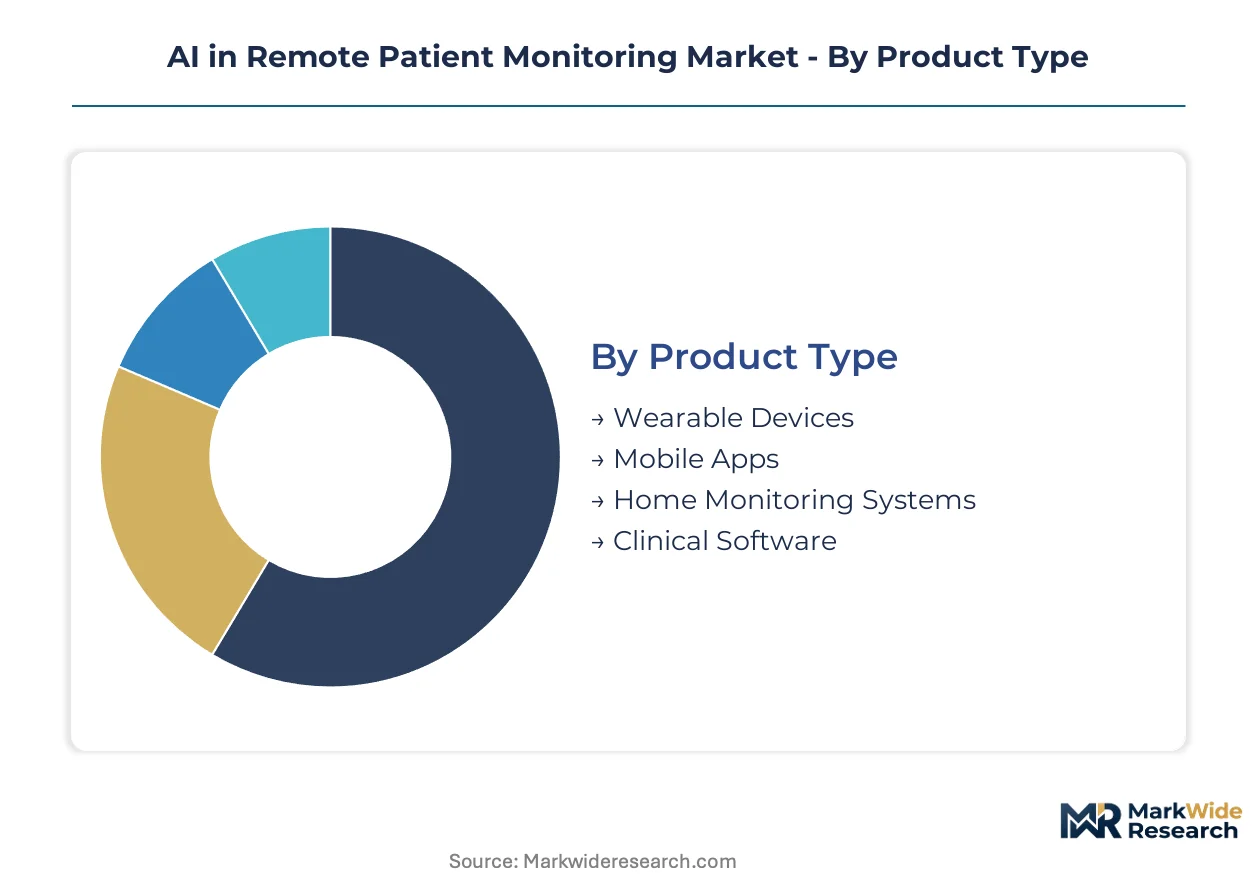
Segmentation in AI-enabled remote patient monitoring reveals how hardware margins concentrate in clinical software while deployment models diverge across care settings. Understanding these axes clarifies where platform economics outperform device sales and which technology stacks command procurement priority.
Product Type:
Sensor-to-algorithm integration depth defines cost structures and renewal economics across hardware-software boundaries.
- Wearable Devices:Photoplethysmography and accelerometer-based form factors dominate shipment volumes. Demand concentrates in Medicare Advantage populations where CMS remote physiologic monitoring reimbursement codes offset patient out-of-pocket costs.
- Clinical Software:Cloud-based inference pipelines processing heart rate variability and respiratory patterns capture disproportionate margin pools through recurring SaaS licensing. Health systems in the United States prioritize native Epic and Cerner integration during procurement reviews.
- Mobile Apps:Patient-facing interfaces for data visualization and alert receipt. FDA 510(k) pathway requirements for algorithm updates compress vendor iteration cycles.
- Home Monitoring Systems:Hub-and-spoke architectures connecting multiple peripherals. Deployment concentrates in hospital-at-home programs replacing inpatient bed-days.
Mature deployment sits with Clinical Software. Newer deployment is concentrated in Home Monitoring Systems.
End User:
Workflow integration requirements vary sharply across direct care delivery versus intermediary coordination roles.
- Healthcare Providers:Physicians and nursing staff requiring EHR-embedded dashboards for preemptive intervention. Mayo Clinic and Kaiser Permanente anchor demand through acute-level home care infrastructure.
- Telehealth Services:Remote clinical teams managing distributed patient panels. Medicare reimbursement code refinements for remote therapeutic monitoring reshape economic viability.
- Patients:Self-managing chronic conditions through consumer-facing interfaces. Algorithmic personalization is displacing population-based risk scoring in prediabetes and early cardiovascular applications.
- Caregivers:Family members and home health aides receiving delegated alert notifications. HIPAA security requirements constrain multi-user permission architectures.
Revenue concentration rests with Healthcare Providers. Steepest expansion trajectory belongs to Telehealth Services.
Technology:
Inference location—edge versus cloud—determines latency profiles and regulatory conformity burdens.
- Machine Learning:On-device arrhythmia detection and glucose trend prediction reducing alert latency below thirty seconds. Federated learning pilots at Johns Hopkins and Stanford Health integrate privacy-preserving computation into procurement specifications.
- Cloud Computing:Centralized model training and longitudinal data warehousing. EU AI Act high-risk system classification mandates conformity assessments extending notified body review timelines.
- Data Analytics:Population-level risk stratification and readmission prediction. Biostatistician scarcity with FDA submission experience constrains mid-cap vendor pipeline capacity.
- IoT:Sensor connectivity protocols and device fleet management. Photoplethysmography module concentration among Taiwanese contract manufacturers creates single-source vulnerability.
Established capability sits with Cloud Computing. Fastest capability buildout is occurring in Machine Learning.
Application:
Reimbursement visibility and risk-contract alignment determine addressable market sequencing.
- Chronic Disease Management:Diabetes, heart failure, and COPD monitoring with sustained Medicare reimbursement visibility. Abbott's Libre ecosystem anchors real-time metabolic data streams.
- Preventive Healthcare:Prediabetes and early cardiovascular risk for employer-sponsored plans. Risk-based contracts with Medicare Advantage carriers open pre-disease revenue pools.
- Post-operative Care:Surgical recovery monitoring reducing emergency department returns. Hospital purchasing committees consolidate vendor relationships around EHR-native platforms.
- Elderly Care:Fall detection and medication adherence for aging-in-place populations. Retail pharmacy distribution through CVS Health and Walgreens bypasses traditional durable medical equipment channels.
Sustained reimbursement sits with Chronic Disease Management. Gaining share fastest is Preventive Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American health technology commercialization, with Massachusetts General Brigham and Partners HealthCare driving hospital-at-home pilot programs that integrate AI-enabled remote monitoring into acute care workflows.
United States
Medicare Advantage carriers and employer-sponsored plans sustain demand for AI-RPM platforms through risk-based contracting models. FDA Software as a Medical Device frameworks impose 12-18 month clearance timelines for algorithm updates. The Mayo Clinic in Rochester anchors hospital-at-home infrastructure deployment, replacing inpatient bed-days with AI-augmented home monitoring.
Germany
Statutory health insurance funds are piloting remote therapeutic monitoring for chronic heart failure and COPD populations. The EU AI Act's high-risk system classification mandates conformity assessments extending notified body review timelines to 8-14 months. The MedTech cluster in Baden-Württemberg concentrates sleep apnea and respiratory monitoring device manufacturing.
United Kingdom
NHS England's virtual ward programs are scaling AI-enabled RPM for post-operative surgical recovery and elderly fall prevention. MHRA guidance on Software as a Medical Device aligns with evolving FDA frameworks but imposes additional post-market surveillance requirements. The Golden Triangle corridor between London, Oxford, and Cambridge concentrates federated learning research partnerships.
Japan
PMDA accelerated approval pathways for AI/ML-based medical devices are compressing time-to-market for arrhythmia detection algorithms. METI subsidies for aging-in-place technology sustain demand for home monitoring systems in rural prefectures. The Kansai region around Osaka anchors photoplethysmography sensor module assembly for wearable device OEMs.
India
CDSCO medical device rules are harmonizing with ISO 13485 quality management standards for AI-based diagnostic software. The National Digital Health Mission is creating unified health identifier infrastructure enabling interoperable remote monitoring data exchange. Karnataka's Bengaluru corridor concentrates health technology startups developing glucose prediction algorithms for the diabetes management segment.
AI in Remote Patient Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithm-sensor integration depth. Medtronic and Koninklijke Philips N.V. command pricing power through captive hardware-software ecosystems, while smaller vendors compete on narrow application specialization. Three archetypes dominate: vertically integrated device-algorithm platforms, clinical software pure-plays with EHR-native positioning, and sensor-agnostic algorithm licensors. Consolidation is accelerating through strategic partnerships with health systems and technology licensing agreements that bypass lengthy FDA clearance pathways.
Within the integrated platform tier, Medtronic exemplifies deep backward integration across cardiac and metabolic monitoring, while Koninklijke Philips N.V. occupies a position spanning sleep therapy and hospital-at-home infrastructure. Abbott anchors glucose-specific AI specialization through its Libre ecosystem, representing the narrow-application archetype with disproportionate margin capture in real-time metabolic data streams.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| GE HealthCare |
| ResMed |
| Dexcom |
| Abbott |
| Roche |
| Siemens Healthineers |
| Boston Scientific Corporation |
| Others |
Pricing and Supply Chain Analysis
EU AI Act high-risk system classification gates qualified supply for AI-enabled remote patient monitoring platforms, restricting premium-tier pricing access to vendors with notified body conformity assessments exceeding ISO 13485 baseline requirements. This environmental mandate compresses procurement eligibility while elevating pricing power for compliant device-algorithm integrators serving European hospital networks.
Pricing Analysis
Value-based pricing anchored to reduced hospital readmission rates dominates AI-RPM commercial models, with SaaS recurring licenses capturing margin pools disproportionate to hardware shipment volumes. Pricing stratifies across FDA-cleared algorithm tiers, native EHR integration depth, and edge-computing latency performance, with Medicare reimbursement code compression forcing cost absorption in commodity-connected device segments. Hospital purchasing committees demonstrate lowest price sensitivity for platforms with Epic and Cerner native embedding, while telehealth intermediaries face acute margin pressure from manual EHR reconciliation workflows.
Supply Chain Analysis
Domestic-content mandates in India's National Digital Health Mission and Japan's METI aging-in-place subsidies are reshaping sensor sourcing toward localized assembly corridors. Photoplethysmography modules concentrate among Taiwanese and South Korean contract manufacturers, with accelerometer chipsets drawing from Japanese and German semiconductor fabs. Single-source vulnerability in PPG sensor supply creates tariff exposure risk, while distribution runs through retail pharmacy fulfillment networks at CVS Health and Walgreens bypassing traditional durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
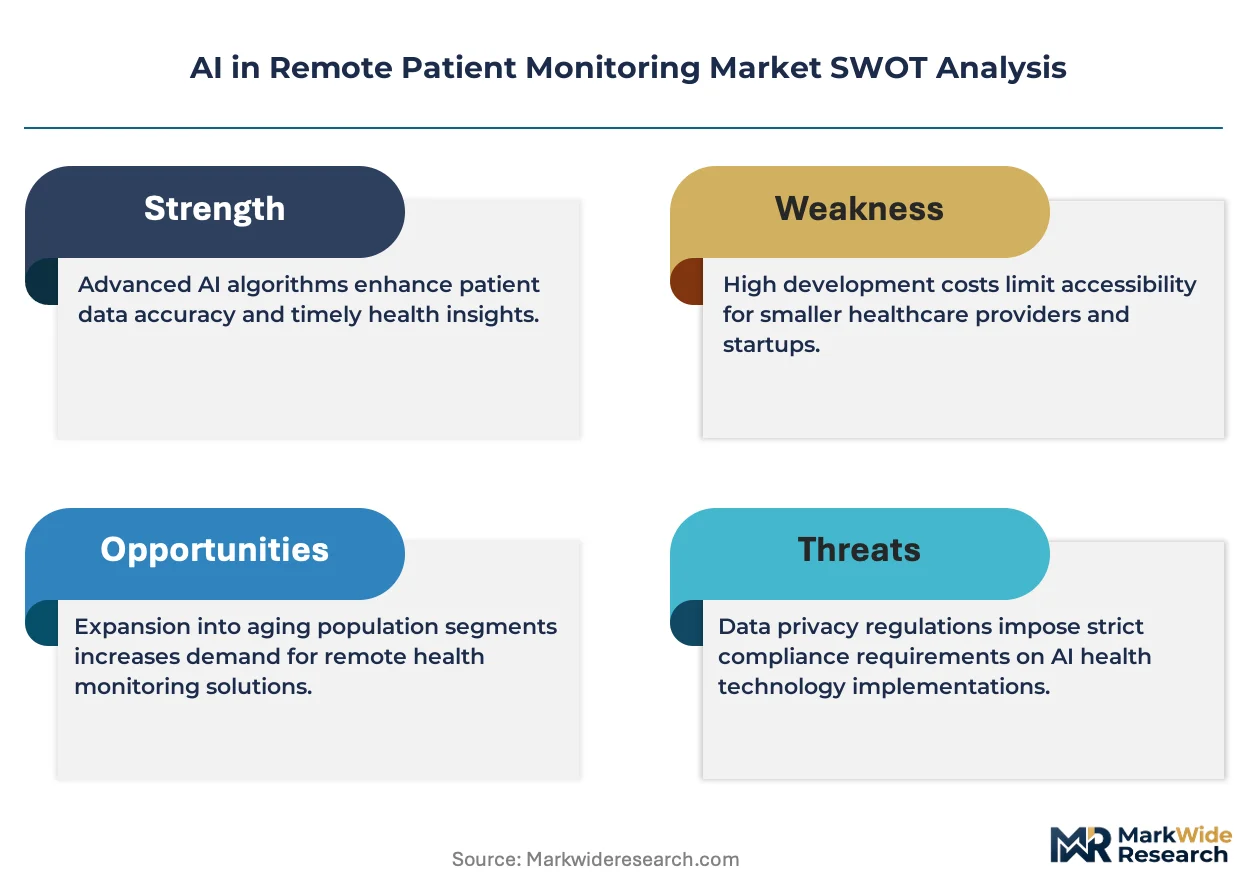
The AI in remote patient monitoring market operates as a cost-of-compliance story where FDA Software as a Medical Device frameworks and EU AI Act high-risk classifications erect barrier-to-entry moats favoring vendors with dedicated regulatory affairs infrastructure and sustained quality management investment.
For Market Incumbents: To counter algorithm drift monitoring requirements and continuous learning system validation burdens, deepen backward integration into photoplethysmography sensor manufacturing to secure supply continuity, and accelerate federated learning infrastructure deployment across Mayo Clinic and Kaiser Permanente hospital-at-home networks to cement EHR-native positioning. For New Entrants and Emerging Players: Begin with preventive healthcare applications for prediabetes and early cardiovascular risk in Medicare Advantage risk-based contracts, where reimbursement code visibility remains nascent and incumbent platform consolidation has not yet closed access, leveraging retail pharmacy distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: CMS remote therapeutic monitoring code refinements covering musculoskeletal and respiratory conditions is the leading indicator that platform economics will shift decisively toward SaaS recurring models over hardware sales, positioning clinical software pure-plays with native Epic integration as the optimal acquisition archetype for long-term viability across the coming decade.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Algorithm update clearance timelines freeze product iteration cycles for twelve to eighteen months. |
| CE Marking Pathway | EU AI Act conformity assessments extend notified body review to eight through fourteen months. |
| Hospital System Partnership | Mayo Clinic and Kaiser Permanente anchor acute-level home care infrastructure deployment. |
| Software Companion Development | Native Epic and Cerner integration dominates health system procurement committee selection criteria. |
| Reimbursement Strategy | CMS remote therapeutic monitoring codes reshape economic viability for AI-augmented versus basic offerings. |
Research Methodology
Independent corroboration across FDA 510(k) clearance databases, CMS reimbursement code filings, and EU notified body conformity assessment records underwrites the qualitative findings, combining primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and telehealth operations directors with secondary validation from SEC device manufacturer filings, ClinicalTrials.gov algorithm validation studies, and hospital procurement database extracts through bottom-up and top-down triangulation.
Comparable-period anchoring to historical remote physiologic monitoring adoption curves and chronic disease management software penetration patterns calibrated the projection horizon, modeling across product type, end user, technology stack, and application dimensions with specific weighting for edge-computing inference latency profiles and federated learning deployment status, deriving CAGRs through convergence of demand-side reimbursement trajectory analysis and supply-side sensor manufacturing capacity assessment.
Underlying measurement precision varies by segment; clinical software and wearable devices carry tighter precision than mobile apps and home monitoring systems due to more mature procurement data availability. Forecasts reflect assumptions about Medicare Advantage risk-contract expansion and EU AI Act enforcement consistency, with algorithm performance validation across demographic subgroups and photoplethysmography supply concentration representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market