
 Japan Commercial Construction Market | 2026-2036
Japan Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Commercial Construction Market Insights
Project finance through public-private partnership concessions is reshaping competitive access for mid-tier contractors in Japan's commercial construction sector. Kajima Corporation leverages its integrated engineering-procurement-construction model to dominate complex urban redevelopment mandates. Obayashi Corporation sustains leadership in seismic-resistant structural systems through captive R&D investment. Takenaka Corporation anchors its position via specialized expertise in constrained-site logistics across central Tokyo and Osaka.
Japan commercial construction encompasses the erection of non-residential structures including offices, retail facilities, logistics warehouses, and mixed-use complexes, typically employing steel moment frames or reinforced concrete shear-wall systems designed to withstand seismic loads exceeding 0.3g peak ground acceleration. Office buildings and mixed-use developments command the deepest margin pools as institutional investors prioritize income-generating assets in prime submarkets. Warehouses represent the fastest-expanding project type, driven by e-commerce fulfillment networks and pharmaceutical cold-chain requirements. Sustainable building and smart technologies are concentrating procurement decisions as JIS standards and green certification thresholds harden.
METI enforces building energy codes through the Top Runner Program, while the Ministry of Land, Infrastructure, Transport and Tourism (MLIT) administers structural performance standards under the Building Standard Law. PMDA-adjacent facility guidelines indirectly shape laboratory and pharmaceutical construction specifications through GMP-aligned cleanroom requirements. Stakeholders must monitor how impending revisions to Japan's GX League carbon-accounting rules will re-tier material procurement eligibility and contractor qualification criteria.
Market Dynamics
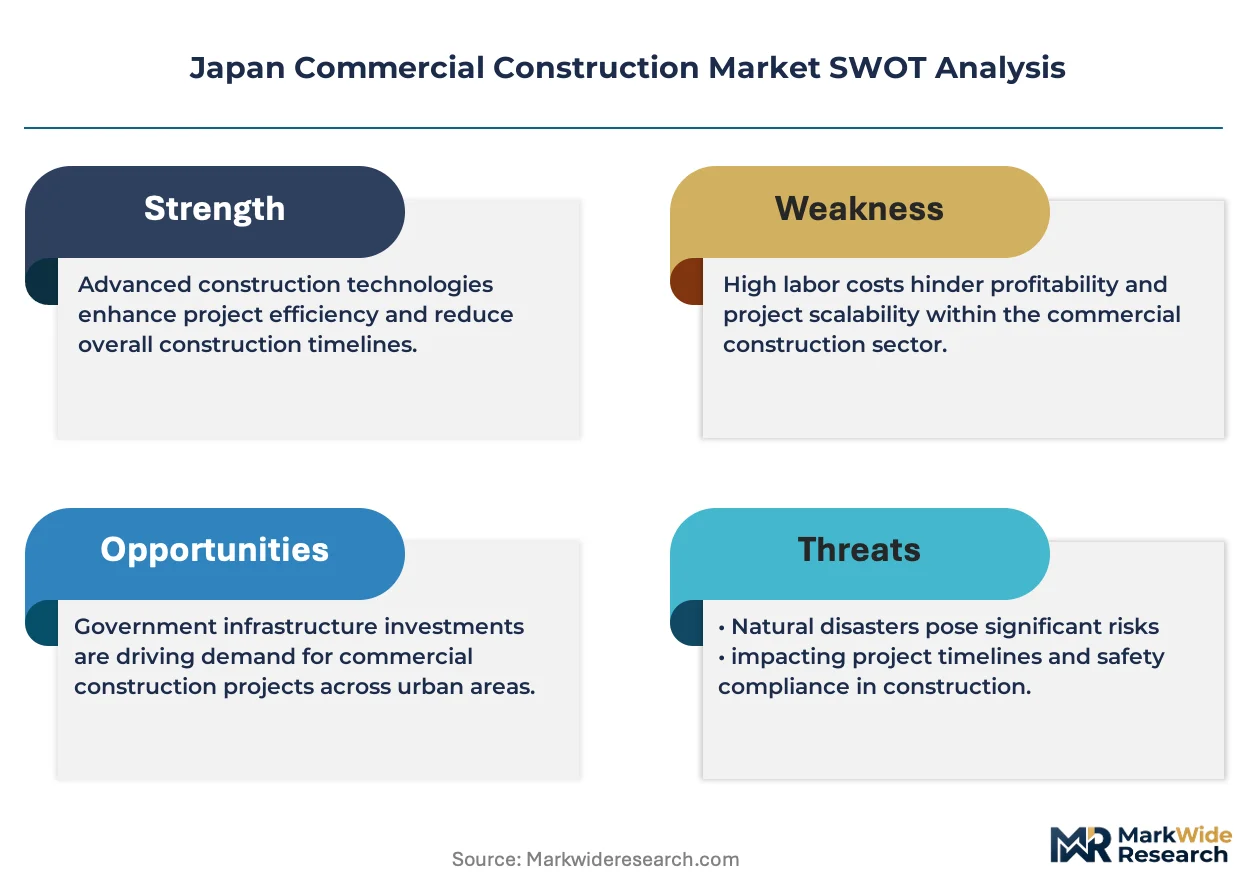
METI's net-zero building mandates are compressing material procurement cycles as developers race to substitute mass timber and low-carbon concrete before GX League carbon-accounting rules harden eligibility criteria.
Growth Catalysts
- E-commerce fulfillment networks:Pharmaceutical cold-chain requirements and last-mile logistics are accelerating warehouse construction across Greater Tokyo and Osaka.
- Public-private partnership concessions:Government-backed infrastructure projects are channeling private capital into urban redevelopment with schedule certainty guarantees.
- Mass timber substitution:Cross-laminated timber and glulam systems are displacing steel moment frames in mid-rise commercial structures under revised JIS standards.
Market Restraints
- Specialized contractor scarcity:Seismic engineering expertise concentrates among a handful of integrated firms, limiting competitive entry for mid-tier players.
- Low-carbon concrete cost premium:Supplementary cementitious materials and carbon capture additives inflate material budgets by double-digit percentages versus conventional mixes.
- Constrained-site logistics:Central Tokyo and Osaka parcel sizes restrict prefabrication module dimensions, compressing efficiency gains from modular methods.
Strategic Opportunities
- GX League early compliance:First-mover contractors securing carbon-accounting certification will lock in preferred supplier status for institutional investor mandates.
- Smart building integration:Convergence of IoT sensors and building energy management systems is opening premium pricing for technology-enabled assets.
- Regional city revitalization:Fukuoka and Sapporo commercial zones remain underpenetrated relative to capital region saturation, offering land cost arbitrage.
Industry Challenges
- Seismic retrofit coordination:Integrating base isolation and damping systems into existing structures demands specialized subcontractor networks with limited capacity.
- Cleanroom certification timelines:PMDA-adjacent GMP facility approvals extend project delivery schedules, compressing developer return timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Commercial Construction Market |
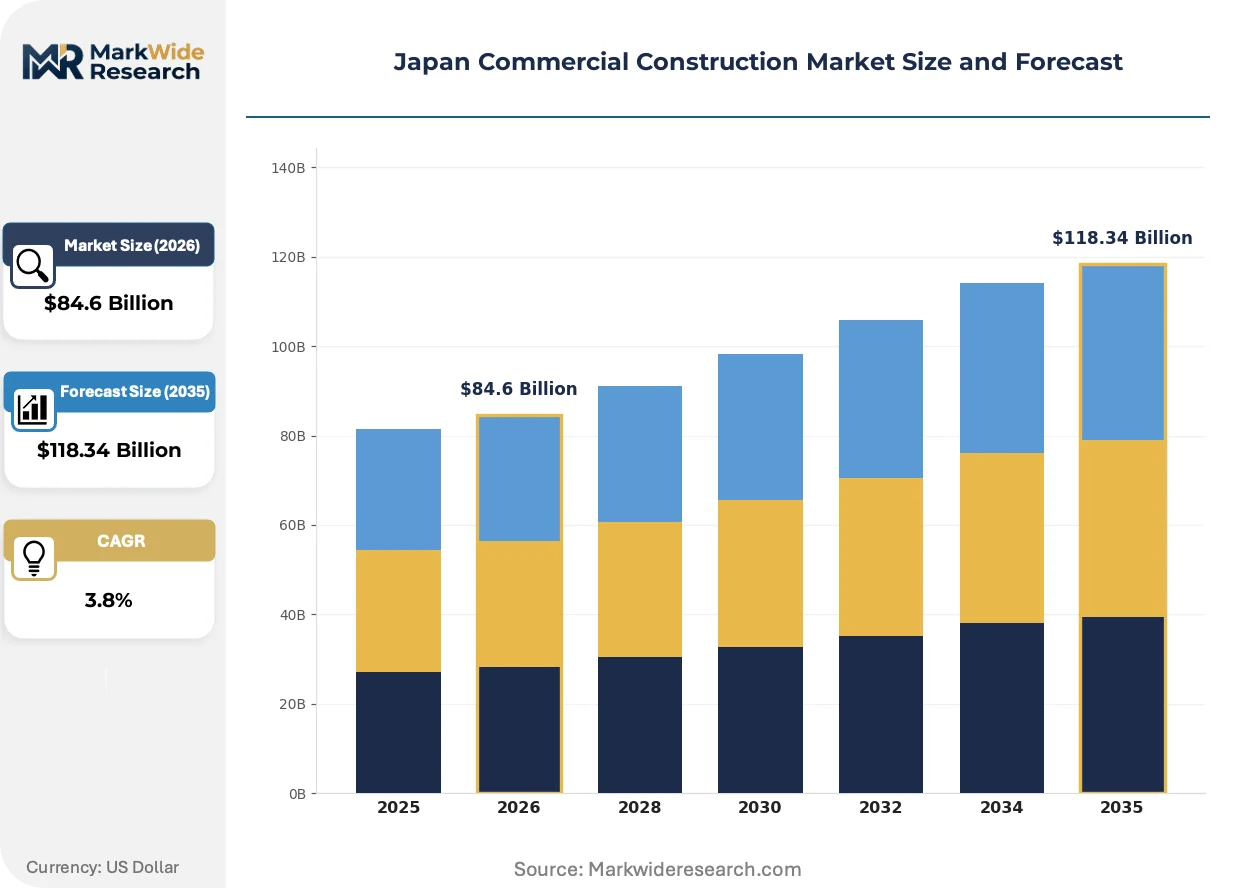
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $118.34 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Office Buildings, Retail Spaces, Warehouses, Mixed-Use Developments Material Type: Steel, Concrete, Glass, Wood Construction Technology: Modular Construction, Prefabrication, Sustainable Building, Smart Technologies End User: Private Developers, Government Agencies, Corporations, Educational Institutions |
| Companies Covered | Kajima Corporation, Obayashi Corporation, Shimizu Corporation, Taisei Corporation, Takenaka Corporation, Infroneer Holdings, Mitsubishi Heavy Industries Ltd., Daiwa House Industry Co., Ltd., Sekisui House, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Commercial Construction Market Trends and Innovations
Digital fabrication and carbon-accounting transparency are compressing traditional procurement hierarchies. Developers now prioritize suppliers with verified lifecycle data and modular delivery capabilities.
Building information modeling is digitizing coordination between architects, engineers, and fabricators. General contractors in mixed-use developments are mandating BIM Level 2 compliance for all trade partners. Clash detection algorithms are compressing rework rates and accelerating steel erection schedules.
METI's Top Runner Program is tightening operational energy intensity thresholds for new commercial structures. Building owners must now disclose performance data or face occupancy restrictions. Office assets in Minato and Chiyoda wards are retrofitting HVAC systems to maintain leasing competitiveness.
Institutional investors are unbundling construction contracts from long-term asset management agreements. Pension funds and REITs now separate developer selection from property manager appointment, compressing contractor margin pools. This pattern concentrates in Tokyo prime submarkets where yield compression demands fee scrutiny.
Japan Commercial Construction Market Segmentation
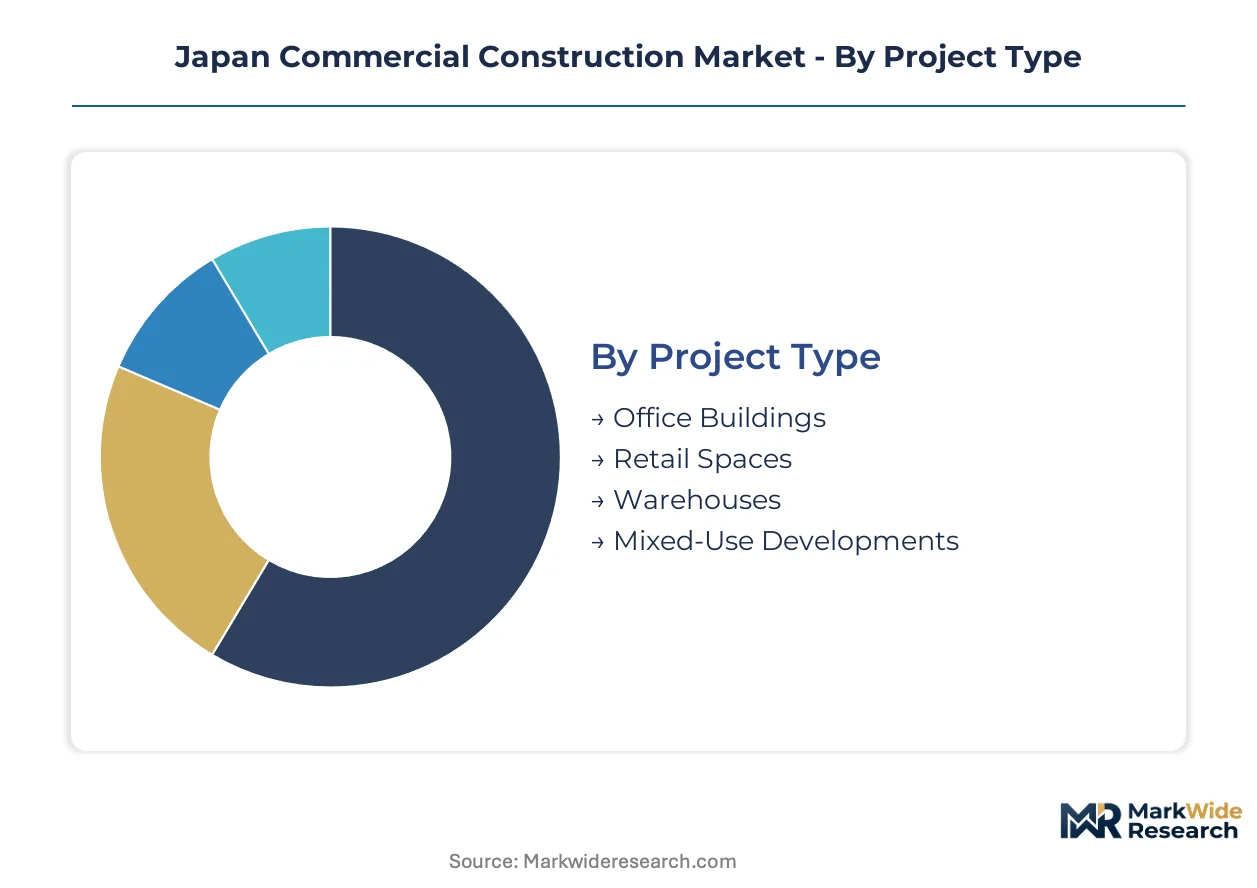
Japan's commercial construction market fragments across project type, material selection, construction methodology, and client category. Each dimension carries distinct regulatory triggers and procurement patterns that reshape contractor positioning.
Project Type:
Mature income-generating assets dominate institutional capital allocation while emerging logistics formats capture developer attention.
- Office Buildings:Steel moment frames and reinforced concrete shear-wall systems accommodate seismic loads exceeding 0.3g peak ground acceleration. Prime submarkets in Minato and Chiyoda wards attract pension fund and REIT capital seeking yield stability.
- Mixed-Use Developments:Integrated retail, office, and residential components optimize land efficiency on constrained Tokyo and Osaka parcels. Heightened private developer interest concentrates in transit-adjacent zones where MLIT zoning permits density bonuses.
- Warehouses:Cold-chain specifications for pharmaceutical distribution and e-commerce fulfillment networks drive specifications across Greater Tokyo and Osaka corridors.
- Retail Spaces:Experiential formats and flagship concepts anchor urban redevelopment mandates, though foot traffic recovery post-pandemic varies by submarket.
Office buildings retain volume leadership; warehouses hold the steepest expansion curve.
Material Type:
Cost tier differentiation separates legacy systems from emerging low-carbon substitutes reshaping procurement eligibility.
- Concrete:Conventional Portland cement mixes face displacement as supplementary cementitious materials and carbon capture additives inflate budgets by double-digit percentages. Low-carbon variants are gaining share ahead of GX League carbon-accounting rule revisions.
- Steel:Moment frame systems remain the default for high-rise commercial structures, though domestic mill capacity constraints and import dependency create price volatility.
- Wood:Cross-laminated timber and glulam systems are displacing steel in mid-rise structures under revised JIS standards, with METI net-zero mandates accelerating substitution timelines.
- Glass:High-performance glazing supports Top Runner Program energy intensity thresholds, particularly in façade retrofits of existing Minato and Chiyoda assets.
Concrete maintains installed base dominance; wood is climbing the fastest on regulatory tailwinds.
Construction Technology:
Application focus separates schedule-certain methodologies from asset-lifecycle optimization systems.
- Prefabrication:Factory-controlled component production reduces on-site labor exposure and compresses delivery schedules for government-backed infrastructure projects. Central Tokyo parcel sizes restrict module dimensions, compressing efficiency gains.
- Smart Technologies:IoT sensor convergence with building energy management systems opens premium pricing for technology-enabled assets. Institutional investors now mandate digital infrastructure as a lease condition.
- Modular Construction:Volumetric units suit repetitive program elements such as hotel and student housing components within larger mixed-use schemes.
- Sustainable Building:Green certification thresholds harden procurement decisions as JIS standards and METI energy codes tighten operational disclosure requirements.
Prefabrication commands the widest deployment; smart technologies are gaining share fastest on investor mandate convergence.
End User:
Customer type determines risk allocation, contract structure, and margin pool depth across the project pipeline.
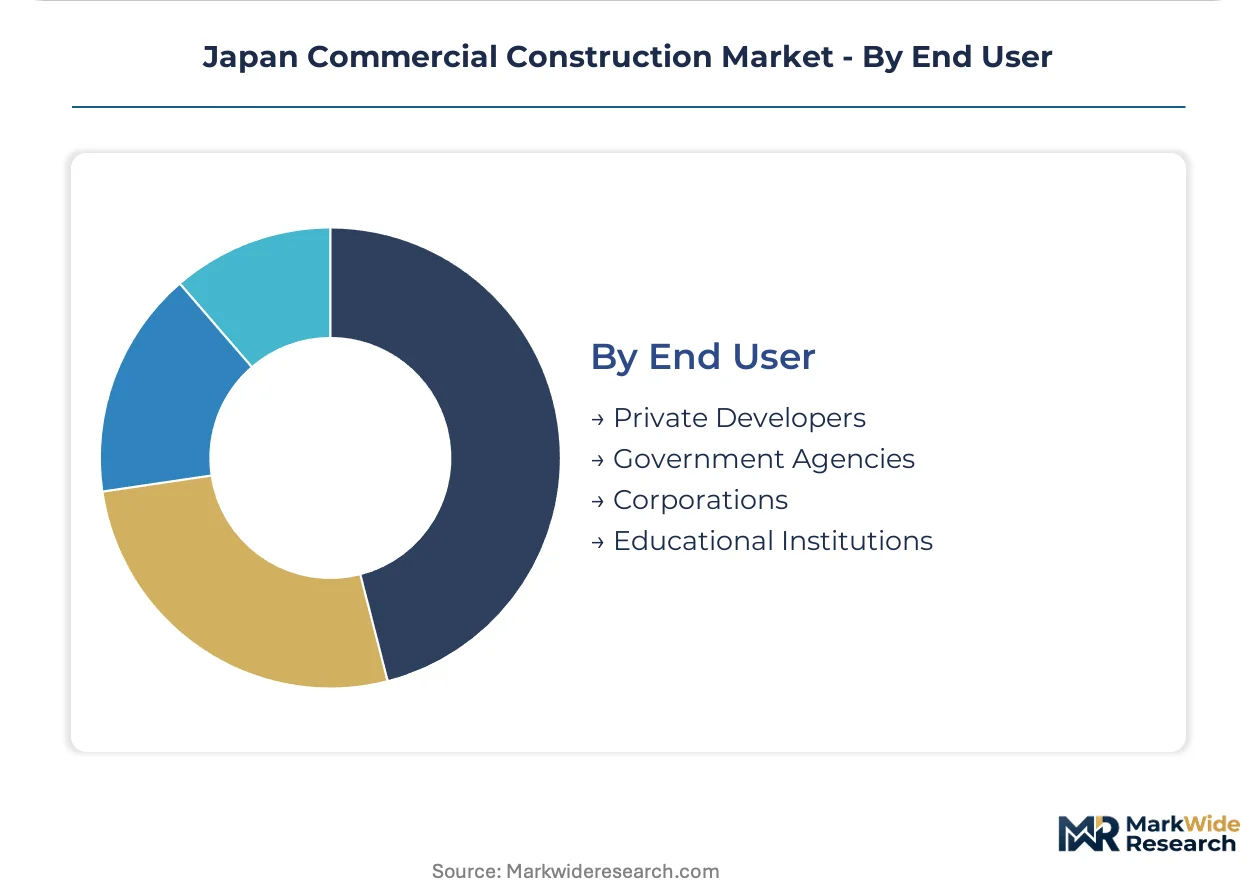
- Private Developers:Speculative and build-to-suit development concentrates in prime Tokyo and Osaka submarkets where land scarcity elevates site acquisition expertise. Margin pools compress as institutional investors unbundle construction contracts from asset management agreements.
- Government Agencies:Public-private partnership concessions channel private capital into urban redevelopment with schedule certainty guarantees, reshaping competitive access for mid-tier contractors.
- Corporations:Build-to-own facilities for headquarters and R&D operations emphasize seismic resilience and brand expression through architectural signature.
- Educational Institutions:Campus expansion and modernization projects in regional cities such as Fukuoka and Sapporo offer land cost arbitrage relative to capital region saturation.
Private developers retain transaction volume leadership; government agencies hold the steepest expansion curve on concession pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's commercial construction sector operates as a net importer of structural steel and specialty engineering services, while exporting seismic-resistant design expertise and prefabrication technology across Asia-Pacific markets. Trade flows concentrate through Kanto and Kansai industrial corridors where material processing and assembly capabilities cluster.
Kanto/Tokyo
Mixed-use redevelopment in Minato and Chiyoda wards drives premium office and retail construction, with institutional investors prioritizing transit-adjacent density bonuses. METI's Top Runner Program enforces operational energy disclosure thresholds that accelerate HVAC retrofit cycles. The Tokyo Bay waterfront corridor hosts concentrated logistics warehouse development serving e-commerce fulfillment networks.
Kansai/Osaka
Osaka's central business district regeneration attracts private developer capital seeking yield stability in Japan's second metropolitan economy. MLIT zoning permits unlock higher floor-area ratios for integrated commercial-residential schemes. The Osaka-Kobe industrial belt sustains specialized steel fabrication capacity for seismic-resistant moment frame systems.
Chubu/Nagoya
Automotive supply chain adjacent commercial facilities dominate regional construction pipelines, with Toyota Motor Corporation's headquarters city anchoring corporate build-to-own demand. Prefabrication module production clusters in Aichi Prefecture factories serving government infrastructure concessions. Nagoya Station vicinity redevelopment concentrates mixed-use mandates from railway-linked developers.
Kyushu
Fukuoka's underpenetrated commercial zones offer land cost arbitrage relative to capital region saturation, attracting logistics and data center investment. Regional city revitalization subsidies from MLIT channel infrastructure spending into urban core densification. Semiconductor adjacent cleanroom construction concentrates in Kumamoto and Kagoshima prefectures.
Hokkaido
Sapporo's commercial construction remains volume-limited but gains attention from cold-chain logistics operators exploiting geographic proximity to Russian Far East trade routes. Heavy snowfall engineering specifications differentiate structural design requirements from Honshu standards. Tourism-related retail and hospitality construction fluctuates with international visitor recovery patterns.
Japan Commercial Construction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying prefabricated modules and seismic engineering subsystems. The vendor base concentrates among five integrated general contractors controlling complex urban redevelopment mandates, with mid-tier players restricted to subcontractor roles by specialized seismic expertise requirements. Three archetypes dominate: integrated engineering-procurement-construction platforms, captive R&D seismic specialists, and regional logistics-focused fabricators. Competitive dynamics center on public-private partnership concession qualification and early GX League carbon-accounting certification securing preferred supplier status.
Among integrated platform operators, Kajima Corporation and Obayashi Corporation exemplify the engineering-procurement-construction archetype dominating Tokyo-Osaka prime submarkets. Takenaka Corporation occupies a specialized position in constrained-site logistics coordination across central business districts. These three contractors anchor competitive positioning through distinct capability configurations rather than undifferentiated scale advantages.
| Leading Market Players |
|---|
| Kajima Corporation |
| Obayashi Corporation |
| Shimizu Corporation |
| Taisei Corporation |
| Takenaka Corporation |
| Infroneer Holdings |
| Mitsubishi Heavy Industries Ltd. |
| Daiwa House Industry Co., Ltd. |
| Sekisui House, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Domestic mill capacity constraints for structural steel concentrate procurement leverage among integrated general contractors, compressing margin pools for mid-tier subcontractors bidding on seismic-resistant commercial projects.
Pricing Analysis
Institutional investors anchor project pricing through build-to-suit mandates in Tokyo's Minato and Chiyoda wards. Three-tier pricing stratifies across premium certified-green assets, standard code-compliant structures, and economy-grade speculative developments. Cost compression in mid-tier segments intensifies as MLIT zoning bonuses concentrate developer leverage. Corporate headquarters buyers exhibit lowest price sensitivity; regional logistics operators face tightest budget constraints.
Supply Chain Analysis
Upstream feedstock for mass timber systems draws from domestic forestry cooperatives in Hokkaido and Tohoku, supplemented by Scandinavian glulam imports. Cross-laminated timber panels, low-carbon concrete admixtures, and high-performance glazing constitute critical material dependencies. Single-source vulnerability concentrates in seismic engineering subsystem fabrication. Distribution runs through Kanto and Kansai industrial corridors serving general contractor assembly yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's commercial construction sector enters an early-cycle expansion phase as METI net-zero mandates accelerate material substitution ahead of GX League carbon-accounting rule revisions.
For Market Incumbents: Build certification moats around GX League early compliance to lock preferred supplier status for institutional mandates. Deepen captive R&D investment in mass timber structural systems before JIS standard revisions harden eligibility. Consolidate seismic engineering subcontractor networks to defend against specialized contractor scarcity threatening project delivery timelines. For New Entrants and Emerging Players: Establish a beachhead in Fukuoka and Sapporo commercial zones where land cost arbitrage offsets capital region saturation. Target logistics warehouse segments driven by pharmaceutical cold-chain and e-commerce fulfillment networks. Pursue public-private partnership concession qualification as the primary go-to-market credential. For Investors and Strategic Acquirers: Capital is best deployed toward integrated engineering-procurement-construction platforms with demonstrated BIM Level 2 compliance and modular construction capabilities. Long-term viability hinges on positioning ahead of operational energy disclosure mandates tightening across the analysis window. Monitor PMDA-adjacent GMP facility approval timelines as inflection indicators for pharmaceutical construction pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GX League Carbon Certification | Early compliance secures preferred supplier status for pension fund and REIT mandates. |
| Mass Timber Manufacturing Scale-Up | Cross-laminated timber capacity expansion captures share from steel moment frame displacement. |
| BIM Level 2 Platform Integration | Digital coordination mandates from general contractors compress rework rates and accelerate schedules. |
| Public-Private Partnership Concession | Government-backed infrastructure projects channel private capital with schedule certainty guarantees. |
| Regional City Revitalization Entry | Fukuoka and Sapporo commercial zones offer land cost arbitrage relative to Tokyo-Osaka saturation. |
Research Methodology
A spread of perspectives from general contractor project directors, MLIT zoning officials, institutional investor asset managers, mass timber fabricators, and seismic engineering specialists converged on the working assumptions. Primary fieldwork combined structured interviews with trade partner qualification reviews. Secondary validation drew from MLIT building permit databases, METI energy disclosure filings, JIS standard revision drafts, and GX League carbon-accounting framework documents. Bottom-up project pipeline assessments triangulated against top-down construction spending forecasts.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included project type, material selection, construction methodology, and end-user category, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from historical construction value trajectories adjusted for policy-driven substitution elasticities. Forecast inputs incorporated METI Top Runner Program enforcement timelines and PMDA facility certification velocity assumptions.
Sensitivities concentrate around GX League rule revision timing and mass timber supply chain scale-up rates. Forecasts reflect documented assumptions on institutional capital allocation patterns and seismic code amendment schedules. Material shifts in carbon-accounting stringency or domestic steel mill capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
India Commercial Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Prefabricated Construction Market
Building Construction
GCC Construction Market
Building Construction
Oman Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
United States Commercial Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Malaysia Construction Market
Building Construction
Early Production Facility Market