
 Japan Residential Construction Market | 2026-2036
Japan Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Residential Construction Market Insights
First-time buyers are rotating into prefabricated and modular housing as affordability pressures reshape Japan's residential demand profile. Sekisui House Ltd leverages its integrated supply chain to control costs across factory-built component streams. Daiwa House sustains dominance in steel-frame multifamily construction through captive manufacturing networks. Sumitomo Forestry Co. Ltd anchors market position in wood-based single-family segments with certified sustainable sourcing programs.
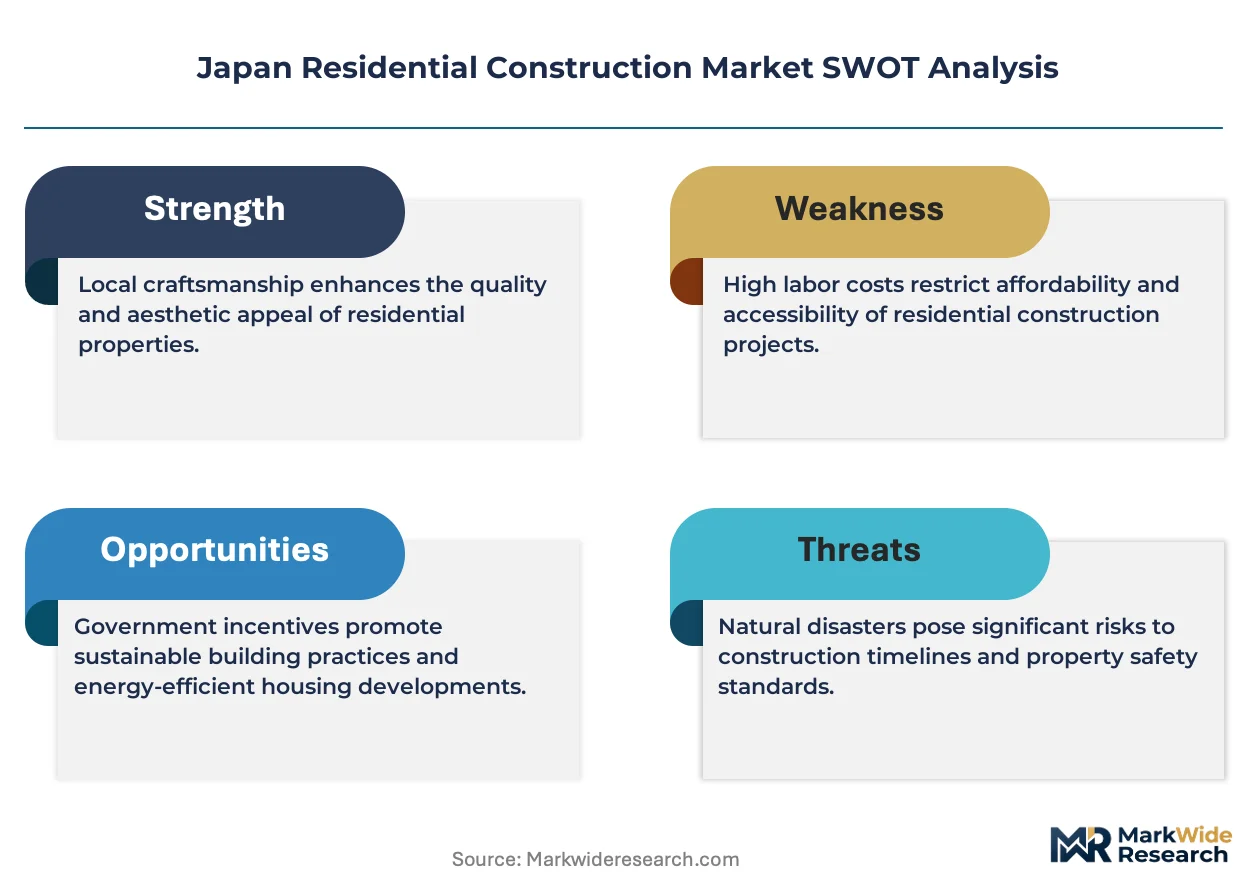
Japan residential construction encompasses the planning, assembly, and finishing of detached dwellings, attached units, and mid-rise condominiums using wood post-and-beam, reinforced concrete, or light-gauge steel framing methods. Structural performance ratings under the Housing Quality Assurance Act mandate seismic resistance grades and thermal insulation benchmarks that govern material selection and engineering design. Single-family homes occupy the largest value share but face margin compression from aging demographics and shrinking household formation rates. Prefabricated construction methods represent the fastest-expanding segment as factory precision reduces waste ratios and shortens on-site build cycles. Green building certifications are concentrating margin pools among suppliers of vacuum-insulated panels and heat-pump-integrated envelope systems.
METI's ZEH roadmap and the Housing Quality Assurance Act shape product standards by mandating net-zero energy performance tiers and post-occupancy defect liability periods. JIS standards for structural lumber and fire-resistant steel coatings govern material compliance and cross-regional market access. Local building confirmation authorities in prefectural governments enforce the Building Standards Law's seismic retrofit and accessibility upgrade requirements. Stakeholders must monitor how METI's evolving carbon-neutrality targets for the built environment will recalibrate material procurement rules and construction method eligibility for public financing support.
Market Dynamics
METI's ZEH roadmap is compressing traditional construction timelines while redirecting material procurement toward high-performance building envelopes. Prefabricated methods are accelerating adoption as factory precision reduces on-site labor dependency and waste ratios.
Growth Catalysts
- Net Zero Energy House compliance:METI's ZEH targets mandate ultra-low energy performance tiers that stimulate demand for vacuum-insulated panels and integrated heat-pump systems across new single-family construction.
- Remote-work permanence:Persistent hybrid work patterns in Tokyo and Osaka prefectures are expanding commuter-belt housing orders as households prioritize space over central location access.
- Seismic retrofit mandates:The Building Standards Law's upgraded seismic resistance grades under the Housing Quality Assurance Act are accelerating replacement demand in aging wooden housing stock.
Market Restraints
- Structural lumber supply concentration:Domestic cedar and cypress harvest constraints limit scalable expansion of wood-frame construction despite sustainability preferences.
- ZEH certification cost barriers:Third-party verification and envelope testing requirements add fixed costs that compress margins on entry-level prefabricated units.
- Demographic headwinds:Shrinking household formation rates and population decline in rural prefectures constrain absolute addressable market expansion regardless of product innovation.
Strategic Opportunities
- Kyushu regional hub development:Fukuoka and Kitakyushu metropolitan zones offer underpenetrated expansion corridors for steel-frame multifamily prefabrication as regional economic decentralization accelerates.
- Solar-integrated envelope convergence:Building-integrated photovoltaics combined with high-performance insulation create premium positioning for suppliers capable of unified system warranties.
- Public financing eligibility expansion:METI's evolving carbon-neutrality procurement rules will extend preferential lending terms to additional construction method categories beyond current ZEH-certified offerings.
Industry Challenges
- Skilled carpenter scarcity:Traditional post-and-beam construction faces acute labor shortages as aging master craftsmen retire without sufficient apprenticeship pipeline replacement.
- Supply chain reconfiguration friction:Transition from conventional on-site assembly to factory-based prefabrication requires capital-intensive retooling of logistics networks and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Residential Construction Market |
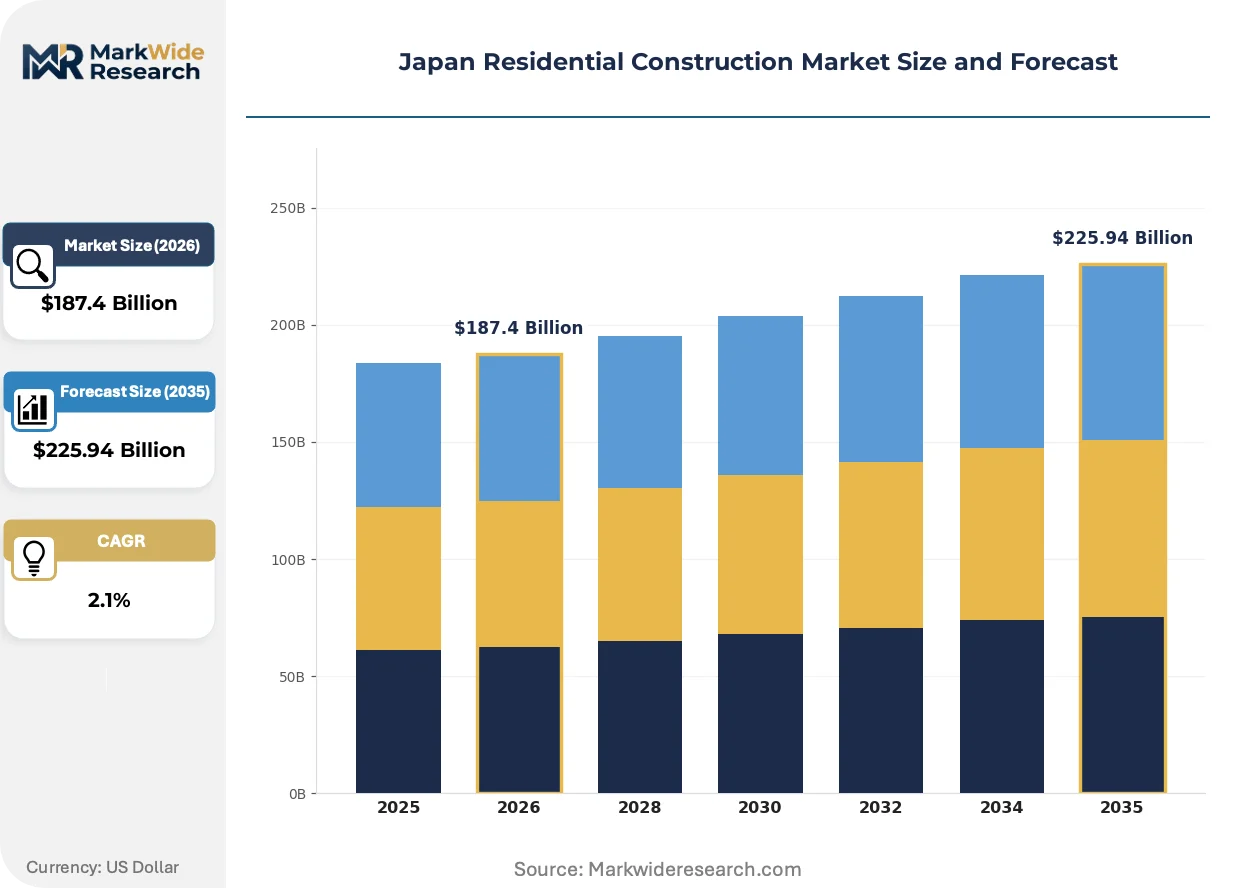
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $225.94 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-family Homes, Multifamily Units, Condominiums, Townhouses Material: Wood, Concrete, Steel, Brick End User: First-time Buyers, Investors, Retirees, Families Construction Method: Traditional, Prefabricated, Green Building, Modular |
| Companies Covered | Sekisui House Ltd, Daiwa House, Sumitomo Forestry Co. Ltd, HASEKO Corp, Iida Group Holdings Co. Ltd, Tama Home Co. Ltd, ES-CON JAPAN Ltd, Panasonic Homes, Asahi Kasei Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Residential Construction Market Trends and Innovations
Factory-based construction methods are fragmenting established supply relationships while compressing project delivery timelines. Digital design-to-fabrication workflows are enabling mass customization at scale previously reserved for standardized units.
Modular volumetric construction is fragmenting the traditional general contractor role as factory operators assume responsibility for structural, MEP, and envelope integration. First-time buyers in suburban Kanto prefectures are adopting these methods fastest due to cost predictability and shortened financing exposure. The shift compresses margin pools for conventional on-site subcontractors while concentrating value with integrated manufacturers controlling design software and component fabrication.
METI's evolving ZEH roadmap is tightening thermal performance benchmarks and expanding mandatory post-occupancy energy disclosure requirements. Housing manufacturers must now certify whole-building energy balance rather than component-level compliance, forcing redesign of HVAC-integrated envelope systems. Steel-frame multifamily developers in Osaka and Nagoya metropolitan areas face the steepest compliance redesign cycles due to higher surface-area-to-volume ratios.
Direct-to-builder procurement platforms are compressing traditional distribution layers as large prefabricated housing manufacturers establish captive supply relationships with insulation and window suppliers. Regional lumber distributors in Tohoku and Chugoku are losing volume share to factory-direct arrangements controlled by Sekisui House and Daiwa House procurement networks. This channel consolidation is most visible in Kanto's outer commuter belts where prefabricated unit delivery concentration exceeds 40 percent of new single-family permits.
Japan Residential Construction Market Segmentation
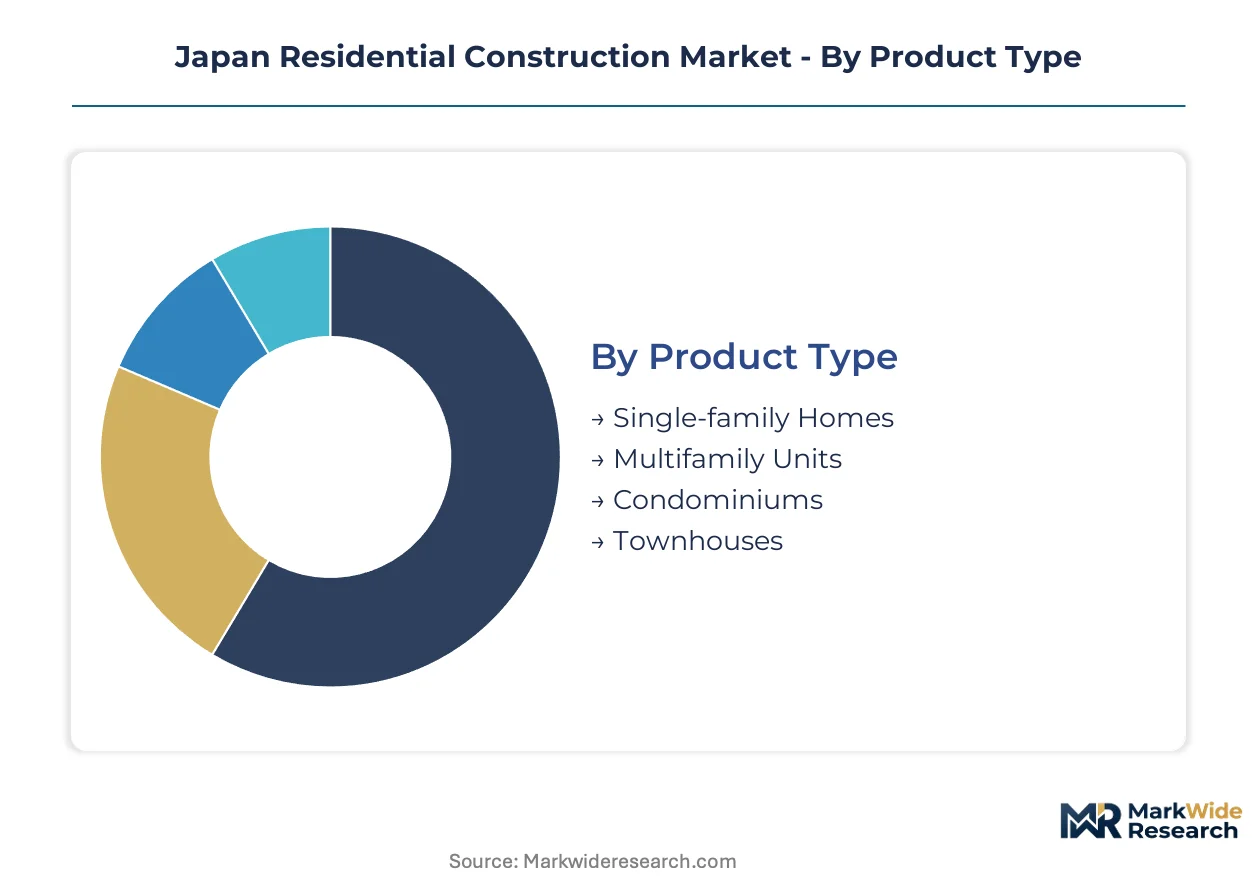
Segmentation in Japan's residential construction market reveals how METI's ZEH mandates and prefabrication adoption are redistributing value across structural methods and buyer categories. Understanding these divisions exposes where procurement power is concentrating among integrated manufacturers.
Product Type:
Margin pools concentrate in multifamily and condominium segments where steel-frame prefabrication enables factory-scale efficiency and ZEH compliance bundling.
- Single-family Homes:Post-and-beam wooden construction dominates this segment under the Housing Quality Assurance Act's seismic grading. Prefabricated wooden units from Sekisui House and Sumitomo Forestry are gaining share in Kanto's outer commuter belts as remote-work households prioritize space.
- Multifamily Units:Steel-frame construction with integrated HVAC-envelope systems commands premium positioning. Daiwa House's captive manufacturing networks dominate Osaka and Nagoya metropolitan zones where surface-area-to-volume ratios complicate ZEH certification.
- Condominiums:Reinforced concrete mid-rise structures face extended compliance redesign cycles under whole-building energy balance rules.
- Townhouses:Attached wooden units serve first-time buyers in suburban Tokyo prefectures seeking cost predictability through modular methods.
Single-family homes hold installed capacity. Multifamily units are rotating up the share rankings.
Material:
Cost tier differentiation separates certified sustainable lumber from commodity concrete as METI's carbon-neutrality procurement rules reshape eligibility for public financing.
- Wood:Domestic cedar and cypress supply constraints limit scalable expansion despite sustainability preferences. Certified sourcing programs from major housing manufacturers anchor positioning in single-family segments where JIS structural standards govern market access.
- Concrete:Reinforced concrete dominates condominium construction with established supply chains through regional ready-mix operators. Thermal mass properties complicate ZEH compliance compared to lighter envelope systems.
- Steel:Light-gauge steel framing enables factory precision and shortened on-site build cycles. Prefabricated steel units are expanding fastest in Kyushu's regional hubs as Fukuoka's economic decentralization accelerates housing demand.
- Brick:Minimal penetration in Japan's seismic-resistant construction codes limits this material to aesthetic cladding applications rather than structural use.
Wood maintains heritage share. Steel is climbing the fastest as prefabrication scales.
End User:
Customer type determines financing structure and ZEH certification willingness, with first-time buyers driving modular adoption through cost predictability requirements.
- First-time Buyers:Affordability pressures rotate this segment toward prefabricated housing with fixed-price contracts. Suburban Tokyo and Osaka prefectures show highest concentration as hybrid work patterns persist.
- Investors:Rental yield focus steers selection toward steel-frame multifamily units with lower maintenance envelopes. Regulatory depreciation schedules influence construction method selection.
- Retirees:Seismic retrofit mandates accelerate replacement demand in aging wooden housing stock. Universal design requirements under the Building Standards Law shape accessibility specifications.
- Families:Space requirements favor single-family or townhouse configurations with ZEH-compliant energy cost predictability.
First-time buyers command volume flows. Investors are rotating up the share rankings.
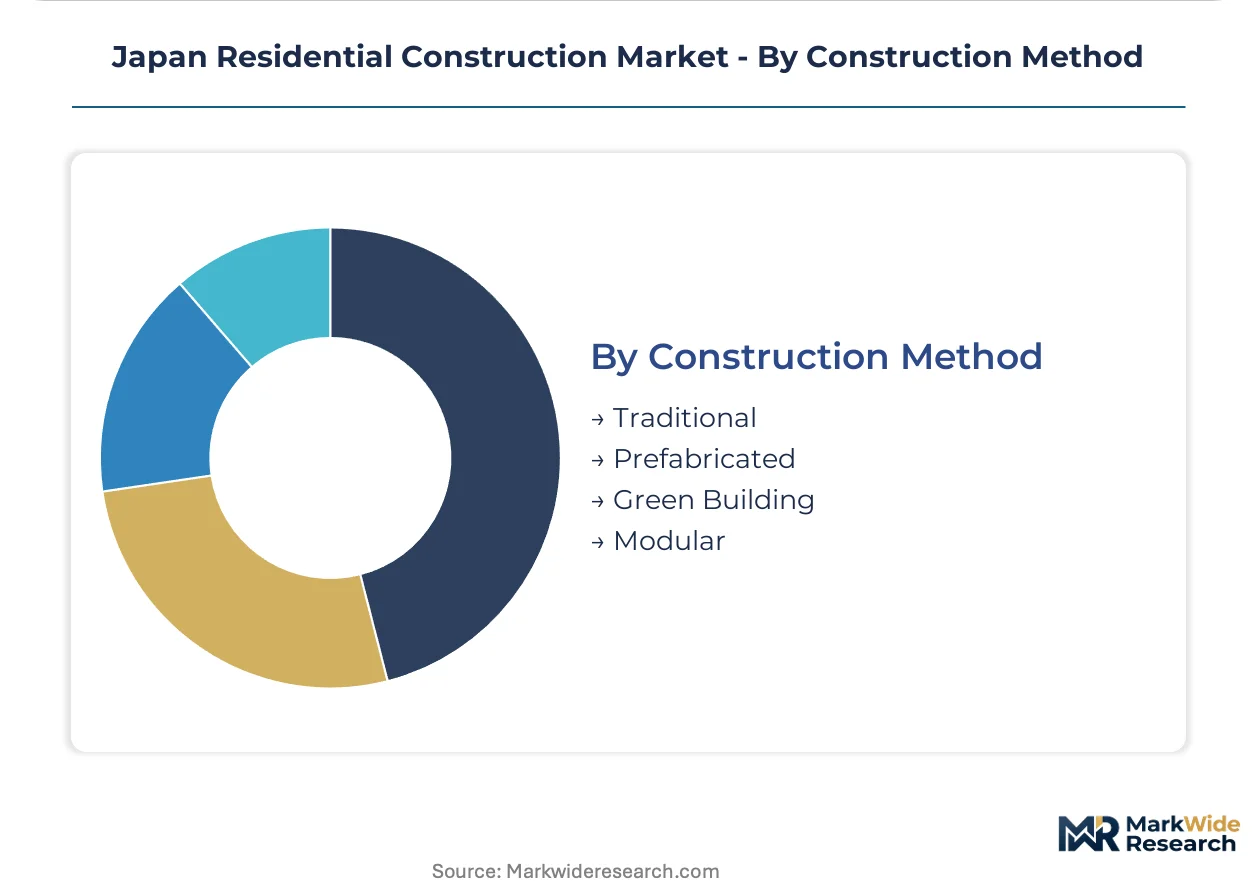
Construction Method:
Supply concentration among integrated manufacturers is fragmenting traditional general contractor roles as factory operators assume structural, MEP, and envelope integration responsibility.
- Traditional:On-site post-and-beam assembly faces acute skilled carpenter scarcity as aging master craftsmen retire. Regional lumber distributors in Tohoku and Chugoku are losing volume share to factory-direct arrangements.
- Prefabricated:Factory precision reduces waste ratios and shortens build cycles. Kanto's outer commuter belts exceed forty percent prefabricated unit delivery concentration among new single-family permits.
- Green Building:ZEH certification and vacuum-insulated panel integration create premium positioning. Third-party verification costs compress margins on entry-level units.
- Modular:Volumetric construction enables mass customization at scale. Digital design-to-fabrication workflows compress project delivery timelines while fragmenting established subcontractor relationships.
Traditional methods hold installed capacity. Prefabricated construction is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-based prefabrication concentrates supply capacity among integrated manufacturers controlling captive component networks across Japan's major metropolitan zones. METI's ZEH mandates and seismic retrofit requirements are redistributing construction activity toward outer commuter belts and regional economic hubs.
Kanto/Tokyo
Remote-work permanence drives first-time buyer demand for spacious single-family units in Saitama, Chiba, and Kanagawa prefectures. The Building Standards Law enforces upgraded seismic resistance grades that accelerate wooden housing replacement. Sekisui House and Daiwa House dominate prefabricated delivery in Tokyo's outer commuter belts where factory-direct procurement exceeds forty percent of new permits.
Kansai/Osaka
Steel-frame multifamily construction concentrates in Osaka, Kyoto, and Hyogo prefectures as investors target rental yield stability. METI's ZEH roadmap mandates whole-building energy balance certification that complicates compliance for high surface-area-to-volume structures. Daiwa House's captive manufacturing networks anchor production in the Osaka metropolitan zone.
Chubu/Nagoya
Automotive industry supply chain workers generate steady housing demand across Aichi, Gifu, and Mie prefectures. JIS standards for structural lumber govern material compliance in wood-frame construction. Sumitomo Forestry Co. Ltd maintains certified sustainable sourcing programs serving single-family developments in Nagoya's suburban corridors.
Kyushu
Fukuoka and Kitakyushu metropolitan zones offer underpenetrated expansion corridors for steel-frame prefabrication as regional economic decentralization accelerates. METI's evolving carbon-neutrality procurement rules extend preferential lending terms to ZEH-certified construction methods. Factory-based producers are establishing distribution nodes to capture emerging demand from Kyushu's regional hubs.
Tohoku
Post-disaster reconstruction programs and seismic retrofit mandates drive replacement demand in aging wooden housing stock across Miyagi, Fukushima, and Iwate prefectures. The Housing Quality Assurance Act's defect liability periods shape builder selection criteria. Regional lumber distributors face volume compression as factory-direct arrangements from Kanto-based manufacturers penetrate northern markets.
Japan Residential Construction Market Competitive Landscape
Concentration sits with integrated housing manufacturers commanding captive supply chains from component fabrication through final assembly. Three archetypes dominate: factory-based prefabrication specialists with in-house steel and wood processing, diversified construction conglomerates with modular manufacturing subsidiaries, and regional lumber-integrated builders with certified sustainable sourcing programs. Competitive moves center on backward integration into insulation and window supply, plus geographic expansion into underpenetrated regional hubs.
Among Japan-based integrated manufacturers, Sekisui House Ltd, Daiwa House, and Sumitomo Forestry Co. Ltd occupy positions exemplifying the three dominant archetypes. Sekisui House represents factory-based prefabrication with integrated supply chain control. Daiwa House anchors steel-frame multifamily production through captive manufacturing networks. Sumitomo Forestry sits within the wood-based single-family segment with certified sustainable sourcing programs. These three entities collectively illustrate how procurement power concentrates among manufacturers controlling design software, component fabrication, and envelope integration capabilities.
| Leading Market Players |
|---|
| Sekisui House Ltd |
| Daiwa House |
| Sumitomo Forestry Co. Ltd |
| HASEKO Corp |
| Iida Group Holdings Co. Ltd |
| Tama Home Co. Ltd |
| ES-CON JAPAN Ltd |
| Panasonic Homes |
| Asahi Kasei Homes |
| Others |
Pricing and Supply Chain Analysis
Fixed-price contracts for prefabricated housing units lock in supply access for first-time buyers while compressing margin visibility for traditional on-site builders facing METI's evolving ZEH compliance costs. This contract structure concentrates procurement power with integrated manufacturers controlling captive component networks across Japan's major metropolitan zones.
Pricing Analysis
METI's ZEH roadmap dictates the pricing tier structure across Japan's residential construction market. Three-tier pricing separates ZEH-certified premium units with vacuum-insulated panels from standard-grade prefabricated homes and economy-tier traditional post-and-beam builds. Cost compression in entry-level prefabricated segments is intensifying because third-party verification and envelope testing requirements add fixed compliance burdens. First-time buyers in suburban Tokyo prefectures exhibit highest price sensitivity, while investors targeting steel-frame multifamily rentals show lowest sensitivity due to depreciation schedule benefits.
Supply Chain Analysis
Domestic cedar and cypress harvest constraints in Japan's Tohoku and Chugoku regions create supply chokepoints for wood-frame construction despite sustainability preferences. The supply chain draws from domestic structural lumber, imported fire-resistant steel coatings, and regionally manufactured vacuum-insulated panels. Single-source vulnerability concentrates in certified sustainable lumber programs where major housing manufacturers control captive sourcing. Distribution runs through factory-direct arrangements controlled by integrated manufacturers rather than traditional regional lumber distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's residential construction market is approaching a platform-economics inflection as digital design-to-fabrication workflows enable mass customization and fragment traditional general contractor roles. Interoperability between housing manufacturers' proprietary software systems and METI's energy disclosure databases is reshaping competitive positioning.
For Market Incumbents: Secure backward integration into high-performance insulation and window supply to defend margin pools against emerging modular entrants. METI's tightening whole-building energy balance rules threaten component-level suppliers unable to offer unified system warranties. Capacity addition in Kyushu's regional hubs anchors positioning as economic decentralization accelerates housing demand in Fukuoka metropolitan zones.
For New Entrants and Emerging Players: Anchor in Kyushu's underpenetrated steel-frame prefabrication corridor where factory-based producers have not yet established distribution density. Fukuoka and Kitakyushu metropolitan zones offer white-space expansion as regional economic decentralization outpaces incumbent manufacturing footprint. Direct-to-builder procurement platforms bypassing traditional distribution layers provide the strongest go-to-market angle against established Kanto-based networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated housing manufacturers with captive supply chains and factory-direct distribution control. Long-term viability across the analysis window favors archetypes combining design software ownership with component fabrication capabilities. Watch METI's carbon-neutrality procurement rule evolution as the signal for which construction method categories will secure preferential public financing eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Performance Insulation | Captive supply of vacuum-insulated panels secures ZEH compliance margins against third-party verification cost compression. |
| Kyushu Regional Hub Capacity Expansion | Fukuoka metropolitan zone manufacturing nodes capture decentralized economic growth outside saturated Kanto markets. |
| Digital Design-to-Fabrication Platform Development | Mass customization capabilities fragment traditional general contractor roles while concentrating value with software-owning manufacturers. |
| Solar-Integrated Envelope System Convergence | Building-integrated photovoltaics combined with HVAC-envelope integration create premium positioning through unified system warranties. |
| Certified Sustainable Sourcing Program Expansion | JIS-compliant structural lumber programs anchor market access in single-family segments under Housing Quality Assurance Act seismic grading. |
Research Methodology
Cross-validation between housing manufacturer procurement disclosures and METI ZEH certification databases anchors the qualitative findings across this analysis. Primary interviews with prefabricated housing executives, regional lumber distributor managers, prefectural building confirmation authority officers, and first-time buyer focus groups combined with secondary validation from JIS standards documentation, Housing Quality Assurance Act regulatory filings, and Building Standards Law enforcement records. Bottom-up permit data triangulates against top-down construction value estimates across the projection horizon.
Sensitivity analysis around remote-work permanence assumptions and METI carbon-neutrality timeline scenarios shapes the analytical framework. Segmentation dimensions modeled include construction method, structural material, buyer archetype, and prefectural regulatory cluster. CAGRs derive from installed capacity rotation rates and share shift trajectories rather than absolute demand expansion. ZEH compliance cost curves and prefabricated delivery concentration thresholds serve as industry-specific forecast inputs.
Material uncertainties — METI regulatory acceleration or deceleration, seismic retrofit mandate enforcement variance across prefectures, and domestic lumber harvest fluctuations — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as METI's evolving carbon-neutrality procurement rules and hybrid work pattern persistence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
US Residential Construction Market