
 Stone Veneer Market | 2026-2036
Stone Veneer Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Veneer Market Analysis
Buyer concentration in residential construction is broadening as custom homebuilders and multifamily developers diversify cladding specifications beyond traditional brick and stucco. Eldorado Stone leverages extensive distributor networks to sustain brand visibility across North American housing markets. Boral Limited anchors its position through captive supply of raw aggregates and in-house production of manufactured stone variants. Coronado Stone Products differentiates via specialized textures that replicate regional geological formations for architect-specified projects.
Stone veneer comprises a thin decorative facing layer, typically manufactured from Portland cement, lightweight aggregates, and iron oxide pigments cast in molds, applied at depths under two inches to simulate natural stone mass without structural load. Its primary commercial purpose is to deliver aesthetic masonry appearance at reduced material cost and simplified structural engineering. Manufactured stone commands the largest volume share due to lower per-square-foot material and freight costs, while thin veneer represents the fastest-expanding format as installers favor reduced mortar beds and faster application cycles. Residential application generates the dominant revenue pool, though commercial facades carry higher per-project margins.
OSHA governs silica exposure limits during stone veneer cutting and installation, compelling contractors toward wet-cutting methods and prefabricated panel systems. EPA oversees VOC emissions from sealants and adhesives used in mechanical installation, shaping product formulation decisions by manufacturers. ISO 9001 quality management certification increasingly gates access to commercial specification channels. Stakeholders must monitor evolving state-level building code amendments that favor continuous insulation assemblies and assess whether thin veneer systems qualify as approved cladding in high-wind zones.
Market Dynamics
Lightweight cladding specifications are displacing traditional masonry across residential construction, compressing installation timelines and reducing structural load requirements for builders.
Growth Catalysts
- OSHA Silica Standards:Wet-cutting mandates and prefabricated panel adoption accelerate installer productivity while reducing on-site exposure liability.
- Texas Housing Corridors:Custom homebuilders in Dallas-Fort Worth and Houston expand manufactured stone specifications for cost-competitive aesthetic differentiation.
- Thin Veneer Format:Reduced mortar bed requirements cut application cycles by half compared to full-bed masonry, driving contractor preference shifts.
Market Restraints
- Portland Cement Volatility:Energy-intensive clinker production faces input cost swings that compress manufacturer margins unpredictably.
- Florida High-Wind Codes:Continuous insulation assembly requirements create technical friction for thin veneer qualification in coastal zones.
- Natural Stone Substitution:Genuine thin-cut slate and granite compete in premium architect-specified segments where authenticity commands specification.
Strategic Opportunities
- Multifamily Developers:Garden-style apartment complexes in Sun Belt states represent underpenetrated volume for lightweight facade systems.
- EPA VOC Pathways:Low-emission sealant formulations open specification channels in LEED-targeted commercial projects.
- Mechanical Fastening Convergence:Integration of rainscreen attachment systems with thin veneer creates premium product tiers for high-performance envelopes.
Industry Challenges
- Skilled Masonry Labor:Specialized thin-set application techniques require training pipelines that lag demand expansion in active construction markets.
- ISO 9001 Certification Timelines:Commercial specification gates demand quality management documentation that elongates vendor qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Veneer Market |
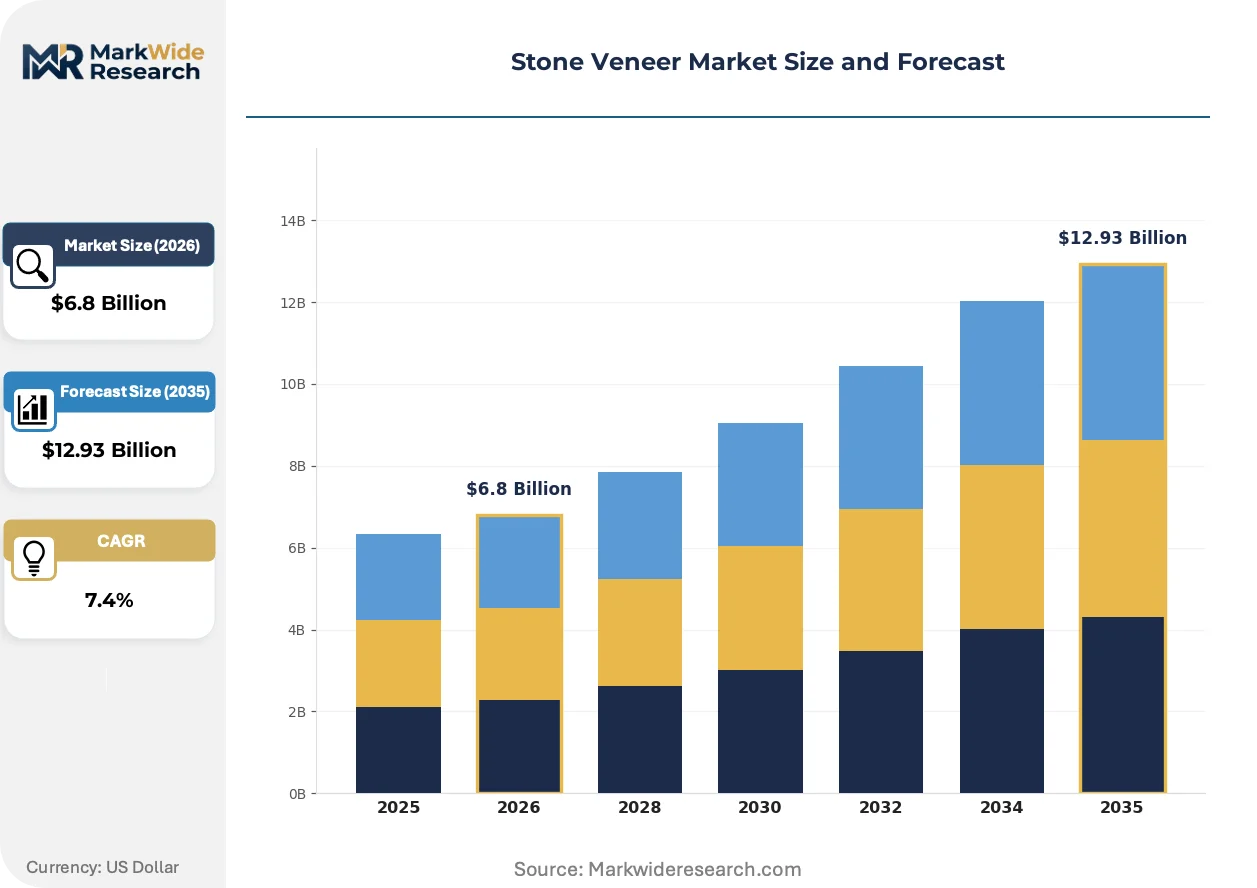
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Stone, Manufactured Stone, Thin Veneer, Full Veneer Application: Residential, Commercial, Landscaping, Interior Decoration Installation Method: Adhesive, Mechanical, Mortar, Prefabricated Finish Type: Polished, Rough, Honed, Textured |
| Companies Covered | Quality Stone Veneer, Boulder Creek Stone, Boral Limited, Fond du Lac Natural Stone, Quarry Mill, Coronado Stone Products, StoneWorks, Eldorado Stone, Mountain View Stone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Veneer Market Emerging Trajectories
Product format evolution and regulatory compliance pathways are compressing traditional specification hierarchies while opening new installation methodologies.
Prefabricated stone veneer panels are consolidating field labor requirements into controlled factory environments. Multifamily developers in high-volume markets adopt these systems to compress construction schedules and reduce weather-dependent trade coordination. The technology is consolidating installation quality variance that previously fragmented contractor performance.
EPA oversight of VOC-emitting sealants and adhesives is tightening formulation requirements for mechanical installation systems. Manufacturers reformulate product chemistries to maintain specification eligibility in commercial channels. Wet-state adhesive categories face the most acute compliance pressure in California and Northeast corridor markets.
Custom homebuilders are unbundling cladding specification from general contractor procurement, engaging directly with regional distributors for texture-matched geological replication. This disintermediation compresses information asymmetry between architect intent and final installation. The pattern is most visible in Texas and Florida custom residential segments where design-build integration is strongest.
Stone Veneer Market Segmentation
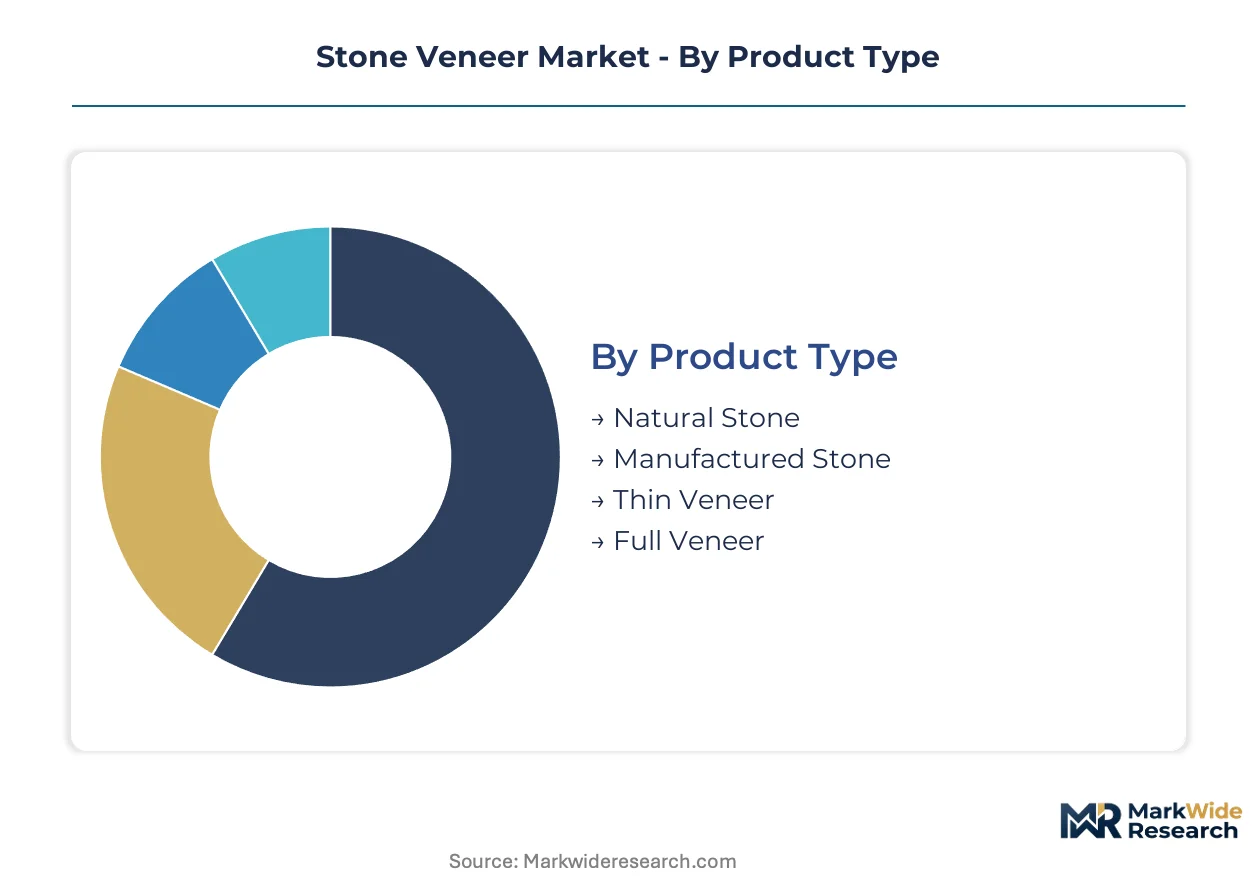
Stone veneer manufacturers align capital deployment with format-specific tooling requirements. Product type determines mold investment intensity, while application focus shapes distribution channel economics. Installation method selection directly impacts field labor training costs and warranty exposure.
Product Type:
Capital intensity peaks with manufactured stone production due to mold fabrication and pigment formulation infrastructure. Natural stone operations demand quarry access and cutting equipment but avoid chemical processing overhead.
- Natural Stone:Quarried material cut to specification thickness delivers authentic geological variation. Demand concentrates in premium architect-specified projects across Texas custom residential corridors where authenticity commands specification premiums. Supply constraints from domestic quarry permitting limit volume expansion.
- Manufactured Stone:Portland cement, lightweight aggregates, and iron oxide pigments cast in molds simulate natural appearance at reduced material cost. Dallas-Fort Worth and Houston builders specify this format for cost-competitive aesthetic differentiation in production housing. Captive aggregate supply anchors manufacturer margin stability.
- Thin Veneer:Reduced bed depth enables faster application cycles and lower structural load requirements.
- Full Veneer:Traditional massing requires reinforced support systems and extended installation timelines.
Manufactured stone absorbs the bulk of installed capacity; thin veneer is expanding most quickly.
Application:
Margin structure varies sharply across end-use segments, with commercial facades capturing premium pricing per square foot despite lower volume.
- Residential:Custom homebuilders and multifamily developers drive volume procurement through regional distributor networks. Florida and Texas housing corridors specify lightweight cladding for foundation cost reduction and accelerated construction schedules. Garden-style apartments in Sun Belt states represent underpenetrated volume opportunity.
- Commercial:LEED-targeted projects and high-performance building envelopes command specification premiums. EPA VOC compliance requirements for sealants and adhesives filter vendor eligibility in this channel. ISO 9001 certification gates access to architect-led specification processes.
- Landscaping:Exterior hardscape and retaining wall applications emphasize durability and freeze-thaw resistance.
- Interior Decoration:Feature walls and fireplace surrounds prioritize aesthetic replication over structural performance.
Residential application generates dominant revenue volume; commercial facades deliver steepest margin expansion.
Installation Method:
Field labor productivity and OSHA compliance exposure differentiate method selection for contractor procurement decisions.
- Adhesive:Wet-state chemical bonding enables thin-veneer application with reduced mortar bed requirements. California and Northeast corridor markets face acute EPA formulation pressure for VOC-emitting adhesive categories. Manufacturers reformulate chemistries to maintain commercial specification eligibility.
- Mechanical:Rainscreen attachment systems integrate with thin veneer for high-performance envelope assemblies. Wind-zone building codes in Florida coastal markets drive technical qualification requirements for continuous insulation compatibility.
- Mortar:Traditional full-bed application persists in heritage replication and structural massing requirements.
- Prefabricated:Factory-controlled panel assembly consolidates field labor and reduces weather-dependent trade coordination.
Adhesive methods retain dominant installation share; prefabricated systems are gaining share fastest in multifamily volume construction.
Finish Type:
Texture replication capability determines architect specification success in regionally differentiated housing markets.
- Polished:Smooth surface treatment suits interior feature applications and contemporary commercial aesthetics.
- Rough:Aggressive texture replicates split-face quarry appearance for rustic residential styling.
- Honed:Satin-smooth finish bridges traditional and modern architectural vocabularies.
- Textured:Mold-cast surface variation enables geological replication matched to regional stone formations. Texas custom homebuilders engage directly with distributors for texture-matched specifications that compress information asymmetry between architect intent and final installation.
Textured finishes dominate residential specification; honed surfaces are climbing fastest in contemporary commercial facades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential construction demand concentrates in the United States, with Texas and Florida housing corridors driving specification volume for lightweight cladding systems. Regional regulatory frameworks and climatic conditions shape product qualification requirements across distinct sub-markets.
United States
Texas and Florida custom homebuilders specify manufactured stone for cost-competitive aesthetic differentiation in Dallas-Fort Worth and Houston corridors. OSHA silica exposure limits govern wet-cutting mandates and prefabricated panel adoption during installation. Miami-Dade County enforces stringent high-wind building codes that create technical friction for thin veneer qualification in coastal zones.
Canada
Multifamily developers in Ontario and British Columbia specify lightweight facade systems for garden-style apartment construction. The country's national building code authority governs continuous insulation assembly requirements for exterior cladding. Greater Toronto Area construction activity concentrates demand for freeze-thaw resistant stone veneer formulations.
Mexico
Monterrey and Mexico City metro areas drive residential cladding demand as production housing expands in northern industrial corridors. The country's federal environmental regulator oversees emissions standards for construction materials and sealants. Bajío Region manufacturing clusters supply lightweight aggregates to regional fabricated stone producers.
Germany
Commercial facade renovation projects specify thin veneer systems for high-performance building envelope upgrades. REACH regulations govern chemical formulations in adhesives and sealants used for mechanical installation. Bavaria and North Rhine-Westphalia industrial districts concentrate prefabricated panel production capacity.
Australia
New South Wales and Victoria residential developers adopt manufactured stone for bushfire-resistant construction in peri-urban expansion zones. The country's building code authority mandates fire performance ratings for external cladding materials. Sydney and Melbourne metropolitan construction corridors concentrate specification activity for textured finish replication.
Stone Veneer Market Vendor Landscape
North American producers anchor one tier; European and Asia-Pacific specialists hold differentiated positions in premium specification channels. The vendor base structures around three tiers: integrated material suppliers with captive aggregate access, specialized texture replication firms serving architect-specified projects, and regional fabricators competing on installation speed and distributor proximity. Strategic moves concentrate on backward integration into raw material supply and prefabricated panel system development to compress field labor requirements.
Among North American fabricators, Eldorado Stone, Boral Limited, and Coronado Stone Products occupy distinct competitive positions. Eldorado Stone exemplifies the distributor-network archetype, sustaining brand visibility across housing markets through extensive channel relationships. Boral Limited represents integrated supply chain positioning, with captive raw aggregate access anchoring margin stability in manufactured stone production. Coronado Stone Products sits within the specialized texture tier, serving architect-specified projects requiring regional geological replication. These three company structures illustrate how capital deployment, raw material control, and specification channel access differentiate competitive outcomes in residential and commercial cladding markets.
| Leading Market Players |
|---|
| Quality Stone Veneer |
| Boulder Creek Stone |
| Boral Limited |
| Fond du Lac Natural Stone |
| Quarry Mill |
| Coronado Stone Products |
| StoneWorks |
| Eldorado Stone |
| Mountain View Stone |
| Others |
Supply Flow & Price Mechanics
OSHA silica exposure mandates are pushing contractors toward wet-cutting equipment and prefabricated panel systems, forcing manufacturers to absorb capital costs for mold fabrication infrastructure while distributors compete on installation support pricing. This specification-driven procurement shift compresses margin flexibility for regional fabricators lacking captive aggregate supply.
Pricing Analysis
Volume concentration in manufactured stone segments runs against margin concentration in thin veneer and prefabricated panel tiers. Price differentiation hinges on ISO 9001 certification status and captive raw material access, with uncertified regional players facing downward pressure from national distributors. Cost compression in standard manufactured stone intensifies as Texas and Florida housing corridors consolidate procurement through fewer distributor gatekeepers. Multifamily developers exhibit highest price sensitivity due to square-footage scale, while architect-specified commercial facades tolerate premium positioning for geological replication fidelity.
Supply Chain Analysis
Skilled masonry labor availability in Texas, Florida, and Ontario manufacturing geographies constrains production scaling for thin-veneer format expansion. Raw material sourcing draws from domestic lightweight aggregate deposits, Portland cement clinker supply, and iron oxide pigment imports. Single-source vulnerability concentrates in specialized mold fabrication equipment where European suppliers dominate precision tooling. Distribution runs through regional building material distributors with exclusive territory agreements, compressing direct manufacturer access to custom homebuilder accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA VOC thresholds and OSHA silica standards erect barrier-to-entry moats favoring capitalized incumbents with quality management documentation and wet-cutting infrastructure already deployed.
For Market Incumbents: Hedge against natural stone substitution in premium architect channels by deepening captive aggregate control and accelerating prefabricated panel R&D. ISO 9001 certification timelines already gate commercial specification access; extend this advantage through rainscreen-integrated thin veneer development for Florida high-wind code compliance. Channel control through exclusive distributor relationships remains the priority defensive lever against direct procurement disintermediation by Texas custom homebuilders. For New Entrants and Emerging Players: The price-point gap between premium geological-replication products and economy manufactured stone creates entry space for mid-tier texture specialists. Garden-style multifamily apartments in Sun Belt states offer the most penetrable volume segment given incumbent neglect of installation-speed value propositions. A go-to-market angle anchored on mechanical fastening system compatibility with continuous insulation assemblies bypasses adhesive formulation compliance burdens that burden established players. For Investors and Strategic Acquirers: The window for entry favors regional fabricators with quarry access or specialized mold libraries over pure distribution plays. Long-term viability centers on backward integration into raw material supply and prefabrication capability as field labor scarcity intensifies. The signal to watch is Florida building code amendment velocity for thin veneer wind-load qualification—acceleration here compresses qualification timelines for non-integrated entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Panel System Development | Factory-controlled assembly consolidates field labor requirements for multifamily developers in Dallas-Fort Worth and Houston corridors. |
| Captive Aggregate Supply Integration | Upstream control over lightweight aggregate deposits anchors margin stability against Portland cement input volatility. |
| ISO 9001 Quality Certification Investment | Documentation gates access to architect-led commercial specification channels with LEED-targeted project eligibility. |
| Low-VOC Adhesive Formulation Reformulation | EPA compliance maintenance preserves specification access in California and Northeast corridor commercial markets. |
| Rainscreen Attachment System Convergence | Integration with thin veneer creates premium tiers for Miami-Dade County high-performance envelope requirements. |
Methodological Framework
Document review covered SEC filings of building material suppliers, OSHA regulatory dockets, EPA emission standard updates, and state-level building code amendments, complemented by interviews with regional distributor account managers, custom homebuilder procurement directors, commercial architect specification leads, and multifamily developer project executives. Secondary validation drew from construction permit databases, customs records for pigment and aggregate trade flows, and industry association shipment reports. Bottom-up project pipeline analysis and top-down construction spending allocation triangulated market sizing.
Segment-level value and volume estimates were produced through demand-side modeling of housing starts by cladding specification intensity and supply-side capacity assessment across mold fabrication infrastructure. Segmentation dimensions included product format, application end-use, installation methodology, and finish texture tier. CAGRs were derived from regression of historical specification penetration rates against regulatory compliance cost trajectories. Forecast inputs incorporated Portland cement price elasticity and skilled masonry labor wage indices.
Inputs from distributor interviews and building permit filings were available through the study window; gaps in real-time multifamily project specification data introduce uncertainty bands around commercial application forecasts. Forecasts reflect assumptions regarding OSHA enforcement consistency and state adoption timelines for continuous insulation assembly codes. Material deviation in Florida wind-load qualification standards or Portland cement carbon border adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Global Elastic Rail Fasteners Market