
 India Ceramic Tiles Market | 2026-2036
India Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
India Ceramic Tiles Market Outlook
Porcelain is pivoting toward premium residential and commercial applications as builders substitute traditional ceramic for denser, lower-absorption alternatives. Kajaria Ceramics leverages integrated manufacturing across Gujarat and Rajasthan to sustain cost leadership in vitrified tiles. Somany Ceramics anchors its position through extensive dealer networks spanning tier-2 and tier-3 cities. Orient Bell Tiles differentiates via design-led product lines targeting architect-specified projects.
India ceramic tiles are fired clay-based surfacing materials, typically composed of kaolin, feldspar, and silica, manufactured through dry pressing or extrusion at temperatures exceeding 1,000°C to achieve hardness and moisture resistance for flooring and wall cladding. Porcelain tiles command the highest value per square meter due to superior density and through-body color consistency, while glazed tiles remain the volume leader in mass residential construction. The residential end user segment generates the deepest demand pool, though commercial applications in hospitality and retail are expanding faster as developers prioritize durability and aesthetic differentiation.
BIS standards govern dimensional stability, water absorption, and breaking strength, compelling manufacturers to upgrade kiln technology and raw material sourcing to maintain certification. The PLI scheme for ceramics and allied sectors incentivizes capital investment in automated production lines and energy-efficient firing. Stakeholders must monitor evolving BIS norms and state-level building codes as these will determine which product grades qualify for government infrastructure and affordable housing tenders.
Market Dynamics
The Morbi ceramic cluster in Gujarat concentrates over 70 percent of domestic vitrified tile capacity, creating a supply architecture where kiln technology upgrades and BIS compliance investments determine competitive survival.
Growth Catalysts
- PLI scheme for ceramics:Capital subsidies for automated production lines and energy-efficient firing systems are accelerating plant modernization across Rajasthan and Gujarat manufacturing belts.
- Affordable housing vertical:Government tender volumes for mass residential projects in tier-2 cities are expanding procurement of standard-grade glazed wall and floor tiles.
- Digital inkjet decoration:High-resolution surface printing technology is enabling cost-effective replication of natural stone aesthetics at porcelain-grade performance specifications.
Market Restraints
- Feldspar and zircon supply concentration:Domestic raw material shortages force dependence on Rajasthan and Andhra Pradesh mining belts, exposing manufacturers to input cost volatility.
- Natural stone substitution:Granite and marble distributors in premium residential segments retain architect preference for through-body authenticity in high-value flooring specifications.
- BIS certification friction:Dimensional tolerance and water absorption testing protocols extend product approval timelines, delaying commercial launch schedules for new tile formats.
Strategic Opportunities
- Tier-3 city retail penetration:Dealer network expansion into Uttar Pradesh and Madhya Pradesh secondary markets captures underpenetrated replacement demand from aging housing stock.
- Export corridor activation:DGFT trade facilitation for Middle East and African markets is opening volume outlets for Morbi-cluster surplus production beyond domestic absorption.
- Thin porcelain large-format slabs:Sintered compact surfaces are converging with traditional tile distribution channels, creating hybrid specification opportunities in commercial facade applications.
Industry Challenges
- Kiln automation skill scarcity:Programmable firing curve optimization and predictive maintenance systems require process engineers that Gujarat technical institutes currently undersupply.
- Legacy gas-fired infrastructure:CNG price volatility and grid electricity reliability gaps complicate the transition to consistent low-carbon thermal energy for continuous roller hearth operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ceramic Tiles Market |
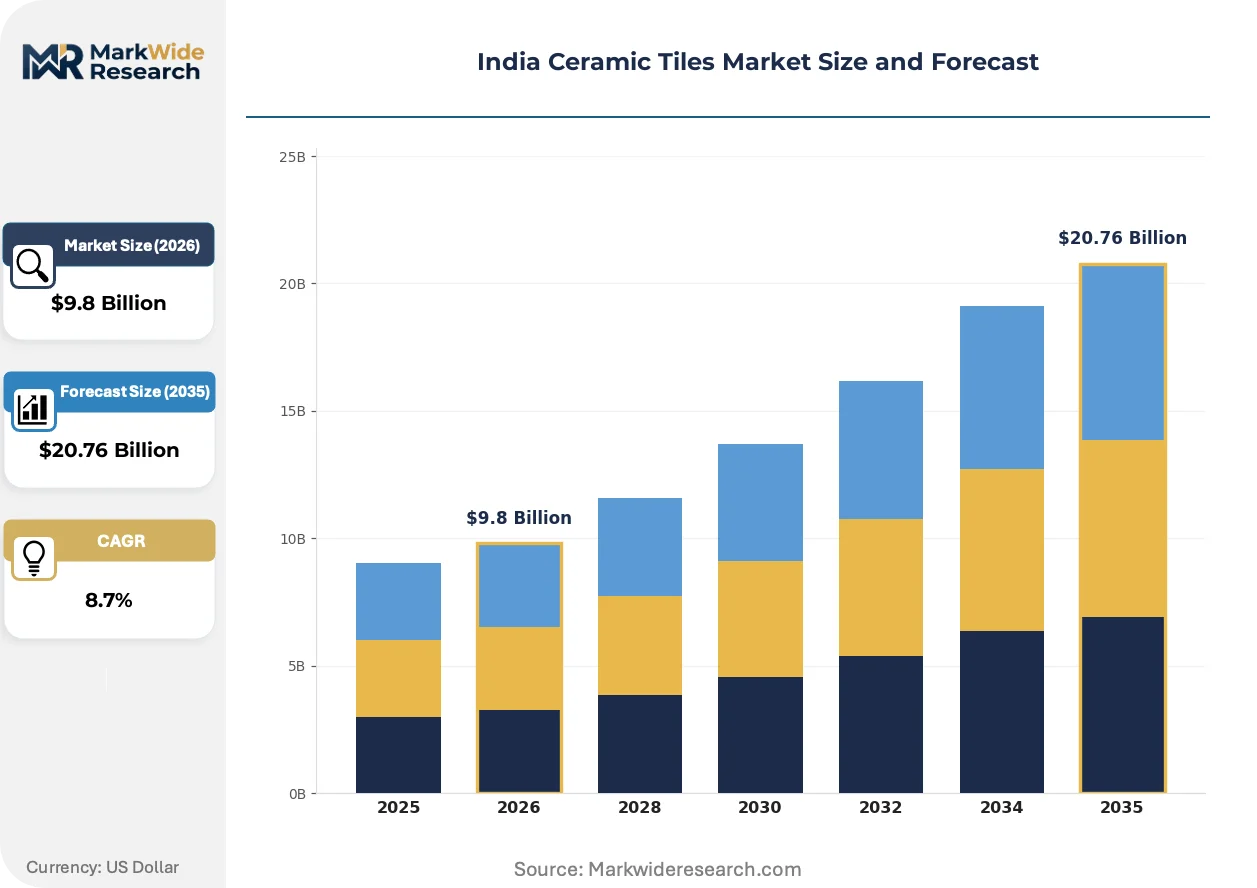
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Porcelain Tiles, Ceramic Mosaic End User: Residential, Commercial, Industrial, Institutional Surface Finish: Polished, Matte, Textured, Anti-slip Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | RAK Ceramics, Metrocity Tiles, Kajaria Ceramics, Somany Ceramics, Nitco, Orient Bell Tiles, Sakar Granito, Varmora Granito, Simpolo Vitrified, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ceramic Tiles Market Strategic Shifts
Digitization of surface decoration and firing control systems is compressing product development cycles while BIS quality mandates are forcing technology refresh investments across the Morbi manufacturing base.
Single-pass digital inkjet printing is decentralizing design iteration authority from centralized R&D facilities to plant-floor quality teams. Mid-tier manufacturers in Morbi are adopting modular printhead configurations that enable 48-hour pattern changeovers. This capability is compressing the competitive moat that premium brands previously maintained through proprietary design archives.
BIS certification mandates for water absorption and breaking strength are tightening product standards nationwide. Manufacturers must upgrade kiln temperature uniformity systems and raw material beneficiation processes to maintain compliance. The residential mass-housing segment faces the steepest compliance cost curve as thin-body glazed tiles approach performance threshold boundaries.
Architect-specified projects are consolidating procurement authority away from traditional dealer networks toward direct manufacturer relationships. Large-format porcelain slabs for commercial facades and hospitality interiors are bypassing distributor markups through specification-driven tender processes. Mumbai and Delhi NCR commercial developments exhibit the most pronounced channel disintermediation, with project consultants managing direct factory negotiations.
India Ceramic Tiles Market Segmentation
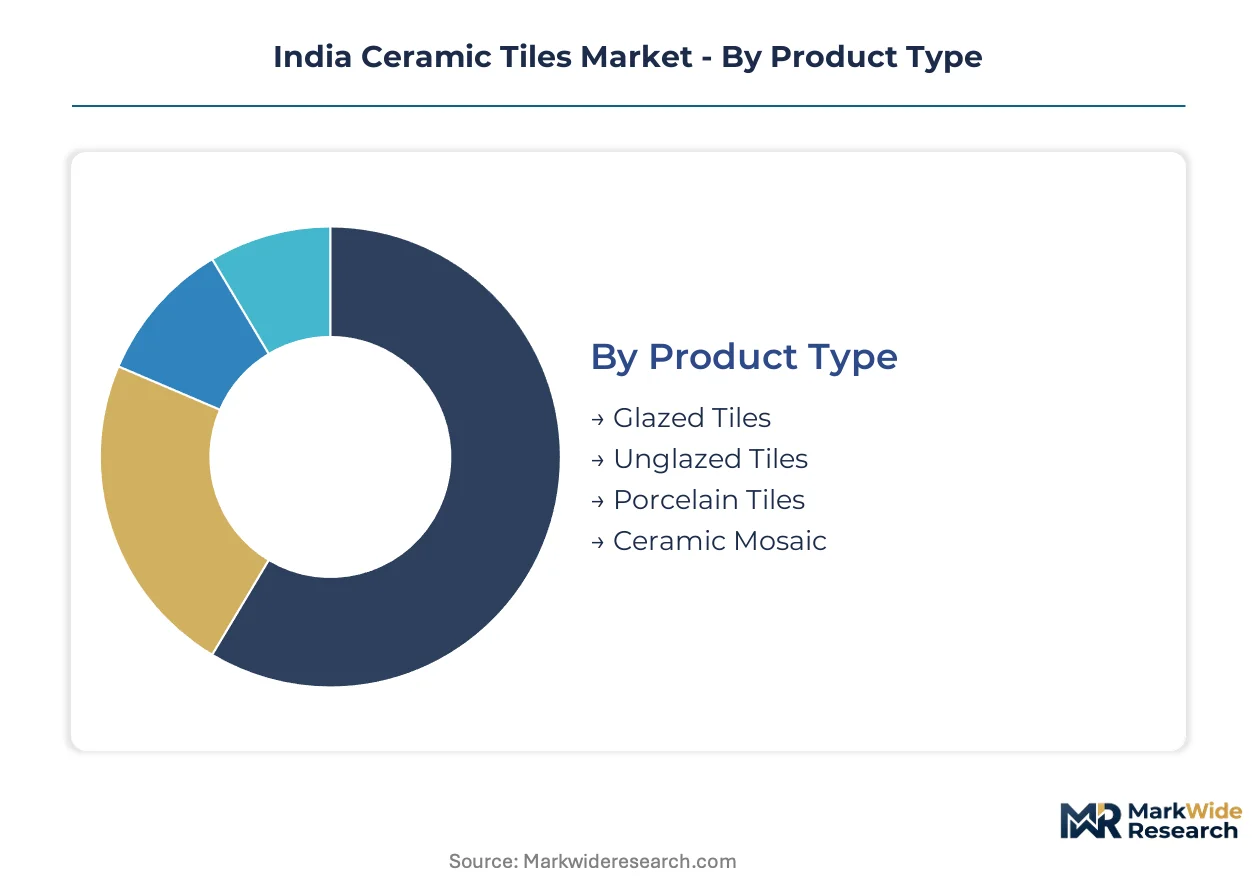
Product differentiation across firing temperature, surface chemistry, and format dimensions determines margin capture and factory utilization rates. Segmentation clarity exposes where Morbi cluster capacity concentrates versus where specification premiums accrue.
Product Type:
Supply concentration in Gujarat's Morbi belt favors vitrified-grade production, yet product mix varies sharply by absorption rates and through-body density.
- Glazed Tiles:Clay bodies coated with glass-forming minerals fired at 1,000–1,050°C create impermeable decorative surfaces. Mass housing tenders in Uttar Pradesh and Madhya Pradesh absorb the highest volumes, though thin-body variants face BIS water absorption compliance pressure.
- Porcelain Tiles:Kaolin-rich formulations fired above 1,200°C achieve sub-0.5% absorption and through-body color consistency. Mumbai and Delhi NCR commercial developments specify these for high-traffic flooring, displacing natural stone in architect-led projects.
- Unglazed Tiles:Single-fire clay bodies without surface glaze rely on body color and texture for aesthetics. Industrial warehousing applications in Gujarat industrial corridors favor these for abrasion resistance.
- Ceramic Mosaic:Small-format tesserae mounted on mesh backing enable complex pattern installation. Swimming pool and hospitality bathroom niches in Goa and Kerala coastal projects sustain fragmented demand.
Glazed tiles absorb the bulk of installed capacity; porcelain tiles are expanding most quickly.
End User:
Cost tier differentiation separates specification-driven commercial procurement from price-sensitive residential replacement cycles.
- Residential:Single-family and multi-unit housing dominates absolute tile consumption. Affordable housing vertical tenders under PMAY drive standard-grade glazed wall and floor tile procurement across tier-2 and tier-3 cities.
- Commercial:Retail, hospitality, and office developments command premium porcelain and large-format slabs. Direct manufacturer relationships are displacing dealer networks in Mumbai and Delhi NCR project specifications.
- Industrial:Factory floors, warehouses, and logistics centers prioritize unglazed and heavy-duty vitrified grades for load-bearing performance.
- Institutional:Hospitals, schools, and government buildings balance durability mandates with public tender pricing constraints.
Residential demand anchors volume throughput; commercial specification is climbing the fastest.
Surface Finish:
Application environment dictates finish selection, with slip resistance and maintenance regimes driving specification divergence.
- Polished:Diamond-abraded vitrified surfaces achieve mirror reflectance. Premium residential living areas and hotel lobbies in metropolitan markets specify these for aesthetic impact.
- Matte:Controlled surface roughness without high-gloss reflection. Commercial office and healthcare settings favor these for reduced glare and concealed wear patterns.
- Textured:Mechanical or digital impression creates tactile surface variation. External facade and landscape applications use these for weathering performance.
- Anti-slip:Surface micro-structuring achieves dynamic friction coefficients above 0.5. Wet-area mandates in commercial kitchens, pools, and healthcare facilities drive specification.
Polished finishes dominate value capture; anti-slip specification is gaining share fastest in regulated commercial environments.
Distribution Channel:
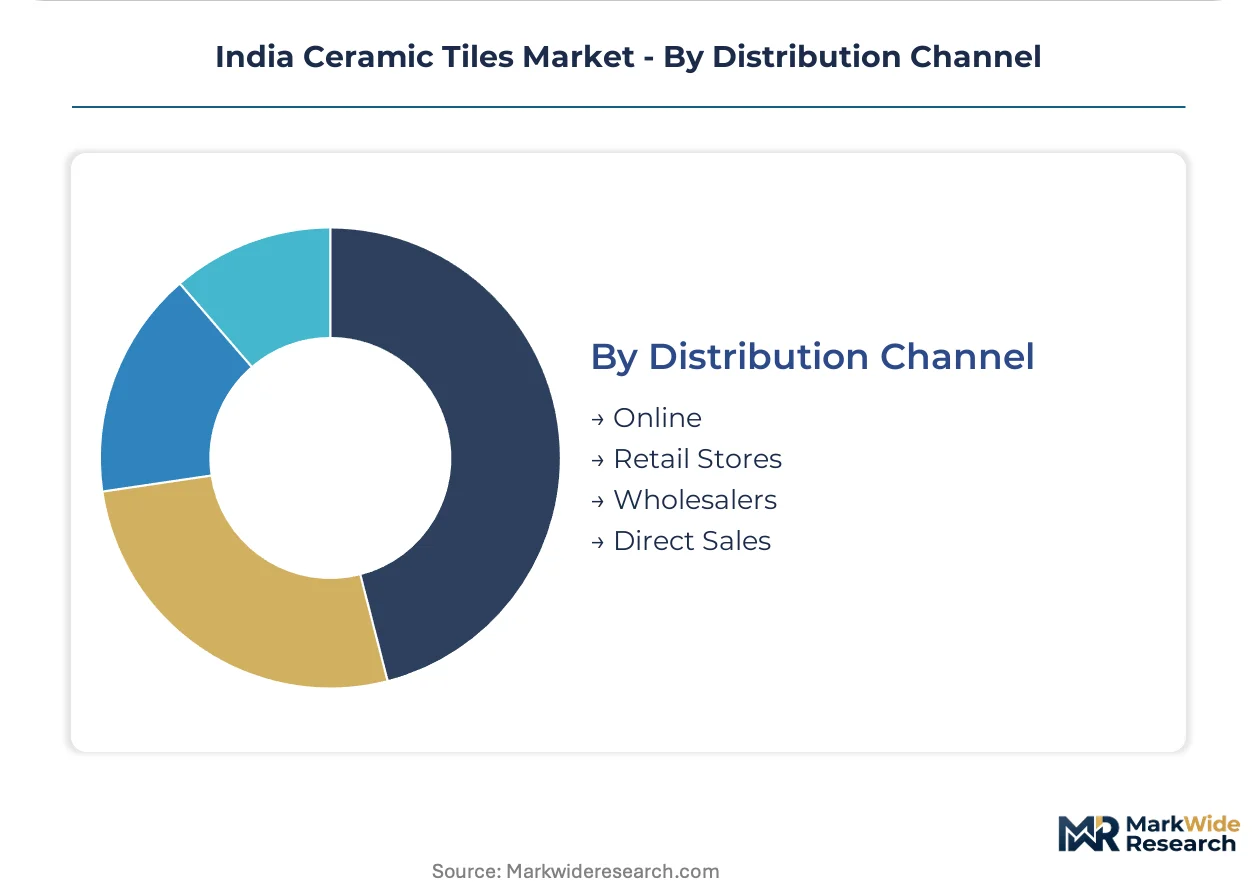
Geography and customer type fragment channel selection, with urban-rural divides shaping route-to-market economics.
- Retail Stores:Dealer networks spanning tier-2 and tier-3 cities handle replacement demand and homeowner selection. Rajasthan and Gujarat belt manufacturers maintain the densest coverage.
- Direct Sales:Project consultants and architect-specified developments negotiate factory-direct for large-format porcelain and slabs. Channel disintermediation concentrates in Mumbai and Delhi NCR commercial developments.
- Wholesalers:Bulk procurement for mass housing contractors and regional distributors. Price transparency pressures margins in standard-grade glazed segments.
- Online:Digital catalog platforms with sample logistics serve dispersed residential replacement demand. Penetration remains limited by tactile selection preferences and freight costs for heavy cargo.
Retail stores handle the deepest volume throughput; direct sales channels show the steepest expansion trajectory in premium specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEZ status and state-level industrial corridor incentives concentrate tile manufacturing capacity in Gujarat, while urban housing booms in Maharashtra and Delhi NCR absorb premium-grade output. State building codes and municipal tender specifications fragment procurement standards across major consumption zones.
Gujarat
The Morbi ceramic cluster hosts over 70 percent of domestic vitrified tile capacity, with continuous roller hearth kilns running on subsidized natural gas under state industrial policy. BIS certification laboratories in Ahmedabad reduce testing turnaround for export-bound manufacturers. Jamnagar and Rajkot secondary hubs are emerging for glazed wall tile production serving affordable housing contractors.
Maharashtra
Mumbai metropolitan redevelopment authority tenders specify large-format porcelain for commercial facade applications, displacing traditional dealer channels through direct manufacturer negotiation. MahaRERA compliance timelines compress material procurement cycles for residential developers. Thane and Pune industrial zones house distribution warehouses feeding western India replacement demand.
Delhi NCR
Gurugram and Noida commercial developments command specification premiums for through-body porcelain in hospitality and retail fit-outs. Delhi Development Authority affordable housing mandates standard-grade glazed tiles, creating volume absorption for Rajasthan-sourced production. Faridabad logistics corridors enable just-in-time delivery for NCR construction schedules.
Rajasthan
Udaipur and Bhilwara feldspar mining belts supply raw material to Morbi kilns, though transport cost volatility affects input economics for unintegrated manufacturers. State mining department royalty revisions influence beneficiation plant investment decisions. Jaipur retail distribution networks penetrate tier-3 markets in Madhya Pradesh and Uttar Pradesh.
Andhra Pradesh
Guntur and Krishna district zircon sand deposits support opacifier production for glazed tile surface chemistry. AP Industrial Infrastructure Corporation land allotments attract ceramic ancillary units to Visakhapatnam corridor. Vijayawada construction activity absorbs mid-tier vitrified grades for residential flooring replacement cycles.
India Ceramic Tiles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated producers capturing premium specification while toll manufacturers serve mass housing tenders. The vendor base organizes around three archetypes: kiln-integrated full-liners controlling raw material beneficiation, design-led specialists commanding architect relationships, and volume-focused exporters leveraging Morbi cluster surplus. Competitive maneuvering centers on backward integration into Rajasthan feldspar mining and automated press line deployment under PLI scheme subsidies.
Among integrated Gujarat-based producers, Kajaria Ceramics and Somany Ceramics occupy positions exemplifying scale-driven cost leadership through captive vitrified capacity. Orient Bell Tiles represents the design-specialist archetype, anchoring architect-specified procurement channels in Mumbai and Delhi NCR commercial developments. These three manufacturers illustrate how competitive positioning diverges between volume throughput optimization and specification premium capture.
| Leading Market Players |
|---|
| RAK Ceramics |
| Metrocity Tiles |
| Kajaria Ceramics |
| Somany Ceramics |
| Nitco |
| Orient Bell Tiles |
| Sakar Granito |
| Varmora Granito |
| Simpolo Vitrified |
| Others |
Value Chain & Pricing Dynamics
Feldspar and zircon procurement costs cascade through Morbi cluster pricing tiers, with integrated manufacturers capturing margin buffers against Rajasthan mining royalty volatility while toll producers absorb spot market swings in standard-grade glazed output.
Pricing Analysis
Short lead-time premiums command pricing power in architect-specified commercial projects, where Mumbai and Delhi NCR developers pay markups for 48-hour pattern customization via single-pass digital inkjet systems. Three-tier pricing structure across premium porcelain, standard vitrified, and economy glazed levels stratifies by BIS certification grade and through-body density. Pricing pressure stems from CNG-fired kiln energy volatility compressing margins in continuous roller hearth operations. Mass housing contractors under PMAY tenders exhibit highest price sensitivity; specification-led commercial buyers show lowest.
Supply Chain Analysis
Direct-to-project channels handle architect-specified porcelain slab demand, bypassing distributor markups in Mumbai and Delhi NCR commercial developments. Supply concentrates in Gujarat's Morbi belt and Rajasthan's Udaipur-Bhilwara mining corridors, with Andhra Pradesh zircon deposits feeding surface chemistry inputs. Raw material dependencies rest on feldspar beneficiation, zircon opacifiers, and kaolin formulations. Single-source vulnerability concentrates in Rajasthan feldspar mining belts exposed to state royalty revisions. Distribution runs through tier-2 retail networks for replacement demand and factory-direct negotiation for premium specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kiln automation skill scarcity across Gujarat technical institutes constrains capacity expansion, propping pricing power for manufacturers with captive process engineering capabilities.
For Market Incumbents: To counter design-led specialists eroding specification premiums, Kajaria and Somany must deepen captive feldspar beneficiation in Rajasthan mining belts and deploy PLI-subsidized automated press lines to sustain cost leadership in vitrified grades. For New Entrants and Emerging Players: Enter via thin porcelain large-format slab production for commercial facade applications, where channel disintermediation opens direct manufacturer relationships. Target tier-3 city retail penetration in Uttar Pradesh and Madhya Pradesh secondary markets, leveraging modular inkjet printhead configurations for rapid pattern iteration against premium brand archives. For Investors and Strategic Acquirers: BIS certification laboratory expansion in Ahmedabad is the leading indicator that compliance infrastructure is scaling to match Morbi cluster output growth, signaling viable long-term positioning. Acquire kiln-integrated full-liners with backward integration into Rajasthan feldspar mining and automated firing curve optimization systems. Watch for DGFT export facilitation momentum to Middle East and African markets as volume outlet inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feldspar Mining | Captive Rajasthan beneficiation plants buffer Morbi manufacturers against state royalty volatility and supply disruption. |
| Automated Press Line Deployment | PLI scheme subsidies accelerate Gujarat and Rajasthan plant modernization for BIS compliance and energy efficiency. |
| Direct-to-Project Channel Development | Architect-specified procurement in Mumbai and Delhi NCR commercial developments bypasses traditional dealer markups. |
| Export Corridor Activation | DGFT trade facilitation opens Middle East and African volume outlets for Morbi-cluster surplus beyond domestic absorption. |
| Digital Inkjet Capability Expansion | Single-pass printing systems compress pattern development cycles and decentralize design authority to plant-floor teams. |
Study Parameters
Document review covered BIS certification protocols, PLI scheme implementation guidelines, and state mining department royalty schedules, complemented by interviews with Morbi cluster plant managers, Rajasthan feldspar beneficiation operators, Mumbai project consultants, and Delhi NCR architect-specification leads. Secondary sources included DGFT trade facilitation circulars, Gujarat Industrial Development Corporation SEZ documentation, and customs export data for ceramic tile shipments. Bottom-up capacity utilization estimates from Morbi kiln counts were triangulated against top-down affordable housing tender absorption projections.
Segment-level value and volume trajectories across the projection horizon were derived from product-grade firing temperature differentials, end-user cost tier stratification, and surface finish specification premiums. The analytical framework modeled porcelain versus glazed versus unglazed mix shifts, residential-commercial-industrial end-use splits, and distribution channel evolution. CAGRs were computed from installed capacity expansion timelines, PMAY tender pipeline visibility, and export corridor activation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BIS certification timeline extensions, CNG price volatility spikes, and feldspar mining lease renewal delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Asphalt Shingles Market