
 Refining Industry Automation and Software Market | 2026-2036
Refining Industry Automation and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Refining Industry Automation and Software Market Analytics
Cloud-native control architectures and edge-computing integration are reshaping how refining automation systems are deployed and maintained across downstream facilities. Honeywell Process Solutions leverages its Experion platform to anchor digital twin implementations at major North American refineries. ABB competes through its Ability Genix suite, which extends predictive analytics across hydrocracker and coker units. Siemens dominates European retrofit cycles with its SPPA-T3000 distributed control architecture, sustaining long-term service contracts with integrated energy majors.
Refining Industry Automation and Software encompasses the engineered systems, algorithms, and hardware interfaces that govern continuous process operations in crude distillation, catalytic reforming, and hydrotreating units, typically executing control loops with sub-second scan rates and SIL-rated safety integrity. Its primary commercial purpose is to maximize throughput yield while constraining energy intensity and unplanned downtime in capital-intensive processing environments. Distributed Control Systems command the largest installed base across mature refineries, though Advanced Process Control applications are expanding fastest as margin-thin operators pursue real-time optimization. Safety Instrumented Systems retain the highest margin pools due to mandatory IEC 61511 certification requirements and specialized engineering services.
The EPA enforces Risk Management Plan mandates that compel US refiners to maintain validated safety instrumented function documentation, while the EU F-Gas Regulation restricts fluorinated greenhouse gas use in refrigeration trains tied to process cooling. IEC 61508 and IEC 61511 standards govern functional safety lifecycle management, creating compliance-driven replacement cycles for legacy relay-based protection systems. Stakeholders must monitor how carbon border adjustment mechanisms and evolving methane emissions protocols reshape capital allocation between brownfield automation upgrades and greenfield digital-native refinery designs.
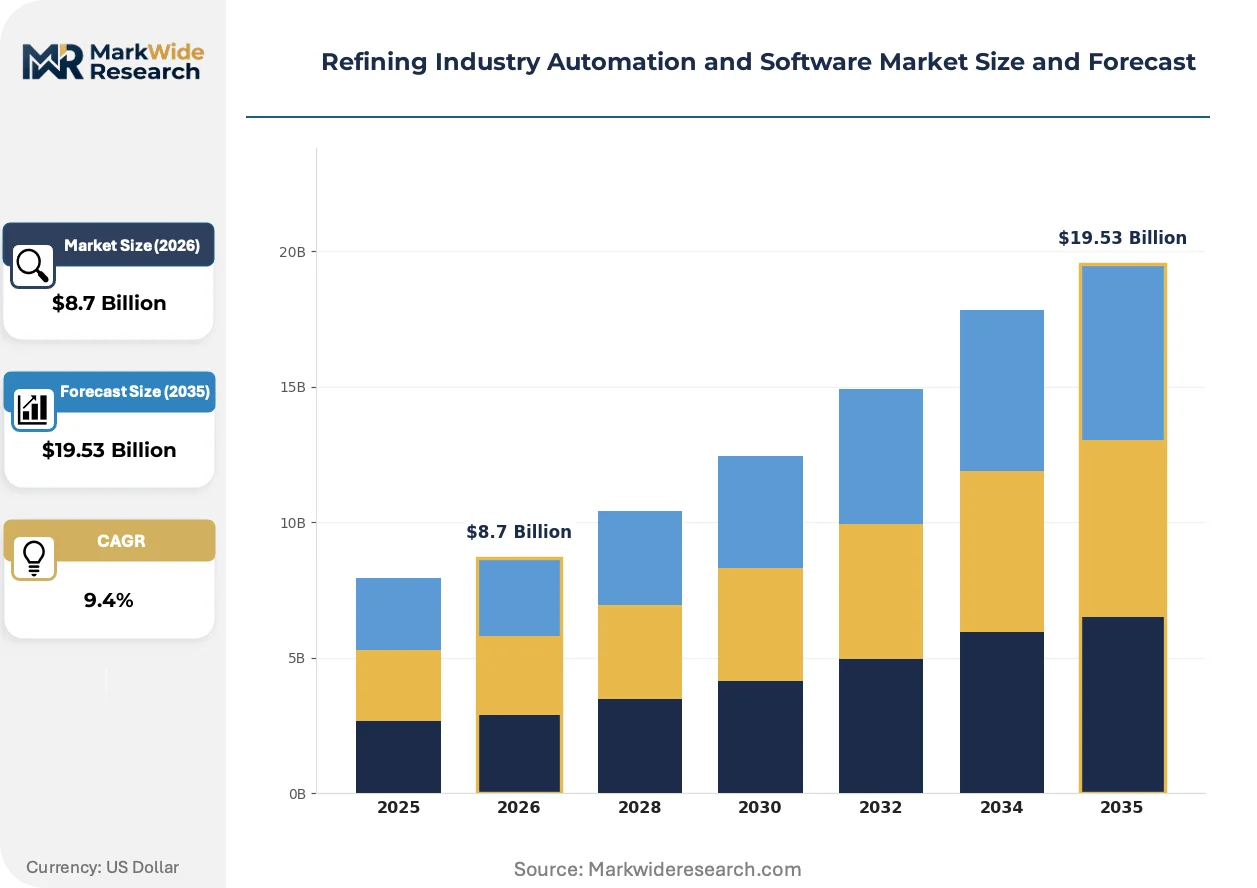
Market Dynamics
Retrofit mandates under the EU F-Gas Regulation are compressing replacement cycles for legacy relay-based protection architectures across European downstream complexes.
Growth Catalysts
- Carbon border adjustment mechanisms:European refiners face escalating compliance costs that accelerate capital allocation toward emission-monitoring automation suites.
- Real-time optimization demand:Margin-thin hydrocracker and coker operators pursue Advanced Process Control applications to maximize throughput yield.
- Edge-computing integration:Cloud-native architectures enable predictive maintenance deployments without full infrastructure replacement.
Market Restraints
- Specialized engineering scarcity:IEC 61511 certification requirements constrain qualified safety system integrator availability.
- Silicon component volatility:Semiconductor supply concentration in East Asian foundries creates lead-time uncertainty for controller hardware.
- Legacy architecture lock-in:Proprietary DCS protocols impede modular upgrade paths at mature North American refineries.
Strategic Opportunities
- India's petrochemical expansion:Reliance Industries and Indian Oil Corporation greenfield complexes present untapped demand for integrated automation platforms.
- Digital twin convergence:Virtual commissioning of catalytic reforming units reduces physical testing requirements and commissioning timelines.
- API 754 performance indicator adoption:Process safety event reporting mandates in the US create aftermarket analytics service revenue streams.
Industry Challenges
- Control systems cybersecurity:IT/OT network convergence exposes downstream operators to ransomware targeting SCADA infrastructure.
- Functional safety documentation:EPA Risk Management Plan validation requirements demand sustained engineering resource commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refining Industry Automation and Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Distributed Control Systems, Supervisory Control Systems, Advanced Process Control, Safety Instrumented Systems Application: Process Optimization, Production Planning, Asset Management, Energy Management End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Oil & Gas Companies Product Type: Software Solutions, Automation Hardware, Control Systems, Monitoring Tools |
| Companies Covered | Honeywell Process Solutions, ABB, Siemens, Emerson, Schneider Electric, Rockwell Automation, Yokogawa Electric, Endress+Hauser, KROHNE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refining Industry Automation and Software Market Evolving Landscape
Automation architecture is fragmenting between edge-deployed intelligence and centralized cloud analytics, forcing vendors to recalibrate platform roadmaps.
Artificial intelligence-based predictive analytics is hybridizing traditional alarm management with probabilistic failure forecasting. Major integrated energy majors deploy these tools across crude distillation trains. The technology is hybridizing maintenance scheduling from calendar-based intervals toward condition-triggered interventions.
The EU F-Gas Regulation restricts fluorinated greenhouse gas deployment in refrigeration trains tied to process cooling. European refiners must retrofit or replace legacy cooling control loops. German chemical-industrial clusters around Ludwigshafen and Leverkusen are driving large-scale distributed control system deployments to meet phased compliance deadlines.
After-sales service unbundling is fragmenting long-term vendor contracts into modular software subscriptions and on-demand engineering support. Downstream operators in complex refining complexes now procure automation platforms through separate hardware, license, and service line items. This pattern concentrates in North American independent refiners seeking operational expenditure flexibility over capital-intensive turnkey agreements.
Refining Industry Automation and Software Market Segmentation
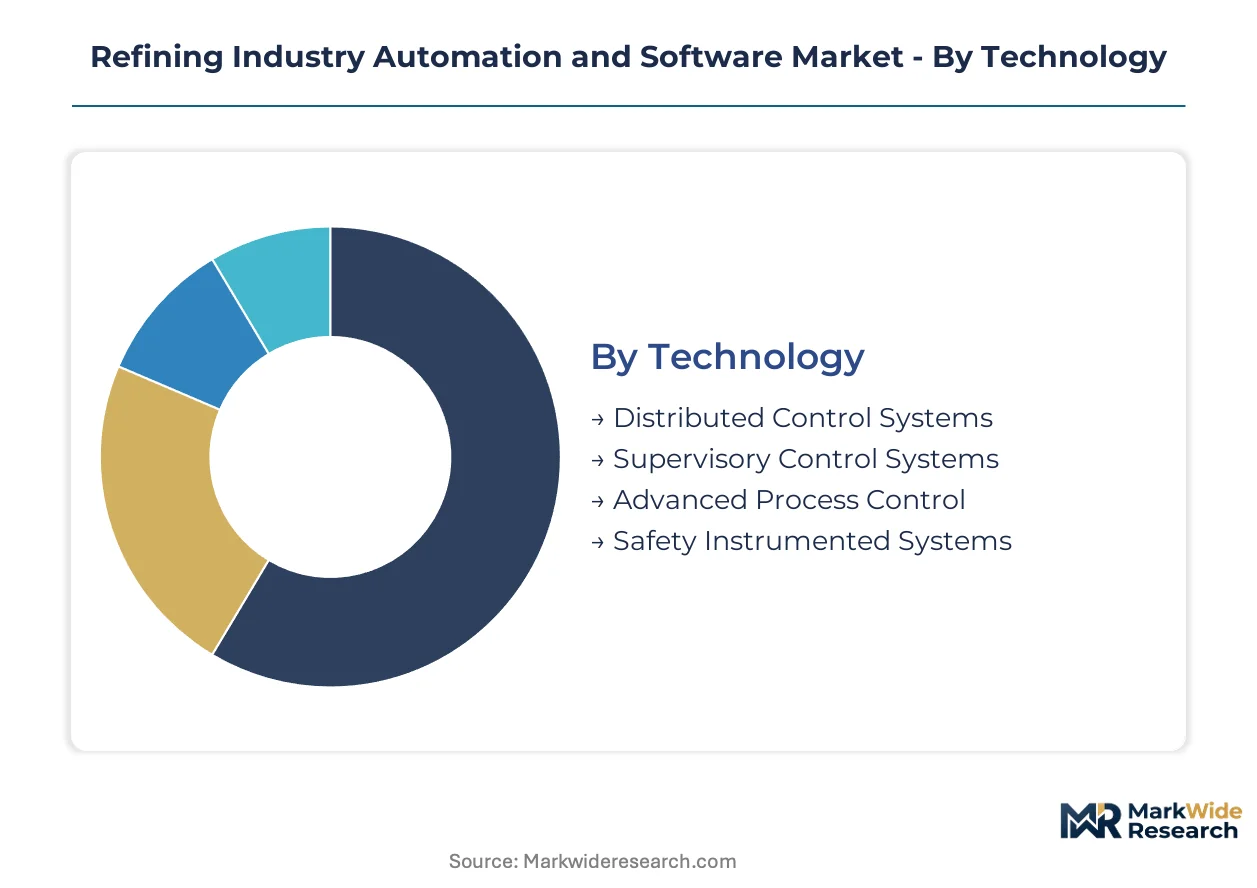
Segmentation in refining automation reveals how capital allocation splits between legacy infrastructure preservation and digital-native architectures. Procurement patterns diverge sharply between integrated majors pursuing full-platform overhauls and independent operators favoring modular edge deployments.
Technology:
Technology segmentation tracks control architecture maturity from centralized legacy systems to distributed intelligence layers.
- Distributed Control Systems:Hierarchical control architectures coordinate continuous process operations through redundant controller networks with millisecond scan reliability. German refineries around Ludwigshafen deploy Siemens SPPA-T3000 architectures to meet EU F-Gas Regulation retrofit deadlines.
- Advanced Process Control:Multivariable model predictive algorithms optimize hydrocracker and coker unit yield in real-time against shifting crude slates. Margin-thin North American independent refiners concentrate procurement here to maximize throughput without infrastructure replacement.
- Supervisory Control Systems:SCADA layers provide human-machine interface visibility across geographically distributed tank farms and pipeline networks.
- Safety Instrumented Systems:SIL-rated protection loops execute emergency shutdown functions per IEC 61511 certification mandates.
Distributed Control Systems hold installed capacity. Advanced Process Control is rotating up the share rankings.
Application:
Application segmentation reflects where automation delivers measurable margin improvement versus compliance documentation.
- Process Optimization:Real-time yield maximization algorithms adjust distillation cut points and reactor severity based on laboratory information management system feedback. US Gulf Coast refiners facing EPA Risk Management Plan mandates concentrate investment here to demonstrate continuous operational improvement.
- Asset Management:Predictive maintenance platforms integrate vibration monitoring, oil analysis, and thermal imaging into unified equipment health dashboards. European downstream complexes prioritize this application to extend catalyst change-out intervals and reduce unplanned turnaround frequency.
- Production Planning:Linear programming models optimize crude slate selection against product liftings and inventory constraints.
- Energy Management:Steam and fuel gas balancing systems reduce carbon intensity per barrel processed.
Process Optimization commands maintenance budgets. Asset Management is climbing the fastest as reliability-centered maintenance displaces calendar-based interventions.
End User:
End user segmentation captures divergence between integrated majors with captive engineering capacity and specialty operators outsourcing system integration.
- Refineries:Complex downstream processing facilities with catalytic reforming, hydrotreating, and conversion units requiring sub-second control loop execution. Indian Oil Corporation greenfield complexes represent expanding demand for integrated automation platforms.
- Petrochemical Plants:Olefins and aromatics producers with extended refrigeration trains subject to EU F-Gas Regulation compliance cycles.
- Chemical Manufacturers:Ludwigshafen and Leverkusen cluster operators deploying large-scale distributed control architectures.
- Oil & Gas Companies:Upstream-downstream integrated majors with standardized global automation specifications.
Refineries anchor procurement volume. Petrochemical Plants are gaining share fastest on ethylene cracker expansion cycles.
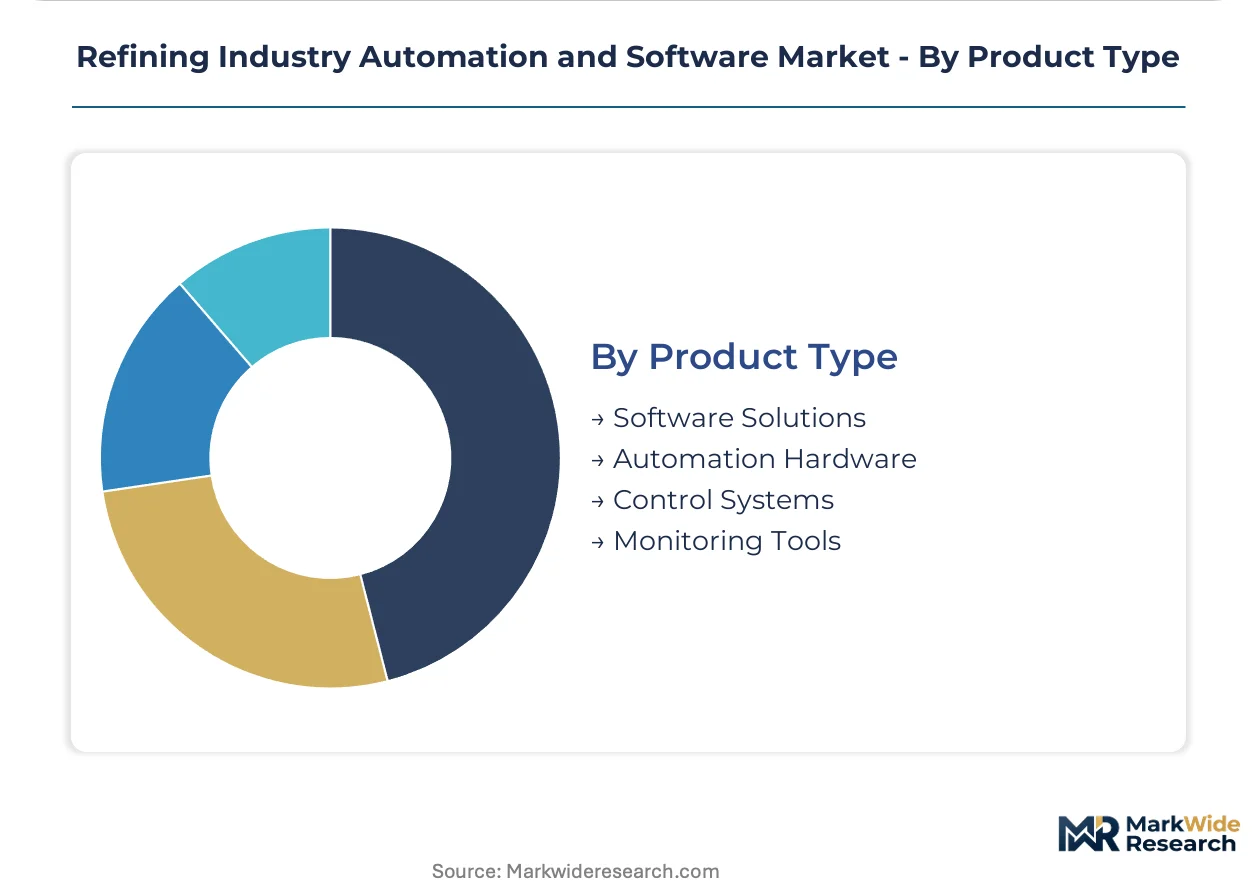
Product Type:
Product type segmentation tracks unbundling of traditional turnkey contracts into separable hardware, license, and service line items.
- Software Solutions:Cloud-native analytics platforms, digital twin environments, and subscription-based optimization algorithms. North American independent refiners favor operational expenditure flexibility here over capital-intensive perpetual licenses.
- Automation Hardware:Controllers, I/O modules, and field instrumentation with semiconductor supply concentration creating lead-time uncertainty.
- Control Systems:Integrated DCS and PLC platforms with proprietary protocols impeding modular upgrade paths.
- Monitoring Tools:Edge-deployed sensors and wireless vibration transmitters enabling predictive maintenance without full infrastructure replacement.
Software Solutions are expanding most quickly on subscription monetization. Automation Hardware retains the largest revenue pool on replacement cycle dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports substantial refining automation engineering services while importing specialized safety system components from European suppliers. Germany and China maintain near-autarky in distributed control system manufacturing. India's petrochemical buildout is absorbing Korean and Japanese hardware imports at accelerating rates.
United States
Gulf Coast refiners around Houston and Corpus Christi are retrofitting catalytic reforming units with edge-computing predictive maintenance platforms. The EPA enforces Risk Management Plan mandates that compel validated safety instrumented function documentation. Complex downstream facilities in Texas and Louisiana concentrate procurement of Advanced Process Control applications to maximize hydrocracker throughput against volatile crude differentials.
Germany
Chemical-industrial clusters around Ludwigshafen and Leverkusen are driving large-scale distributed control system deployments to meet EU F-Gas Regulation retrofit deadlines. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in refrigeration trains tied to process cooling. Siemens anchors long-term service contracts with integrated energy majors across the Rhine-Ruhr industrial corridor.
China
State-owned refining giants are deploying domestic distributed control architectures in greenfield complexes along the eastern seaboard. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate emission-monitoring automation procurement. Shandong Province's independent teapot refiners concentrate demand for modular edge-computing solutions that avoid full infrastructure replacement.
India
Reliance Industries and Indian Oil Corporation greenfield complexes present expanding demand for integrated automation platforms with sub-second control loop execution. The Bureau of Indian Standards governs functional safety certification requirements for imported safety instrumented systems. Gujarat's Jamnagar refining hub anchors procurement volume for predictive analytics suites targeting catalyst change-out optimization.
Saudi Arabia
Saudi Aramco's downstream expansion at Jazan and Yasref complexes is absorbing European and American safety system engineering services. The Saudi Food and Drug Authority regulates process safety documentation for petrochemical exports to European markets. The Eastern Province's Jubail industrial city concentrates deployment of cloud-native digital twin environments for virtual commissioning of hydrotreating units.
Refining Industry Automation and Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated automation majors with captive hardware-software stacks, specialized safety system integrators with IEC 61511 certification moats, and emerging cloud-native analytics vendors unbundling traditional service contracts. Consolidation pressures are forcing mid-scale European controls specialists into strategic partnerships with Asian semiconductor suppliers. Capacity expansion concentrates in Indian engineering centers serving Middle Eastern greenfield complexes. Technology licensing agreements are proliferating between legacy DCS vendors and edge-computing startups.
Within the integrated automation tier, Honeywell Process Solutions, ABB, and Siemens occupy positions that exemplify divergent geographic anchoring strategies. Honeywell Process Solutions represents North American independent refiner preferences for operational expenditure flexibility through subscription monetization. ABB exemplifies European retrofit cycle dominance through predictive analytics suites extending across hydrocracker and coker units. Siemens anchors German chemical-industrial cluster relationships through long-term service contracts tied to SPPA-T3000 distributed control architectures.
| Leading Market Players |
|---|
| Honeywell Process Solutions |
| ABB |
| Siemens |
| Emerson |
| Schneider Electric |
| Rockwell Automation |
| Yokogawa Electric |
| Endress+Hauser |
| KROHNE |
| Others |
Value Network & Pricing Analysis
Semiconductor supply concentration in East Asian foundries determines both tiered pricing spreads across controller hardware and the geographic shape of automation system supply chains. Refinery operators face compressed margins when silicon component volatility coincides with mandatory IEC 61511 certification requirements for safety instrumented systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command substantial markups for SIL-rated safety integrity certification and integrated digital twin environments. Cost compression in standard controller hardware is intensifying because semiconductor supply bottlenecks extend lead times without proportional value capture. Independent refiners in North America exhibit the highest price sensitivity, favoring subscription-based software solutions over capital-intensive perpetual licenses.
Supply Chain Analysis
Taiwanese and South Korean foundries hold dominant capacity for industrial controller semiconductors. German and Chinese distributed control system manufacturers draw from East Asian silicon suppliers for I/O modules and processor cores. Single-source vulnerability in advanced node production creates exposure to tariff escalation or export restriction scenarios. Distribution runs through authorized system integrators with IEC 61511 certification, limiting direct procurement flexibility for end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refining automation sector sits in early-cycle expansion as carbon border compliance obligations force European retrofit investments and Indian greenfield complexes accelerate procurement. Edge-computing integration and cloud-native architectures are displacing legacy capital-intensive deployment models.
For Market Incumbents: Pre-empt modular software vendors by unbundling long-term service contracts into separable subscription tiers. Acquire edge-computing specialists with predictive analytics capabilities to defend against cloud-native entrants targeting North American independent refiners. Deepen captive hardware-software integration to maintain margin pools in safety instrumented systems.
For New Entrants and Emerging Players: India's petrochemical expansion presents the most penetrable geography for integrated automation platforms without incumbent service contract lock-in. Target modular edge deployments at Shandong Province teapot refiners seeking operational expenditure flexibility. Pursue partnership routes with Korean and Japanese hardware suppliers to bypass semiconductor supply constraints.
For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by compressing replacement cycles for legacy protection architectures. Position for five-to-ten year viability through specialized safety system integrators with IEC 61511 certification moats. Monitor carbon border adjustment mechanism implementation timelines as the critical inflection signal for capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual commissioning reduces physical testing requirements at Saudi Aramco's Jazan complex. |
| Backward Integration into Edge Hardware | Captive sensor production insulates against semiconductor lead-time volatility from East Asian foundries. |
| Long-term Service Contract Unbundling | Modular subscriptions attract North American independent refiners seeking operational expenditure flexibility. |
| Joint Venture with Indian Engineering Centers | Local capacity expansion captures Reliance Industries and Indian Oil Corporation greenfield demand. |
| Green Certification Program Alignment | EU F-Gas Regulation compliance positioning secures German chemical-industrial cluster retrofit contracts. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with downstream automation stakeholders and secondary validation across regulatory and trade databases. Refinery operations directors, safety system integrators, distributed control system procurement leads, and petrochemical plant engineering heads contributed structured input. Secondary sources encompassed EPA Risk Management Plan filings, EU F-Gas Regulation implementation documentation, IEC 61508 and IEC 61511 certification registries, and customs trade data for industrial controller imports. Bottom-up project pipeline assessment and top-down sector expenditure analysis were triangulated to establish market sizing.
Forecast inputs considered technology deployment model, end-user facility scale, regional regulatory framework stringency, and integration complexity tier across the projection horizon. Segmentation dimensions modeled included control architecture maturity, application purpose, end-user category, and product type unbundling pattern. CAGRs were derived from weighted scenario analysis incorporating adoption curve penetration rates and replacement cycle compression factors. Industry-specific inputs captured EU carbon border adjustment mechanism phase-in schedules and Indian petrochemical capacity expansion timelines.
Practitioners should monitor semiconductor supply chain disruption indicators and evolving methane emissions protocol stringency for early signals of forecast revision. Assumptions underlying projections reflect current regulatory implementation trajectories and technology adoption patterns. Quarterly review of safety system certification backlog data and carbon border mechanism enforcement thresholds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market