
 Asia Industry 4.0 Market | 2026-2036
Asia Industry 4.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Industry 4.0 Market Outlook
Carbon fiber-reinforced polymers is hardening as the preferred structural material for lightweight robotic arms and automated guided vehicle chassis across high-throughput assembly environments. Fanuc Corporation leverages its captive servo-motor foundry in Yamanashi Prefecture to sustain cost leadership in multi-axis articulated robots. Siemens AG anchors its Asia-Pacific software revenue through digital twin deployments in automotive paint shops and battery gigafactories. Yaskawa Electric Corporation differentiates via harmonic drive precision control in semiconductor wafer handling systems.
Asia Industry 4.0 encompasses cyber-physical production systems integrating industrial IoT sensors, edge computing nodes, and AI-driven process controllers to enable real-time manufacturing optimization with sub-millisecond latency requirements. Its primary commercial purpose is to synchronize heterogeneous equipment fleets across multi-site supply networks while minimizing unplanned downtime through predictive fault detection. Robotics and IoT Devices currently command the largest product-type revenue pools, though Machine Learning Platforms are expanding fastest as manufacturers shift from descriptive to prescriptive analytics. Within applications, Predictive Maintenance is maturing in process industries, while Quality Control vision systems are capturing margin concentration in pharmaceutical and electronics contract manufacturing.
China's MIIT enforces GB standards for industrial data security and interoperable equipment protocols, while Japan's METI coordinates JIS certification for collaborative robot safety specifications. South Korea's MFDS and KISA jointly regulate cybersecurity frameworks for smart medical device manufacturing, creating compliance-driven replacement cycles for legacy SCADA infrastructure. India's BIS and CEA are drafting mandatory energy-efficiency labeling for industrial automation equipment under the PLI scheme for advanced manufacturing. Stakeholders must weigh localization requirements against cross-border cloud architecture costs when selecting deployment models for multi-country production footprints.
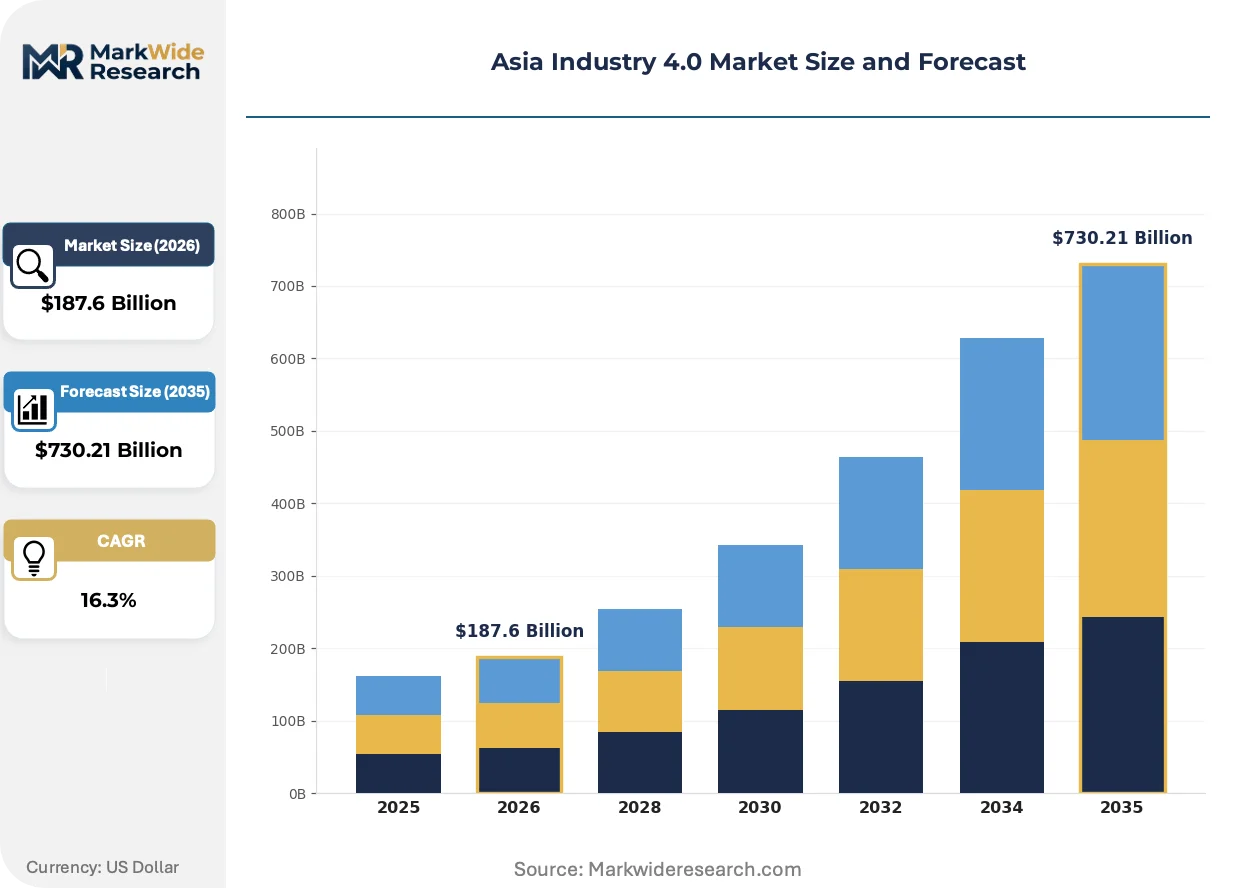
Market Dynamics
China's MIIT dual carbon mandates and Japan's METI Society 5.0 roadmap are compressing replacement cycles for legacy industrial equipment while accelerating capital deployment into cyber-physical production systems across East Asian manufacturing clusters.
Growth Catalysts
- MIIT Energy-Efficiency Mandates:China's dual carbon goals enforce GB standards for industrial data security and interoperable equipment protocols, forcing state-owned enterprises to modernize SCADA infrastructure.
- Semiconductor Packaging Demand:Precision electronics manufacturers in the Yangtze River Delta are subsidizing digital twin adoption to achieve sub-millisecond latency in wafer handling systems.
- Carbon Fiber-Reinforced Polymers:Lightweight robotic arm chassis materials enable higher throughput in automotive paint shops and battery gigafactories across South Korea's Gyeonggi Province.
Market Restraints
- Rare Earth Magnet Supply Concentration:Servo-motor manufacturers face input cost volatility from concentrated rare earth processing capacity in China's Inner Mongolia region.
- JIS Certification Timelines:Japan's METI collaborative robot safety specifications create regulatory friction, extending product launch cycles by 8-14 months for foreign entrants.
- Legacy SCADA Obsolescence:South Korea's MFDS cybersecurity frameworks for smart medical device manufacturing force premature replacement of installed industrial control systems.
Strategic Opportunities
- India PLI Scheme Expansion:BIS mandatory energy-efficiency labeling for industrial automation equipment creates first-mover advantage for vendors establishing local assembly under the advanced manufacturing incentive.
- Edge-AI Convergence:Machine learning platforms integrating with industrial IoT sensors enable prescriptive analytics in pharmaceutical contract manufacturing, displacing descriptive maintenance dashboards.
- Harmonic Drive Precision Control:Semiconductor wafer handling systems in Japan's Kumamoto region demand nanometer-scale positioning accuracy, opening premium pricing tiers for motion control specialists.
Industry Challenges
- Multi-Protocol Integration Complexity:Manufacturers struggle to synchronize heterogeneous equipment fleets across multi-site supply networks due to incompatible industrial Ethernet standards.
- Predictive Maintenance Talent Scarcity:Process industries in China's Pearl River Delta lack sufficient data engineers to operationalize AI-driven fault detection models at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Industry 4.0 Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $730.21 Billion |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotics, IoT Devices, Cloud Solutions, Machine Learning Platforms Application: Manufacturing Automation, Supply Chain Optimization, Predictive Maintenance, Quality Control End User: Manufacturers, Logistics Providers, Retailers, Agricultural Sector Technology: Artificial Intelligence, Big Data Analytics, Cybersecurity Solutions, Blockchain Technology |
| Companies Covered | Mitsubishi Electric Corporation, Fanuc Corporation, Yaskawa Electric Corporation, Omron Corporation, Yokogawa Electric Corporation, ABB Ltd, Siemens AG, Denso Corporation, Schneider Electric SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Industry 4.0 Market Strategic Shifts
Real-time manufacturing optimization is displacing batch-oriented production scheduling as edge computing nodes achieve sub-millisecond latency in cyber-physical systems across automotive and electronics assembly environments.
Digital twin technology is integrating physics-based simulation with live sensor feeds to enable virtual commissioning of automotive paint shops before physical deployment. Tier-1 suppliers in Japan's Aichi Prefecture are adopting these systems at compressed 18-month refresh cycles. This convergence is integrating design validation with operational execution, collapsing traditional pilot-to-production timelines.
Japan's METI JIS certification for collaborative robot safety specifications now mandates force-limiting controls and emergency stop interoperability. Industrial equipment vendors must redesign control architectures to satisfy these requirements. Automotive subcontractors in Toyota City and Osaka are prioritizing certified systems to maintain OEM supplier status.
Pharmaceutical contract manufacturers are unbundling after-sales service from equipment procurement, shifting to outcome-based uptime guarantees. Electronics assembly firms in South Korea's Incheon Free Economic Zone now specify availability contracts rather than capital purchase agreements. This rotation is most visible in semiconductor packaging facilities where downtime costs exceed $50,000 per hour.
Asia Industry 4.0 Market Segmentation
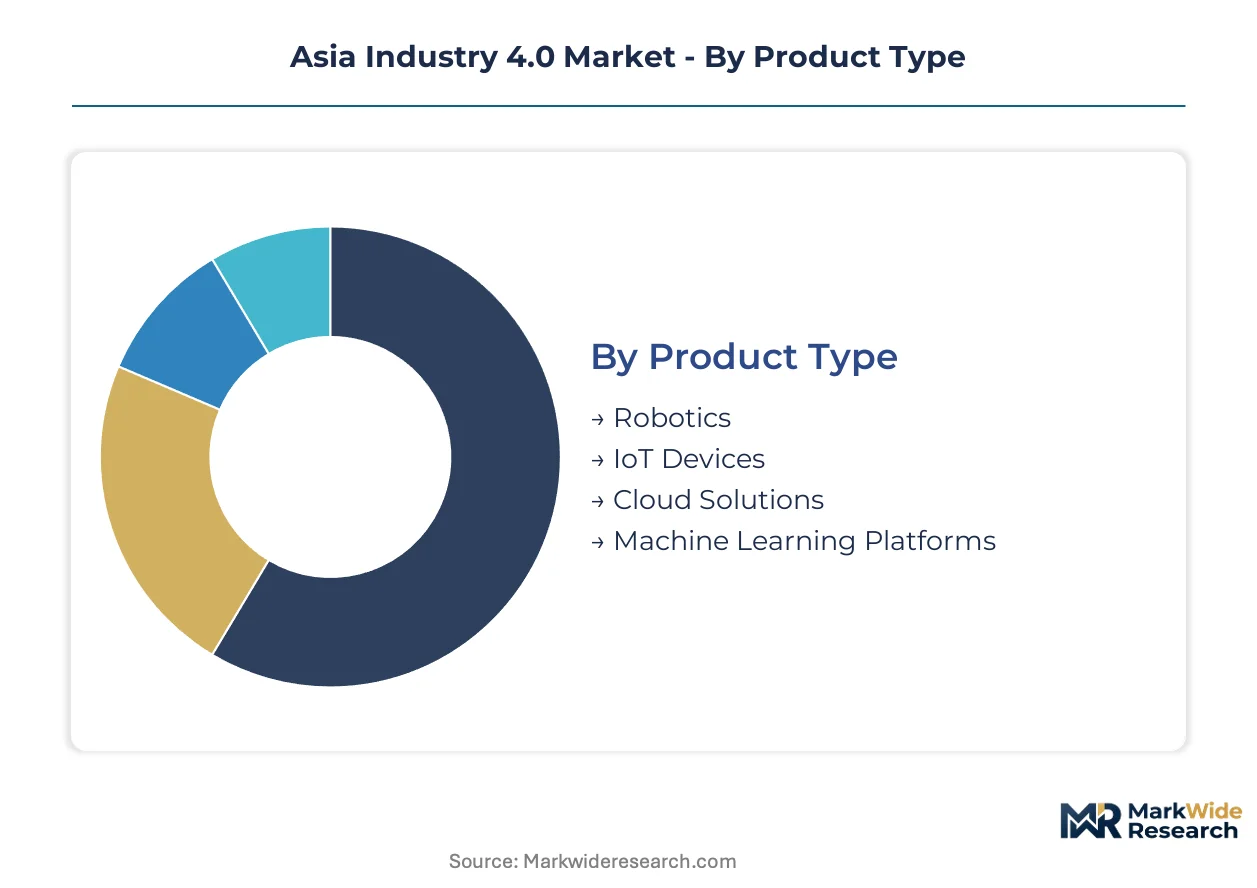
Asia Industry 4.0 deployment patterns diverge sharply across product types and end-use verticals, with MIIT cybersecurity certifications and METI JIS safety standards creating divergent compliance burdens that reshape procurement priorities. Manufacturers must map segment-specific regulatory requirements against operational maturity to optimize capital allocation across heterogeneous technology stacks.
Product Type:
MIIT GB standards for industrial data security and METI JIS collaborative robot certifications impose tiered compliance costs, with cloud-connected systems facing mandatory encryption protocols while edge-deployed hardware navigates electromagnetic compatibility testing.
- Robotics:Multi-axis articulated systems with carbon fiber-reinforced polymer chassis dominate automotive paint shops and battery gigafactories. Fanuc Corporation's Yamanashi servo-motor foundry supplies precision actuators to Toyota City subcontractors facing JIS force-limiting control mandates. Demand concentrates in South Korea's Gyeonggi Province for lightweight high-throughput assembly.
- IoT Devices:Industrial sensor networks with sub-millisecond latency specifications enable real-time equipment synchronization. Yangtze River Delta semiconductor packaging facilities subsidize edge node deployment under provincial digital twin initiatives. MIIT interoperability protocols require GB-certified protocol gateways for cross-vendor integration.
- Cloud Solutions:Cross-border data architecture faces localization requirements under China's Cybersecurity Law and South Korea's KISA frameworks.
- Machine Learning Platforms:Prescriptive analytics engines displace descriptive dashboards in pharmaceutical contract manufacturing.
Leading the category by volume: Robotics. Growing fastest: Machine Learning Platforms.
Application:
Cost tier stratification separates mission-critical uptime guarantees from pilot-scale deployments, with semiconductor packaging facilities absorbing premium pricing for availability contracts exceeding $50,000 per hour downtime exposure.
- Manufacturing Automation:Cyber-physical production systems integrate heterogeneous equipment fleets across multi-site supply networks. Japan's Aichi Prefecture tier-1 suppliers compress refresh cycles to 18 months for virtual commissioning of paint shop digital twins. China's Pearl River Delta faces talent scarcity in AI-driven fault detection operationalization.
- Supply Chain Optimization:Real-time inventory synchronization demands edge-AI convergence with legacy ERP systems. South Korea's Incheon Free Economic Zone electronics assemblers specify outcome-based uptime guarantees rather than capital purchase agreements.
- Predictive Maintenance:Process industries in China's Inner Mongolia rare earth processing clusters lack sufficient data engineering capacity.
- Quality Control:Vision systems with nanometer-scale positioning capture margin concentration in Kumamoto semiconductor wafer handling.
Manufacturing Automation commands the largest deployment base. Quality Control climbs the fastest as pharmaceutical and electronics contract manufacturers prioritize defect prevention over downstream remediation.
End User:
Customer type segmentation reflects divergent digital maturity, with state-owned enterprises navigating MIIT dual carbon mandates while private logistics operators prioritize rapid ROI from modular edge deployments.
- Manufacturers:Automotive OEMs and precision electronics producers anchor demand for certified collaborative robot systems. METI JIS specifications force 8-14 month launch cycle extensions for foreign entrants lacking established Japan testing partnerships.
- Logistics Providers:Automated guided vehicle fleets in China's Yangtze River Delta distribution hubs require GB-standard industrial data security compliance.
- Retailers:Warehouse robotics adoption concentrates in South Korea's metropolitan fulfillment networks.
- Agricultural Sector:Smart greenhouse deployments in India's PLI scheme advanced manufacturing corridors face BIS energy-efficiency labeling requirements.
Manufacturers generate the dominant revenue pool. Logistics Providers expand most quickly as e-commerce fulfillment density accelerates automated material handling investment.
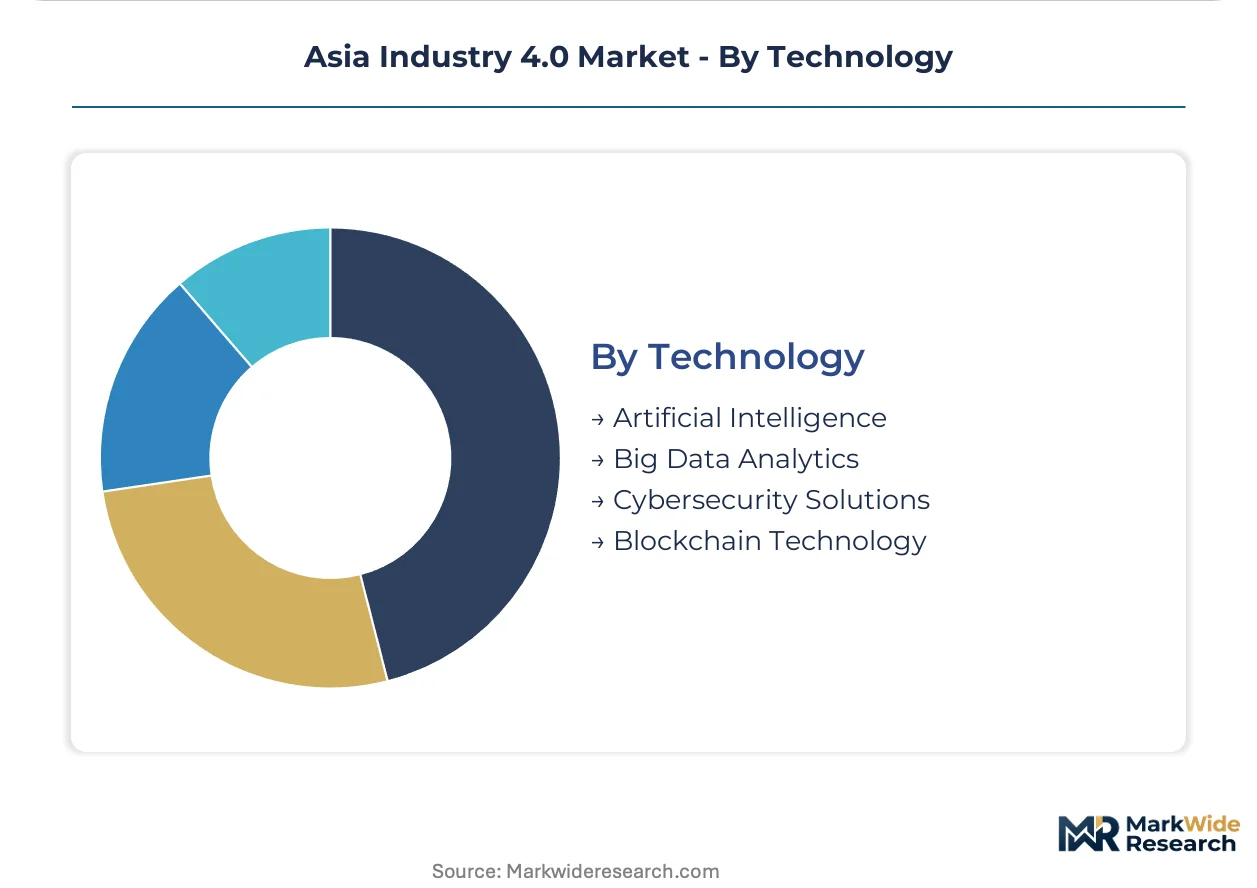
Technology:
Supply concentration for core intellectual property shapes segment accessibility, with AI training infrastructure concentrating among hyperscale cloud operators while cybersecurity solutions fragment across specialized industrial vendors.
- Artificial Intelligence:Edge inference engines with prescriptive analytics capabilities displace centralized cloud processing in pharmaceutical batch manufacturing. Japan's Kumamoto semiconductor cluster demands harmonic drive precision control integration with AI-driven positioning systems.
- Big Data Analytics:Physics-based simulation platforms enable virtual commissioning before physical deployment. China's MIIT enforces data localization for industrial analytics processing state-owned enterprise operational telemetry.
- Cybersecurity Solutions:SCADA infrastructure replacement cycles accelerate under South Korea's MFDS medical device manufacturing frameworks.
- Blockchain Technology:Supply chain provenance tracking pilots concentrate in India's pharmaceutical export corridors.
Artificial Intelligence captures the steepest expansion trajectory. Big Data Analytics maintains the largest installed base across automotive and electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of Industry 4.0 deployment volume, with provincial governments in the Yangtze River Delta and Pearl River Delta subsidizing digital twin adoption in precision electronics facilities. Japan and South Korea anchor high-value automation demand through METI and MFDS regulatory frameworks. India's PLI scheme for advanced manufacturing is accelerating capital deployment into smart factory systems across its industrial corridors.
China
MIIT dual carbon mandates and GB standards for industrial data security are compressing replacement cycles for legacy SCADA infrastructure in state-owned enterprises. Provincial governments in Jiangsu and Zhejiang subsidize digital twin adoption for semiconductor packaging facilities. The Yangtze River Delta manufacturing cluster absorbs the highest concentration of edge computing node deployment for sub-millisecond latency requirements.
Japan
METI Society 5.0 roadmap and JIS certification for collaborative robot safety specifications are extending product launch cycles by 8-14 months for foreign entrants. Tier-1 automotive suppliers in Aichi Prefecture compress refresh cycles to 18 months for virtual commissioning of paint shop digital twins. Toyota City and Osaka subcontractors prioritize force-limiting control systems to maintain OEM supplier status.
South Korea
MFDS and KISA joint cybersecurity frameworks for smart medical device manufacturing are accelerating replacement of installed industrial control systems. Electronics assemblers in the Incheon Free Economic Zone specify outcome-based uptime guarantees exceeding $50,000 per hour downtime exposure. Gyeonggi Province absorbs concentrated demand for lightweight robotic arm chassis in battery gigafactories.
India
BIS and CEA mandatory energy-efficiency labeling for industrial automation equipment under the PLI scheme creates first-mover advantage for vendors establishing local assembly. Advanced manufacturing corridors in Maharashtra and Gujarat face BIS compliance requirements for smart greenhouse and precision electronics deployments. State-level industrial policies are channeling subsidy flows toward cyber-physical production system adoption.
Vietnam
Electronics contract manufacturers are expanding automated guided vehicle fleets in northern industrial zones to serve relocated supply chain nodes from China. Provincial industrial parks around Hanoi and Hai Phong are absorbing spillover demand for industrial IoT sensor networks. Foreign direct investment flows are concentrating in precision electronics packaging facilities requiring GB-compatible protocol gateways.
Asia Industry 4.0 Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors commanding premium positioning in certified collaborative robot systems while component specialists capture margin in precision motion control. The vendor landscape organizes around three archetypes: captive foundry operators with in-house servo-motor production, software-anchored digital twin platforms, and precision mechanics specialists in harmonic drive systems. Competitive dynamics center on M&A activity for edge-AI capabilities and strategic partnerships to satisfy cross-border data localization requirements.
Among Japan-based integrated automation houses, Fanuc Corporation, Yaskawa Electric Corporation, and Mitsubishi Electric Corporation exemplify the captive manufacturing archetype. Fanuc's Yamanashi Prefecture operations represent vertical integration into precision actuator supply. Yaskawa occupies a position within harmonic drive precision control for semiconductor wafer handling. Mitsubishi Electric sits within the multi-protocol industrial Ethernet segment, navigating MIIT GB certification requirements for China market access.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| Omron Corporation |
| Yokogawa Electric Corporation |
| ABB Ltd |
| Siemens AG |
| Denso Corporation |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China's Inner Mongolia rare earth processing belt anchor upstream magnet supply, transmitting cost volatility downstream through concentrated servo-motor pricing while private-equity-rolled-up automation specialists in Japan enforce JIS certification premiums that stratify procurement budgets across East Asian manufacturing clusters.
Pricing Analysis
High-volume robotics deployments in South Korea's Gyeonggi Province absorb compressed margins on standardized articulated arms, while nanometer-precision motion control systems for Kumamoto semiconductor handling capture premium tiers. Three-tier pricing structure across certified-collaborative, standard-industrial, and economy-modular levels separates buyers by safety-critical application exposure. Cost compression in entry-level IoT sensor networks intensifies because Chinese provincial subsidies flood Yangtze River Delta procurement channels. State-owned enterprises under MIIT dual carbon mandates show lowest price sensitivity; contract electronics manufacturers in Vietnam's northern industrial zones exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs in Toyota City and Osaka force Fanuc Corporation and Yaskawa Electric Corporation to maintain qualified secondary actuator channels despite Yamanashi captive foundry dominance. Rare earth magnet processing concentrates in China's Inner Mongolia region, Japan's precision harmonic drive gear manufacturing, and Germany's industrial Ethernet component base. Neodymium-iron-boron magnets, carbon fiber-reinforced polymer feedstock, and edge-AI inference chips constitute critical input dependencies. Single-source vulnerability runs through concentrated rare earth separation capacity. Distribution runs through tier-1 system integrators with METI JIS certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
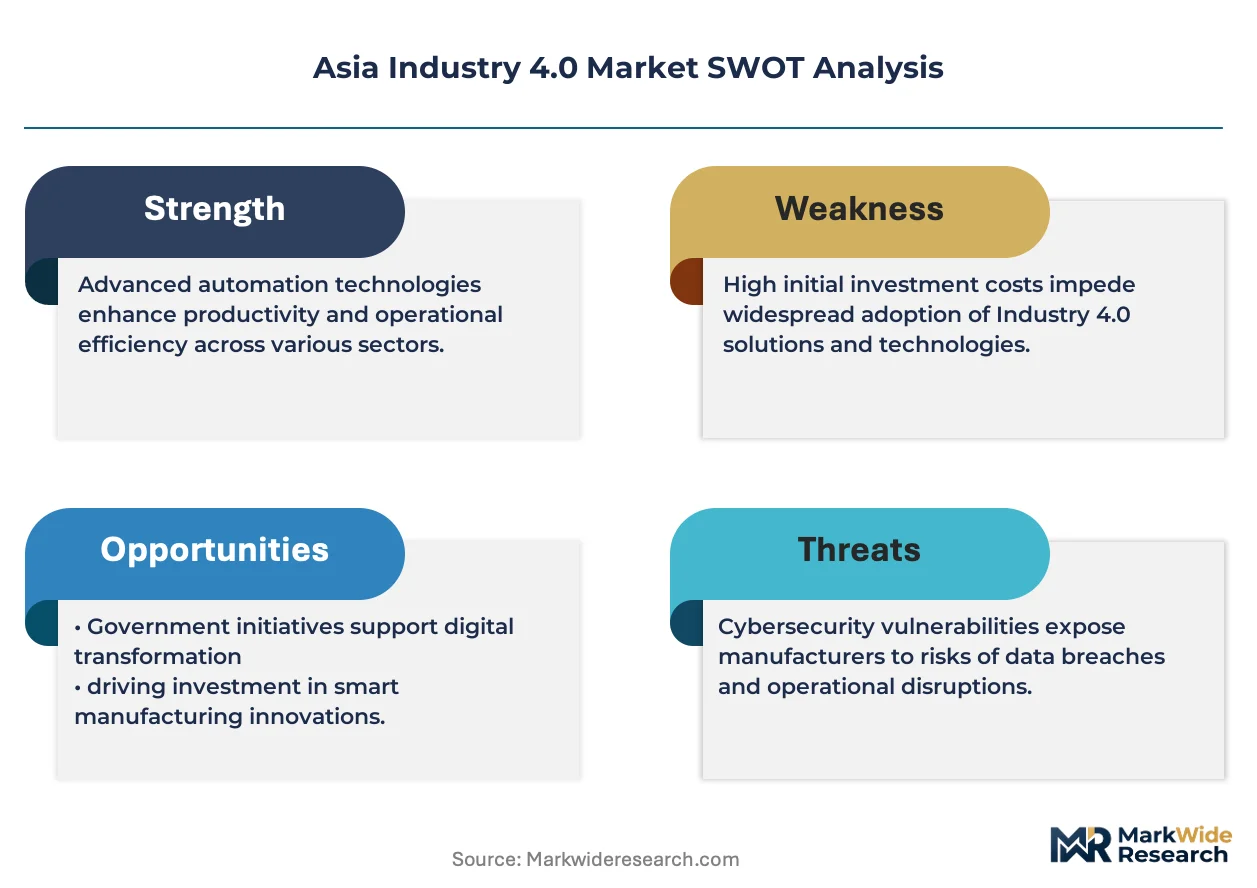
Asia Industry 4.0 sits in a technology-transition phase where prescriptive analytics platforms displace descriptive maintenance dashboards, compressing replacement cycles for legacy SCADA infrastructure across MIIT-regulated state-owned enterprises.
For Market Incumbents: Hedge against edge-AI specialist encroachment by deepening backward integration into servo-motor foundry capacity and securing METI JIS certification partnerships for collaborative robot safety specifications. Prioritize capacity positioning in India's PLI scheme corridors before BIS mandatory labeling locks in supplier relationships. For New Entrants and Emerging Players: Machine learning platforms with sub-millisecond latency optimization offer the clearest technology-first wedge into pharmaceutical contract manufacturing in South Korea's Incheon Free Economic Zone. Target predictive maintenance white space in China's Pearl River Delta process industries where data engineering talent scarcity stalls incumbent operationalization. Pursue outcome-based uptime guarantee contracts rather than capital equipment sales to bypass entrenched procurement relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision mechanics specialists with harmonic drive IP in Japan's Kumamoto region amid semiconductor capital expenditure volatility. Long-term viability hinges on 5-10 year positioning for AI-driven motion control convergence rather than standalone hardware margins. Watch for MIIT GB standard enforcement acceleration as inflection signal triggering state-owned enterprise modernization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Platform Integration | Enables prescriptive analytics in pharmaceutical batch manufacturing under MFDS frameworks. |
| Backward Integration into Rare Earth Magnet Supply | Insulates servo-motor costs from Inner Mongolia processing concentration volatility. |
| METI JIS Certification Partnership | Unlocks Toyota City and Osaka automotive subcontractor procurement channels. |
| India PLI Scheme Local Assembly | Captures BIS energy-efficiency labeling first-mover advantage in Maharashtra corridors. |
| Digital Twin Virtual Commissioning | Collapses Aichi Prefecture paint shop deployment timelines to 18-month refresh cycles. |
Study Parameters
Independent corroboration across plant engineers at Yangtze River Delta semiconductor facilities, procurement leads at Gyeonggi Province battery gigafactories, and aftermarket service heads at Japanese tier-1 automotive suppliers underwrites the qualitative findings. Secondary validation draws from MIIT GB standard filings, METI JIS certification registries, and MFDS cybersecurity framework disclosures. Bottom-up equipment shipment aggregation and top-down industrial automation capex analysis triangulate market sizing.
Comparable-period anchoring to historical MIIT mandate implementation waves and METI Society 5.0 roadmap milestones structured the forecast window. Segmentation modeling spans product type, application vertical, end-user archetype, and technology deployment complexity. CAGRs derive from equipment replacement cycle compression under dual carbon mandates and edge-AI adoption curve inflections. Prescriptive analytics platform revenue trajectories and digital twin deployment subsidies constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth magnet trade flows and unannounced revisions to India's PLI scheme eligibility criteria. Forecasts reflect documented assumptions regarding provincial subsidy continuity and JIS certification timeline stability. Deviation in MIIT enforcement intensity or MFDS cybersecurity framework expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Europe ICS Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Global Smart Warehousing Market