
 Global PC Based Automation Market | 2026-2036
Global PC Based Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global PC Based Automation Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is restructuring the cost-of-entry calculus for industrial control systems. This regulation forces companies to justify automation investments based on energy efficiency and resource use, not solely on labor savings. In response, Siemens leverages its deep integration with German manufacturing to provide compliant solutions that track energy consumption. Rockwell Automation competes on the scalability of its software platforms for diverse end-user applications across the United States and Canada.
PC based automation utilizes industrial PCs, often equipped with real-time operating system (RTOS) extensions, to manage and control machinery and factory processes. This architecture provides superior processing power, data handling, and network connectivity compared to traditional programmable logic controllers (PLCs). The software segment, particularly platforms enabling complex data acquisition and analytics, commands significant value and margin. Cloud-based deployment models represent the fastest-growing approach, enabling remote monitoring and predictive maintenance for utilities and distributed manufacturing sites.
Compliance with standards like IEC 61131-3 for programming languages is a baseline requirement for global market access. Regulators such as the US FDA and China's National Medical Products Administration (NMPA) impose stringent validation protocols for automation in pharmaceutical and food production. These frameworks directly influence software development cycles and hardware certification costs. Stakeholders must now decide between adopting open-source software stacks for flexibility or proprietary, fully-supported vendor ecosystems for guaranteed long-term viability and security.
Market Dynamics
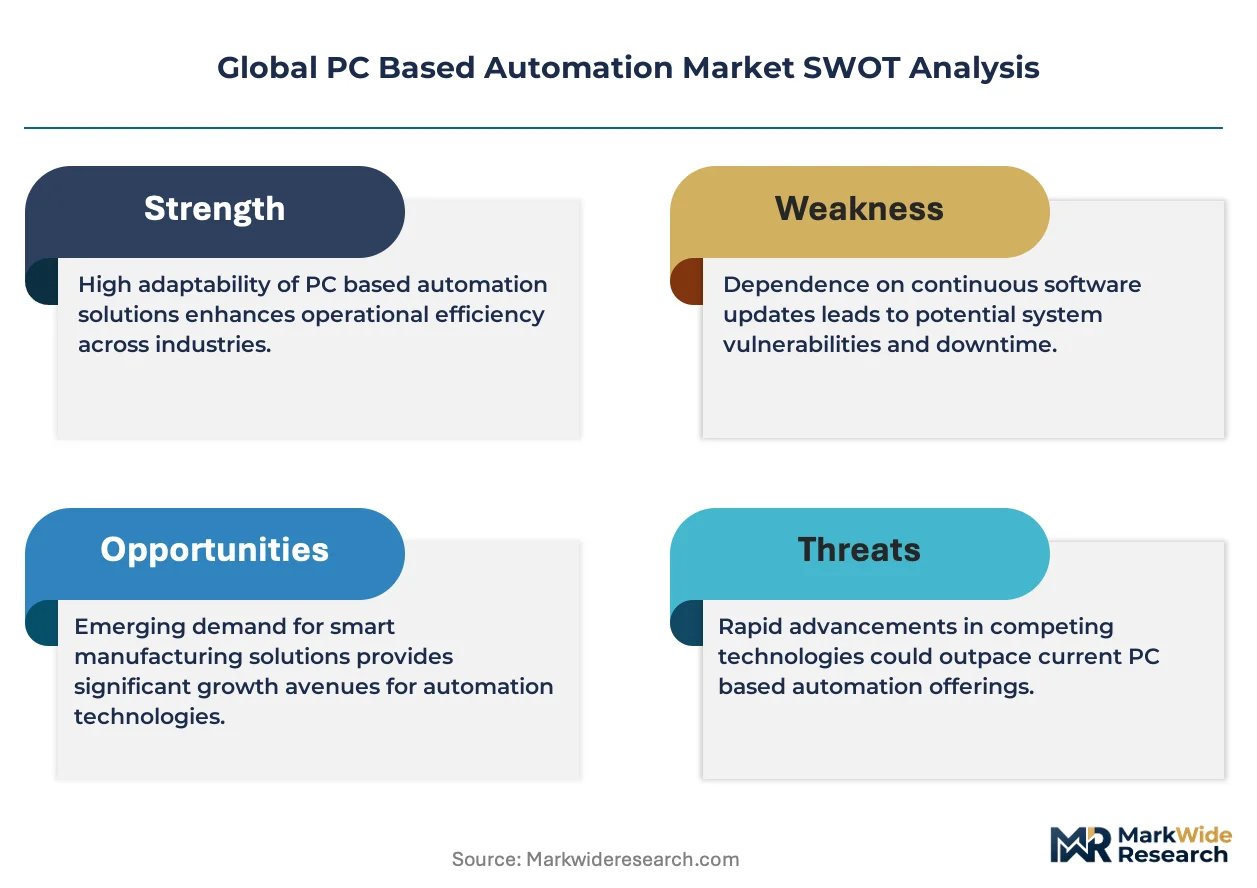
The convergence of regulatory mandates for sustainability and transparency with the processing power of industrial PCs is the central force shaping the market. This dual pressure compels a shift from cost-centric automation to value-based, data-driven process control.
Growth Catalysts
- Advanced Process Control:Demand for machine vision integration in discrete manufacturing for quality assurance requires the processing power found in PC-based systems.
- EU Sustainability Mandates:The CSRD is forcing companies to justify automation with energy efficiency data, which PC-based platforms can readily provide.
- Predictive Maintenance:The utility sector's push for remote monitoring and analytics relies on the superior data handling and connectivity of PC architectures.
Market Restraints
- High Initial Cost:The capital expenditure for industrial PCs and software licenses often exceeds that of traditional, single-purpose PLC hardware.
- Real-Time Determinism Challenges:Ensuring consistent performance on multi-purpose operating systems, even with RTOS extensions, is a technical hurdle compared to dedicated PLCs.
- Regulatory Validation Burden:Regulators like the US FDA and China's NMPA impose lengthy and costly validation cycles for automation software in life sciences.
Strategic Opportunities
- AI and ML Convergence:Integrating AI algorithms with PC-based control creates opportunities for adaptive process optimization in complex manufacturing applications.
- Expansion in Utilities:The water and wastewater sector is an underpenetrated market for cloud-based PC automation used for monitoring distributed assets.
- Open-Source Stacks:Providing solutions based on open-source software can attract customers who wish to avoid vendor lock-in and require deep customization.
Industry Challenges
- IT/OT Talent Scarcity:A shortage of engineers with hybrid expertise in information and operational technology complicates system integration and maintenance.
- Legacy System Integration:Connecting modern PC-based controls with older, proprietary factory equipment is a complex and costly technical hurdle for end-users.
- Cybersecurity Vulnerabilities:The increased connectivity of PC-based systems exposes critical industrial processes to a wider range of cybersecurity threats than traditional PLCs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PC Based Automation Market |
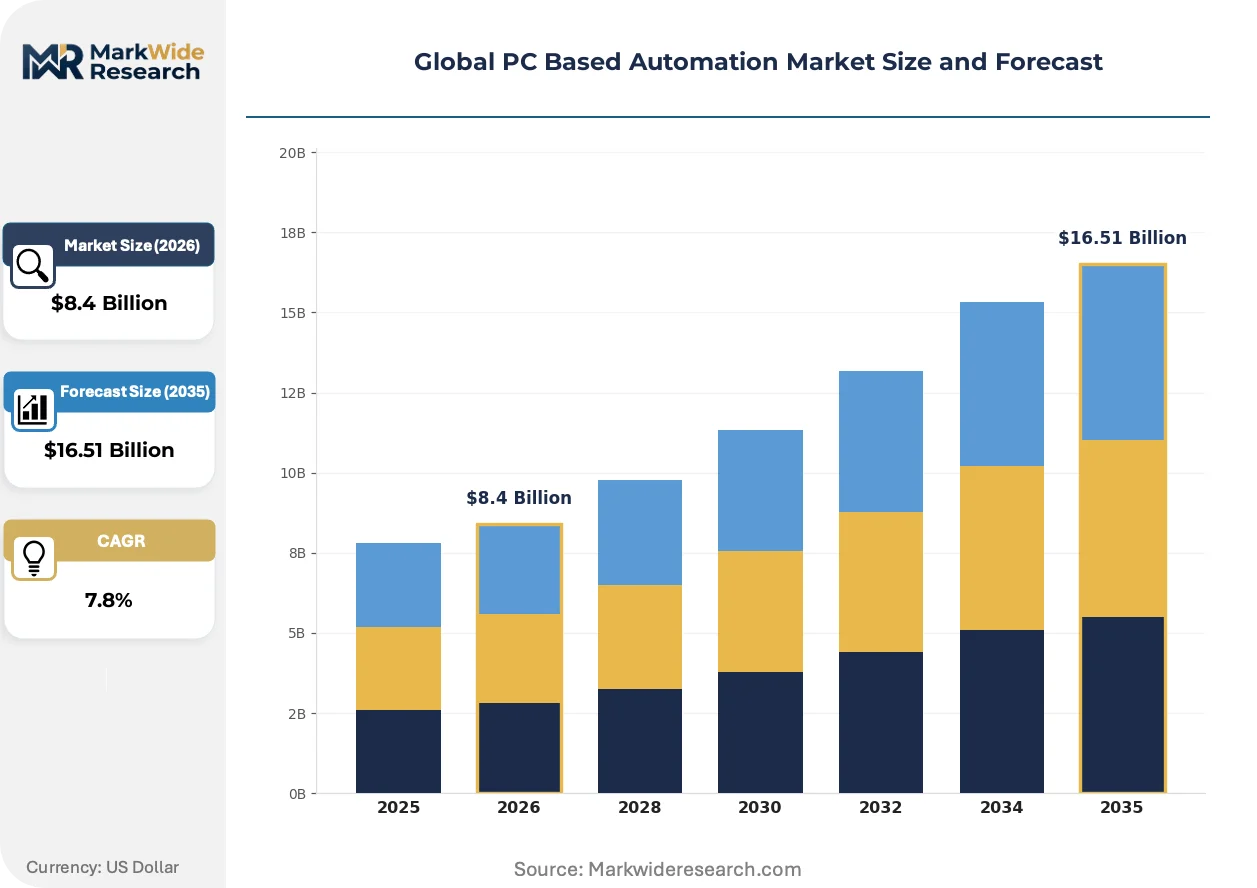
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Software, Sensors, Actuators End User: Manufacturing, Oil & Gas, Utilities, Food & Beverage Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Process Automation, Factory Automation, Building Automation, Data Acquisition |
| Companies Covered | Honeywell International, Beckhoff Automation, ABB, Rockwell Automation, Advantech, Siemens, Omron Corporation, Schneider Electric, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PC Based Automation Market Strategic Shifts & Innovations
Software-defined functionality is reshaping competitive positioning in the PC-based automation market. The evolution is moving from hardware-centric control to flexible, data-rich platforms driven by regulatory pressures for transparency and operational demands for greater intelligence at the machine level.
Real-time operating system (RTOS) extensions for standard platforms like Windows or Linux provide the deterministic performance required for industrial control. Discrete manufacturing and process industries are adopting this technology to consolidate control, HMI, and data analytics on a single industrial PC. This convergence of IT and OT capabilities on one hardware platform is rewriting the traditional architecture of factory automation systems.
The European Union's AI Act introduces stringent requirements for transparency and auditability in high-risk applications, including industrial control. This legislation directly impacts PC-based automation systems that use machine learning for process optimization or safety-critical functions. Vendors serving the EU market must now incorporate robust data logging and risk management frameworks into their software to ensure compliance.
A preference for open-source software stacks is gaining traction among sophisticated end-users seeking to avoid proprietary vendor ecosystems. This behavioral shift transfers the burden of system integration and long-term support to the user in exchange for greater customization and flexibility. The trend is most visible within academic research institutions and agile manufacturing startups in the United States.
Global PC Based Automation Market Segmentation
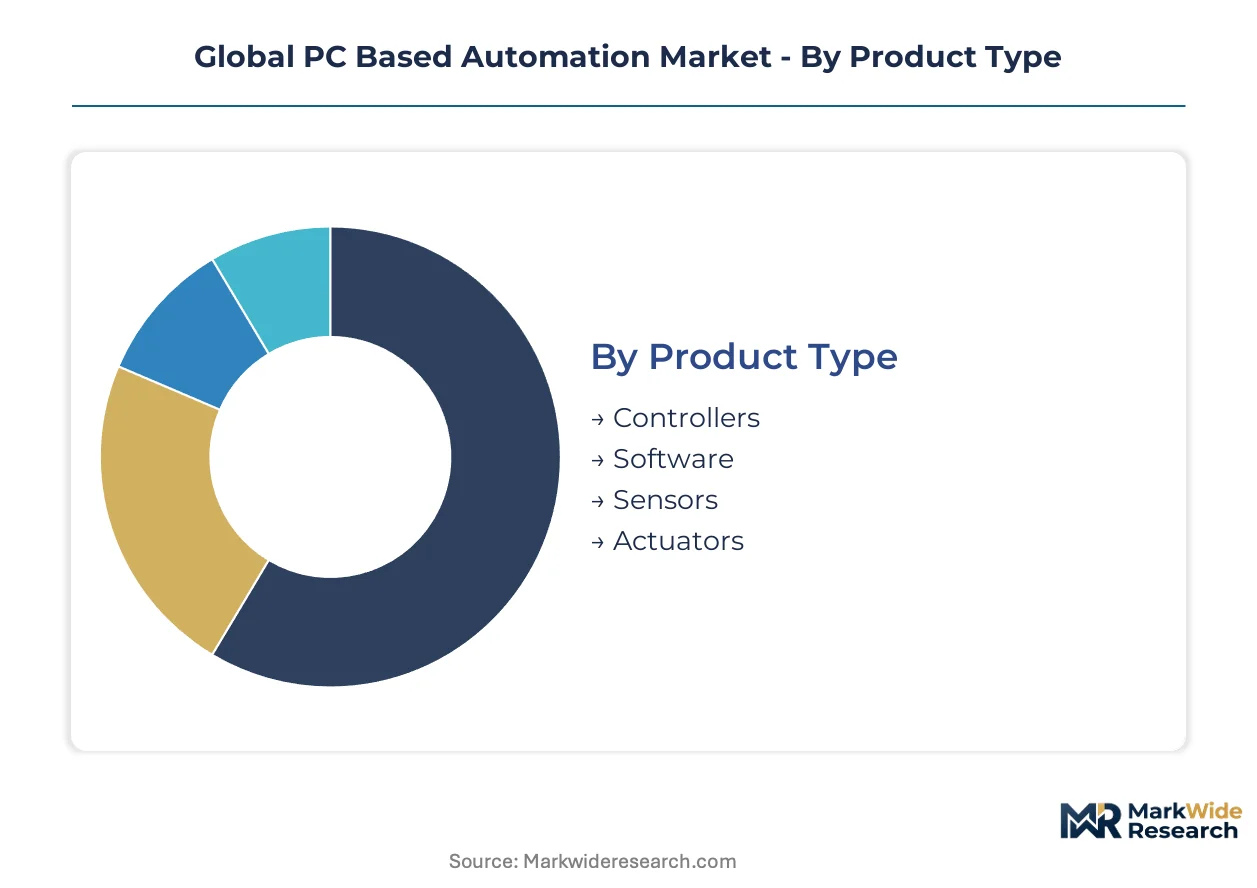
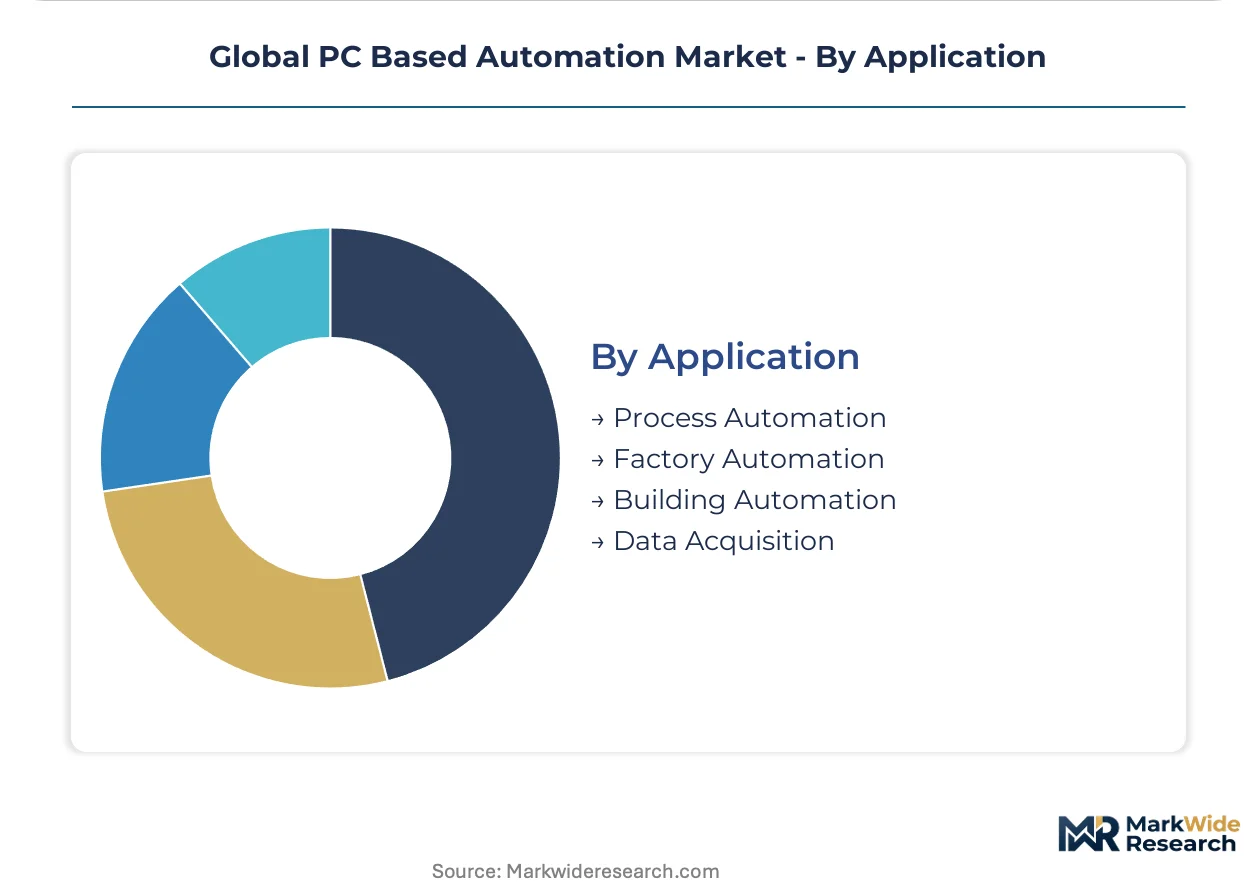
Understanding the segmentation of the Global PC Based Automation Market reveals the diverse needs driving technological adoption across industries. Each segment reflects specific operational challenges and investment priorities for end-users. This granular view highlights where innovation and capital are concentrating within the industrial automation landscape.
Product Type:
The upfront capital expenditure for PC-based automation systems varies significantly across product types.
- Controllers:These utilize industrial PCs, often with real-time operating system extensions, to execute control logic and manage machinery. Demand concentrates in discrete manufacturing and process industries seeking enhanced processing power and superior data handling capabilities.
- Software:This segment includes platforms for programming, human-machine interfaces (HMI), data acquisition, and analytics. Significant value and margin are commanded by platforms enabling complex data analysis, particularly for utilities and distributed manufacturing sites requiring remote monitoring and predictive maintenance.
- Sensors:These devices gather real-time data from physical processes, feeding critical input into PC-based control systems. Machine vision integration in discrete manufacturing relies heavily on advanced sensor technology for quality assurance.
- Actuators:These components translate control signals from PC-based systems into physical motion or action within industrial machinery. Robotic systems and precision assembly lines utilize various actuators for automated tasks.
Most installed capacity flows through Controllers. Expansion is steepest in Software.
End User:
Operational complexity and regulatory compliance significantly influence PC-based automation adoption across various end-user sectors.
- Manufacturing:This sector, encompassing both discrete and process industries, utilizes PC-based automation for enhanced process control, quality assurance, and data-driven optimization. Germany's automotive and machinery industries are concentrating demand for advanced factory automation solutions, including machine vision.
- Utilities:This sector leverages PC-based systems for remote monitoring, predictive maintenance, and managing distributed assets like water treatment plants and power grids. The water and wastewater sub-sector represents an underpenetrated market for cloud-based PC automation.
- Food & Beverage:Automation in this industry requires stringent validation protocols imposed by regulators like the US FDA and China's NMPA. PC-based systems support precise process control for product consistency and safety.
- Oil & Gas:PC-based automation optimizes complex drilling, refining, and distribution processes in challenging environments. Advanced data handling capabilities support real-time decision-making and operational efficiency.
The manufacturing sector accounts for the largest share of PC-based automation deployments. The utilities sector is experiencing the most rapid expansion in new installations.
Deployment Model:
The choice of deployment model for PC-based automation is driven by data sovereignty requirements and network infrastructure capabilities.
- Cloud-Based:This model enables remote monitoring, predictive maintenance, and scalable data analytics by hosting automation software on cloud infrastructure. Utilities and distributed manufacturing sites benefit from the flexibility and reduced IT overhead.
- Edge Computing:Processing data closer to the source of generation, edge computing reduces latency and enhances real-time control for critical industrial applications. Discrete manufacturing and smart factory initiatives benefit from localized data processing.
- On-Premises:Traditional deployment where automation software and hardware reside within the user's facility, offering maximum control over data security and network performance. Critical infrastructure and highly sensitive operations often prefer this model.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing for flexible data management and workload distribution. Companies can integrate legacy systems while leveraging cloud benefits for non-critical functions.
On-premises solutions maintain strong adoption for critical infrastructure. Cloud-based models offer the greatest flexibility for scaling operations.
Application:
The complexity of industrial processes and the need for seamless integration define the requirements for PC-based automation applications.
- Process Automation:This application manages continuous or batch processes in industries like chemicals, pharmaceuticals, and food & beverage. PC-based systems provide the processing power for complex control algorithms and data logging required by regulators.
- Factory Automation:Focused on discrete manufacturing, this application automates production lines, assembly processes, and quality control. Machine vision integration, enabled by PC-based systems, enhances quality assurance in industries such as automotive and machinery.
- Building Automation:PC-based systems control and monitor building functions like HVAC, lighting, and security for energy efficiency and operational management. Smart building initiatives leverage these platforms for integrated control.
- Data Acquisition:This application involves collecting, processing, and storing data from sensors and other devices for analysis and decision-making. Superior data handling capabilities of PC architectures are crucial for advanced analytics and predictive maintenance.
Factory automation remains a primary application for PC-based systems. Data acquisition capabilities are rapidly advancing across all application areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's skilled engineering workforce anchors a significant portion of the global PC based automation market. This concentration drives innovation in industrial control systems and advanced manufacturing. Regulatory frameworks and specific industry demands shape adoption patterns across diverse geographies.
Germany
Demand for advanced machine vision integration in discrete manufacturing is strong in Germany. The EU AI Act compels vendors to build transparent control systems for high-risk applications. German automotive and machinery industries, particularly in Bavaria, are concentrating demand for these advanced factory automation solutions.
United States
The United States sees strong demand for scalable software platforms across diverse end-user applications. The US FDA imposes stringent validation protocols for automation in pharmaceutical production. Silicon Valley and the Midwest manufacturing belt are centers for software innovation and industrial application of PC-based systems.
China
China's manufacturing sector drives demand for high-performance factory automation solutions. The National Medical Products Administration (NMPA) sets rigorous standards for automation in pharmaceutical and food production. The Yangtze River Delta region is a key hub for industrial production and adoption of PC-based controls.
Japan
Japanese industries require precision control and data handling capabilities for advanced manufacturing processes. The Ministry of Economy, Trade and Industry (METI) promotes smart factory initiatives and industrial digitalization. Tokyo and the Kansai region lead in implementing PC-based automation for robotics and complex assembly lines.
Canada
Canadian utilities and distributed manufacturing sites demand remote monitoring and predictive maintenance solutions. Health Canada influences automation standards in food and pharmaceutical sectors. Ontario's industrial corridor and energy sector are adopting cloud-based PC automation for managing widespread assets.
Global PC Based Automation Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the PC based automation market. The competitive structure is tiered, with large industrial automation firms offering comprehensive suites alongside niche software and hardware providers. Strategic partnerships for IT/OT convergence and continuous portfolio diversification represent dominant competitive moves.
Among established industrial automation providers, Germany-based Siemens and US-based Rockwell Automation exemplify companies with extensive portfolios spanning hardware and software. These firms occupy a position serving diverse industrial sectors with integrated solutions. Beckhoff Automation, a German specialist, represents vendors focused on PC-based control technology, catering to specific performance and flexibility requirements.
| Leading Market Players |
|---|
| Honeywell International |
| Beckhoff Automation |
| ABB |
| Rockwell Automation |
| Advantech |
| Siemens |
| Omron Corporation |
| Schneider Electric |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
Vertical integration within established industrial automation firms anchors their supply position and pricing power. This strategy enables comprehensive solution offerings and robust after-sales support, influencing market entry costs for competitors.
Pricing Analysis
Bundled software and service packages often command premium pricing in PC-based automation. Licensing models, particularly for complex data acquisition and analytics platforms, drive differentiation based on customization level and vendor support. Pricing pressure stems from the high initial capital expenditure for industrial PCs and associated software licenses. End-users seeking customization and flexibility, such as academic institutions, exhibit higher price sensitivity for proprietary solutions.
Supply Chain Analysis
Direct-to-end-user channels, supported by system integrators, define the distribution model for PC-based automation solutions. Geographic supply concentration for industrial PCs and components draws from East Asia, notably China and Taiwan, and European manufacturing hubs like Germany. Key component dependencies include specialized processors, memory modules, and industrial-grade sensors. Regulatory restrictions, such as those from the EU AI Act, represent a structural risk influencing software and hardware compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global PC based automation market represents a significant margin-expansion story. The shift towards software-defined functionality and cloud-based deployments drives premium-tier service adoption and recurring revenue streams for vendors.
For Market Incumbents:Anchor existing customer relationships by providing comprehensive, compliant solutions that address emerging regulatory demands like the EU AI Act and CSRD. Invest in cybersecurity expertise and develop secure-by-design architectures to mitigate increased connectivity risks. Leverage existing integration capabilities to address legacy system challenges for end-users, strengthening market share against focused specialists.
For New Entrants and Emerging Players:Enter via specialized software solutions built on open-source stacks, targeting customers seeking customization and avoiding vendor lock-in. Focus on underpenetrated segments like the water and wastewater sector, offering cloud-based monitoring and analytics. A go-to-market angle emphasizing rapid deployment and adaptive AI-driven process optimization can attract agile manufacturing startups.
For Investors and Strategic Acquirers:Roll-up economics work for software platform providers because of the high margin potential in data acquisition and analytics. Long-term viability rests on securing intellectual property in AI/ML algorithms for adaptive optimization. Acquire niche specialists with deep expertise in specific industrial applications or critical cybersecurity solutions. The signal to watch is the increasing adoption rate of cloud-based solutions across distributed manufacturing sites.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating IT and OT capabilities on single hardware platforms enhances operational efficiency. |
| AI/ML IP Acquisition | Acquiring intellectual property in AI algorithms drives adaptive process optimization for complex manufacturing. |
| Cybersecurity Solution Development | Building robust cybersecurity features into products protects critical industrial infrastructure from threats. |
| Open-Source Ecosystem Participation | Contributing to open-source software stacks attracts customization-focused end-users and talent. |
| Regulatory Compliance Services | Offering solutions compliant with EU AI Act and CSRD reduces market entry barriers for customers. |
Research Approach
Multiple input streams — primary interviews with industry experts, secondary data from regulatory bodies, and company financial disclosures — were reconciled. Field interviews included automation engineers, plant managers, IT directors, and regulatory compliance officers. Secondary validation involved reports from industrial associations, government industrial statistics, and academic research papers. This approach utilized both bottom-up market sizing and top-down validation.
Historical market performance was cross-referenced with panel input from industry specialists for the forecast framework. Segmentation dimensions modeled include product type, end-user industry, deployment model, and specific application areas. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical trends and projected technological adoption. Regulatory compliance requirements, such as IEC 61131-3, served as a key forecast input across the modeling period.
The model holds under current regulatory frameworks and technological adoption rates; deviation in global economic stability or new cybersecurity threats would shift projections. Forecasts reflect assumptions regarding the pace of digital transformation and industrial investment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Factory Automation Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Drilling Automation Market
Industrial Automation
North America Process Automation Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market