
 North America Industrial Vending Machine Market | 2026-2036
North America Industrial Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Vending Machine Market Analytics
Midwestern tool and die production capacity is shifting toward automated inventory management as labor costs climb. Fastenal Company leverages its branch density to control last-mile distribution for industrial consumables. MSC Industrial Direct Co., Inc. anchors its position through deep catalog breadth and same-day fulfillment networks. Apex Industrial Technologies LLC differentiates via proprietary software that integrates with enterprise resource planning systems.
North America industrial vending machines are electromechanical dispensing systems, typically constructed from galvanized steel with RFID or biometric authentication modules, designed to control access to tools, personal protective equipment, and maintenance supplies in factory and warehouse environments. Tool Vending dominates product type revenue as aerospace and heavy equipment manufacturers prioritize cutting tool traceability, while IoT-enabled Vending is expanding fastest as cloud-connected units allow real-time inventory monitoring and predictive restocking algorithms. Smart Vending systems command premium positioning through usage analytics that reduce carrying costs and eliminate stockout downtime.
OSHA mandates on personal protective equipment accountability and EPA reporting requirements for hazardous substance tracking shape product design specifications across the United States. Health Canada and the Canadian Standards Association enforce parallel workplace safety equipment standards that vendors must satisfy for cross-border market access. Stakeholders should monitor how NHTSA supply chain traceability rules for automotive components migrate toward consumable tracking requirements in adjacent industrial sectors.
Market Dynamics
OSHA workplace safety mandates and EPA hazardous material tracking protocols are compressing adoption cycles for authentication-enabled dispensing systems across Great Lakes manufacturing clusters.
Growth Catalysts
- OSHA PPE Accountability Mandates:Federal workplace safety protocols now require documented personal protective equipment issuance, forcing automotive and aerospace plants toward biometric-enabled vending architectures.
- Tool Traceability Requirements:Aerospace manufacturers in Wichita and Hartford demand cutting tool lifecycle tracking to satisfy NADCAP audit standards and reduce foreign object debris incidents.
- Cloud-Connected Inventory Systems:IoT-enabled vending units with predictive restocking algorithms are eliminating stockout downtime in Ohio and Indiana heavy equipment production lines.
Market Restraints
- Galvanized Steel Input Volatility:Electromechanical cabinet construction depends on steel pricing exposed to tariff fluctuations and domestic mill capacity constraints.
- ERP Integration Complexity:Proprietary software protocols from incumbent vendors create switching costs that lock mid-tier manufacturers into suboptimal system architectures.
- Biometric Authentication Fragmentation:Competing fingerprint, facial recognition, and RFID standards delay unified procurement decisions at multi-site industrial operators.
Strategic Opportunities
- Canadian Cross-Border Expansion:Health Canada and CSA workplace equipment standards create parallel certification pathways for US-designed smart vending systems in Ontario and Quebec manufacturing corridors.
- Maintenance Supply Diversification:Industrial MRO distributors are embedding vending units within existing branch networks to capture consumable spend previously routed through centralized procurement.
- NHTSA Traceability Migration:Automotive component tracking rules are expanding toward consumable categories, creating regulatory tailwinds for tool vending deployments in Michigan and Ohio assembly plants.
Industry Challenges
- Legacy Equipment Retrofit Costs:Brownfield manufacturing facilities face capital intensity challenges when integrating cloud-connected vending with decades-old facility management systems.
- Field Service Technician Shortage:Electromechanical repair and IoT diagnostics skill gaps constrain deployment velocity and uptime guarantees across distributed industrial sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Vending Machine Market |
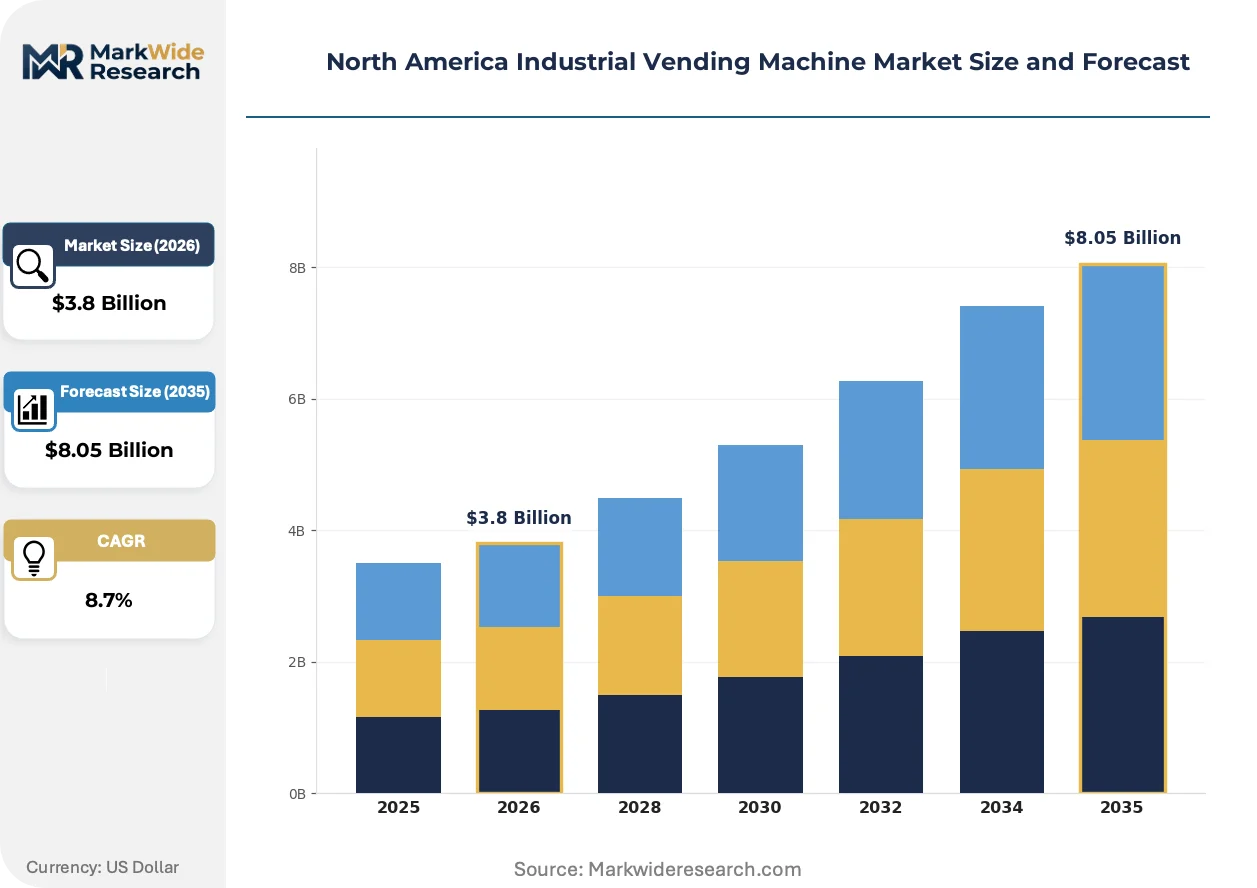
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tool Vending, Snack Vending, Beverage Vending, Custom Vending End User: Manufacturing, Warehousing, Construction, Automotive Technology: Smart Vending, Traditional Vending, IoT-enabled Vending, Cashless Vending Service Type: Maintenance Services, Supply Services, Installation Services, Software Services |
| Companies Covered | Fastenal Company, MSC Industrial Direct Co., Inc., Apex Industrial Technologies LLC, AutoCrib, Inc., Airgas, Inc., CribMaster, IVM Ltd., SupplyPro, Inc., SECURASTOCK, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Vending Machine Market Evolving Landscape
Authentication technology, regulatory compliance architectures, and procurement centralization are simultaneously rewriting how industrial consumables flow through factory environments.
Biometric authentication modules paired with RFID credentialing are rewriting access control protocols for high-value tooling. Aerospace manufacturers in Connecticut and Kansas are deploying dual-factor systems at pilot scale. This convergence is compressing the acceptable security threshold for unattended inventory management from perimeter-based to point-of-use verification.
EPA hazardous substance tracking requirements are mandating serialized dispensing records for solvents, adhesives, and cutting fluids. Chemical manufacturers must now demonstrate chain-of-custody documentation from vending unit to consumption point. Automotive suppliers in the Great Lakes corridor are responding by specifying vending systems with built-in lot tracking and automated EPA report generation.
Centralized procurement teams are consolidating vendor relationships and demanding usage analytics dashboards that aggregate consumption patterns across multi-state manufacturing footprints. This behavioral shift is displacing site-level purchasing autonomy. The concentration is most visible among tier-one automotive suppliers operating across Illinois, Indiana, and Ohio production networks.
North America Industrial Vending Machine Market Segmentation
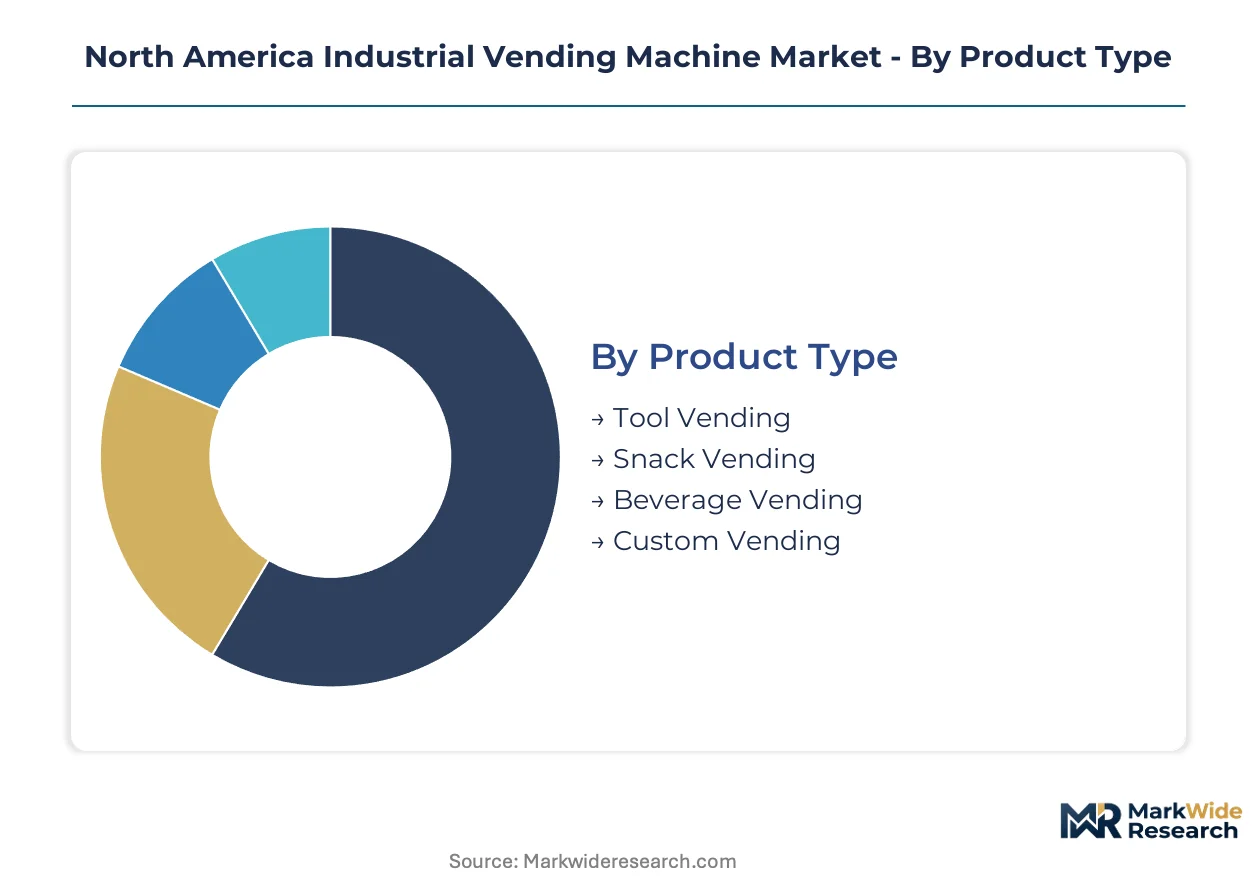
Segmentation in industrial vending machines reveals how authentication technologies, end-use requirements, and service architectures fragment procurement decisions across Great Lakes manufacturing clusters. Supply chain configuration varies sharply between aerospace tool traceability mandates and construction site consumable replenishment.
Product Type:
Supply concentration in electromechanical cabinet manufacturing favors galvanized steel fabricators with automotive-adjacent production footprints.
- Tool Vending:Electromechanical dispensing cabinets constructed from galvanized steel with RFID or biometric authentication modules control access to cutting tools, PPE, and maintenance supplies. Aerospace manufacturers in Wichita and Hartford prioritize these systems to satisfy NADCAP audit standards and reduce foreign object debris incidents.
- IoT-enabled Vending:Cloud-connected units with predictive restocking algorithms allow real-time inventory monitoring across distributed production lines. Heavy equipment manufacturers in Ohio and Indiana deploy these architectures to eliminate stockout downtime and compress carrying costs.
- Snack Vending:Peripheral installations in break areas and facility common spaces serve secondary workforce amenities rather than production-critical functions.
- Beverage Vending:Hydration stations positioned near welding bays and heat-intensive workstations address OSHA thermal stress protocols in foundry environments.
- Custom Vending:Purpose-built configurations for serialized hazardous substance tracking serve EPA chain-of-custody documentation requirements for solvents and cutting fluids.
Tool Vending absorbs the bulk of installed capacity; IoT-enabled Vending is expanding most quickly.
End User:
Cost tier stratification separates aerospace-grade authentication requirements from construction site durability specifications.
- Manufacturing:Automotive and heavy equipment production lines in Michigan and Ohio drive demand for biometric-enabled systems that track consumable usage to individual workstations. OSHA PPE accountability mandates force tier-one suppliers toward documented issuance protocols.
- Automotive:Assembly plants and component suppliers across the Great Lakes corridor specify vending systems with ERP integration and automated restocking algorithms. NHTSA supply chain traceability rules are migrating toward consumable tracking requirements in adjacent industrial sectors.
- Warehousing:Distribution centers prioritize durability and rapid replenishment cycles over sophisticated authentication layers.
- Construction:Job-site deployments favor ruggedized cabinets with simplified credentialing to withstand environmental exposure and high workforce turnover.
Manufacturing commands the dominant share of authentication-enabled deployments; Automotive is climbing the fastest as traceability requirements tighten.
Technology:
Volume concentration in cloud-connected architectures reflects procurement centralization across multi-state manufacturing footprints.
- Smart Vending:Systems with usage analytics dashboards aggregate consumption patterns across distributed sites, displacing site-level purchasing autonomy. Tier-one automotive suppliers operating across Illinois, Indiana, and Ohio production networks demand these centralized visibility tools.
- IoT-enabled Vending:Sensor-equipped units transmit real-time inventory levels to predictive restocking algorithms. Heavy equipment manufacturers deploy these systems to synchronize consumable availability with production schedules.
- Traditional Vending:Mechanical dispensing without connectivity persists in brownfield facilities with limited IT infrastructure.
- Cashless Vending:Card and mobile payment modules address workforce convenience in break-area installations rather than production floor deployments.
Smart Vending captures the largest technology investment; IoT-enabled Vending is gaining share fastest as cloud adoption accelerates.
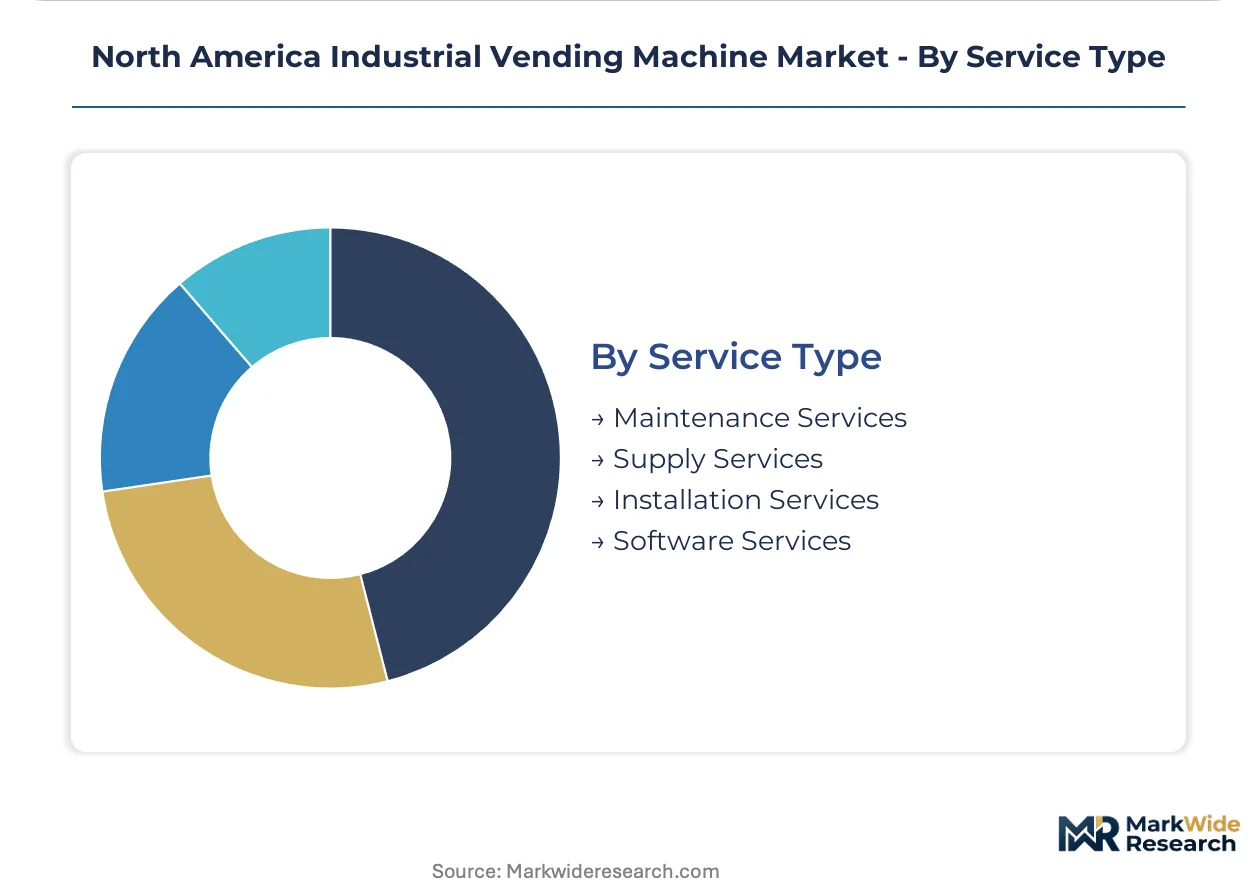
Service Type:
Margin structure favors recurring revenue streams over one-time installation economics.
- Maintenance Services:Electromechanical repair and IoT diagnostics contracts address field service technician shortages that constrain uptime guarantees. Distributors embed technical support within existing branch networks to differentiate against equipment-only vendors.
- Software Services:ERP integration, usage analytics, and automated compliance reporting generate subscription revenue. Aerospace manufacturers demand these layers to satisfy NADCAP and EPA documentation requirements.
- Supply Services:Consumable replenishment and vendor-managed inventory programs capture ongoing material spend.
- Installation Services:One-time deployment revenue concentrates in greenfield facilities and system replacements.
Maintenance Services anchor recurring revenue; Software Services is expanding most quickly as compliance automation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galvanized steel mills in Indiana and Ohio anchor North American cabinet fabrication for electromechanical dispensing systems. The Great Lakes manufacturing corridor concentrates demand from automotive and aerospace production networks.
United States
OSHA PPE accountability mandates and EPA hazardous material tracking protocols compress adoption cycles for authentication-enabled systems. NHTSA supply chain traceability rules migrate toward consumable tracking in Michigan and Ohio assembly plants. Aerospace manufacturers in Wichita and Hartford deploy cutting tool vending to satisfy NADCAP audit standards.
Canada
Health Canada and CSA workplace safety equipment standards create parallel certification pathways for cross-border market access. Ontario and Quebec manufacturing corridors import US-designed smart vending systems for tool traceability compliance. Toronto-area automotive suppliers specify ERP-integrated units with automated restocking algorithms.
Mexico
Nearshoring acceleration in Nuevo León and Baja California drives demand for inventory control systems in maquiladora operations. Mexican labor law amendments strengthen workplace safety enforcement, indirectly supporting PPE vending deployment. Monterrey heavy equipment assembly plants pilot IoT-enabled units for consumable monitoring.
Midwest Manufacturing Belt
Illinois, Indiana, and Ohio production networks concentrate tier-one automotive supplier demand for centralized procurement visibility. Fastenal branch density controls last-mile distribution across this corridor. Chicago-area distributors embed maintenance services within existing networks to differentiate against equipment-only vendors.
North America Industrial Vending Machine Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and software integration capabilities. The vendor base stratifies between diversified industrial distributors and specialized vending technology developers. Three archetypes dominate: branch-network distributors with captive logistics, ERP-integrated software specialists, and equipment-focused hardware fabricators. M&A activity concentrates on software capability acquisition, while organic expansion targets Canadian cross-border certification.
Among diversified industrial distributors, Fastenal Company and MSC Industrial Direct Co., Inc. occupy positions anchored by dense branch networks and same-day fulfillment infrastructure. Apex Industrial Technologies LLC represents the software-specialist archetype, sitting within the tier defined by proprietary ERP integration protocols. AutoCrib, Inc. exemplifies equipment-focused developers concentrating on authentication hardware and cabinet durability specifications.
| Leading Market Players |
|---|
| Fastenal Company |
| MSC Industrial Direct Co., Inc. |
| Apex Industrial Technologies LLC |
| AutoCrib, Inc. |
| Airgas, Inc. |
| CribMaster |
| IVM Ltd. |
| SupplyPro, Inc. |
| SECURASTOCK |
| Others |
Value Network & Pricing Analysis
Galvanized steel price indices cascading from Indiana and Ohio mill contracts compress margin structures across authentication-enabled cabinet tiers, forcing vendors to unbundle software subscriptions from hardware procurement to preserve pricing flexibility for mid-tier manufacturers.
Pricing Analysis
Warranty and field service bundling separates premium smart vending deployments from economy-tier mechanical units. Three-tier pricing structure across premium, standard, and economy levels reflects authentication complexity and ERP integration depth. Cost compression in the standard tier is intensifying because mid-market manufacturers resist SaaS subscription models. Construction site operators exhibit highest price sensitivity; aerospace NADCAP-compliant buyers accept premium positioning for traceability assurance.
Supply Chain Analysis
Galvanized steel sheet supply rests on Indiana, Ohio, and Pennsylvania domestic mill capacity with limited import substitution. Electromechanical components draw from Mexican maquiladora assembly and Taiwanese sensor module producers. Single-source vulnerability in biometric authentication chipsets creates procurement bottlenecks for dual-factor system builders. Distribution runs through Fastenal's branch-network density and MSC Industrial's same-day fulfillment nodes across the Great Lakes corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric-enabled smart vending architectures are displacing mechanical credentialing systems across OSHA-mandated manufacturing environments, compressing legacy equipment replacement cycles.
For Market Incumbents: Deploy software subscription bundling to lock in recurring revenue against hardware commoditization pressure from Chinese equipment entrants. Deepen ERP integration protocols with SAP and Oracle to raise switching costs for tier-one automotive accounts. Anchor capacity in Ontario and Quebec to capture Canadian cross-border certification requirements before regional champions consolidate. For New Entrants and Emerging Players: Direct-to-manufacturer digital sales channels bypass incumbent distributor markups in the construction and warehousing segments. Target brownfield facilities in Indiana and Ohio with retrofit-focused IoT gateway solutions that bridge legacy mechanical cabinets to cloud inventory systems. Lead with usage-based pricing to displace capital-intensive procurement models at mid-tier metal fabrication shops. For Investors and Strategic Acquirers: The window for entry favors software-specialist vending technology developers with proven ERP integration modules and Health Canada certification pathways. Long-term viability hinges on predictive analytics differentiation as procurement centralization eliminates site-level vendor fragmentation. Watch NHTSA consumable traceability rulemaking as the inflection trigger for accelerated automotive sector penetration.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Platform Development | Proprietary SAP and Oracle connectors raise switching costs for tier-one automotive suppliers across Michigan and Ohio. |
| Canadian Certification Pathway Investment | Health Canada and CSA parallel approvals unlock Ontario and Quebec manufacturing corridor demand. |
| Predictive Analytics Subscription Launch | Usage dashboards displace site-level purchasing autonomy in centralized procurement organizations. |
| Biometric Authentication Module Acquisition | Dual-factor hardware capabilities satisfy NADCAP aerospace audit standards in Wichita and Hartford. |
| Field Service Network Expansion | Technical support density addresses technician shortages constraining uptime guarantees across distributed sites. |
Research Methodology
Independent corroboration across maintenance directors at tier-one automotive suppliers, plant engineers in heavy equipment manufacturing, procurement leads at aerospace OEMs, and branch operations managers at industrial distributors underwrites the qualitative findings. Secondary validation draws from OSHA enforcement databases, EPA hazardous substance tracking filings, NHTSA supply chain traceability guidance, and customs import records for galvanized steel and electromechanical components. Bottom-up installation estimates triangulate against top-down manufacturing sector capital expenditure patterns.
Comparable-period anchoring to pre- and post-OSHA PPE mandate implementation phases structures the forecast window across the analysis window. Segmentation modeling incorporates product type, end-use industry, authentication technology tier, and service architecture dimensions. CAGRs derive from logistic diffusion curves fitted to cloud-connected vending adoption rates. Forecast inputs include automotive production schedules, aerospace NADCAP audit cycle timing, and steel mill capacity utilization indices.
The model holds under steady regulatory enforcement intensity and stable galvanized steel input costs; deviation in tariff exposure or biometric chipset supply disruption would shift deployment velocity assumptions. A small set of named triggers warrants ongoing watch: NHTSA traceability rule expansion, Health Canada certification timeline acceleration, and field service technician labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
India Industrial Automation Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
United States SCADA Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
North America Human Machine Interface Market