
 Smart Escalator Market | 2026-2036
Smart Escalator Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Escalator Market Analysis
Airport authorities and mass transit operators is collapsing the historical dominance of shopping mall developers as the primary procurement channel for smart escalator systems. KONE Corporation leverages its Nordic engineering heritage to anchor premium contracts across Scandinavian transit hubs. Schindler Group competes through its specialized maintenance analytics platform that extends equipment lifecycle value. Mitsubishi Electric Corporation dominates high-capacity installations in Asia-Pacific rail corridors through its traction motor expertise.
A smart escalator integrates IoT connectivity, variable frequency drives, and sensor arrays to enable real-time traffic adaptation, energy recovery, and condition-based maintenance in vertical transportation systems. These units typically incorporate brushless DC motors with regenerative braking capability exceeding 70% efficiency in downward operation cycles. IoT Integration and AI-powered Systems segments capture the fastest expansion as building operators prioritize predictive uptime over reactive service models. Energy-efficient Technology segments sustain margin pools through regulatory compliance premiums in jurisdictions with strict carbon benchmarks. New Installations segments lead absolute volume while Retrofitting segments accelerate as aging infrastructure in developed economies faces obsolescence deadlines.
The US Department of Transportation and FAA coordinate accessibility mandates that shape escalator specifications in federally funded transit projects. China's SAMR enforces GB 16899 safety standards that compel sensor redundancy and emergency braking protocols in all public installations. The EU Machinery Directive and CE marking requirements create technical barriers that filter non-compliant suppliers from European procurement channels. Stakeholders must monitor how AI liability frameworks evolve alongside mechanical safety regulations to anticipate compliance cost trajectories.
Market Dynamics
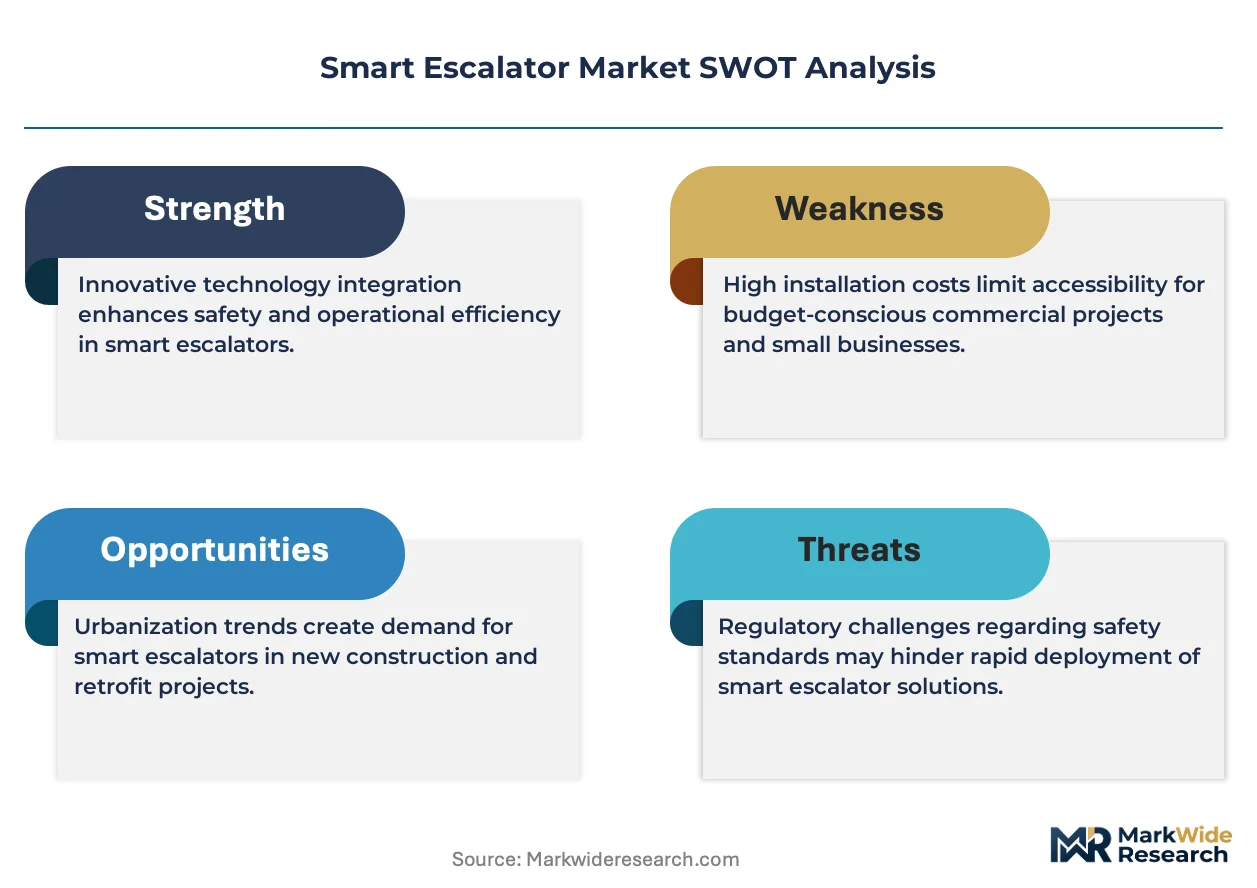
Airport infrastructure modernization is collapsing the traditional buyer hierarchy, as transit authorities displace shopping mall developers through procurement volume concentration and stricter uptime requirements.
Growth Catalysts
- China's GB 16899 Safety Mandates:Sensor redundancy requirements are compelling infrastructure upgrades across all public installations. Transit operators face compliance deadlines that accelerate replacement cycles.
- Variable Frequency Drive Adoption:Energy recovery systems in downward operation cycles are capturing regulatory premiums in jurisdictions with carbon benchmarking frameworks.
- Southeast Asian Commercial Corridors:Bangkok-to-Jakarta development clusters are generating concentrated demand for high-capacity installations in mixed-use transit hubs.
Market Restraints
- Copper and Rare Earth Input Volatility:Traction motor manufacturing faces raw material price swings that compress margin pools for system integrators.
- European Supply Concentration:CE marking compliance filters non-compliant suppliers from procurement channels, limiting vendor diversity for transit authorities.
- Stairway Escalator Substitution:Inclined moving walkways in low-rise commercial spaces are capturing share in retail and hospitality verticals.
Strategic Opportunities
- India Transit Infrastructure:Underpenetrated metro rail networks present white space for predictive maintenance platform deployment.
- AI-IoT Convergence:Machine learning algorithms layered on sensor arrays are enabling condition-based maintenance contracts that extend equipment lifecycle value.
- US FAA Accessibility Coordination:Federally funded transit projects are mandating specifications that favor integrated system providers over component vendors.
Industry Challenges
- Mechatronics Talent Scarcity:Maintenance technician shortages in developed economies are extending service response windows and degrading uptime guarantees.
- Legacy Building Integration:Retrofitting sensor arrays into aging infrastructure requires structural modifications that extend project timelines and inflate capex requirements.
- Multi-Jurisdiction Certification:Divergent safety protocols across national regulators are fragmenting product development roadmaps and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Escalator Market |
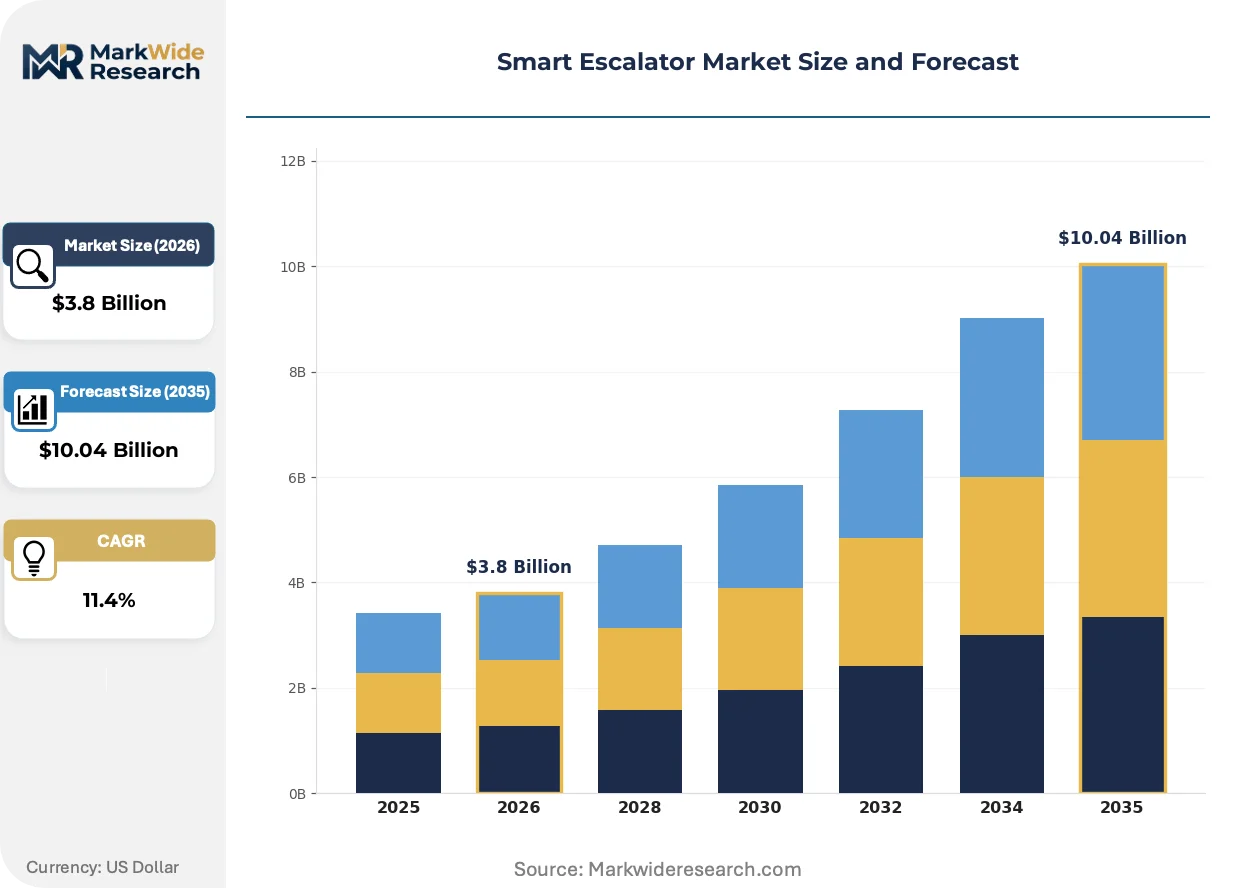
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Integration, AI-powered Systems, Energy-efficient Technology, Smart Sensors End User: Commercial Buildings, Airports, Shopping Malls, Train Stations Feature: Automatic Adjustment, Safety Sensors, User Control, Predictive Maintenance Installation: New Installations, Upgrades, Retrofitting, Modular |
| Companies Covered | Otis Worldwide Corporation, KONE Corporation, Schindler Group, Mitsubishi Electric Corporation, Hitachi Ltd., Thyssenkrupp Elevator, Hyundai Elevator, Fujitec, TK Elevator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Escalator Market Emerging Trajectories
Regenerative braking systems and predictive analytics platforms are compressing the traditional service model, as building operators prioritize uptime guarantees over transactional maintenance contracts.
Brushless DC motors with regenerative braking capability are displacing conventional induction motor designs in high-traffic installations. Airport authorities in Singapore and Dubai are specifying these systems for 24-hour operational environments. The technology is displacing reactive maintenance contracts by enabling real-time energy recovery monitoring that ties service payments to measurable efficiency outcomes.
China's SAMR enforcement of GB 16899 safety standards is mandating emergency braking protocols and sensor redundancy in all public installations. Equipment manufacturers must redesign control systems to accommodate dual-channel safety architectures. Transit operators in Shanghai and Beijing are responding by consolidating procurement around certified system integrators who can demonstrate compliance documentation.
After-sales service unbundling is fragmenting the traditional bundled maintenance model across European commercial real estate portfolios. Facility management firms are separating predictive analytics subscriptions from physical maintenance labor, creating tiered service offerings. This pattern is most visible in German and French office complexes where property managers negotiate algorithm access independently from technician dispatch contracts.
Smart Escalator Market Segmentation
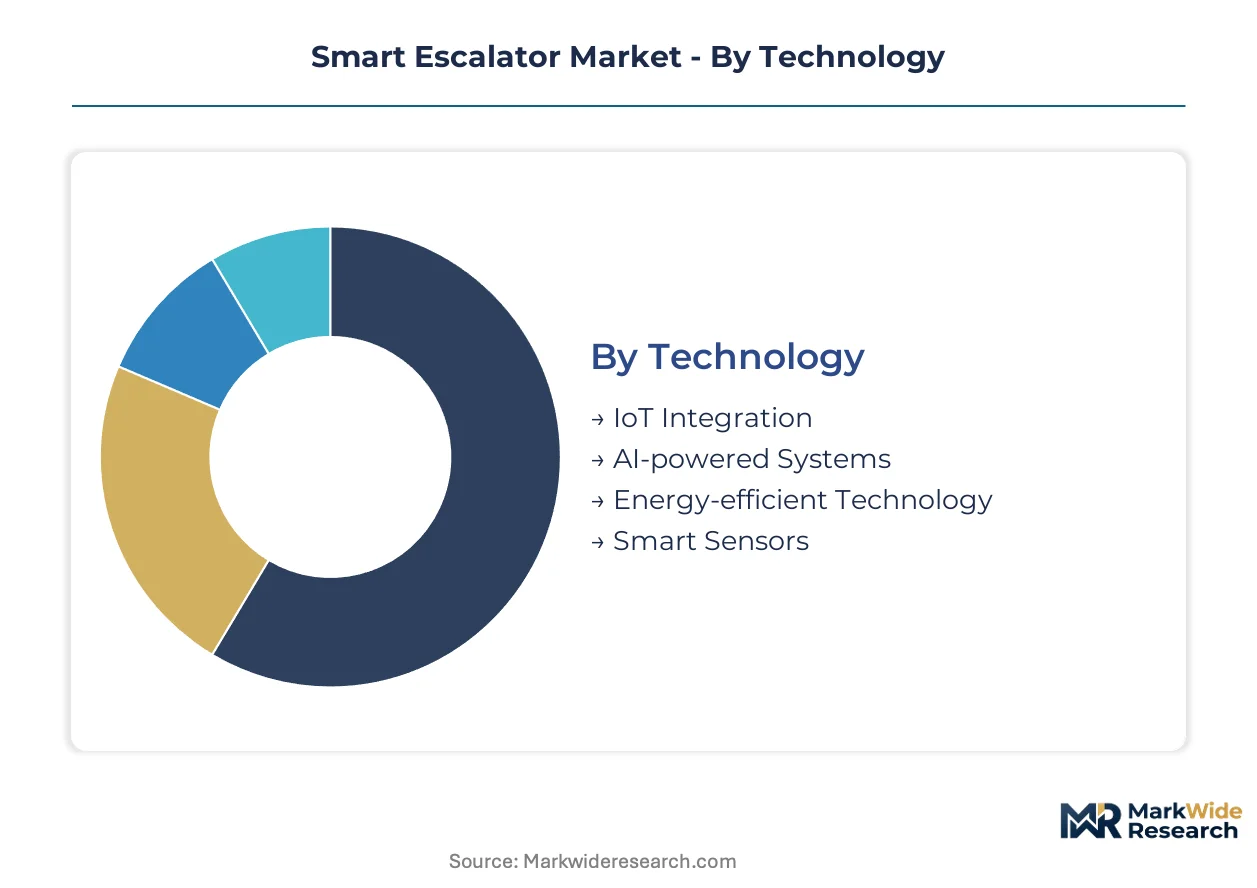
Technology and end-user segmentation in smart escalators determines regulatory compliance pathways and procurement specifications. Airport operators and transit authorities impose stricter uptime requirements than commercial developers, fragmenting vendor strategies across installation types.
Technology:
China's GB 16899 mandates sensor redundancy that filters which technologies qualify for public infrastructure contracts.
- IoT Integration:Sensor arrays transmit real-time operational data to centralized building management systems. Bangkok's Suvarnabhumi Airport and Jakarta's Soekarno-Hatta International Airport specify these systems for passenger flow optimization in high-traffic terminals.
- AI-powered Systems:Machine learning algorithms analyze traffic patterns to predict component failure before operational disruption. Shanghai Metro's procurement guidelines favor AI-enabled predictive maintenance platforms for reducing service interruption penalties.
- Energy-efficient Technology:Variable frequency drives with regenerative braking recover kinetic energy during downward operation cycles.
- Smart Sensors:Multi-channel safety architectures detect obstructions and trigger emergency braking protocols.
IoT Integration handles the majority of throughput; AI-powered Systems are expanding most quickly on share.
End User:
Procurement concentration varies sharply by facility type and operational intensity requirements.
- Commercial Buildings:Office complexes and mixed-use developments prioritize energy recovery metrics for LEED certification compliance. Singapore's Marina Bay Financial Centre specifications emphasize regenerative braking efficiency in 24-hour operational environments.
- Airports:Transit hubs demand 99.5% uptime guarantees with redundant control systems. Dubai International Airport's Terminal 3 expansion mandated dual-channel safety architectures and real-time diagnostic connectivity.
- Shopping Malls:Retail developers balance capital expenditure constraints against aesthetic integration requirements.
- Train Stations:High-frequency rail corridors require heavy-duty traction motors rated for continuous operation cycles.
Airports command premium pricing tiers; Train Stations show the steepest expansion trajectory as metro networks proliferate.
Feature:
Safety certification requirements from China's SAMR and the EU Machinery Directive shape which feature sets enter procurement channels.
- Automatic Adjustment:Variable speed control adapts escalator velocity to passenger density detected by infrared arrays.
- Safety Sensors:GB 16899-compliant redundant detection systems trigger immediate braking upon obstruction identification. Beijing Subway's procurement specifications mandate triple-channel sensor architectures for underground installations.
- User Control:Interface panels enable manual speed override and directional switching for maintenance operations.
- Predictive Maintenance:Algorithm-driven component monitoring extends equipment lifecycle through condition-based servicing. German facility management firms unbundle predictive analytics from physical maintenance labor in Frankfurt and Munich office portfolios.
Safety Sensors dominate public infrastructure specifications; Predictive Maintenance is climbing the fastest as service contracts fragment.
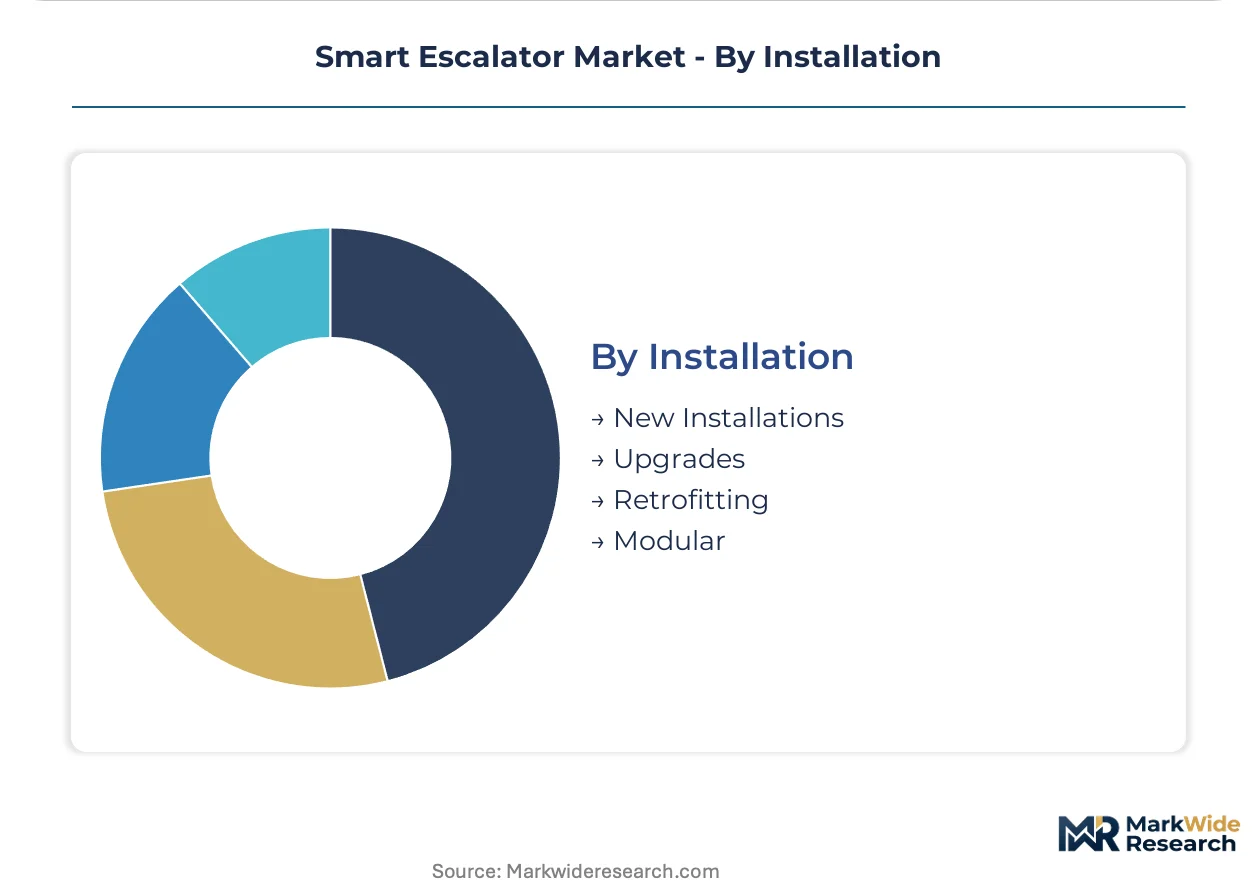
Installation:
Project timeline and structural modification requirements differentiate procurement economics across installation modes.
- New Installations:Greenfield developments integrate smart systems during construction phase with minimal retrofit complexity. Indonesia's Jakarta-Bandung high-speed rail corridor specified new-installation smart escalators across all station platforms.
- Upgrades:Control system replacements modernize legacy equipment without full structural replacement.
- Retrofitting:Sensor array integration into aging infrastructure requires structural modifications that extend project timelines. New York City's MTA faces extended capex requirements retrofitting century-old station configurations with GB-equivalent safety systems.
- Modular:Prefabricated component systems enable rapid deployment in temporary or expandable facilities.
New Installations lead absolute volume; Retrofitting is gaining share fastest as developed economies face obsolescence deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany, China, Japan, and the United States supply the majority of smart escalator systems worldwide. Transit infrastructure investments in Southeast Asia and the Middle East are redirecting procurement flows toward these manufacturing bases. Regulatory divergence across national safety regimes continues to fragment certification requirements.
China
Metro rail expansions in Shanghai and Beijing are driving concentrated demand for high-capacity installations. SAMR enforces GB 16899 safety standards that mandate sensor redundancy and emergency braking protocols in all public facilities. The Yangtze River Delta manufacturing corridor produces traction motor systems for domestic transit authorities and export markets.
Germany
Industrial machinery heritage anchors precision engineering capabilities for European transit projects. CE marking requirements under the EU Machinery Directive filter non-compliant suppliers from procurement channels. The Ruhr industrial cluster hosts control system specialists serving airport modernization programs across the continent.
United States
Federally funded transit projects through the Department of Transportation prioritize accessibility-compliant specifications. FAA coordination with airport authorities shapes escalator requirements for 24-hour operational environments. New York City's MTA faces extended retrofitting timelines as century-old station configurations require structural modifications.
Japan
High-frequency rail corridors in Tokyo and Osaka demand heavy-duty traction motors rated for continuous operation cycles. METI industrial standards influence regional procurement specifications for energy recovery systems. The Kansai manufacturing base supplies brushless DC motor technologies to Southeast Asian transit developments.
Singapore
Changi Airport's Terminal 5 expansion mandates dual-channel safety architectures with real-time diagnostic connectivity. Building and Construction Authority codes enforce strict uptime guarantees for critical infrastructure. The city-state's procurement specifications serve as reference standards for Jakarta and Bangkok airport developments.
Smart Escalator Market Vendor Landscape
Concentration sits with integrated system providers possessing in-house traction motor manufacturing and predictive maintenance platforms. The vendor base spans three tiers: full-stack elevator-escalator conglomerates with global service networks; regional specialists focused on transit authority contracts; and component suppliers licensing control system technologies. Dominant competitive moves include vertical integration into sensor manufacturing and strategic partnerships with airport operators for lifecycle service contracts.
Within the full-stack tier, Otis Worldwide Corporation, KONE Corporation, and Mitsubishi Electric Corporation exemplify the engineering-to-service model that transit authorities favor for complex installations. These entities occupy positions where Nordic engineering heritage, specialized maintenance analytics, and Asia-Pacific rail corridor expertise respectively anchor regional procurement preferences.
| Leading Market Players |
|---|
| Otis Worldwide Corporation |
| KONE Corporation |
| Schindler Group |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Thyssenkrupp Elevator |
| Hyundai Elevator |
| Fujitec |
| TK Elevator |
| Others |
Supply Flow & Price Mechanics
China's GB 16899 safety mandates gate both supplier qualification and price differentiation simultaneously, as transit authorities filter procurement toward certified system integrators who absorb compliance documentation costs into premium-tier positioning while non-compliant vendors face exclusion from public infrastructure channels.
Pricing Analysis
GB 16899 dictates the pricing tier structure across installation categories, with certified system integrators commanding premium positioning against component vendors locked out of transit authority procurement. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive maintenance bundles from basic sensor arrays from unconnected legacy replacements. Cost compression in the economy tier is intensifying because copper and rare earth input volatility squeezes traction motor manufacturers. Shopping mall developers exhibit the highest price sensitivity as capital expenditure constraints dominate aesthetic integration decisions, while airport authorities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of rare earth elements and copper windings dominates inventory strategy over just-in-time preferences, as traction motor manufacturers buffer against commodity price swings that would otherwise destabilize project quoting. Supply concentration centers on China, Germany, and Japan for brushless DC motor production, control system engineering, and precision sensor manufacturing respectively. Manufacturing draws from copper windings, neodymium magnets, and silicon steel laminations as critical inputs. Single-source vulnerability in rare earth processing creates structural exposure to export restriction shocks. Distribution runs through certified system integrators who bundle installation, commissioning, and lifecycle service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart escalator market represents a high-growth disruption anchored by AI-IoT convergence, as machine learning algorithms layered on sensor arrays compress traditional reactive maintenance models into predictive uptime guarantees that reshape procurement specifications across transit infrastructure.
For Market Incumbents: Compound defensive positioning through in-house production of sensor arrays and traction motors to capture margin pools eroding to component suppliers, while accelerating certification investment in China's SAMR compliance documentation to lock out emerging competitors from Shanghai and Beijing metro expansions. Priority consolidation moves include backward integration into rare earth magnet supply chains and captive control system development to neutralize copper price volatility exposure. For New Entrants and Emerging Players: CE marking fast-track pathways enable market entry into European commercial real estate portfolios where facility management firms unbundle predictive analytics from physical maintenance labor. White-space targets concentrate on India's underpenetrated metro rail networks and Southeast Asian airport developments from Bangkok to Jakarta. Go-to-market positioning emphasizes modular sensor retrofit kits that minimize structural modification requirements for aging infrastructure obsolescence deadlines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered predictive maintenance platforms as algorithm development and sensor array integration demand specialized engineering talent pools. Long-term viability favors vertically integrated specialists with in-house traction motor manufacturing and certified service networks over pure-play component licensors. Acquisition target archetypes include regional maintenance analytics platforms with established transit authority relationships. The signal to watch is GB 16899 compliance deadline acceleration triggering consolidation among non-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Array Backward Integration | In-house production of GB 16899-compliant redundant architectures locks out component-dependent competitors from transit authority procurement. |
| Predictive Maintenance Platform Launch | Machine learning algorithms tied to measurable uptime outcomes displace transactional service contracts in German and French office portfolios. |
| India Transit Authority Partnership | Metro rail network expansion in underpenetrated corridors creates first-mover positioning for lifecycle service bundling. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors neutralize commodity volatility exposure in traction motor manufacturing. |
| CE Marking Fast-Track Certification | Accelerated EU Machinery Directive compliance filters non-certified competitors from European commercial real estate channels. |
Methodological Framework
The analysis maps IoT integration architectures, AI-powered predictive systems, energy-efficient variable frequency drives, and sensor redundancy configurations, each validated through primary interviews with transit authority procurement directors, elevator-escalator maintenance technicians, airport infrastructure planners, and facility management executives, cross-referenced against secondary sources including SAMR GB standard filings, EU Machinery Directive compliance databases, FAA accessibility coordination memos, and SEC 10-K disclosures from listed equipment manufacturers, with bottom-up installation volume estimates triangulated against top-down market value reconstructions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling technology adoption curves, end-user procurement concentration by facility type, installation mode preferences, and regional regulatory cluster divergence. CAGRs were derived from segmented growth trajectory analysis incorporating metro rail expansion pipelines, airport modernization capex cycles, and commercial corridor development timelines as industry-specific forecast inputs.
Underlying assumptions cover copper and rare earth price stability, certification deadline enforcement consistency, and transit infrastructure funding continuity, with deviation risk concentrated in raw material input volatility and multi-jurisdiction safety protocol fragmentation. Revision becomes warranted when GB 16899 compliance acceleration or rare earth export restriction intensity crosses thresholds that would fundamentally alter supplier qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Sortation Systems Market