
 Europe Water Automation and Instrumentation Market | 2026-2036
Europe Water Automation and Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Automation and Instrumentation Market Foresight
CE marking under the EU Measuring Instruments Directive is rotating vendor eligibility across the Europe Water Automation and Instrumentation landscape, forcing recertification cycles that favor incumbents with dedicated compliance labs. ABB Ltd leverages its integrated automation portfolio to anchor large municipal SCADA contracts in Northern Europe. Endress+Hauser specializes in flow measurement calibration services that sustain premium positioning among industrial water users. Siemens AG competes through digital twin platforms that extend hardware margins into recurring software revenue streams.
Europe water automation and instrumentation encompasses sensor networks, control systems, and telemetry infrastructure that measure, transmit, and act upon hydraulic parameters in real time; core specifications include IP68-rated submersible pressure transmitters operating at depths exceeding 100 meters and electromagnetic flow meters achieving accuracy within 0.2% of reading. The primary commercial purpose centers on optimizing water distribution efficiency, ensuring regulatory compliance, and minimizing non-revenue water losses across municipal and industrial infrastructure. Flow meters and quality analyzers command the deepest margin pools where calibration traceability requirements create sticky supplier relationships. IoT Solutions within the technology dimension are expanding fastest as cellular LPWAN coverage reaches smaller utility operators previously locked out of real-time monitoring. Municipalities dominate end-user demand but industrial users generate higher per-site instrumentation spend due to complex effluent monitoring obligations.
The EU Urban Wastewater Treatment Directive, the F-Gas Regulation affecting cooling systems in instrumentation enclosures, and national implementations of the Water Framework Directive shape product specifications and procurement criteria across member states. EMA and national regulators like Germany's KBA do not directly govern this sector, but ECHA's REACH restrictions on sensor materials and the EU AI Act's emerging requirements for automated decision systems in critical infrastructure are tightening component sourcing and algorithm validation protocols. Stakeholders must monitor whether the EU Green Deal's forthcoming water resilience standards will mandate predictive maintenance capabilities that favor vendors with embedded analytics over pure hardware suppliers.
Market Dynamics
The EU Green Deal's water resilience targets are forcing utilities to replace reactive maintenance with predictive systems, compressing replacement cycles for aging instrumentation across municipal distribution networks.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Municipal utilities in Germany are accelerating SCADA deployments to meet stricter discharge monitoring mandates, creating pull-through demand for integrated sensor networks.
- Cellular LPWAN expansion:Smaller utility operators in France's industrial corridor are accessing real-time telemetry previously limited to large metropolitan systems.
- Industrial effluent obligations:Chemical processors face tightened discharge monitoring requirements that sustain premium positioning for calibration-traceable flow measurement services.
Market Restraints
- CE marking recertification cycles:The EU Measuring Instruments Directive is rotating vendor eligibility, forcing dedicated compliance lab investments that favor incumbents and raise barriers for new entrants.
- REACH material restrictions:ECHA's constraints on sensor materials are tightening component sourcing protocols and extending R&D timelines for next-generation transmitters.
- Legacy infrastructure lock-in:Aging distribution networks in Southern Europe lack the digital backbone to support advanced automation, limiting addressable market expansion.
Strategic Opportunities
- Digital twin convergence:Platforms combining hydraulic modeling with live sensor feeds are extending hardware margins into recurring software revenue streams among Northern European utilities.
- Poland's underpenetrated municipal sector:EU cohesion funding is enabling first-time automation deployments in water districts previously reliant on manual monitoring.
- F-Gas Regulation tailwinds:Cooling system retrofits in instrumentation enclosures are creating replacement demand for thermally optimized control cabinets.
Industry Challenges
- Calibration technician scarcity:Specialized flow measurement expertise is concentrating among incumbent service providers, constraining deployment velocity for complex industrial installations.
- Algorithm validation protocols:The EU AI Act's emerging requirements for automated decision systems in critical infrastructure are extending commissioning timelines for smart metering deployments.
- Interoperability fragmentation:Proprietary communication protocols between legacy SCADA layers and new IoT sensor networks are forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Automation and Instrumentation Market |
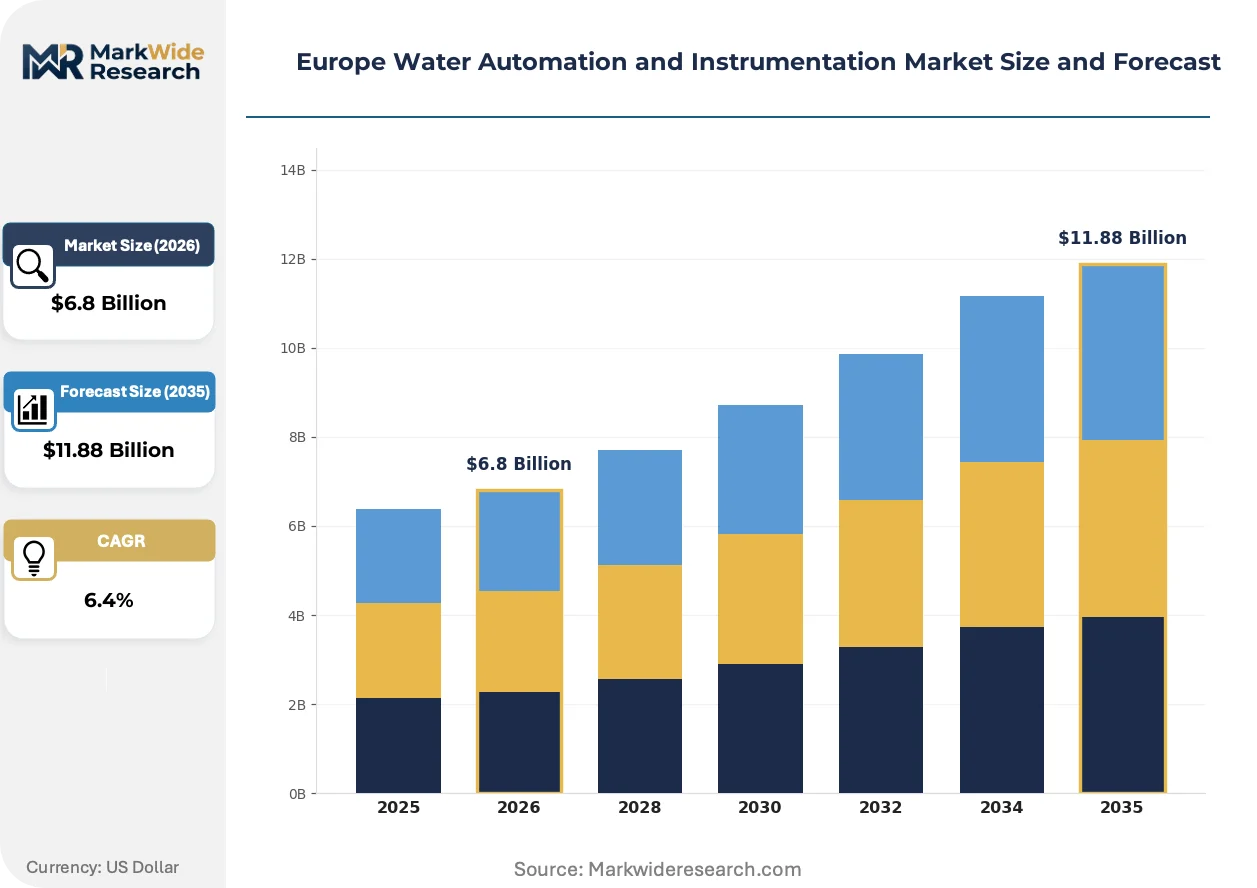
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Meters, Level Sensors, Pressure Transmitters, Quality Analyzers End User: Municipalities, Water Treatment Facilities, Industrial Users, Agricultural Applications Technology: SCADA Systems, PLCs, IoT Solutions, Remote Monitoring Application: Water Distribution, Wastewater Management, Process Control, Environmental Monitoring |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Rockwell Automation Inc, Mitsubishi Electric Corporation, Emerson Electric, Yokogawa Electric Corporation, Endress+Hauser, KROHNE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Automation and Instrumentation Market Shifts & Advancements
Cellular LPWAN coverage expansion is democratizing real-time water monitoring, while regulatory pressure on non-revenue water losses is accelerating sensor density in distribution networks.
Electromagnetic flow meters achieving accuracy within 0.2% of reading are supplanting mechanical turbine designs in municipal billing applications. German utilities are adopting these solid-state devices at compressed replacement cycles to minimize measurement disputes. The shift is compressing maintenance revenue pools while expanding upfront hardware margins.
The EU AI Act's requirements for automated decision systems in critical infrastructure are mandating algorithm validation protocols for smart leak detection platforms. Industrial water users in France's chemical corridor face the steepest compliance burdens as they deploy predictive maintenance systems. Vendors are responding by embedding explainable AI modules that document decision pathways for regulator audit trails.
Service unbundling is fragmenting traditional hardware-plus-maintenance contracts into discrete calibration, software, and telemetry subscriptions. Municipal procurement teams in the Netherlands are pioneering outcome-based fee structures tied to non-revenue water reduction targets. This restructuring is most visible among mid-sized utilities seeking to transfer operational risk to instrumentation vendors.
Europe Water Automation and Instrumentation Market Segmentation
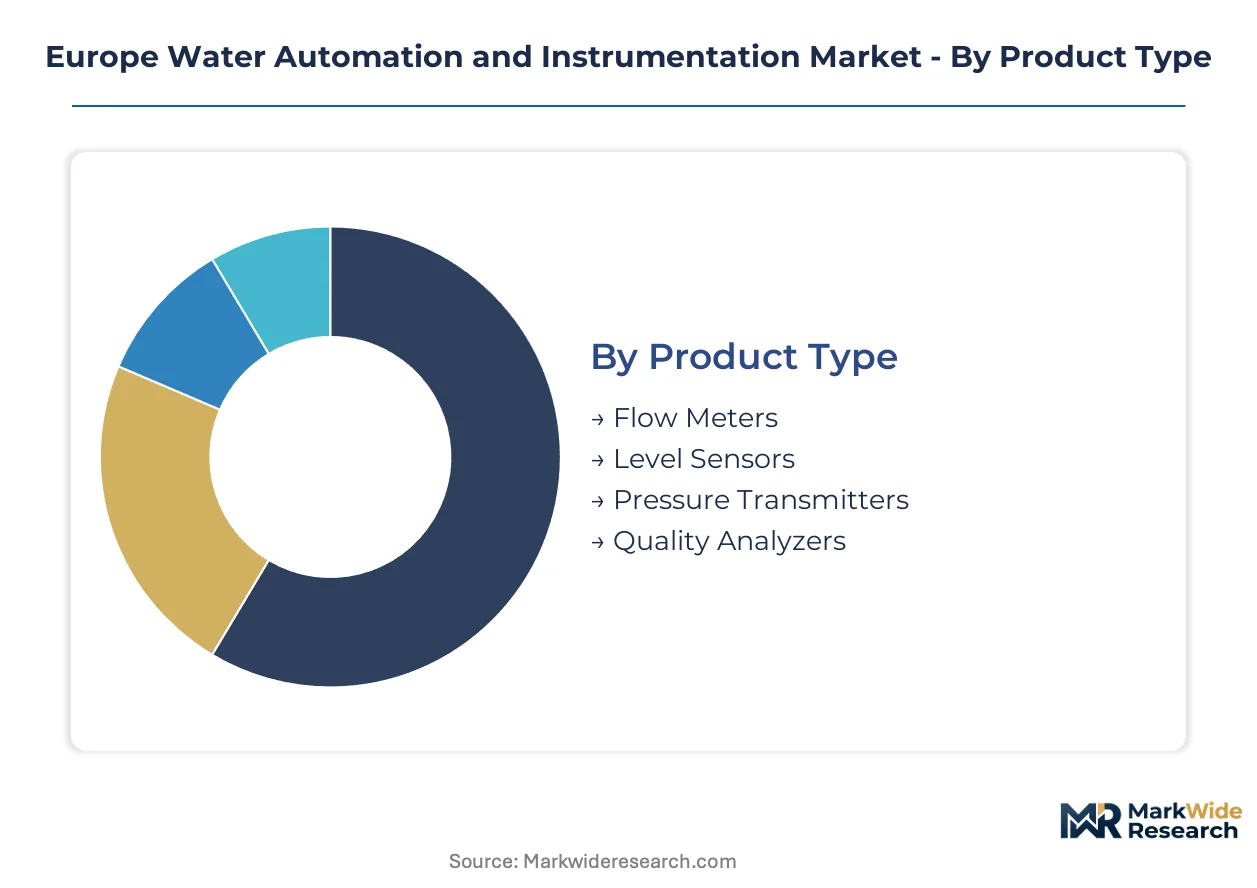
Segmentation in Europe water automation and instrumentation reveals distinct procurement patterns between municipal utilities seeking compliance-driven replacements and industrial operators pursuing predictive capabilities. Understanding these divides clarifies where hardware margins concentrate versus where software subscriptions gain traction.
Product Type:
Flow meters and quality analyzers dominate export-led demand from German and Swiss manufacturing bases, while level sensors and pressure transmitters serve more localized municipal retrofit cycles across Southern Europe.
- Flow Meters:Electromagnetic designs achieving 0.2% accuracy are displacing mechanical turbines in German municipal billing applications. Dutch utilities are compressing replacement cycles to minimize measurement disputes and non-revenue water losses.
- Quality Analyzers:Multi-parameter probes measuring pH, turbidity, and dissolved oxygen face tightened calibration traceability requirements under the EU Measuring Instruments Directive. French chemical processors in the Lyon corridor sustain premium positioning for validation-ready analyzer services.
- Level Sensors:Ultrasonic and radar technologies serve reservoir and tank monitoring across Polish water districts receiving EU cohesion funding for first-time automation.
- Pressure Transmitters:IP68-rated submersible units operating beyond 100 meters depth anchor leakage detection networks in aging Belgian distribution infrastructure.
Flow meters command the established base. The steepest expansion runs through quality analyzers.
End User:
Cost tier stratification separates high-complexity industrial installations from standardized municipal deployments, with agricultural applications emerging as a price-sensitive volume segment.
- Industrial Users:Chemical processors and food manufacturers face complex effluent monitoring obligations under the EU Urban Wastewater Treatment Directive. Per-site instrumentation spend exceeds municipal benchmarks by substantial multiples due to calibration-intensive analyzer requirements.
- Municipalities:German water utilities are accelerating SCADA deployments to meet stricter discharge mandates, creating pull-through demand for integrated sensor networks. Procurement concentrates in Northern Europe where digital infrastructure supports real-time telemetry.
- Water Treatment Facilities:Specialized plants serving industrial parks require redundant measurement chains for regulatory compliance.
- Agricultural Applications:Irrigation districts in Spain and Italy are adopting basic flow monitoring as drought resilience measures intensify.
Industrial users capture the highest per-site value. Municipalities provide the deepest volume base.
Technology:
Technology maturity curves diverge sharply, with legacy SCADA systems defending installed bases while IoT Solutions penetrate previously unserved smaller operators.
- IoT Solutions:Cellular LPWAN coverage expansion is democratizing real-time monitoring for French utility operators below 50,000 connections. Battery-powered sensors with 10-year lifespans are eliminating trenching costs that previously locked out smaller municipalities.
- SCADA Systems:Integrated control platforms anchor large municipal contracts across Northern Europe, though proprietary protocols create interoperability friction with emerging IoT sensor networks.
- PLCs:Programmable logic controllers remain embedded in industrial process control loops where millisecond response times are mandatory.
- Remote Monitoring:Cloud-based dashboards are unbundling from hardware contracts into discrete telemetry subscriptions among Dutch mid-sized utilities.
SCADA retains the installed base dominance. IoT Solutions are climbing the fastest.
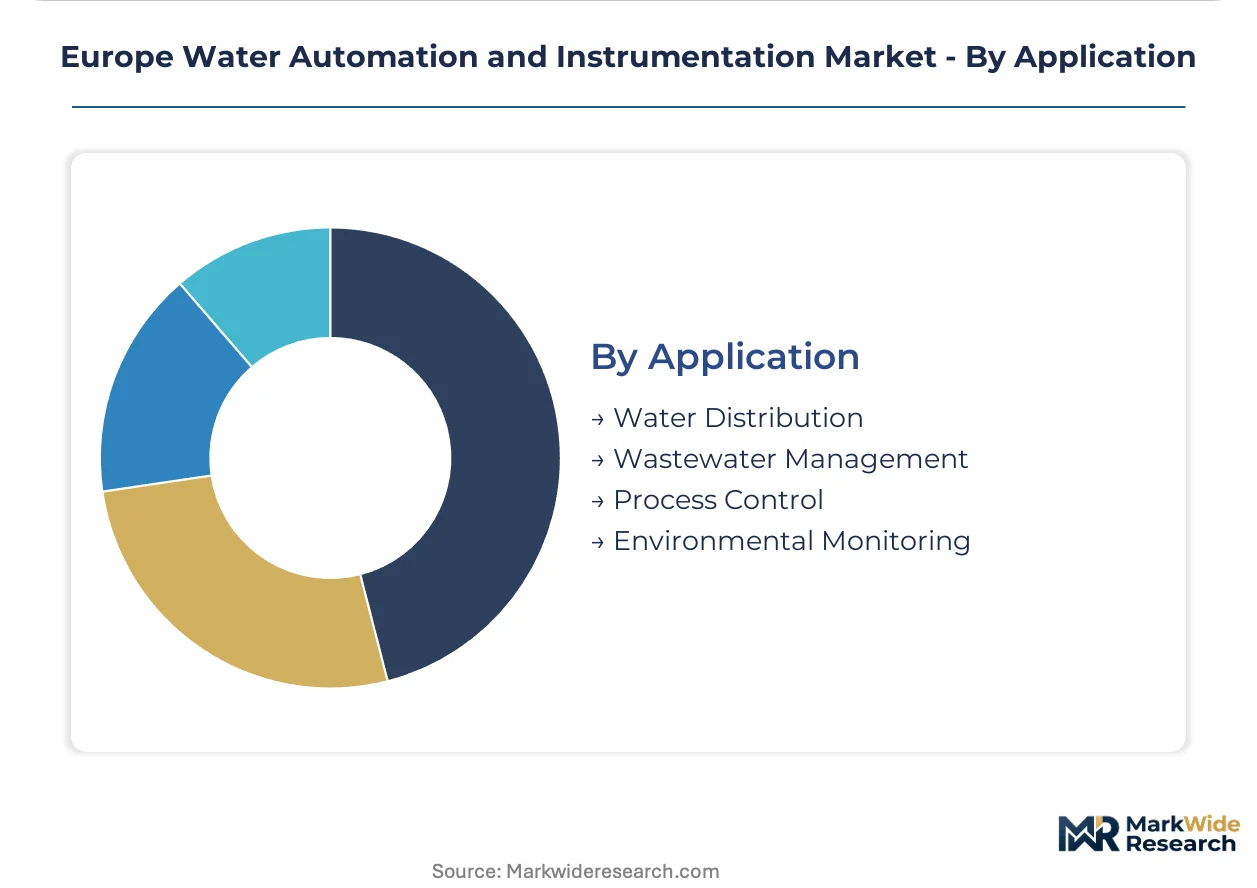
Application:
Application focus tracks regulatory pressure intensity, with wastewater management commanding stricter compliance burdens than distribution efficiency projects.
- Wastewater Management:Discharge monitoring mandates under the EU Urban Wastewater Treatment Directive are rotating vendor eligibility through CE marking recertification cycles. German utilities face the steepest compliance timelines for effluent quality reporting.
- Water Distribution:Non-revenue water reduction targets are accelerating sensor density in Belgian and Dutch networks. Smart leak detection platforms are embedding explainable AI modules to satisfy emerging EU AI Act validation protocols.
- Process Control:Industrial water recycling loops in France's chemical corridor require continuous analyzer feedback for closed-loop operation.
- Environmental Monitoring:River basin authorities under the Water Framework Directive are deploying telemetry for ecological status assessment.
Water distribution holds the broader deployment base. Wastewater management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's water resilience targets are channeling cohesion funding into municipal automation upgrades across member states with varying infrastructure maturity. National implementations of the Water Framework Directive and Urban Wastewater Treatment Directive are creating differentiated procurement timelines.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria are accelerating SCADA deployments to meet stricter KBA-monitored discharge mandates under the EU Urban Wastewater Treatment Directive. The country's measuring instruments regulator enforces CE marking recertification cycles that favor incumbents with dedicated compliance laboratories. Chemical processors in the Ludwigshafen corridor sustain premium demand for calibration-traceable flow measurement services.
France
Industrial water users in the Lyon and Rouen chemical corridors face tightened effluent monitoring obligations that compress replacement cycles for quality analyzers. ANSM-aligned calibration protocols are rotating vendor eligibility through the EU Measuring Instruments Directive. Mid-sized utilities in the Provence-Alpes-Côte d'Azur region are adopting cellular LPWAN telemetry for real-time leak detection.
Netherlands
Water boards in the Randstad are pioneering outcome-based procurement structures tied to non-revenue water reduction targets. The country's stringent implementation of the Water Framework Directive is mandating sensor density increases in aging distribution networks. Dutch municipalities are unbundling traditional hardware-plus-maintenance contracts into discrete software and calibration subscriptions.
Poland
EU cohesion funding is enabling first-time automation deployments in water districts surrounding Warsaw and Kraków previously reliant on manual monitoring. The national environmental regulator is aligning with EU Green Deal timelines for predictive maintenance capabilities. Polish utilities lack the digital backbone for full SCADA integration, creating demand for standalone IoT sensor networks.
Belgium
Walloon and Flemish water operators are deploying IP68-rated submersible pressure transmitters beyond 100 meters depth for leakage detection in aging distribution infrastructure. REACH restrictions on sensor materials are tightening component sourcing protocols for Brussels-based system integrators. The country's transposition of the F-Gas Regulation is driving cooling system retrofits in instrumentation enclosures.
Europe Water Automation and Instrumentation Market Competitive Landscape
Player mix skews toward diversified industrial automation conglomerates with dedicated water sector divisions. Consolidation pressure concentrates among incumbents possessing integrated SCADA portfolios and compliance laboratory infrastructure. Three archetypes dominate: full-stack automation providers, specialized flow measurement calibration services, and digital twin platform vendors. Competitive moves center on strategic partnerships for interoperability middleware and portfolio diversification into predictive analytics software layers.
Within the full-stack automation tier, ABB Ltd and Siemens AG exemplify positioning that anchors large municipal contracts through integrated control platforms. Endress+Hauser occupies a specialist position emphasizing calibration-traceable services that sustain premium relationships with industrial water users. These three Swiss and German entities represent the compliance-heavy, certification-driven competitive dynamic that CE marking recertification cycles under the EU Measuring Instruments Directive reinforce.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation Inc |
| Mitsubishi Electric Corporation |
| Emerson Electric |
| Yokogawa Electric Corporation |
| Endress+Hauser |
| KROHNE |
| Others |
Supply & Pricing Matrix
CE marking recertification cycles under the EU Measuring Instruments Directive simultaneously gate vendor qualification and stratify price tiers across European water automation markets. German utilities pay substantial premiums for calibration-traceable instrumentation from incumbents possessing dedicated compliance laboratories, while Polish municipalities sourcing first-time automation face compressed budgets that favor unbundled hardware procurement.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with CE-marked electromagnetic flow meters commanding substantial premiums over non-certified alternatives in German municipal billing applications. Three-tier pricing structure across premium, standard, and economy levels reflects calibration traceability depth and software bundling intensity. Cost compression in economy-tier pressure transmitters is intensifying because REACH material restrictions are extending R&D timelines for next-generation sensors. Industrial water users in France's chemical corridor exhibit the lowest price sensitivity due to complex effluent monitoring obligations, while agricultural irrigation districts in Southern Europe prioritize upfront hardware cost minimization over service bundling.
Supply Chain Analysis
Strategic stockpiling of IP68-rated sensor housings and rare-earth magnet assemblies dominates inventory strategy among German and Swiss instrumentation manufacturers facing extended lead times for REACH-compliant materials. Component sourcing concentrates in Germany, Switzerland, and the Netherlands for precision flow measurement assemblies, while battery-powered IoT sensor modules draw from Taiwanese and South Korean electronics suppliers. Single-source vulnerability in rare-earth magnet supply creates exposure to commodity price volatility for electromagnetic flow meter producers. Distribution runs through authorized system integrators in Northern Europe and direct municipal procurement channels in cohesion-funded Polish districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European water automation sits in early-cycle expansion as cellular LPWAN coverage democratizes real-time monitoring for utility operators below 50,000 connections previously locked out of telemetry infrastructure.
For Market Incumbents: Consolidate calibration service capabilities through captive laboratory investments that defend margin position against emerging IoT-native entrants unburdened by legacy SCADA protocol obligations. Prioritize backward integration into sensor material supply chains to mitigate REACH restriction exposure and compress R&D cycle times for next-generation transmitters. For New Entrants and Emerging Players: Calibration-as-a-service gaps among mid-sized French utilities create immediate white-space opportunity where incumbent response times lag predictive maintenance demands. Poland's underpenetrated municipal sector offers the most penetrable geography for standalone IoT sensor networks bypassing full SCADA integration requirements. Pursue outcome-based fee structures tied to non-revenue water reduction targets to differentiate from hardware-centric procurement patterns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital twin platform development as software subscriptions displace transactional hardware margins in Northern European utility contracts. Target acquisition archetypes include specialized flow measurement calibration services with sticky industrial relationships and embedded analytics vendors with EU AI Act-compliant validation protocols. Watch for algorithm audit trail standardization as the signal indicating predictive maintenance capability maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | CE marking recertification cycles favor incumbents with captive compliance infrastructure in Germany. |
| IoT Sensor Network Deployment | Cellular LPWAN coverage reaches Polish municipalities previously dependent on manual monitoring. |
| Digital Twin Platform Integration | Siemens and ABB extend hardware margins into recurring software revenue across Dutch water boards. |
| REACH-Compliant Material Sourcing | ECHA restrictions on sensor materials tighten component protocols for Belgian system integrators. |
| Explainable AI Module Development | EU AI Act validation requirements mandate documented decision pathways for French leak detection platforms. |
Research Methodology
Initial hypotheses were tested against primary input from municipal utility planning officers, industrial water treatment engineers, SCADA integration specialists, and calibration service technicians and refined through secondary validation against EU Urban Wastewater Treatment Directive implementation timelines, ECHA REACH restriction updates, national water board procurement databases, and CE marking recertification records. Bottom-up unit economics from sensor deployment projects were triangulated against top-down market sizing derived from cohesion funding allocation patterns.
Variance decomposition across product type, end-user complexity tier, technology maturity curve, and application regulatory intensity shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, first-time automation penetration rates in underpenetrated districts, and software subscription conversion trajectories among Northern European utilities. Forecast inputs incorporated cellular LPWAN coverage expansion maps, EU Green Deal water resilience standard drafting progress, and predictive maintenance capability adoption curves.
Forecasts assume regulatory continuity in EU Measuring Instruments Directive enforcement and EU AI Act algorithm validation protocols; material policy shifts would require re-modeling. Revision becomes warranted when F-Gas Regulation cooling system retrofit mandates or REACH material restriction expansions cross implementation thresholds that compress hardware replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
North America Factory Automation and Industrial Controls Market