
 Food Grade Sodium Hydroxide Market | 2026-2036
Food Grade Sodium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sodium Hydroxide Market Foresight
Multi-source procurement toward captive chlor-alkali output is recalibrating how food-grade caustic soda reaches downstream buyers. Dow Chemical Company leverages integrated membrane-cell capacity to sustain cost-advantaged supply to North American beverage bottlers. BASF SE anchors European distribution through dedicated food-certification logistics, while Tata Chemicals competes on bulk liquid deliveries to tropical-market processors.
Food grade sodium hydroxide designates sodium hydroxide meeting purity standards for incidental food contact, typically manufactured via membrane electrolysis to minimize mercury or asbestos contamination and delivered at concentrations from 50% liquid to 99% solid forms for pH adjustment, cleaning-in-place protocols, and peeling operations. Flake and pellet formats dominate margin pools due to handling precision in automated dosing systems, while liquid supply leads volume through direct tanker delivery to large beverage manufacturing sites. Application segmentation shows food processing and pH regulation commanding the bulk of offtake, with cleaning agents representing a mature, price-sensitive tier.
FDA food-contact substance notifications and REACH Annex XVII restrictions on heavy-trace impurities shape formulation standards and market access conditions for imported material. BIS certification requirements in India and EFSA purity specifications in Europe further fragment compliance pathways across supply corridors. Stakeholders must monitor regulatory divergence on allowable trace-metal thresholds when qualifying new sourcing regions.
Market Dynamics
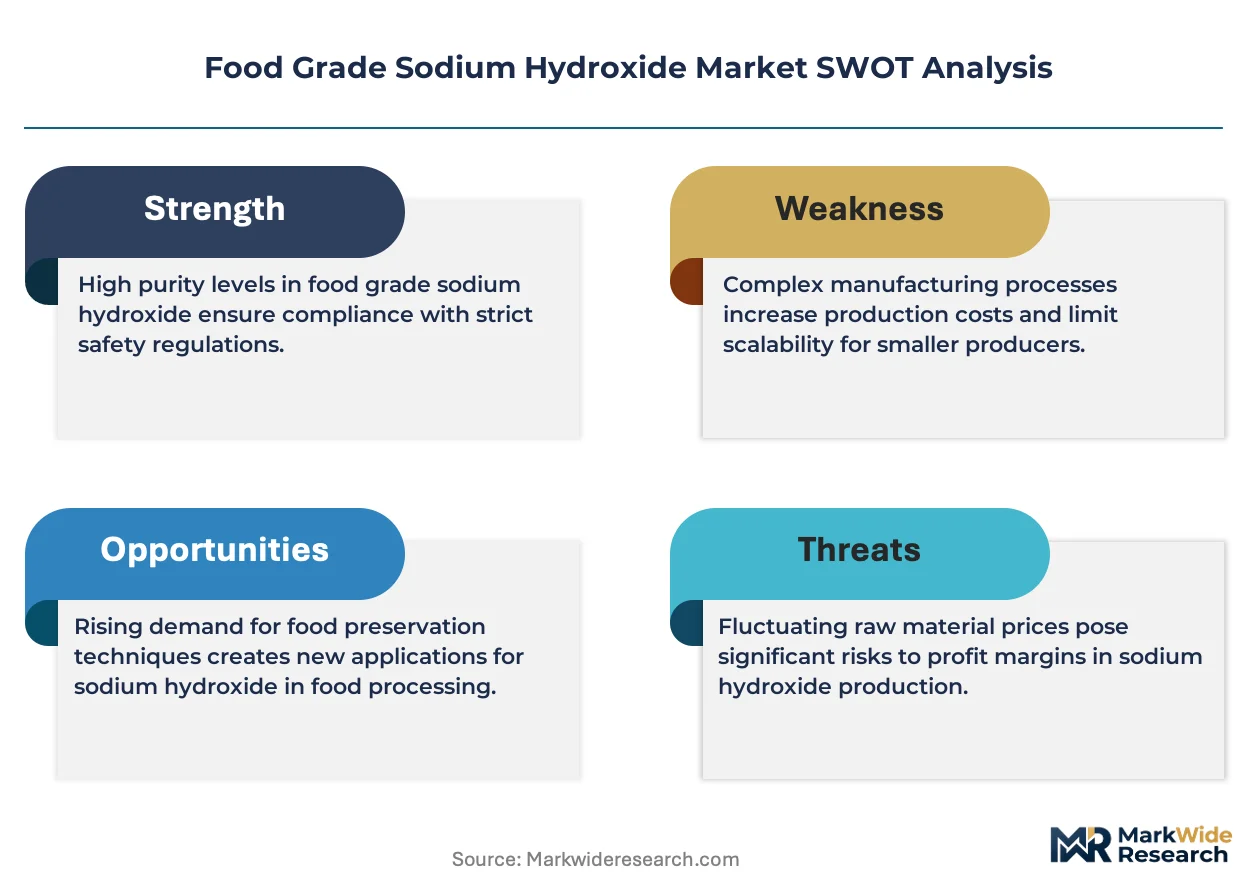
Membrane-cell chlor-alkali technology is consolidating production economics while REACH and FDA purity mandates fragment compliance pathways across supply corridors. This structural tension between scale efficiency and certification complexity defines competitive positioning in food-grade caustic soda.
Growth Catalysts
- REACH Annex XVII heavy-metal thresholds:Tightening purity specifications in Europe are disqualifying merchant-grade suppliers and redirecting bakery and confectionery processors toward certified food-grade supply chains with documented mercury-free membrane electrolysis.
- Cleaning-in-place automation:Dairy and beverage manufacturing lines are expanding caustic soda dosing for equipment sanitation protocols, particularly in Germany where flake format precision supports automated pH adjustment systems.
- India FSSAI food-additive notifications:Formal recognition of sodium hydroxide as a permitted processing aid is opening import corridors for certified material into tropical-market fruit peeling and cocoa processing operations.
Market Restraints
- Salt and electricity input volatility:Chlor-alkali production economics remain exposed to energy cost swings, compressing margin buffers for merchant producers without captive power or integrated salt sourcing.
- Supply concentration in coastal industrial clusters:Production gravity along US Gulf Coast and Rotterdam-Antwerp corridor creates hurricane and logistics disruption exposure for North American and European buyers.
- Substitute alkaline agents:Potassium hydroxide and sodium carbonate formulations are displacing caustic soda in select beverage pH adjustment applications where potassium labeling appeals to clean-label positioning.
Strategic Opportunities
- Brazil ANVISA pharmaceutical-grade crossover:Underpenetrated Latin American markets present white space for suppliers holding dual food-pharma certifications to serve emerging plant-based protein processing clusters.
- EU Green Deal industrial decarbonization incentives:Renewable-powered membrane-cell installations qualify for carbon border adjustment exemptions, creating cost-advantaged positioning for low-carbon caustic soda in European food processing.
- Direct tanker-to-silo distribution:Bulk liquid delivery bypassing traditional distributor networks is capturing large beverage bottlers seeking volume certainty and reduced handling steps.
Industry Challenges
- Membrane-cell technical certification timelines:FDA food-contact substance notification pathways for new production facilities extend 18-24 months, delaying market entry for emerging suppliers.
- Trace-metal testing capability scarcity:Third-party laboratories capable of ICP-MS analysis to REACH and EFSA heavy-metal specifications are concentrated in Germany and the Netherlands, creating qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sodium Hydroxide Market |
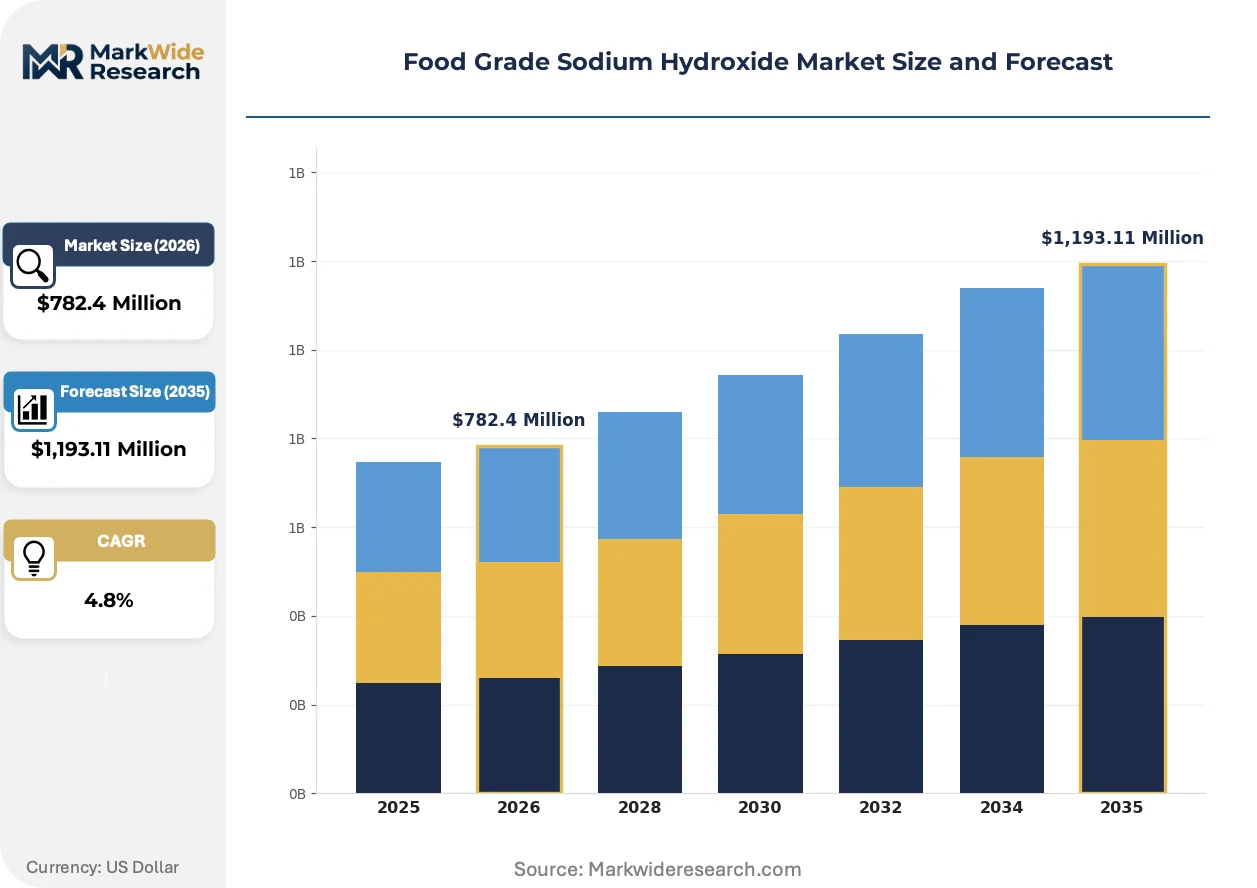
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,193.11 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pellets, Liquid, Prills Application: Food Processing, Beverage Manufacturing, Cleaning Agents, pH Regulation, Chemical Processing End User Industry: Bakery, Confectionery, Catering Services, Beverage Producers, Food Packaging Packaging Type: Drums, Bags, Bulk Containers, Intermediate Bulk Containers |
| Companies Covered | AkzoNobel, Tata Chemicals, Dow Chemical Company, Shin-Etsu Chemical, Formosa Plastics Corporation, BASF SE, Solvay, Tosoh Corporation, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sodium Hydroxide Market Shifts & Advancements
Electrochemical process intensification and regulatory digitization are compressing traditional supply chain structures. Three developments are actively restructuring how food-grade caustic soda reaches downstream processors.
Oxygen-depolarized cathode technology is electrifying chlor-alkali energy economics by cutting electricity consumption roughly 30% versus conventional membrane cells. European chemical producers with carbon-neutral power purchase agreements are deploying this at Rotterdam and Ludwigshafen sites. The technology is compressing cost curves for low-carbon caustic soda and threatening merchant producers without process upgrade pathways.
REACH SCIP database requirements for article-level substance disclosure are forcing food-equipment manufacturers to document caustic soda contact points across processing lines. German packaging machinery OEMs are now demanding batch-level certificates of analysis from chemical suppliers. This regulatory layer is segmenting the market between documentation-capable integrated producers and commodity traders.
Consolidated procurement through chemical management services is displacing spot purchasing among multinational beverage and dairy processors. Unilever and Nestlé manufacturing sites in France and Italy are contracting integrated supply-and-dosing service providers rather than buying commodity caustic soda. This channel shift is squeezing independent distributors and favoring producers with technical service capabilities and regional logistics density.
Food Grade Sodium Hydroxide Market Segmentation
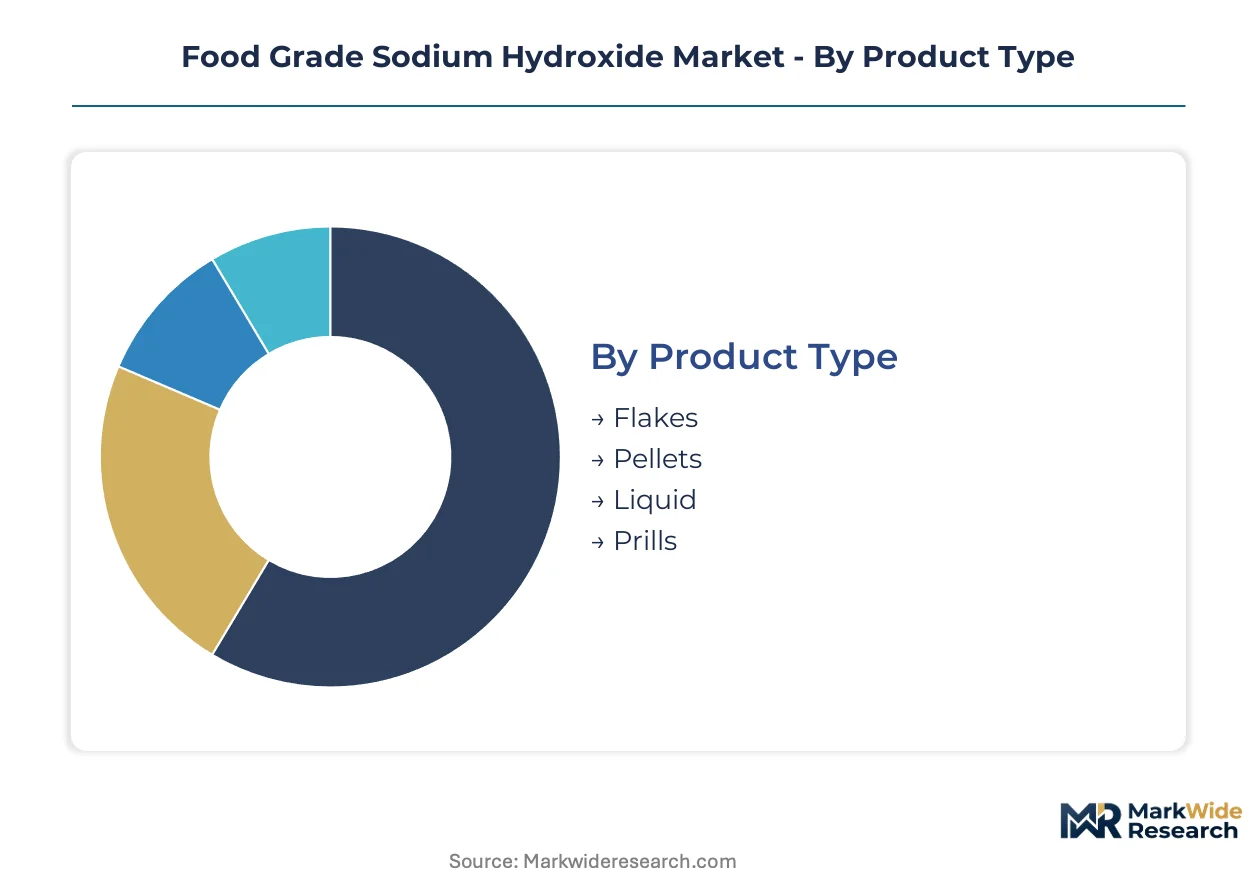
Physical form and handling precision determine procurement economics for food-grade sodium hydroxide buyers. Each segmentation dimension reveals distinct margin structures, regulatory exposure, and logistics requirements that shape supplier selection criteria across processing applications.
Product Type:
Buyers differentiate primarily by dosing automation compatibility and storage infrastructure investment.
- Flakes:Thin, brittle sheets dissolve rapidly in controlled-temperature water systems. German bakery and confectionery manufacturers favor this format for automated pH adjustment lines requiring precise gram-level dosing.
- Pellets:Dense, spherical granules minimize dust generation during pneumatic conveying. Beverage bottlers in tropical climates specify pellets for reduced caking in humid storage conditions.
- Liquid:Pre-diluted 50% concentration eliminates dissolution equipment for large-volume users. Direct tanker delivery to dairy processing sites captures economies of scale.
- Prills:Small, porous beads offer intermediate dissolution rates between flakes and pellets. Limited adoption in food applications due to higher residual moisture content.
Volume sits with liquid for industrial-scale beverage operations; growth tilts toward flake and pellet formats as automated dosing systems penetrate mid-size processing facilities.
Application:
Regulatory classification intensity varies sharply across use cases, with food-contact approvals commanding premium positioning.
- Food Processing:Direct ingredient applications include olive curing, cocoa alkalization, and pretzel glazing. REACH Annex XVII mercury thresholds disqualify non-membrane electrolysis material from European supply chains.
- Beverage Manufacturing:pH adjustment in soft drink and bottled water production requires documented heavy-metal testing to FDA food-contact substance standards. German mineral water producers specify certified flake supply.
- Cleaning Agents:Clean-in-place protocols for dairy equipment represent mature, price-sensitive demand. Merchant-grade material competes aggressively here.
- pH Regulation:Secondary processing aid status in cheese making and caramel production demands lower documentation burden than direct food-contact applications.
- Chemical Processing:Food-grade specification occasionally extends to pharmaceutical intermediates where dual certification opens crossover revenue streams.
Food processing commands absolute volume; beverage manufacturing climbs the fastest as clean-label positioning intensifies pH control precision requirements.
End User Industry:
Scale concentration and certification sophistication create distinct procurement behavior across buyer categories.
- Bakery:Pretzel and bagel alkaline baths require consistent flake quality for surface browning reactions. German craft bakeries favor 25kg bag formats.
- Confectionery:Cocoa powder alkalization demands precise pH targeting for color and flavor development. Swiss chocolate processors specify ultra-low heavy-metal thresholds.
- Catering Services:Institutional kitchen cleaning applications represent fragmented, distributor-dependent demand with minimal certification requirements.
- Beverage Producers:Carbonated soft drink and bottled water acid neutralization drives bulk liquid procurement through chemical management service contracts.
- Food Packaging:Equipment sanitation for aseptic filling lines requires documented batch certificates under REACH SCIP database protocols.
Beverage producers dominate procurement volumes; confectionery generates the steepest margin expansion through premium certification tiers.
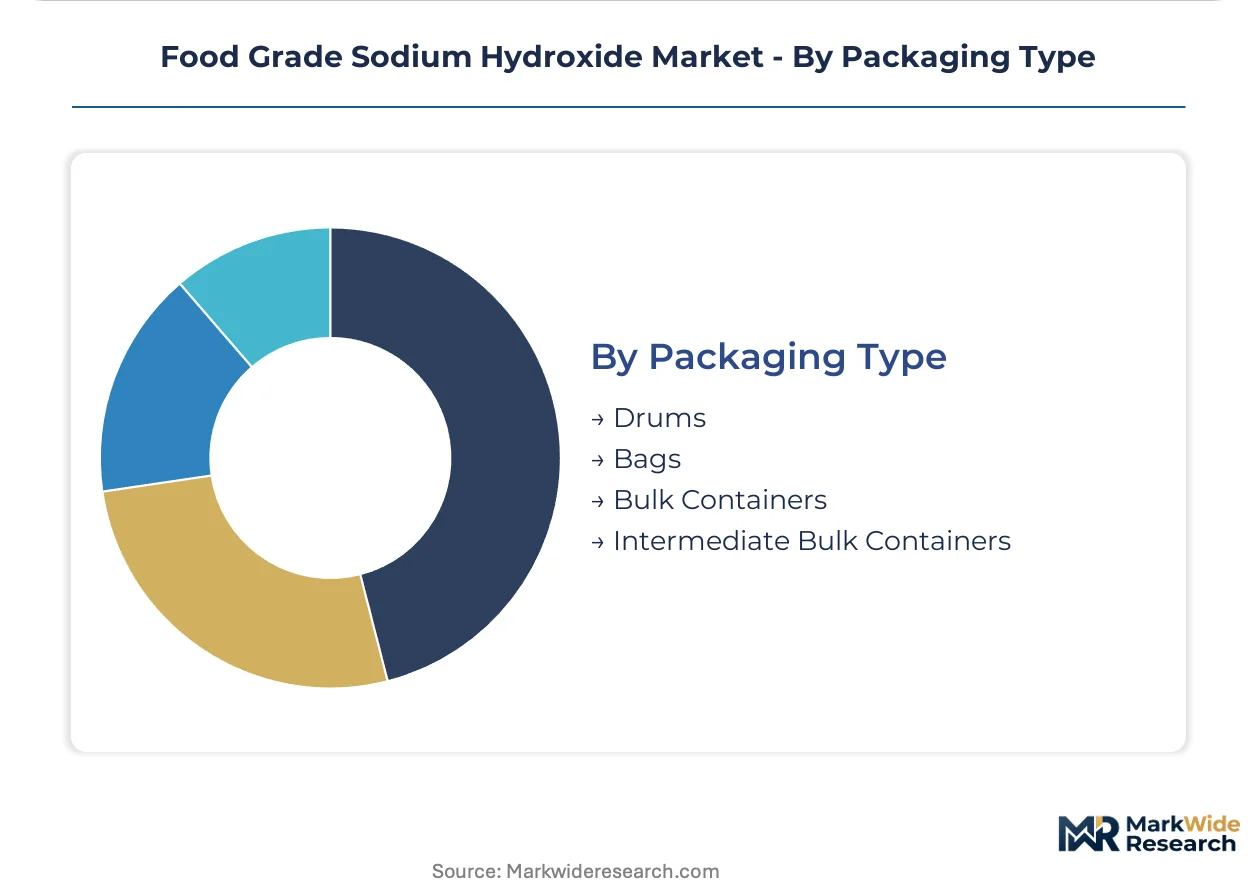
Packaging Type:
Logistics density and handling automation determine format selection across customer scale tiers.
- Drums:200-liter steel containers serve mid-size processors lacking bulk storage infrastructure. Higher per-kilogram cost reflects manual handling requirements.
- Bags:25kg multi-layer paper sacks dominate artisan bakery and small confectionery procurement. German distributors maintain regional warehouse stock for rapid replenishment.
- Bulk Containers:Flexible intermediate bulk containers capture mid-scale beverage operations transitioning from drums toward tanker delivery.
- Intermediate Bulk Containers:Rigid IBC totes with integrated dispensing systems reduce contamination risk for high-frequency users in automated processing lines.
Bulk liquid tanker deliveries capture the largest volume flows; bag and drum formats retain defensive positioning in fragmented artisan processing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt dome deposits along the US Gulf Coast anchor chlor-alkali production economics for food-grade sodium hydroxide supply chains. Membrane-cell capacity clusters in Texas and Louisiana feed North American beverage bottlers through direct tanker networks.
United States
Dairy processing expansion in Wisconsin and California drives flake format demand for automated clean-in-place systems. FDA food-contact substance notifications govern heavy-metal documentation for domestic supply chains. Houston-Galveston corridor membrane-cell facilities supply bulk liquid to Coca-Cola and PepsiCo bottling sites.
Germany
Bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia specify pellet and flake formats for precise pH control in pretzel glazing and cocoa alkalization. REACH Annex XVII mercury thresholds disqualify non-membrane electrolysis imports. BASF SE anchors European distribution through Ludwigshafen logistics hubs serving Swiss chocolate processors.
India
FSSAI recognition of sodium hydroxide as a permitted processing aid opens import corridors for fruit peeling and cocoa operations in Maharashtra and Gujarat. BIS certification requirements fragment compliance pathways for domestic chlor-alkali producers. Mundra Port bulk liquid terminals serve tropical-market beverage concentrate manufacturers.
China
Coastal membrane-cell capacity in Shandong and Jiangsu provinces supplies domestic food processing and export markets. GB standards for food-additive purity create parallel compliance frameworks to REACH and FDA specifications. Qingdao chemical clusters face carbon neutrality mandates under dual carbon goals that reshape production economics.
Brazil
Plant-based protein processing clusters in São Paulo state generate emerging demand for pharmaceutical-grade crossover supply. ANVISA dual certification pathways remain underpenetrated relative to North American and European benchmarks. Santos Port import infrastructure connects to Argentine and Chilean food processing markets.
Food Grade Sodium Hydroxide Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated chemical producers scale membrane-cell installations to capture food-grade certification premiums. The vendor base concentrates around chlor-alkali specialists with captive power and salt sourcing, creating tiered supply structures between integrated majors and regional merchant producers. Three archetypes define competitive positioning: integrated petrochemical conglomerates with global logistics networks, regional membrane-cell specialists serving coastal industrial clusters, and diversified chemical houses with dual food-pharma certification capabilities. Geographic expansion through dedicated food-certification logistics and backward integration into salt and electricity inputs represent the dominant competitive vectors.
Among integrated majors, Dow Chemical Company and BASF SE exemplify scale-driven positioning through membrane-cell capacity and regional distribution density. Tata Chemicals occupies a distinct tier serving tropical-market processors through bulk liquid delivery formats. AkzoNobel and Solvay represent European membrane-cell specialists with REACH-compliant supply chains. Shin-Etsu Chemical and Tosoh Corporation anchor Asia-Pacific supply corridors.
| Leading Market Players |
|---|
| AkzoNobel |
| Tata Chemicals |
| Dow Chemical Company |
| Shin-Etsu Chemical |
| Formosa Plastics Corporation |
| BASF SE |
| Solvay |
| Tosoh Corporation |
| Olin Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal industrial decarbonization incentives gate qualified supply and premium-tier pricing access for food-grade sodium hydroxide, rewarding membrane-cell producers with renewable power purchase agreements while marginalizing merchant-grade suppliers lacking carbon border adjustment exemptions. Buyers seeking REACH-compliant material face bifurcated sourcing economics between certified low-carbon supply and conventional production.
Pricing Analysis
Service-bundling separates integrated producers offering technical dosing support and batch-level documentation from unbundled commodity traders competing on spot price alone. Three-tier pricing structure across premium certified, standard food-grade, and economy merchant tiers reflects membrane electrolysis certification, heavy-metal testing depth, and geographic delivery cost. Price differentiation intensifies as beverage bottlers consolidate procurement through chemical management services, squeezing independent distributors. Cost compression in economy-tier cleaning-agent applications runs through substitute alkaline competition, while confectionery processors show least price sensitivity due to ultra-low heavy-metal specification requirements.
Supply Chain Analysis
Reverse-logistics flows are minimal for consumable caustic soda, though container return programs for intermediate bulk totes create closed-loop handling systems for high-frequency dairy processors. Supply concentrates in the United States, Germany, and China, with membrane-cell capacity clustering along the US Gulf Coast, Rotterdam-Antwerp corridor, and Shandong-Jiangsu provinces. Production draws from salt dome deposits, electricity grids, and membrane-cell technology licensors. Single-source vulnerability concentrates around hurricane-exposed Texas-Louisiana production clusters. Distribution runs through direct tanker networks for bulk liquid, regional distributor warehouses for bag and drum formats, and chemical management service providers for integrated supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade sodium hydroxide operates as a supply-constrained market where FDA food-contact substance notification timelines stretching 18-24 months prop pricing premiums for qualified incumbent producers.
For Market Incumbents: Anchor membrane-cell capacity expansions in renewable-powered corridors to capture EU carbon border adjustment exemptions and defend margin position against emerging low-carbon entrants. Deepen backward integration into captive salt sourcing and power generation to buffer electricity cost volatility threatening merchant producers. Reinforce technical service capabilities to capture chemical management service contracts displacing spot purchasing among multinational beverage processors.
For New Entrants and Emerging Players: Begin with Brazil ANVISA dual food-pharma certification pathways serving underpenetrated plant-based protein processing clusters in São Paulo state. Target Indian FSSAI-permitted import corridors for tropical-market fruit peeling and cocoa operations where domestic membrane-cell capacity lags demand growth. Pursue direct tanker-to-silo distribution partnerships with large beverage concentrate manufacturers seeking volume certainty outside traditional distributor networks.
For Investors and Strategic Acquirers: European renewable-powered membrane-cell installation announcements are the leading indicator that low-carbon caustic soda cost curves are compressing sufficiently to threaten conventional production economics. Long-term viability across the analysis window favors integrated producers with captive salt, power, and certification logistics density. Acquisition targets should emphasize regional membrane-cell specialists with REACH-compliant supply chains and technical documentation capabilities. Monitor oxygen-depolarized cathode technology deployment timelines at Rotterdam and Ludwigshafen sites as the signal for electrification-driven competitive restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Expansion | Captures REACH and FDA certification premiums while displacing mercury-cell legacy production. |
| Renewable Power Integration | Qualifies for EU carbon border adjustment exemptions and defends positioning against low-carbon imports. |
| Backward Integration into Salt Sourcing | Reduces input cost volatility exposure threatening merchant producers without captive supply. |
| Long-Term Supply Agreement | Locks volume certainty with multinational beverage bottlers consolidating procurement through chemical management services. |
| Dual Food-Pharma Certification | Opens crossover revenue streams in underpenetrated Latin American plant-based protein processing markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with chlor-alkali plant managers, procurement leads at beverage and dairy processors, distribution channel partners, and technical R&D directors specializing in membrane-cell technology. Secondary sources included ECHA REACH registration databases, FDA food-contact substance notifications, FSSAI additive approvals, SEC 10-K filings from integrated chemical producers, and Cefic chlor-alkali production statistics. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis to validate volume estimates.
Segmentation-level granularity modeled physical form, application intensity, and end-user procurement behavior across the projection horizon. CAGRs derived from regression analysis of historical production capacity, regulatory approval timelines, and substitution elasticity between caustic soda and potassium hydroxide in beverage pH adjustment. Forecast inputs incorporated membrane-cell technology diffusion curves, renewable power purchase agreement penetration rates, and chemical management service contract adoption patterns among multinational processors.
Underlying measurement precision varies by segment; liquid bulk deliveries to large beverage sites carry tighter precision than fragmented artisan bakery bag-format procurement. Forecasts reflect assumptions about regulatory harmonization timelines and electrolysis technology substitution rates. Practitioners should monitor oxygen-depolarized cathode deployment announcements and EU carbon border adjustment implementation details for early signals of competitive restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
United States Food Preservatives Market