
 Dairy Foods Market | 2026-2036
Dairy Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Foods Market Analysis
The split between premium and commodity tiers is shifting as consumers trade up on protein content, probiotic claims, and grass-fed sourcing while private-label milk competes on price alone. Danone leverages its specialized nutrition portfolio to capture margin in medical and pediatric segments. Lactalis anchors its position through backward integration into farm-level milk collection across multiple continents. Fonterra differentiates via ingredient technology leadership in whey protein isolates and milk fat globule membranes.
Dairy foods encompass fluid milk, fermented products, concentrated derivatives, and solid fats containing minimum protein and fat thresholds standardized by Codex Alimentarius, with pasteurization or UHT treatment required for pathogen elimination and shelf stability. The primary commercial purpose spans direct human nutrition, food manufacturing inputs, and specialized infant formula bases. Cheese occupies the deepest margin pool among product types due to aging infrastructure requirements and regional appellation protections. Yogurt leads growth velocity as functional probiotic positioning expands across convenience stores and online retail channels. Liquid milk remains the volume anchor but faces structural pressure from plant-based alternatives in supermarket dairy aisles.
The USDA enforces Grade A standards for fluid milk safety and compositional identity, while the FDA oversees cheese manufacturing under current Good Manufacturing Practice regulations and the Food Safety Modernization Act. The EU Green Deal and F-Gas Regulation are accelerating cold-chain decarbonization mandates that reshape processing plant energy profiles and refrigeration technology procurement. Stakeholders must monitor how carbon border adjustment mechanisms and methane reduction commitments alter feed sourcing economics and farm-gate pricing structures.
Market Dynamics
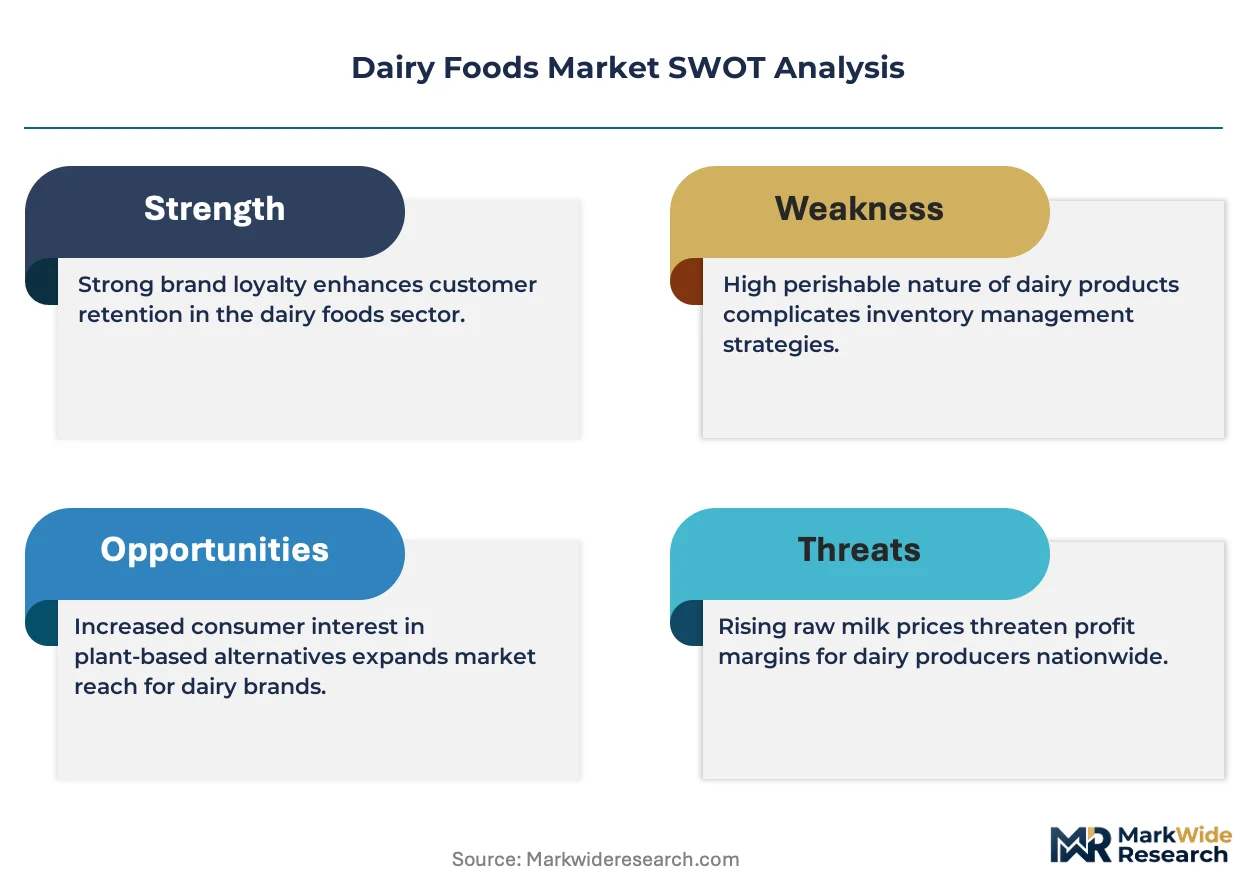
The EU F-Gas Regulation is compressing refrigeration technology choices across European processing plants while simultaneously elevating capital requirements for cold-chain compliance. This regulatory pressure cascades through equipment procurement, energy sourcing decisions, and farm-gate pricing structures in ways that favor integrated operators with balance-sheet capacity for asset replacement.
Growth Catalysts
- Urban packaged milk transition:Indian metropolitan consumers are abandoning loose milk vendors for UHT and ESL formats, creating volume anchors for Tetra Pak filling lines and cold-chain infrastructure investments.
- EU Green Deal methane protocols:The European Commission's farm-level emission accounting is accelerating feed additive adoption and manure management technology deployment across Dutch and Danish cooperative networks.
- Precision fermentation scale-up:Whey protein isolate production via microbial hosts is reducing reliance on traditional cheese-making byproduct streams for high-value ingredient sourcing.
Market Restraints
- Feed cost volatility:Soybean meal and alfalfa hay price swings compress margin predictability for pasture-dependent operations in New Zealand and Ireland.
- Refrigerant supply concentration:EU HFC quota reductions have concentrated compliant coolant sourcing among three chemical manufacturers, elevating maintenance contract pricing for cold-storage facilities.
- Plant-based substitution:Oat and almond beverage formats are displacing fluid milk occasions in North American and Western European retail dairy aisles.
Strategic Opportunities
- Medical nutrition white space:Pediatric and geriatric specialized formulas remain underpenetrated in Southeast Asian hospital channels, where pharmacist recommendation drives brand selection.
- Direct-to-consumer subscription:Farm-branded fresh delivery models bypass traditional retail markup structures in Australian and Canadian urban corridors.
- Carbon credit monetization:Methane capture digester installations at large-scale Wisconsin and California dairies generate compliance offsets for California Air Resources Board cap-and-trade participants.
Industry Challenges
- Automation technician scarcity:Robotic milking system maintenance and data analytics interpretation require skill sets absent from traditional agricultural labor pools in Germany and Japan.
- Organic certification timeline:Three-year pasture conversion periods delay premium milk price realization for transitioning farms in France's Brittany region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Foods Market |
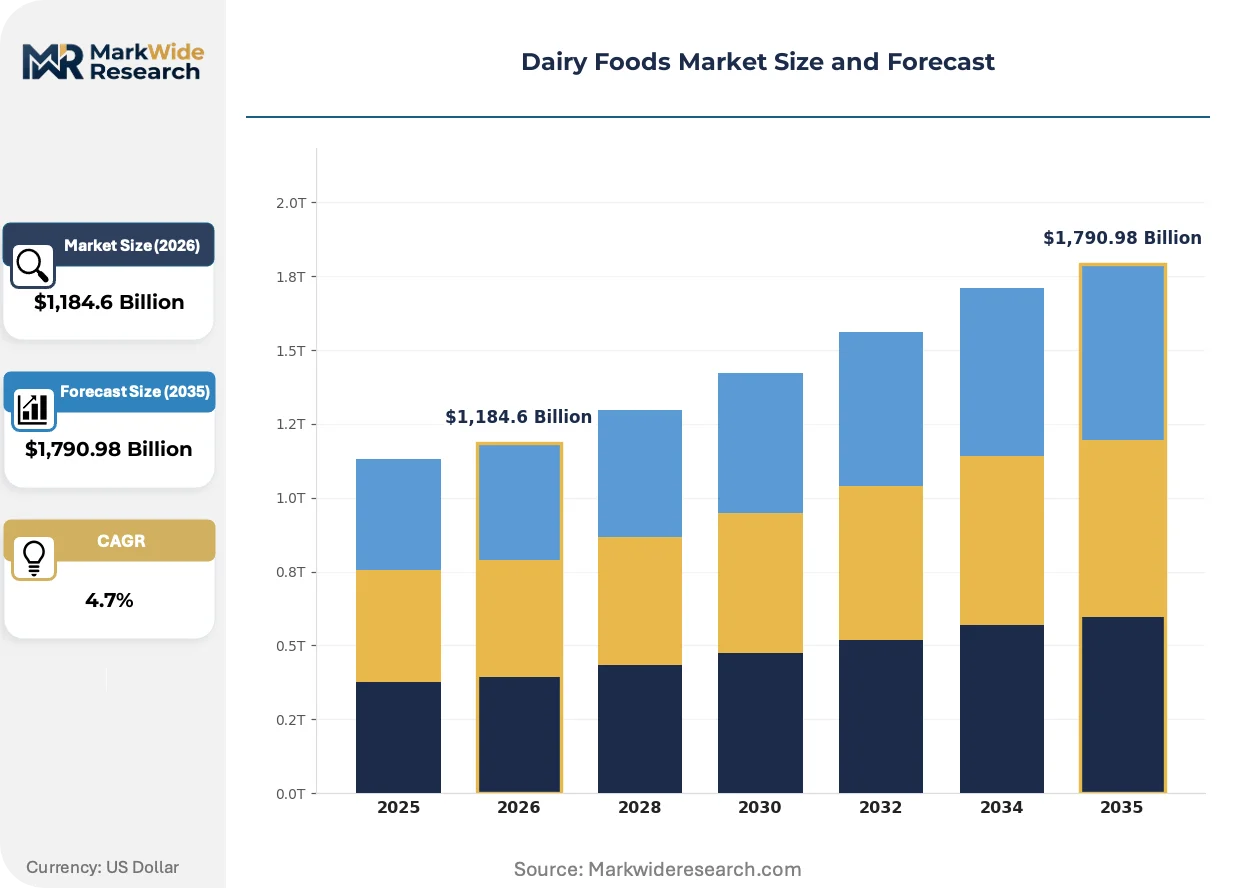
| Market Size in 2026 | $1,184.6 Billion |
| Market Size in 2035 | $1,790.98 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Yogurt, Milk, Butter Form: Liquid, Powder, Cream, Solid Packaging Type: Bottle, Carton, Tub, Pouch Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Danone, Arla Foods, Lactalis, FrieslandCampina, Fonterra, Nestlé, Yili, Saputo, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Foods Market Emerging Trajectories
Digital traceability infrastructure is replacing paper-based farm records across major exporting regions, compressing audit timelines while enabling real-time compositional monitoring from parlor to processing plant.
Blockchain-enabled supply chain verification is unifying farm-level data with retail shelf claims. Major European retailers now mandate immutable origin documentation for private-label cheese and butter lines. This technology is compressing the gap between premium positioning and verifiable sourcing, forcing commodity processors to invest in data infrastructure or exit branded segments entirely.
The EU F-Gas Regulation's phasedown schedule is accelerating adoption of transcritical CO2 and ammonia-based refrigeration systems. Processing plants in the Netherlands and Denmark face 2027 deadlines for HFC phaseout compliance. Large cooperatives are consolidating smaller facilities to amortize capital costs across higher throughput volumes, reducing plant counts in Jutland and Friesland.
Indian urban households are consolidating dairy purchases toward morning delivery subscriptions and convenience-store single-serve formats. Traditional loose-milk vendors in Mumbai and Delhi are losing share to organized retail and app-based ordering platforms. This channel rotation is concentrating volume among processors with last-mile cold-chain density in Maharashtra and National Capital Region corridors.
Dairy Foods Market Segmentation
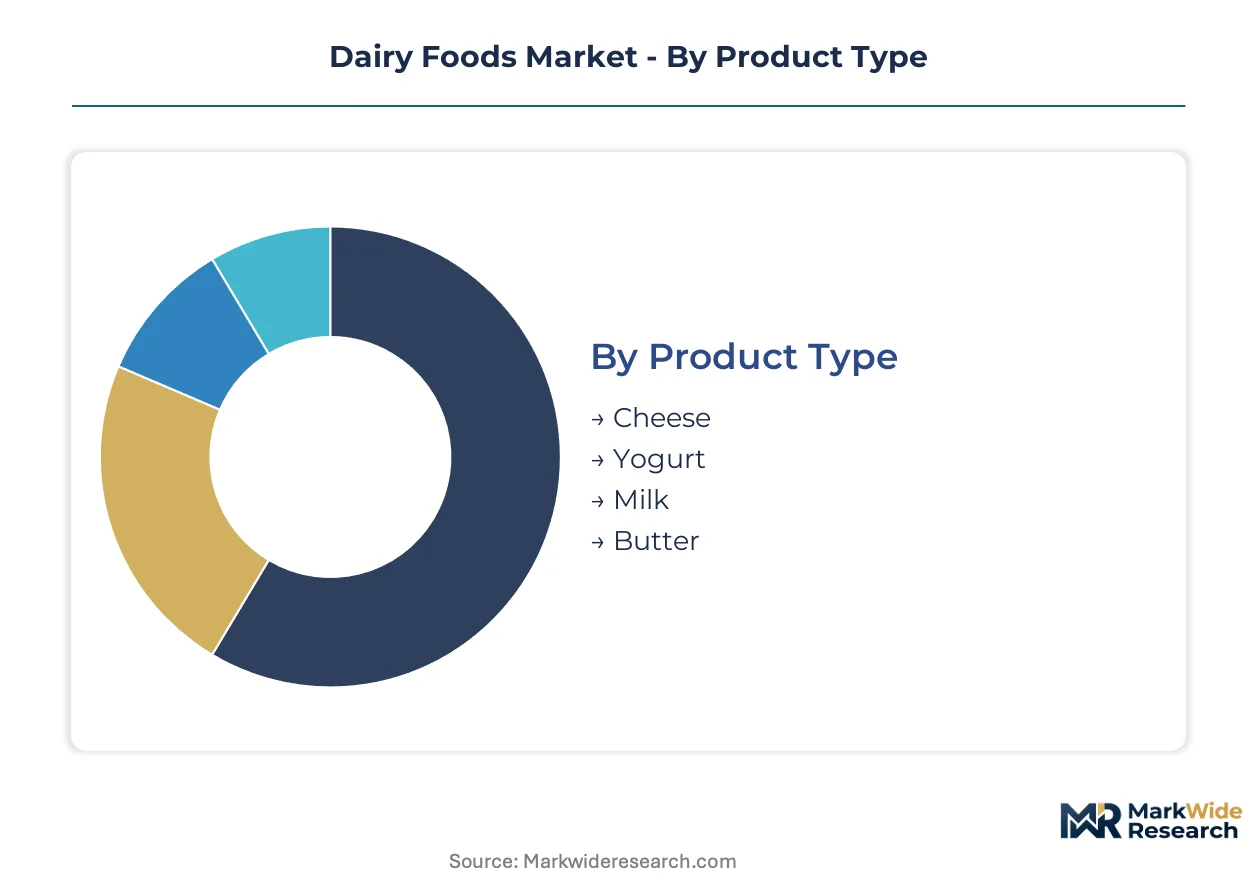
Segmentation in dairy foods separates volume commodities from margin-rich specialties. Each dimension—product type, form, packaging, and channel—creates distinct competitive arenas with different capital intensity and brand loyalty profiles.
Product Type:
Cheese and yogurt command premium positioning through aging infrastructure and functional claims, while milk and butter anchor volume throughput with thinner margins.
- Cheese:Requires controlled humidity aging environments and carries protected designation of origin status in European markets. Aged cheddar and parmesan variants concentrate demand in US specialty retail and foodservice channels where regional appellation protections justify price premiums.
- Yogurt:Fermented dairy with live culture specifications drives the steepest expansion trajectory through probiotic health positioning and single-serve convenience formats. Greek and skyr variants concentrate in urban convenience stores across India and Southeast Asia where functional nutrition claims command shelf space.
- Milk:Standardized fluid dairy with pasteurization or UHT treatment dominates tonnage but faces plant-based displacement in North American retail.
- Butter:Churned fat product with 80% minimum milkfat content anchors baking and cooking applications in European and Australian households.
Today's leader: Cheese. Tomorrow's challenger: Yogurt.
Form:
Form selection determines shelf stability, logistics economics, and reformulation flexibility for downstream food manufacturing.
- Liquid:Fluid dairy requiring continuous cold-chain integrity from processing through retail. ESL and UHT variants extend reach in Indian urban corridors where ambient distribution infrastructure remains limited.
- Powder:Dehydrated dairy proteins and whole milk powder enable intercontinental trade and infant formula manufacturing. Whey protein concentrate and skim milk powder concentrate demand in Chinese ingredient import channels where domestic supply falls short of processing capacity.
- Cream:High-fat dairy fraction with 18-40% butterfat content serves coffee culture and dessert applications in European foodservice.
- Solid:Concentrated butter, cheese blocks, and compressed milk powders optimize ocean freight economics for African and Middle Eastern import markets.
Powder commands export economics. Liquid retains proximity advantage.
Packaging Type:
Packaging technology shapes shelf life extension, portion control, and retail channel access across temperature-controlled and ambient supply chains.
- Bottle:HDPE and PET containers dominate fluid milk in North American retail where returnable glass has largely exited. Extended shelf-life bottle formats are gaining share fastest in Brazilian urban supermarkets.
- Carton:Aseptic paperboard with aluminum foil layers enables UHT milk distribution without refrigeration. Tetra Pak and SIG Combibloc formats concentrate in European and Asian markets where ambient logistics reduce last-mile costs.
- Tub:Polypropylene containers with resealable lids anchor yogurt and spreadable cheese in refrigerated dairy aisles.
- Pouch:Flexible film formats reduce material cost and shipping cube for powder products and single-serve liquid portions.
Carton leads ambient penetration. Pouch challenges on cost.
Distribution Channel:
Channel selection determines margin capture, brand control, and consumer data access across fragmented retail landscapes.
- Supermarkets:Multi-category retailers with dedicated refrigerated dairy sections generate the highest absolute volume. Private-label concentration in German and UK chains compresses branded margin pools.
- Online Retail:Direct-to-home delivery platforms with cold-chain fulfillment are expanding most quickly in Chinese and South Korean metropolitan markets where subscription models lock in recurring purchase patterns.
- Convenience Stores:Small-format urban retailers with limited refrigeration stock single-serve and immediate consumption formats.
- Specialty Stores:Cheese mongers and organic retailers with curated assortments capture premium price realization for artisan and farm-branded products.
Supermarkets anchor volume. Online retail climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's packaged milk transition accelerates faster than Brazil's dairy consolidation, yet both trail the EU's regulatory compression on cold-chain emissions. Geographic differentiation sharpens as feed economics, urban distribution infrastructure, and carbon protocols diverge.
United States
Wisconsin and California dairies drive specialized ingredient exports through whey protein isolate and milk fat globule membrane processing. The USDA enforces Grade A fluid milk standards while California Air Resources Board cap-and-trade mechanisms incentivize methane capture digester installations. Large-scale operations in the Central Valley and Upper Midwest consolidate processing capacity to amortize compliance costs.
India
Maharashtra and Delhi-NCR urban corridors abandon loose milk vendors for UHT and ESL formats through app-based subscription platforms. FSSAI packaging and safety standards tighten while PLI scheme incentives support cold-chain infrastructure investments. Organized retail concentrates volume among processors with last-mile density in Mumbai and National Capital Region corridors.
Netherlands
Dutch cooperative networks deploy feed additives and manure management technologies under EU Green Deal methane protocols. The F-Gas Regulation mandates transcritical CO2 refrigeration adoption by 2027, accelerating plant consolidation in Jutland and Friesland. FrieslandCampina anchors processing scale across cooperative farm networks.
China
Ingredient import demand for whey protein concentrate and skim milk powder outpaces domestic supply in coastal processing zones. SAMR oversees infant formula registration while NMPA standards tighten on specialized nutrition imports. Yangtze River Delta and Pearl River Delta clusters concentrate formulation and packaging capacity for pediatric segments.
New Zealand
Pasture-dependent operations face margin compression from soybean meal and alfalfa hay price volatility. Fonterra anchors ingredient technology leadership in whey protein isolates through cooperative structures. Canterbury and Waikato regions concentrate milk collection infrastructure for intercontinental powder exports.
Dairy Foods Market Vendor Landscape
Top-tier vendors anchor cooperative and multinational scale, while regional specialists and private-label processors compete on proximity and price. The structure tiers across backward-integrated farm networks, ingredient technology leaders, and medical nutrition specialists. Cooperative-owned processors and publicly traded multinationals represent dominant archetypes. Competitive moves concentrate on cold-chain asset replacement and pediatric formula registration expansion.
Within the cooperative archetype, Fonterra and Dairy Farmers of America exemplify farm-gate integration models that compress procurement costs across ocean freight and domestic distribution. Danone and Nestlé occupy positions in specialized nutrition where pediatric and geriatric formulation expertise commands hospital channel access. Lactalis and Yili represent scale-driven processors consolidating regional capacity to amortize EU F-Gas Regulation compliance and Chinese SAMR registration investments.
| Leading Market Players |
|---|
| Danone |
| Arla Foods |
| Lactalis |
| FrieslandCampina |
| Fonterra |
| Nestlé |
| Yili |
| Saputo |
| Dairy Farmers of America |
| Others |
Supply Flow & Price Mechanics
Premium-protein bifurcation between grass-fed organic and conventional commodity milk redraws margin architecture across procurement networks and retail shelf positioning. This tier divergence concentrates pricing power with processors commanding backward-integrated farm networks while commodity operators absorb feed cost volatility through thin contract structures.
Pricing Analysis
Capacity additions in India are reshaping price floors for UHT and extended-shelf-life formats through government PLI scheme subsidies. Three-tier pricing structure across premium grass-fed, standard pasteurized, and economy private-label segments anchors retail competition. Price differentiation rests on FSSAI certification grade and cold-chain density in last-mile corridors. Margins are tightening due to soybean meal and alfalfa hay input volatility. Foodservice buyers exhibit lowest price sensitivity; loose-milk transition households in Indian urban corridors show highest.
Supply Chain Analysis
Automation technician scarcity in Germany and Japan constrains robotic milking system deployment across processing plant networks. Geographic supply concentration centers on New Zealand, the Netherlands, and India for powder exports and cooperative processing scale. Raw material dependencies draw from soybean meal, alfalfa hay, and refrigerant chemicals under EU HFC quota restrictions. Single-source vulnerability runs through concentrated compliant coolant sourcing among three chemical manufacturers. Distribution runs through cooperative collection networks consolidating toward large-scale facilities in Jutland and Friesland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's phasedown schedule compounds capital intensity for cold-chain compliance, elevating processor consolidation and cooperative network restructuring as demand drivers.
For Market Incumbents: Lock in methane capture digester installations at Wisconsin and California dairies to generate California Air Resources Board cap-and-trade offsets. Secure transcritical CO2 refrigeration technology procurement ahead of 2027 Netherlands and Denmark deadlines. Defensive consolidation of smaller Friesland and Jutland facilities amortizes EU Green Deal compliance costs across higher throughput volumes. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models in Australian and Canadian urban corridors bypassing retail markup structures. Target pediatric and geriatric specialized formula white space in Southeast Asian hospital channels where pharmacist recommendation drives brand selection. Pursue app-based morning delivery platforms in Maharashtra and Delhi-NCR corridors exploiting loose-milk vendor displacement. For Investors and Strategic Acquirers: Asymmetric upside sits with ingredient technology specialists commanding whey protein isolate and milk fat globule membrane processing capabilities. Long-term viability favors cooperative-integrated processors with balance-sheet capacity for EU F-Gas Regulation asset replacement cycles. Watch precision fermentation scale-up in microbial host protein production as inflection signal for traditional cheese byproduct stream displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Networks | Lactalis compresses procurement costs across multiple continents through captive milk collection infrastructure. |
| Cold-Chain Asset Replacement | Dutch cooperatives consolidate facilities to amortize transcritical CO2 refrigeration capital requirements under EU deadlines. |
| Pediatric Formula Registration Expansion | Danone leverages specialized nutrition expertise to capture hospital channel access in underpenetrated Southeast Asian markets. |
| Direct-to-Consumer Platform Launch | Farm-branded subscription models bypass traditional retail markup structures in Australian urban corridors. |
| Precision Fermentation Scale-Up | Microbial host whey protein production reduces reliance on traditional cheese-making byproduct streams for ingredient sourcing. |
Methodological Framework
Coverage spans India, the Netherlands, the United States, China, and New Zealand, with primary inputs from each major processing region. The analysis combines structured interviews with cooperative procurement directors, dairy plant engineers, cold-chain logistics operators, and retail category buyers with secondary validation from FSSAI filings, USDA Grade A standards documentation, EU Green Deal regulatory texts, and customs trade data. Bottom-up volume modeling triangulates against top-down macroeconomic anchors.
Granularity-level modeling disaggregates projections across product type, form, packaging technology, distribution channel, and regional regulatory cluster dimensions. CAGRs derive from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted demand drivers. Forecast inputs incorporate EU F-Gas Regulation compliance timelines, Indian PLI scheme infrastructure deployment curves, and precision fermentation capacity build-out assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feed commodity price spikes and refrigerant supply disruptions. Projections reflect documented assumptions on urban packaged milk transition velocity and methane protocol enforcement intensity. Material deviation in EU Green Deal implementation pace or Indian cold-chain subsidy allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Milk Protein Market
Dairy Products
Lactose Free Butter Market
Dairy Products
GCC Casein Market
Dairy Products
Organic Dairy Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Kefir Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Cream Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Cream Powder Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Halloumi Cheese Market