
 Organic Cheese Market | 2026-2036
Organic Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cheese Market Analysis
Market Context
The EU Organic Regulation is recalibrating the cost-of-entry calculus for producers seeking certified status across European markets. Fonterra Co-operative Group Limited leverages its integrated dairy supply chain to secure organic milk pools in Oceania. Arla Foods anchors its competitive position through cooperative farmer ownership and stringent Nordic organic standards. Organic Valley specializes in domestic US organic milk sourcing, sustaining premium positioning through farmer-controlled supply.
Technical Definition and Structural Segments
Organic cheese denotes cheese produced from milk sourced from livestock raised under certified organic protocols, prohibiting synthetic hormones, antibiotics, and pesticides while mandating pasture-based feed regimens and minimum grazing days. Hard cheese commands the largest share of product type revenue due to extended shelf stability and export suitability, while spreadable formats in the form category capture accelerating demand from convenience-oriented foodservice operators. Cow milk dominates source-based segmentation by volume, though goat milk variants command margin premiums in specialty retail channels across France and the United States.
Regulatory Frame and Outlook
USDA National Organic Program standards, EU Organic Regulation, and Codex Alimentarius guidelines collectively define permissible inputs, labeling claims, and cross-border equivalence arrangements. EFSA and national regulators in Germany and France conduct residue testing that determines market access for imported organic cheese lots. Stakeholders must monitor evolving feed certification requirements and bilateral organic equivalence negotiations to preserve supply continuity.
Market Dynamics
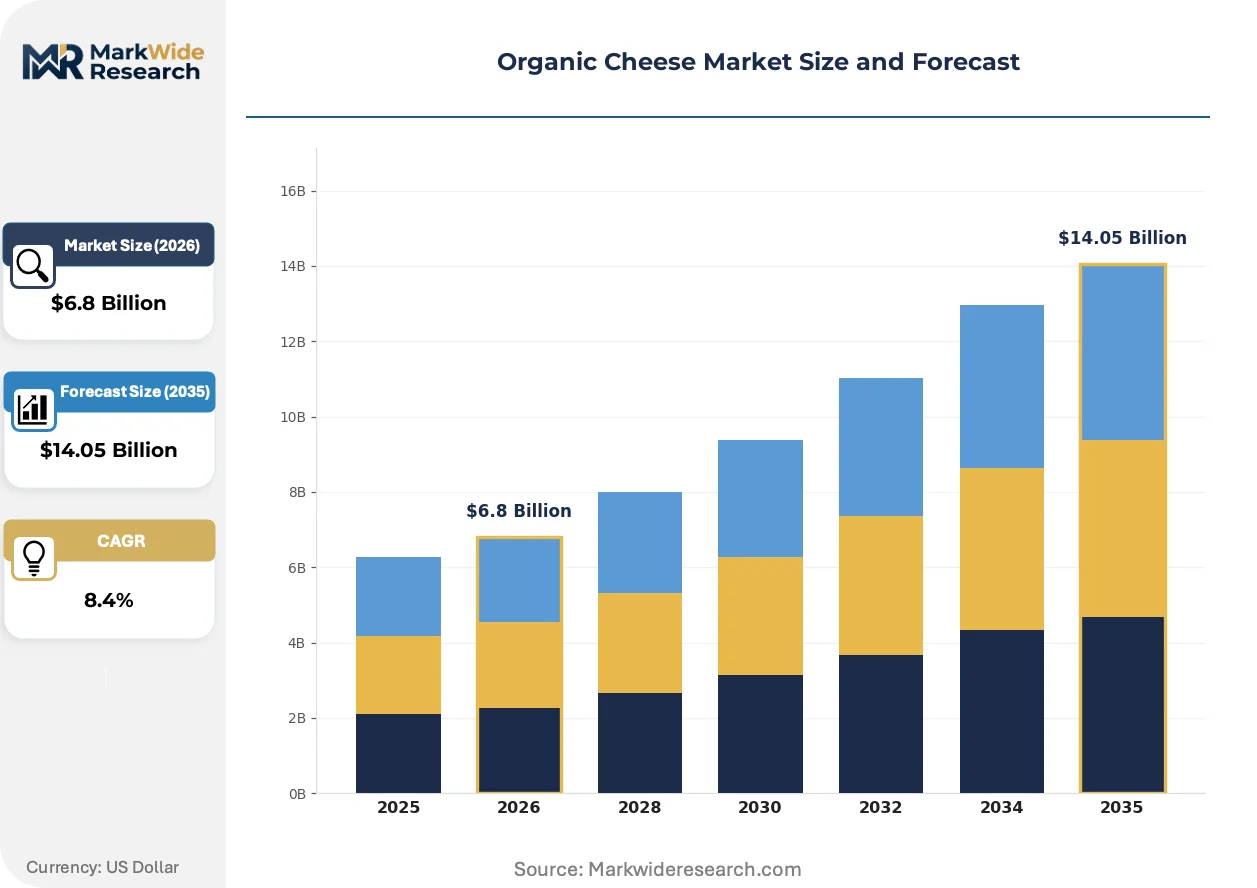
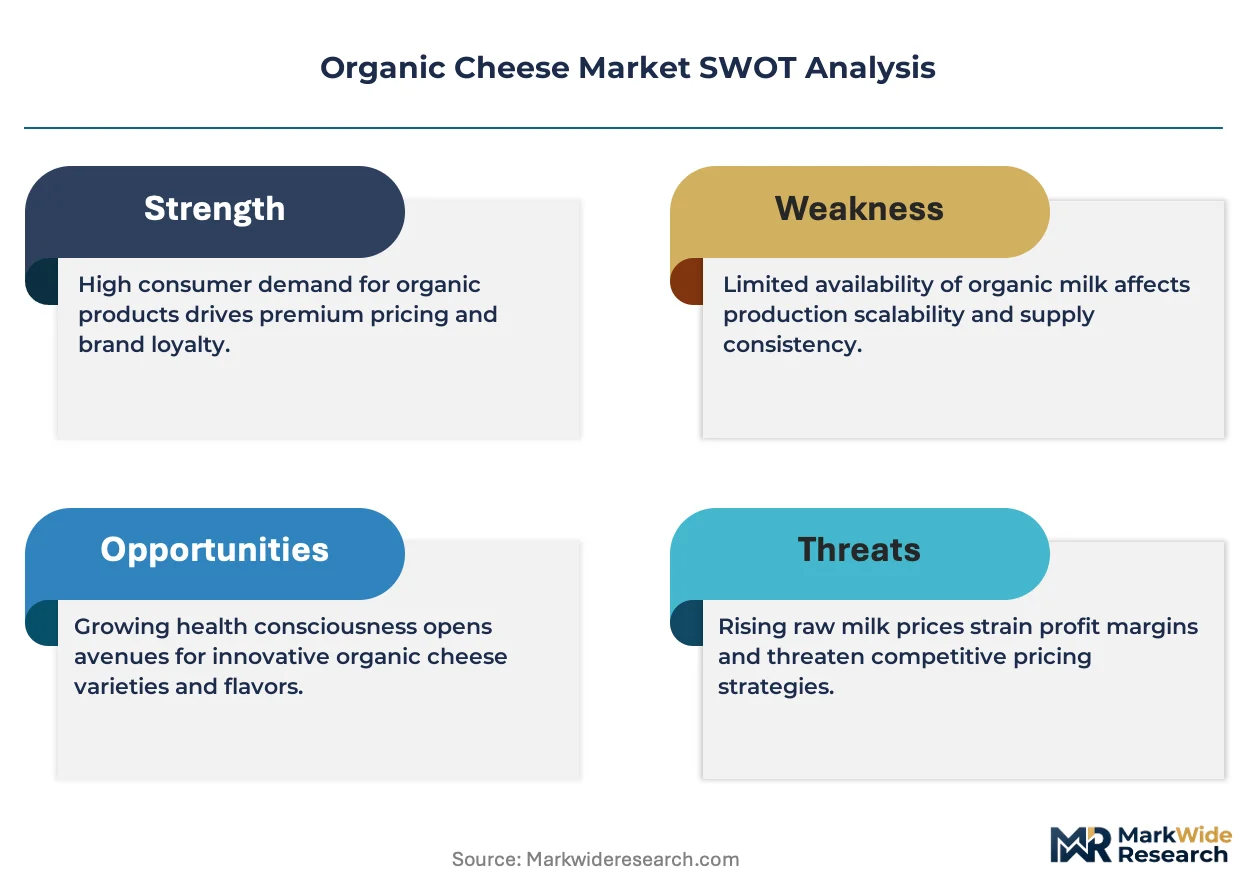
EU Organic Regulation feed-source verification mandates are compressing certified milk availability while specialty retailers absorb larger organic cheese volumes, creating a structural squeeze between compliance costs and channel expansion.
Growth Catalysts
- EU Organic Regulation tightening:Enhanced feed-source verification requirements across member states are consolidating certified producer bases and accelerating channel migration toward specialty retail formats.
- Pasture-based feed protocols:Mandatory grazing day minimums under USDA National Organic Program standards are differentiating certified supply and commanding shelf-space premiums in domestic US channels.
- Germany-France-US demand concentration:These three markets anchor certified organic cheese absorption, with specialty food retail operators expanding SKU counts and refrigerated footprint allocations.
Market Restraints
- Organic feed input volatility:Certified grain and forage costs fluctuate with climate-induced harvest variability, compressing processor margins during drought cycles in major supplying regions.
- Certified milk pool concentration:Organic dairy farm numbers remain limited in Oceania and the Nordic region, creating supply bottlenecks for processors seeking volume scale.
- Extended certification timelines:Three-year land conversion requirements under EU Organic Regulation and USDA NOP delay new entrant supply availability and capital recovery periods.
Strategic Opportunities
- Goat milk premium positioning:France and US specialty retail channels absorb margin-enhancing goat milk variants at price points exceeding cow milk equivalents by substantial spreads.
- Spreadable format foodservice penetration:Convenience-oriented operators in Germany and France are expanding organic cheese spread applications for prepared meal and catering segments.
- Hard cheese export suitability:Extended shelf stability enables certified organic hard cheese to access distant markets with developing organic retail infrastructure.
Industry Challenges
- Residue testing compliance:EFSA and German national regulator protocols require batch-level verification, creating documentation burdens and rejection risks for imported lots.
- Cross-border equivalence negotiations:Bilateral organic recognition agreements between the EU and major supplying countries remain incomplete, fragmenting supply routing options.
- Legacy dairy infrastructure retrofit costs:Conventional processing lines require dedicated organic segregation and cleaning protocols, demanding capital outlays for certification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cheese Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cheese, Hard Cheese, Fresh Cheese, Aged Cheese Form: Blocks, Slices, Shredded, Spreadable Source: Cow Milk, Goat Milk, Sheep Milk, Buffalo Milk Packaging Type: Vacuum Packs, Jars, Tubs, Wraps |
| Companies Covered | Fonterra Co-operative Group Limited, Organic Valley, Arla Foods, FrieslandCampina, Savencia Fromage & Dairy, Groupe Lactalis, Kraft Heinz Company, Saputo Inc., Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cheese Market Emerging Trajectories
Digital traceability systems are penetrating organic dairy supply chains, enabling real-time feed-source verification and compressing audit cycle timelines for certification maintenance.
Blockchain-enabled milk provenance tracking is converging with mobile-based farm management platforms. German and French processors are piloting these systems to preempt EU Organic Regulation documentation demands. The technology is converging with retailer sustainability scoring requirements, forcing upstream investment in data infrastructure.
REACH chemical authorization expansions are restricting sanitizing agents and processing aids permitted in EU organic cheese facilities. This regulatory tightening is eliminating legacy cleaning chemistries from certified production lines. Small-scale processors in France and Germany are responding by retrofitting thermal cleaning systems and dry-ice blasting equipment.
Foodservice procurement is consolidating organic cheese specifications around single-source supplier arrangements with integrated traceability. Independent distributors in the United States are losing share to direct processor relationships as large contract caterers demand batch-level origin data. This pattern is most visible in corporate dining and institutional segments across Germany and the US, where sustainability reporting obligations drive purchasing centralization.
Organic Cheese Market Segmentation
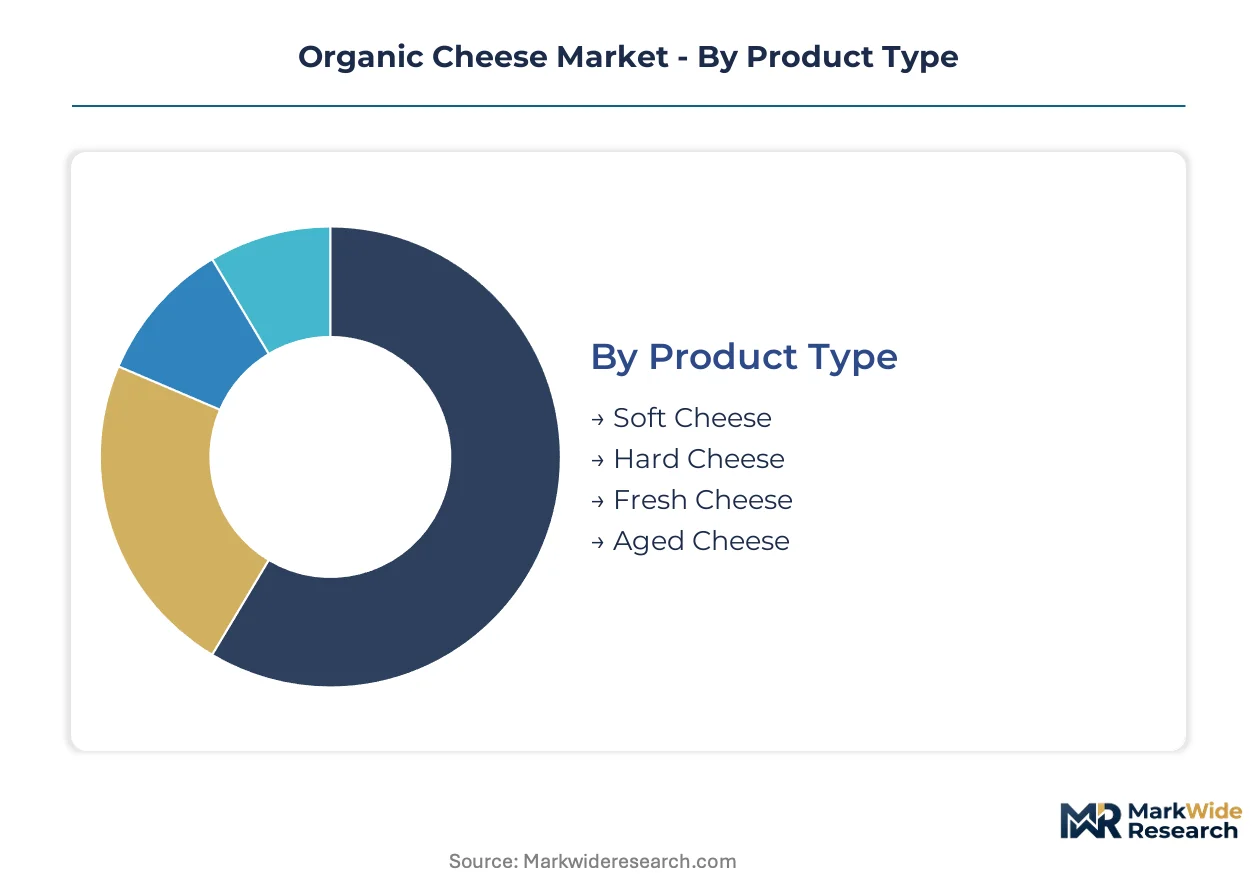
Segmentation in organic cheese markets reveals how processing specifications, shelf-life requirements, and animal husbandry protocols create distinct competitive arenas. Each axis carries unique regulatory burdens and margin profiles that determine viable positioning strategies for processors and retailers.
Product Type:
Processing protocols and aging requirements differentiate certified organic cheese across moisture content, microbial development, and storage stability specifications.
- Hard Cheese:Low-moisture curd pressed under extended aging protocols delivers shelf stability exceeding twelve months. German and French specialty retailers allocate disproportionate refrigerated footprint to aged hard varieties for export-ready inventory.
- Soft Cheese:High-moisture curd with abbreviated aging cycles demands cold-chain integrity and compressed distribution windows. Foodservice operators in France absorb volume for prepared meal applications where creamy texture commands premium positioning.
- Fresh Cheese:Unaged curd products requiring continuous refrigeration from production to consumption point.
- Aged Cheese:Extended cellar-aged varieties with crystalline texture development and concentrated flavor profiles.
Hard cheese leads on scale; soft cheese leads on momentum.
Form:
Downstream handling requirements and end-use convenience specifications shape processor capital allocation and packaging line configurations.
- Blocks:Bulk formats supporting foodservice portion control and retail deli counter operations. German contract caterers specify block formats for in-house shredding and recipe integration.
- Spreadable:Emulsified or whipped preparations with extended workability for sandwich and cracker applications. Convenience-oriented operators in France are expanding organic spread applications across prepared meal and catering segments.
- Slices:Individually portioned formats for quick-service and retail grab-and-go channels.
- Shredded:Pre-grated preparations eliminating labor at point of use for pizza and prepared food manufacturers.
Block formats dominate foodservice procurement; spreadable climbs fastest in retail convenience positioning.
Source:
Animal husbandry protocols and milk composition characteristics create divergent certification pathways and margin structures across livestock types.
- Cow Milk:Standardized fat and protein profiles supporting volume-scale production and broad application compatibility. USDA National Organic Program pasture mandates differentiate certified supply across domestic US channels.
- Goat Milk:Smaller fat globules and distinct protein structures yielding digestibility claims and specialty positioning. France and US specialty retail channels absorb margin-enhancing goat variants at substantial price premiums over cow milk equivalents.
- Sheep Milk:Concentrated solids content supporting robust flavor profiles in Mediterranean-style cheese traditions.
- Buffalo Milk:Elevated butterfat composition for premium fresh mozzarella and stretched-curd applications.
Cow milk anchors volume availability; goat milk captures steepest margin expansion.
Packaging Type:
Barrier properties and consumer access modalities determine shelf-life extension and retail presentation strategies.
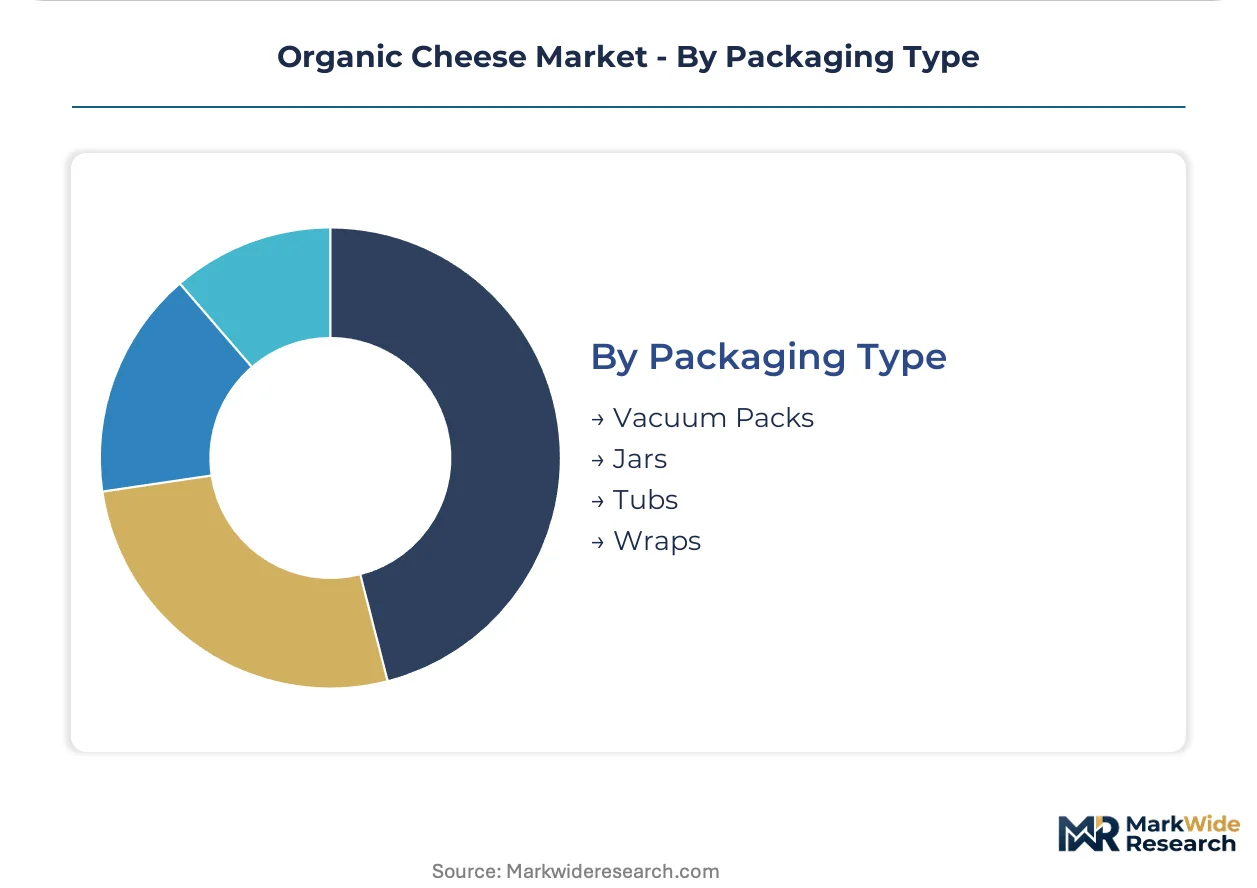
- Vacuum Packs:Oxygen-exclusion films suppressing aerobic spoilage organisms for extended distribution reach. Hard cheese exporters to Germany rely on vacuum barrier integrity for transcontinental shipment viability.
- Tubs:Rigid containers with resealable closures supporting multi-use consumption patterns for spreadable and fresh formats. French retailers specify tub configurations for organic cream cheese and fresh curd presentations.
- Jars:Glass or rigid plastic vessels with hermetic seals for brined or oil-preserved preparations.
- Wraps:Breathable films or waxed papers permitting moisture exchange for surface-ripened soft varieties.
Vacuum packs dominate export logistics; tubs gain share fastest in convenience-oriented retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic dairy expertise clusters in Germany's Bavaria and Baden-Württemberg regions, France's Normandy and Loire Valley, and Wisconsin in the United States. These concentrations anchor certified milk supply and processing infrastructure for premium cheese production.
United States
Specialty food retail operators in Wisconsin and Vermont are absorbing larger organic cheese volumes while expanding refrigerated footprint allocations. USDA National Organic Program pasture mandates differentiate certified supply across domestic channels. Organic Valley's farmer-controlled cooperative structure in the Upper Midwest sustains premium positioning through captive milk sourcing.
Germany
Discounters and specialty retailers in Bavaria and North Rhine-Westphalia are consolidating procurement around single-source suppliers with integrated traceability. EFSA residue testing protocols require batch-level verification for imported lots, creating documentation burdens. Munich-based processors are piloting blockchain-enabled milk provenance tracking to preempt EU Organic Regulation demands.
France
Specialty retail channels in Île-de-France and Auvergne-Rhône-Alpes absorb margin-enhancing goat milk variants at substantial price premiums. ANSM enforces REACH chemical authorization restrictions on sanitizing agents in certified facilities. Roquefort-sur-Soulzon and surrounding Aveyron departments concentrate artisanal organic cheese production with protected designation heritage.
Netherlands
Contract caterers in the Randstad region are demanding batch-level origin data for sustainability reporting obligations. Dutch national regulators align with EU Organic Regulation feed-source verification mandates, compressing certified milk availability. FrieslandCampina's cooperative structure in Friesland and Groningen provinces secures organic milk pools through farmer ownership models.
Switzerland
Premium retail channels in Zurich and Geneva absorb imported organic hard cheese for extended shelf-stable inventory. Swissmedic coordinates with EU regulators on cross-border equivalence for organic dairy imports. Alpine dairy cooperatives in Graubünden and Valais maintain stringent organic standards that exceed baseline EU requirements.
Organic Cheese Market Vendor Landscape
The competitive structure tilts toward cooperative ownership models with integrated farmer bases. Tiered positioning separates scale-driven processors from artisanal specialists and private-label suppliers. Three archetypes dominate: cooperative-owned dairies with captive milk supply, diversified dairy conglomerates with organic SKUs, and regional artisan producers with protected designation status. Capacity expansion and strategic partnerships represent the dominant competitive moves as processors secure certified milk access.
Within the cooperative archetype, Fonterra Co-operative Group Limited and Arla Foods exemplify farmer-owned structures that anchor competitive position through supply control. Organic Valley occupies a position representing the domestic US specialist tier with farmer-controlled sourcing. Among diversified processors, Groupe Lactalis and Savencia Fromage & Dairy sit within the European conglomerate tier leveraging existing dairy infrastructure for organic line extensions.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Organic Valley |
| Arla Foods |
| FrieslandCampina |
| Savencia Fromage & Dairy |
| Groupe Lactalis |
| Kraft Heinz Company |
| Saputo Inc. |
| Danone |
| Others |
Supply Flow & Price Mechanics
Certified organic feed costs cascade through producer margins into three distinct price tiers: artisanal farmstead operations commanding shelf-space premiums, mid-scale cooperative processors sustaining contract premiums through captive milk pools, and private-label suppliers absorbing compressed margins in discounter channels. Organic grain and forage price volatility in major supplying regions feeds directly into processor procurement spreads, widening the gap between pasture-based premium positioning and conventional organic equivalence.
Pricing Analysis
Unbundled milk sourcing separates artisanal producers charging farmgate premiums from processors purchasing on spot organic milk markets. Three-tier pricing structure across premium artisanal, standard cooperative, and economy private-label levels stratifies by certification depth and provenance documentation. Pricing pressure stems from EU Organic Regulation feed verification mandates compressing certified milk availability while specialty retailers expand volume commitments. Discounters in Germany exhibit highest price sensitivity, whereas US specialty food retail channels absorb substantial premiums for goat milk variants and extended-aging hard cheese formats.
Supply Chain Analysis
Dual-sourcing requirements from German and French contract caterers force processors to qualify multiple certified milk pools across Oceania and the Nordic region. Geographic supply concentrates in New Zealand, Denmark, and the Upper Midwest United States, with each node tethered to distinct organic certification protocols. Raw material dependencies center on certified organic grain, pasture forage, and veterinary inputs compliant with residue testing protocols. Single-source vulnerability persists in aged hard cheese cellar capacity, where extended aging cycles limit flexible volume scaling. Distribution runs through cold-chain logistics networks serving specialty retail and foodservice channels with batch-level traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in organic cheese rests on pasture-based feed protocol premiums widening as EU Organic Regulation compliance costs consolidate producer bases, compressing supply availability while channel migration toward specialty retail accelerates absorption at elevated price points.
For Market Incumbents: Lock in certified milk pool access through long-term cooperative agreements in Bavaria and Wisconsin before three-year land conversion timelines delay new entrant supply. Prioritize blockchain-enabled traceability infrastructure to preempt EFSA documentation demands and defend shelf-space allocations against private-label encroachment in German discounters. Retrofit legacy processing lines for thermal cleaning systems to satisfy REACH chemical authorization restrictions eliminating legacy sanitizing chemistries.
For New Entrants and Emerging Players: Direct-to-specialty-retail platforms in France's Île-de-France region offer the most penetrable route, bypassing consolidated foodservice procurement controlled by incumbent processors with integrated traceability. Target goat milk variant production where margin premiums over cow milk equivalents sustain capital recovery despite extended certification timelines. Launch with single-origin provenance storytelling aligned with retailer sustainability scoring requirements to secure refrigerated footprint allocations.
For Investors and Strategic Acquirers: Consolidation pressure builds where three-year organic land conversion requirements and retrofit capital demands exceed standalone processor capacity, creating acquisition opportunities for cooperative-owned dairies with captive farmer bases. Focus on mid-scale French and German processors with protected designation heritage assets and established specialty retail relationships. Watch EU-US bilateral organic equivalence negotiations as the inflection signal determining supply routing optionality and import lot viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | German processors piloting systems preempt EFSA batch-level documentation mandates. |
| Cooperative Milk Pool Expansion | Farmer-owned structures in Wisconsin and Denmark secure captive certified supply. |
| Thermal Cleaning Retrofit | French facilities eliminate REACH-restricted sanitizing agents from production lines. |
| Goat Milk Variant Development | Specialty retail channels in France absorb margin-enhancing variants at steep premiums. |
| Direct Foodservice Partnership | Contract caterers in Germany consolidate procurement around single-source traceable suppliers. |
Methodological Framework
Direct dialogue with organic dairy processors, cooperative farmer representatives, specialty retail category buyers, and EFSA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from EU Organic Regulation implementation documents, USDA National Organic Program pasture mandate filings, ANSM chemical authorization updates, and trade customs records tracking certified organic cheese flows. Bottom-up volume estimates from processor capacity and milk pool data triangulated against top-down absorption modeling across German, French, and US retail channels.
Bottom-up segment modeling across product type, milk source, and packaging format dimensions converged with top-down macroeconomic elasticity assumptions across the analysis window. CAGRs derived from historical certified organic dairy growth patterns adjusted for regulatory phase-in timelines and channel migration trajectories. Forecast inputs incorporated EU Organic Regulation feed verification compliance rates, pasture-based protocol adoption curves, and specialty retail refrigerated footprint expansion plans.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled milk provenance tracking would alter the outlook if retailer sustainability scoring requirements accelerate faster than processor infrastructure investment. Deviation in EU-US bilateral organic equivalence negotiations or EFSA residue testing protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Emmental Cheese Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Table Butter Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Goat Milk Market
Dairy Products
Natural Cheese Market
Dairy Products
North America Sour Cream Market
Dairy Products
Cream Market
Dairy Products
China Dairy Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Colombia Dairy Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Canada Casein and Caseinate Market