
 Enzyme Modified Cheese Market | 2026-2036
Enzyme Modified Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Enzyme Modified Cheese Market Analysis
REACH compliance is recalibrating the cost-of-entry calculus for European enzyme-modified cheese suppliers, forcing reformulation investments that smaller producers struggle to absorb. Kerry Group plc leverages its integrated enzyme supply chain to sustain margin stability amid these regulatory shifts. DSM anchors its position through specialized lipase portfolios tailored to clean-label dairy applications. Novozymes A/S competes on fermentation-scale efficiency, extending its reach across industrial cheese flavoring contracts.
Enzyme modified cheese refers to natural cheese subjected to controlled proteolysis or lipolysis using food-grade enzymes, typically achieving flavor intensification five to twenty times that of unmodified base cheese within hours rather than months of traditional aging. Its primary commercial purpose centers on delivering concentrated, consistent cheese flavor to processed foods without proportional increases in fat or solids content. Spreadable cheese formulations dominate current volume given their integration into convenience-oriented retail and food service channels, while snacking applications represent the fastest-growing demand pocket as portable protein formats expand. Industrial end users command the deepest margin pools due to bulk procurement scale and long-term supply agreements with enzyme houses.
The FDA governs enzyme safety and GRAS status for dairy applications in the United States, while EFSA evaluates novel enzyme preparations for the European market, and FSSAI establishes permissible enzyme categories for cheese modification in India. These frameworks collectively determine which enzymatic treatments achieve commercial scale and which remain confined to regional niche production. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as clean-label expectations tighten across major dairy-importing economies.
Market Dynamics
Clean-label reformulation mandates from major retail chains are compressing acceptable ingredient lists, forcing enzyme-modified cheese suppliers to eliminate synthetic carriers while maintaining flavor intensity parity with legacy formulations.
Growth Catalysts
- Quick-service restaurant procurement:Burger chains and pizza operators in the United States source enzyme-modified cheese concentrates for sauce and topping applications at volumes exceeding traditional natural cheese inputs.
- FDA GRAS pathway modernization:Streamlined enzyme safety reviews accelerate commercialization timelines for novel lipase preparations targeting dairy flavor enhancement.
- Controlled lipolysis systems:Precision fermentation infrastructure enables batch-to-batch flavor consistency that artisan aging cannot replicate, attracting industrial food manufacturers.
Market Restraints
- Enzyme input cost volatility:Food-grade lipase and protease prices fluctuate with microbial fermentation substrate markets, squeezing compounder margins during commodity spikes.
- European supply concentration:REACH-compliant enzyme production clusters in the Netherlands and Denmark, creating single-source vulnerability for clean-label formulations.
- Natural cheese substitution:Aged cheddar and parmesan flavor concentrates from extended maturation programs compete on authenticity positioning in premium retail channels.
Strategic Opportunities
- India FSSAI enzyme categories:Permissible enzyme lists for cheese modification are expanding, opening formulation licensing opportunities for exporters targeting dairy processing growth in Maharashtra and Gujarat.
- Plant-based cheese analogs:Enzyme-modified dairy proteins deliver authentic cheese notes to oat and cashew bases, addressing flavor gaps that deter flexitarian adoption.
- Direct-to-manufacturer digital platforms:Bulk ingredient marketplaces bypass traditional distributor markups for mid-sized sauce and snack compounders seeking transparent pricing.
Industry Challenges
- Flavor chemist talent scarcity:Cross-trained professionals combining enzymology with sensory science command premium compensation, constraining R&D throughput at emerging suppliers.
- Clean-label certification timelines:Non-GMO Project and organic enzyme verification processes extend product launch schedules by eight to fourteen months.
- Legacy ERP integration:Batch tracking systems for enzyme activity measurement require middleware development to connect with existing dairy processor inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzyme Modified Cheese Market |
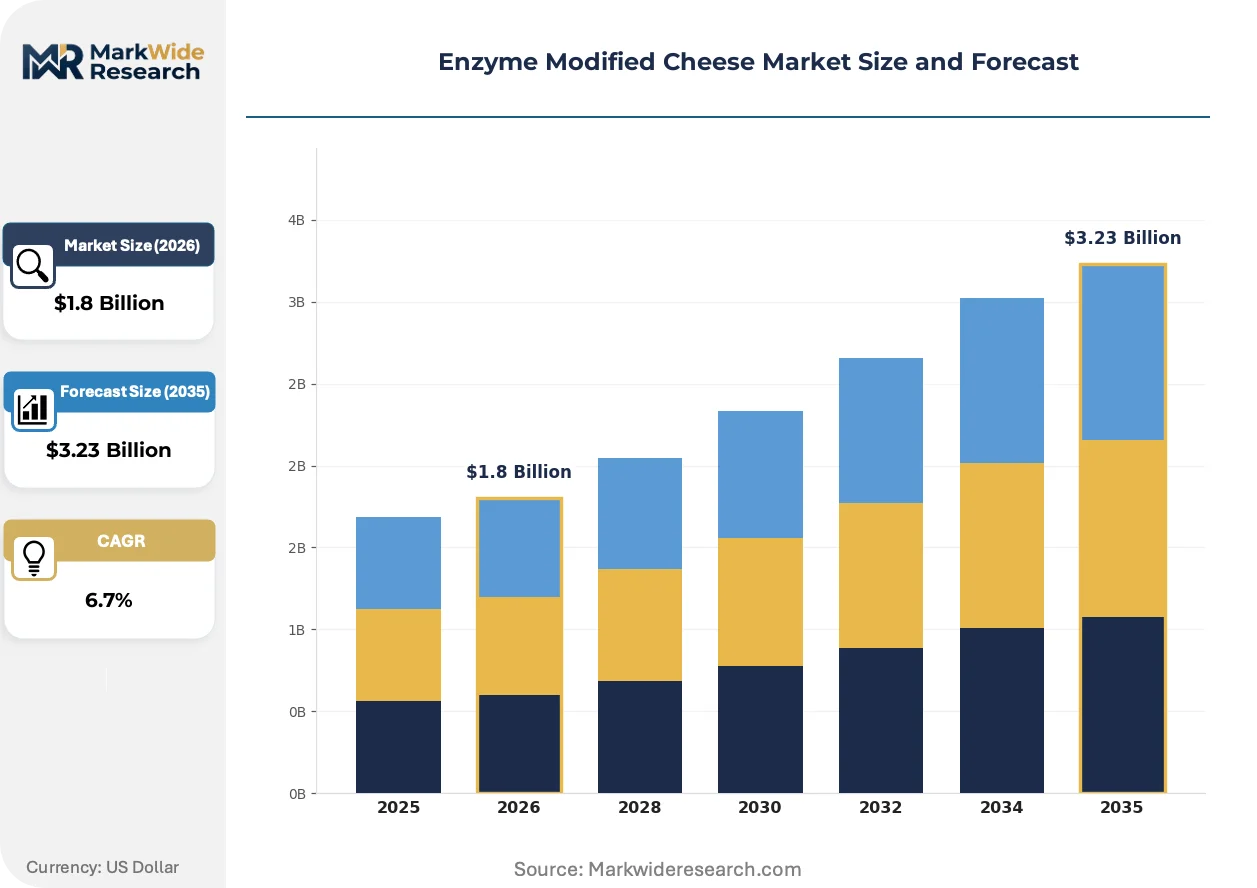
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cheese, Hard Cheese, Processed Cheese, Spreadable Cheese Application: Cooking, Baking, Snacking, Flavoring End User: Food Service, Retail, Industrial, Catering Packaging Type: Plastic Wrap, Vacuum Sealed, Tubs, Slices |
| Companies Covered | DuPont de Nemours, Inc., Jeneil Biotech Inc., Kerry Group plc, CP Ingredients, Kanegrade, Novozymes A/S, DSM, Flaverco, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzyme Modified Cheese Market Emerging Trajectories
Precision fermentation infrastructure and regulatory disclosure requirements are converging to reshape how enzyme-modified cheese achieves commercial scale and buyer acceptance across food manufacturing channels.
Microbial lipase production via submerged fermentation is consolidating flavor compound manufacturing into fewer, larger-capacity facilities. Industrial sauce manufacturers in the United States now specify fermentation-derived enzymes over animal-origin alternatives in procurement contracts. This technology shift compresses the supplier base while enabling batch volumes that solvent-extraction methods cannot match.
EFSA novel food enzyme evaluations are extending safety dossier requirements for protease preparations used in accelerated cheese aging. European compounders must submit extended toxicity studies that US FDA GRAS notifications do not require. Clean-label dairy processors in Germany and France are reformulating around pre-approved enzyme lists to avoid regulatory delays.
Food service operators are unbundling cheese flavor procurement from dairy commodity purchasing, creating separate tender processes for concentrated enzyme-modified inputs. Quick-service chains in the United States now contract directly with enzyme houses for custom flavor profiles rather than sourcing through dairy cooperatives. This disintermediation concentrates buying power among the largest restaurant groups while fragmenting supplier relationships.
Enzyme Modified Cheese Market Segmentation
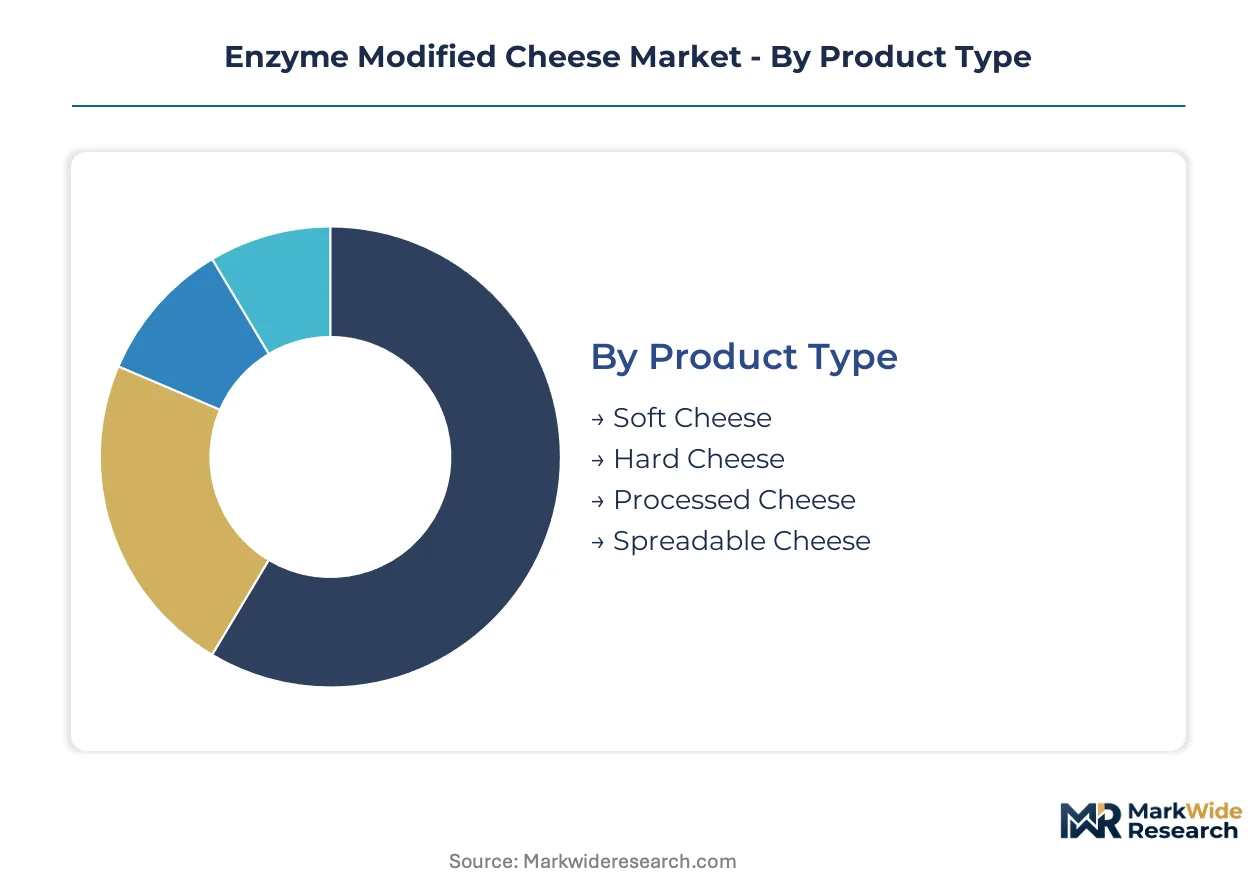
Enzyme-modified cheese serves distinct functional roles across product formats, with integration depth varying from standalone retail formats to embedded industrial concentrates. Segment boundaries reflect divergent supply chain configurations, regulatory exposure, and margin structures that reshape supplier prioritization.
Product Type:
Standalone retail formats demand full flavor intensity without additional processing, while embedded industrial inputs sacrifice some concentration for formulation flexibility.
- Soft Cheese:High-moisture bases undergo rapid proteolysis to develop creamy, rounded flavor profiles suited for cold-application sauces. Quick-service restaurant chains in the United States specify soft cheese concentrates for dip and dressing programs where spreadability governs performance.
- Spreadable Cheese:Optimized lipid-protein matrices accept enzyme modification without syneresis, delivering consistent pumpability across temperature fluctuations. Retail channel growth in convenience-oriented formats accelerates as single-serve portions expand in grab-and-go dairy cases.
- Hard Cheese:Extended lipolysis generates sharp, crystalline flavor notes mimicking aged parmesan or romano; limited by longer modification cycles and higher enzyme input costs.
- Processed Cheese:Emulsifying salts and enzyme-modified concentrates combine in industrial melting applications; formulation transparency pressures mount under clean-label retail mandates.
Volume placements concentrate in Spreadable Cheese; the faster expansion belongs to Soft Cheese.
Application:
Heat exposure during end-use determines enzyme stability requirements and flavor volatility constraints across formulation specifications.
- Cooking:Sauces, soups, and prepared meals incorporate enzyme-modified cheese for flavor density without fat addition; thermal degradation limits drive selection toward heat-stable lipase preparations.
- Flavoring:Concentrated pastes and powders deliver cheese notes to seasonings, coatings, and savory snacks; precision dosing requirements favor standardized enzyme activity specifications.
- Baking:Filled pastries and savory baked goods demand moisture retention alongside flavor release; enzyme selection balances proteolysis depth with structural integrity.
- Snacking:Portable protein formats and cheese crisps represent emerging uptake as manufacturers seek authentic dairy positioning in better-for-you categories.
Procurement scale favors Cooking applications; steepest expansion trajectory resides in Snacking.
End User:
Buying power concentration and technical specification sophistication diverge sharply across customer types, fragmenting supplier engagement models.
- Industrial:Bulk compounders and sauce manufacturers negotiate long-term enzyme supply agreements with volume-based pricing; specification control enables custom flavor profile development.
- Food Service:Chain operators disaggregate cheese flavor procurement from commodity dairy purchasing, creating direct contracting opportunities with enzyme houses for concentrated inputs.
- Retail:Private-label programs and branded spreadable lines face clean-label reformulation deadlines from major supermarket banners compressing acceptable ingredient declarations.
- Catering:Institutional feeding operations prioritize cost stability over flavor intensity, sourcing through redistributors with limited technical specification involvement.
Margin depth pools in Industrial segments; Food Service captures the fastest share gains.
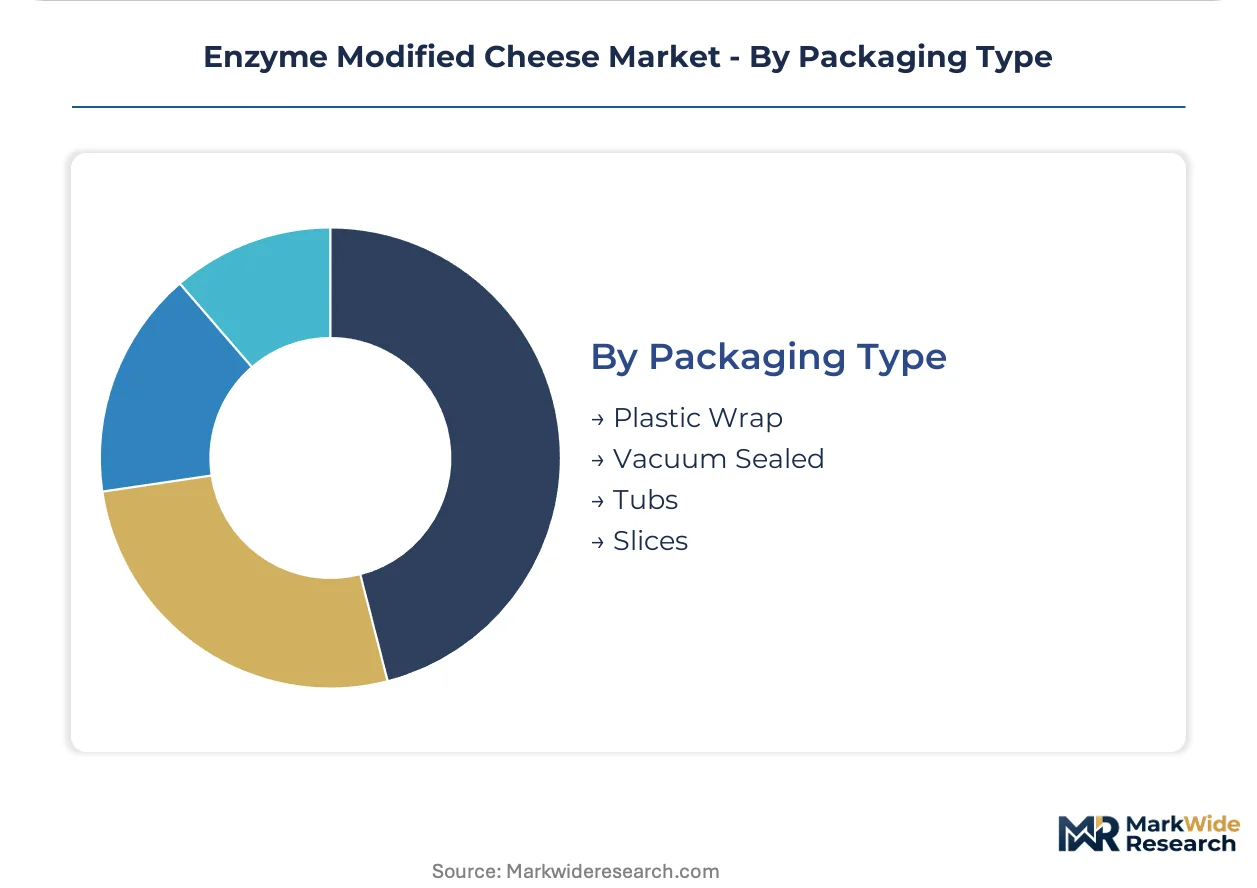
Packaging Type:
Barrier properties and portion control features align with distribution channel requirements and consumer usage occasions across format selection.
- Tubs:Reclosable rigid containers dominate food service portioning and retail spreadable segments; enzyme-modified cheese stability under repeated thermal cycling governs shelf-life claims.
- Vacuum Sealed:Oxygen exclusion extends flavor intensity retention in high-value concentrates; industrial users specify vacuum packaging for bulk enzyme-modified inputs to prevent oxidative rancidity.
- Slices:Individually wrapped portions serve quick-service sandwich assembly and retail convenience positioning; modified atmosphere requirements add cost layer.
- Plastic Wrap:Basic barrier protection for block and wedge formats; limited to short-distribution-radius applications where flavor degradation risks remain manageable.
Tub configurations anchor current volume; Vacuum Sealed formats climb fastest on industrial specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra drive enzyme-modified cheese concentration through dairy processing incentives. Tax holidays for food technology investments pull formulation laboratories toward these corridors.
United States
Quick-service restaurant chains in Chicago and Dallas source concentrated cheese flavors at volumes exceeding traditional dairy inputs. FDA GRAS pathway modernization accelerates novel lipase approvals for dairy applications. Wisconsin dairy cooperatives integrate enzyme modification lines to supply industrial sauce manufacturers.
Netherlands
REACH-compliant enzyme production clusters around Rotterdam and Eindhoven serve clean-label dairy processors across Northern Europe. ECHA registration requirements force smaller compounders toward pre-approved enzyme lists. DSM anchors specialized lipase manufacturing for accelerated cheese aging programs.
India
FSSAI permissible enzyme category expansion opens formulation licensing for exporters targeting Maharashtra and Gujarat dairy growth. Central government PLI scheme subsidies for food processing infrastructure reduce capital barriers. Anand and Bangalore host emerging enzyme application laboratories serving regional cheese processors.
Germany
Clean-label retail mandates from Berlin and Munich supermarket banners compress acceptable ingredient declarations for spreadable cheese. EFSA novel food enzyme evaluations extend safety dossier timelines for protease preparations. Bavarian dairy cooperatives reformulate around pre-approved enzyme lists to avoid regulatory delays.
Denmark
Novozymes A/S fermentation-scale efficiency attracts industrial cheese flavoring contracts from Copenhagen biotech corridors. Danish EPA alignment with REACH standards enables seamless EU market access. Aarhus hosts precision fermentation facilities supplying lipase concentrates to continental sauce manufacturers.
Enzyme Modified Cheese Market Vendor Landscape
United States producers anchor one tier; European specialists hold regulatory compliance advantages. The supplier base concentrates around integrated enzyme houses and dairy compounders with captive fermentation capacity. Three archetypes dominate: fermentation-scale lipase manufacturers, dairy-processor-integrated flavor houses, and specialized clean-label formulators. M&A activity targets enzyme technology access; capacity expansion concentrates in REACH-compliant zones.
Within the integrated tier, Kerry Group plc and DSM exemplify supply chain control strategies. Novozymes A/S occupies a position representing fermentation efficiency at scale. DuPont de Nemours, Inc. and Chr. Hansen Holding A/S sit within the specialty enzyme archetype. Jeneil Biotech Inc. and CP Ingredients represent regional formulators adapting to clean-label mandates. Kanegrade and Flaverco exemplify flavor house positioning for industrial end users.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Jeneil Biotech Inc. |
| Kerry Group plc |
| CP Ingredients |
| Kanegrade |
| Novozymes A/S |
| DSM |
| Flaverco |
| Chr. Hansen Holding A/S |
| Others |
Supply Flow & Price Mechanics
Quick-service restaurant procurement concentration in the United States anchors contract-based pricing for enzyme-modified cheese concentrates, with long-term offtake agreements commanding premium stability over spot market volatility.
Pricing Analysis
Short lead-time premiums separate emergency procurement from scheduled contract volumes in enzyme-modified cheese supply. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation scale, certification grade, and formulation complexity. Cost compression in standard-tier concentrates is intensifying because REACH-compliant enzyme input costs fluctuate with microbial substrate markets. Industrial sauce manufacturers exhibit lowest price sensitivity due to specification lock-in, while mid-sized snack compounders drive spot-market discount negotiations.
Supply Chain Analysis
Cold-chain freight costs from Netherlands and Denmark fermentation clusters to continental European processors represent a structural cost layer that US-based suppliers bypass for North American quick-service chains. Geographic supply concentration centers on the Netherlands, Denmark, and the United States, with REACH-compliant production anchoring European clean-label output. Raw material dependencies include microbial fermentation substrates, food-grade lipase concentrates, and dairy protein bases. Single-source vulnerability persists around specialized lipase portfolios from DSM and Novozymes A/S facilities. Distribution runs through enzyme houses to industrial compounders, with direct contracting bypassing traditional dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
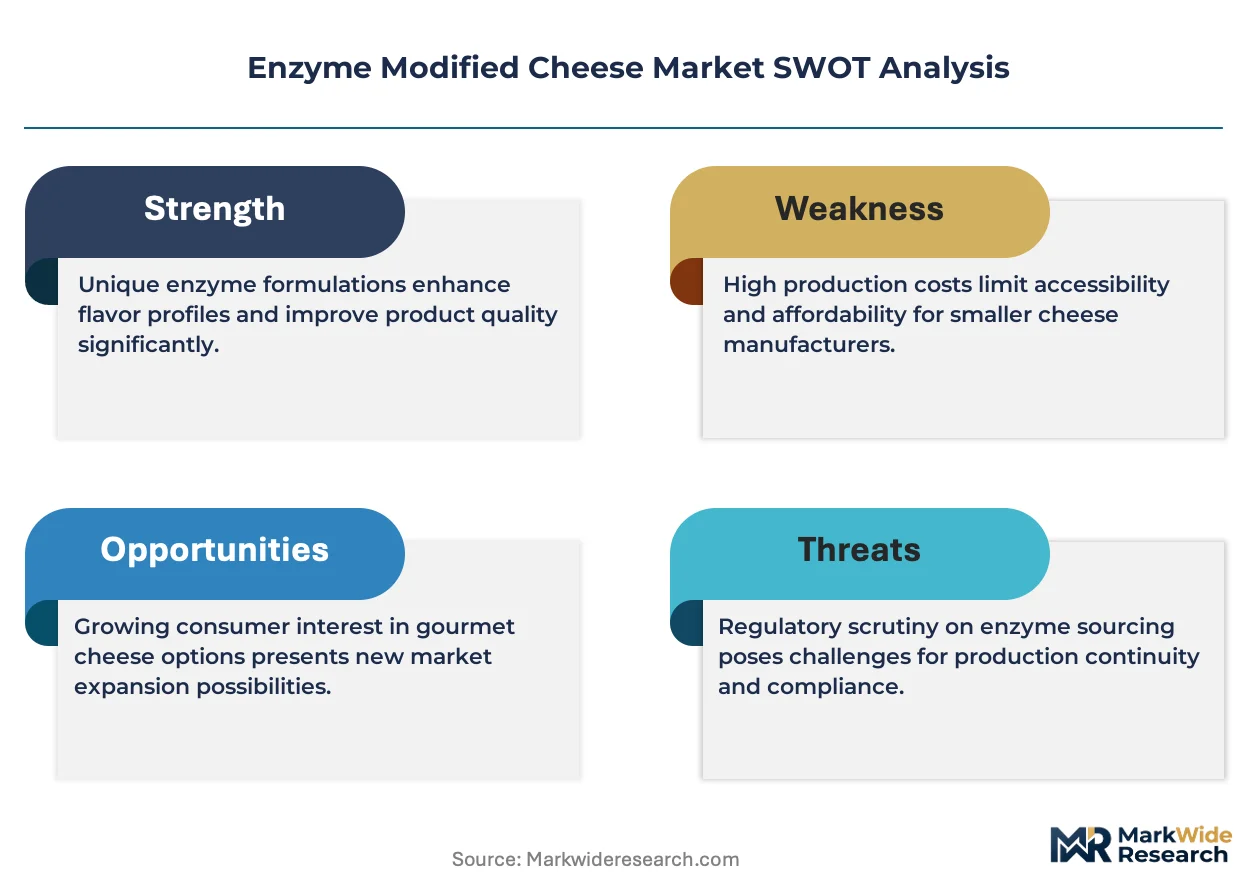
Enzyme-modified cheese supply remains constrained by REACH-compliant fermentation capacity concentration in Rotterdam and Eindhoven corridors, propping pricing power for holders of pre-approved enzyme registrations.
For Market Incumbents: Lock in multi-year enzyme supply agreements with Maharashtra and Gujarat dairy processors before FSSAI category expansion triggers demand surges. Defend formulation portfolios against natural cheese substitution threats by accelerating clean-label certification timelines. Prioritize captive lipase production capacity in Denmark or the Netherlands to shield margin stability from substrate volatility. For New Entrants and Emerging Players: Begin with plant-based cheese analog flavoring applications, where enzyme-modified dairy proteins address authenticity gaps in oat and cashew bases that incumbents underweight. Target mid-sized US snack compounders seeking transparent bulk pricing through direct digital platforms. Establish technical credibility through precision fermentation partnerships before scaling to quick-service restaurant qualification. For Investors and Strategic Acquirers: The window for entry favors fermentation-scale specialists with existing EFSA safety dossiers over de novo regulatory submissions. Long-term viability hinges on backward integration into microbial lipase production rather than formulation-only positioning. Watch FDA GRAS pathway modernization velocity as the inflection signal determining whether novel enzyme preparations achieve commercial scale acceleration or face extended review bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Capacity Expansion | Rotterdam and Eindhoven fermentation clusters anchor clean-label supply security for European dairy processors. |
| FSSAI Formulation Licensing | Maharashtra and Gujarat dairy growth corridors open first-mover positioning as permissible enzyme categories expand. |
| Precision Fermentation Partnership | Submerged fermentation infrastructure enables batch volumes that solvent-extraction methods cannot match for industrial sauce manufacturers. |
| Direct-to-Manufacturer Platform Launch | Digital bulk marketplaces bypass distributor markups for mid-sized US snack and sauce compounders seeking price transparency. |
| Clean-Label Certification Investment | Non-GMO Project and organic enzyme verification accelerates product launch schedules for retail private-label programs. |
Methodological Framework
Multi-period observation of FDA GRAS notification timelines, EFSA novel food enzyme evaluation queues, and FSSAI permissible category expansions anchored the trend analysis, supplemented by interviews with fermentation technology directors, enzyme procurement managers at industrial sauce manufacturers, regulatory affairs leads at dairy compounders, and flavor chemists at clean-label formulators. Secondary validation drew from FDA GRAS notices, EFSA safety dossier publications, FSSAI gazette notifications, customs trade data for enzyme concentrate flows, and SEC filings from integrated enzyme houses. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down market sizing from trade association estimates.
Input-output matrices mapped enzyme activity specifications to end-use formulation requirements across the projection horizon, with segmentation dimensions spanning product type, application heat exposure profile, end-user buying power concentration, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement volumes and forward-looking capacity expansion announcements. Forecast inputs included quick-service restaurant chain expansion plans, REACH registration renewal schedules, and precision fermentation yield improvement trajectories.
Underlying measurement precision varies by segment; industrial end-user volumes carry tighter precision than emerging snacking applications due to contract disclosure requirements. Forecasts reflect assumptions around regulatory approval velocity and enzyme input cost stabilization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Spicy Dairy Products Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
China Dairy Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Table Butter Market
Dairy Products
North America Milk Powder Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
United States Casein Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Canada Casein and Caseinate Market