
 North America A2 Milk Market | 2026-2036
North America A2 Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America A2 Milk Market Intelligence
Asset-light contract manufacturing and third-party dairy processing agreements is narrowing the capital barrier for new entrants in premium fluid milk. The a2 Milk Company Limited leverages direct-to-consumer subscription channels to sustain brand loyalty in the United States. Danone S.A. anchors its North American portfolio through specialty yogurt lines that compete on protein positioning. Saputo controls extensive cold-chain distribution networks that dominate Canadian retail placement.
A2 milk contains exclusively the A2 beta-casein protein variant, produced through selective herd breeding and genomic screening of Holstein and Jersey cattle. Its primary commercial purpose is to serve consumers who experience digestive discomfort from A1 beta-casein while maintaining conventional milk's nutritional profile. A2 Whole Milk captures the largest margin pool among product types, while A2 Yogurt posts the fastest volume trajectory as fermentation extends shelf appeal. Online Retail reshapes customer acquisition economics, though Supermarkets still occupy the dominant throughput position for family purchasing.
The FDA enforces fluid milk identity standards that govern protein labeling claims, while USDA organic certification creates a parallel premium tier that many A2 producers pursue. Health Canada and the Canadian Food Inspection Agency maintain comparable dairy grading rules that affect cross-border product positioning. Stakeholders must monitor evolving genomic testing costs and herd conversion timelines as these variables determine supply scalability faster than consumer demand signals.
Market Dynamics
Selective breeding programs and genomic verification protocols are compressing herd conversion timelines, allowing A2 milk supply to scale faster than conventional premium dairy categories. This structural acceleration is reshaping competitive entry economics across the United States and Canada.
Growth Catalysts
- USDA Organic Certification:Dual-certified A2-organic products command shelf-space premiums in California and Pacific Northwest retail clusters, expanding addressable household penetration.
- Digestive wellness positioning:Residential consumers with self-diagnosed lactose sensitivity are migrating to A2 fluid milk as a perceived gentler alternative without nutritional compromise.
- Specialty dairy processing infrastructure:Third-party toll processors in Wisconsin and Quebec are adding dedicated A2 segregation lines, lowering capital barriers for brand entrants.
Market Restraints
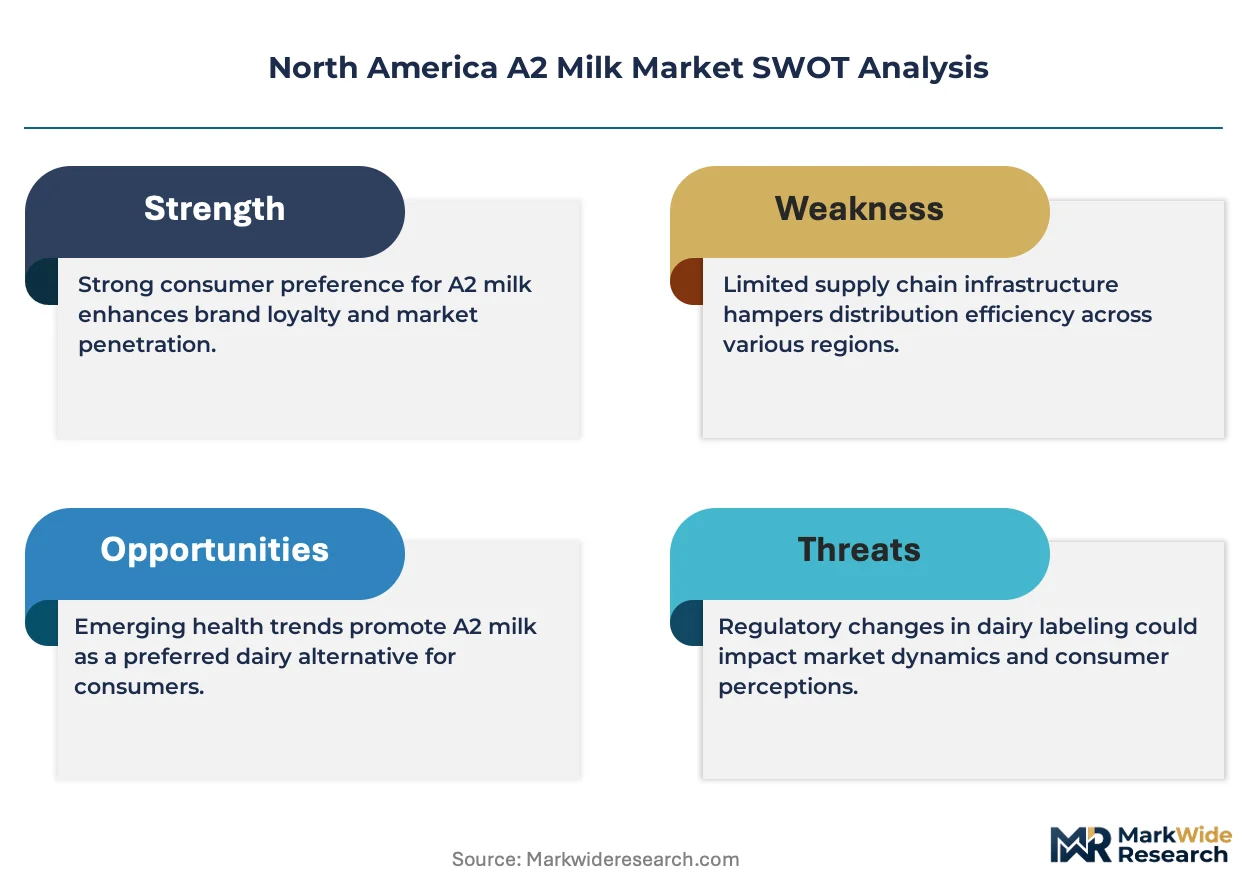
- Genomic testing cost volatility:PCR verification of beta-casein variants in Holstein and Jersey herds fluctuates with veterinary diagnostics pricing, squeezing margin predictability for producers.
- Canadian supply concentration:Saputo's dominance over cold-chain distribution networks in Ontario and Quebec limits independent brand access to mainstream retail placement.
- Fluid milk identity standards:FDA protein labeling restrictions prevent explicit digestive health claims, constraining marketing differentiation against plant-based alternatives.
Strategic Opportunities
- Direct-to-consumer subscription channels:The a2 Milk Company's U.S. e-commerce infrastructure demonstrates recurring revenue potential bypassing traditional retail slotting fees.
- Fermented product extension:A2 yogurt and kefir applications leverage extended shelf stability to penetrate convenience store and foodservice channels underserved by fluid milk.
- Canadian underpenetration:British Columbia and Alberta retail markets show lower A2 SKU density relative to California, presenting geographic white space for portfolio expansion.
Industry Challenges
- Herd conversion timelines:Converting conventional dairy operations to A2-exclusive production requires 18-24 month breeding cycles, creating supply-demand mismatches during demand surges.
- Genomic technician scarcity:Certified bovine genetic screening specialists are concentrated in Wisconsin and California, limiting rapid herd verification in secondary dairy states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America A2 Milk Market |
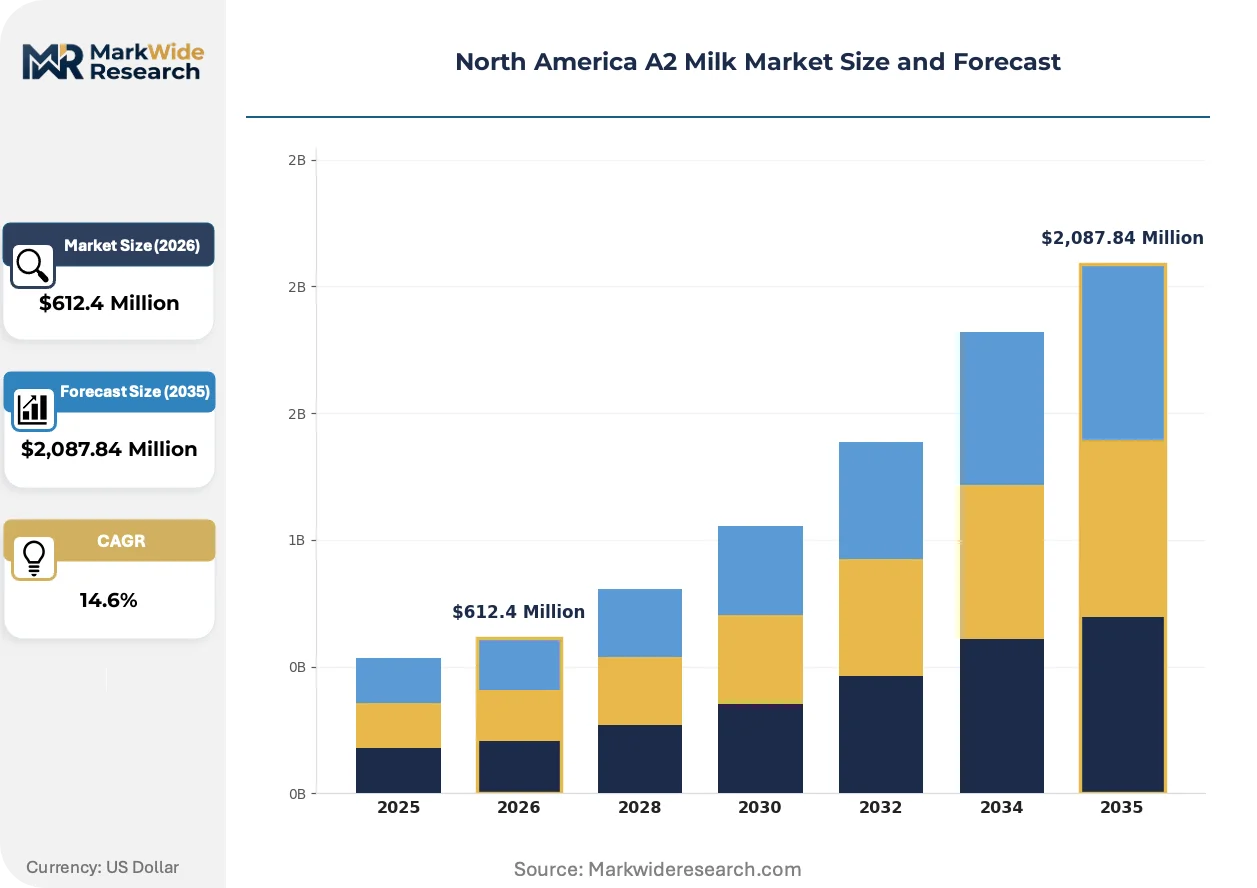
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,087.84 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: A2 Whole Milk, A2 Skim Milk, A2 Cream, A2 Yogurt Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Customer Type: Health-Conscious Consumers, Families, Athletes, Lactose Intolerant Individuals End User: Residential, Food Service Establishments, Cafes, Schools |
| Companies Covered | Groupe Lactalis, Danone S.A., The a2 Milk Company Limited, Westland Milk Products, Arla Foods, Nestlé S.A., Fonterra, Friesland Campina, Saputo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America A2 Milk Market Strategic Shifts & Innovations
Genomic screening and precision fermentation are converging to reshape how A2 protein supply chains authenticate and scale. These technical advances are compressing verification costs while opening new product format possibilities.
CRISPR-assisted genomic selection is hybridizing conventional breeding programs with marker-assisted verification, allowing dairy cooperatives in Wisconsin and California to identify A2 allele carriers at embryo stage. Mid-scale herd operators are adopting this screening protocol to accelerate conversion timelines. The technology is compressing the traditional 5-year herd turnover cycle into 18-month conversion windows.
FDA enforcement discretion on A2 beta-casein labeling is tightening identity standards for fluid milk protein claims, requiring third-party verification documentation for retail packaging. This regulatory pressure is forcing smaller processors to outsource genomic certification to accredited veterinary laboratories. The Pacific Northwest organic dairy segment is responding fastest, integrating USDA organic and A2 verification into unified audit protocols.
Subscription-based replenishment models are displacing conventional supermarket stock-up behavior among health-conscious households in metropolitan California and Vancouver. Direct-to-consumer platforms are capturing recurring purchase commitments that insulate brands from retail price volatility. This channel rotation is most visible in dual-income households with children under age twelve.
North America A2 Milk Market Segmentation
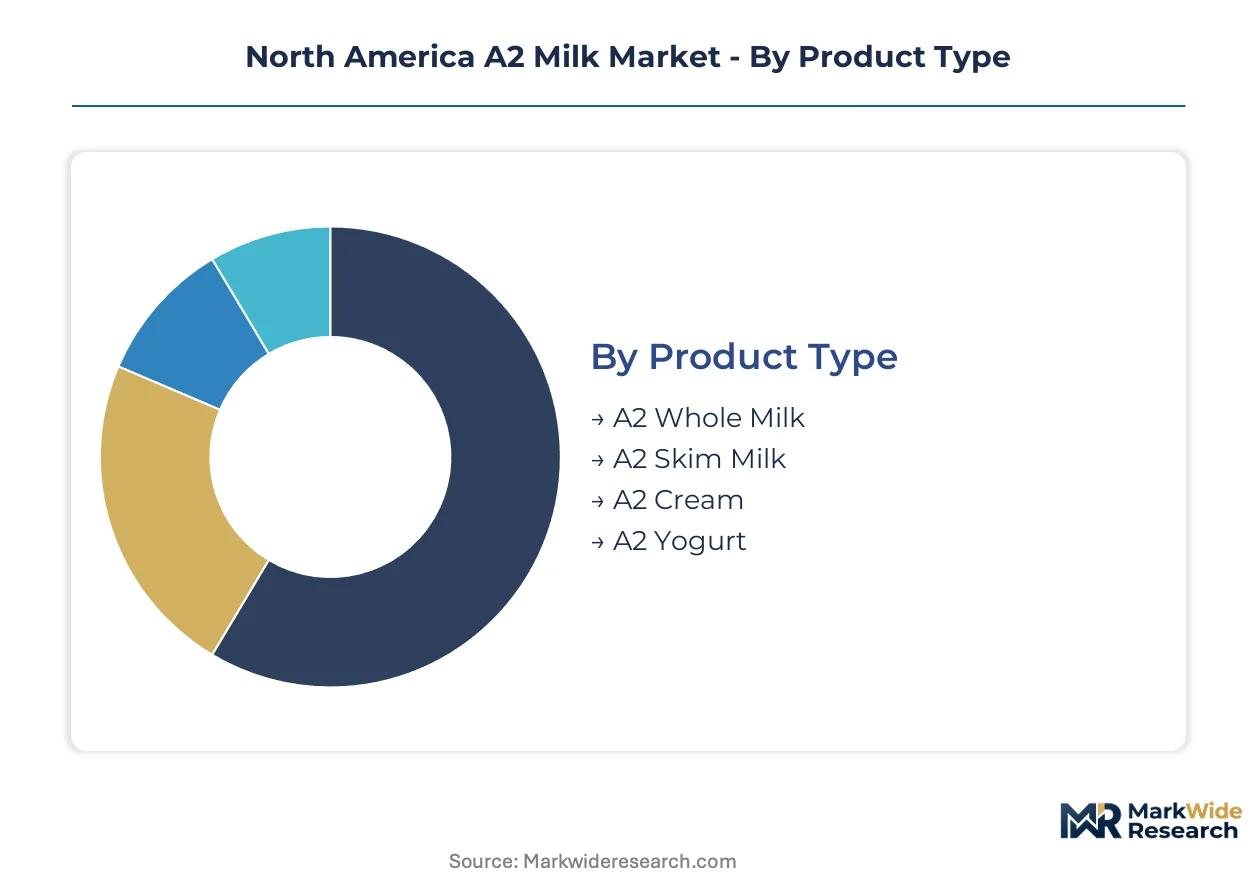
Segmentation in the North America A2 Milk Market reveals how protein-variant dairy commands differentiated positioning across fluid and fermented formats. Each dimension—product chemistry, channel access, buyer motivation, and consumption setting—creates distinct margin profiles and supply requirements.
Product Type:
Mature fluid formats anchor revenue stability while fermented derivatives reshape growth economics.
- A2 Whole Milk:Full-fat fluid milk with exclusively A2 beta-casein protein delivers the highest per-unit margins in retail dairy. California and Pacific Northwest households with children under twelve drive repeat purchase frequency due to digestive wellness positioning.
- A2 Yogurt:Fermented A2 dairy extends shelf stability from 14 days to 45+ days, unlocking convenience store and foodservice penetration. Extended fermentation protocols in Wisconsin specialty plants are scaling volume fastest as brands bypass fluid milk's cold-chain limitations.
- A2 Skim Milk:Fat-reduced A2 fluid milk serves calorie-conscious athletes and fitness-oriented consumers in metropolitan Vancouver and Los Angeles.
- A2 Cream:High-butterfat A2 dairy targets premium coffeehouse channels and residential baking applications with limited SKU proliferation.
A2 Whole Milk handles the majority of throughput; A2 Yogurt is the fastest mover on share.
Distribution Channel:
Channel selection determines customer acquisition cost and brand control intensity.
- Supermarkets:Dominant throughput position for family purchasing with established cold-chain infrastructure. California Safeway-Albertsons clusters and Ontario Loblaws banners set slotting fee benchmarks that squeeze independent brand margins.
- Online Retail:Subscription replenishment models capture recurring revenue commitments from dual-income households. Direct-to-consumer platforms in Seattle and San Francisco metropolitan areas demonstrate highest repeat purchase rates.
- Specialty Stores:Natural grocery banners like Whole Foods Market and Sprouts Farmers Market command organic-A2 dual certification premiums.
- Convenience Stores:Single-serve A2 yogurt and flavored milk formats penetrate grab-and-go occasions in urban Canadian markets.
Supermarkets still process the largest volume baskets; Online Retail is climbing the fastest on customer lifetime value metrics.
Customer Type:
Buyer motivation splits between clinical necessity and lifestyle aspiration.
- Health-Conscious Consumers:Self-directed wellness seekers migrate from plant-based alternatives to A2 dairy for complete protein without digestive trade-offs. Pacific Northwest organic dairy adopters show highest willingness-to-pay premiums.
- Families:Multi-person households prioritize A2 whole milk for children based on perceived gentleness versus conventional dairy. Suburban California school districts are piloting A2 milk in breakfast programs.
- Athletes:Protein-focused consumers in Colorado and Arizona fitness markets adopt A2 skim and recovery-oriented yogurt formats.
- Lactose Intolerant Individuals:Consumers with self-diagnosed dairy sensitivity use A2 as a bridge product before full elimination diets.
Health-Conscious Consumers generate the highest per-capita spend; Families represent the broadest addressable base.
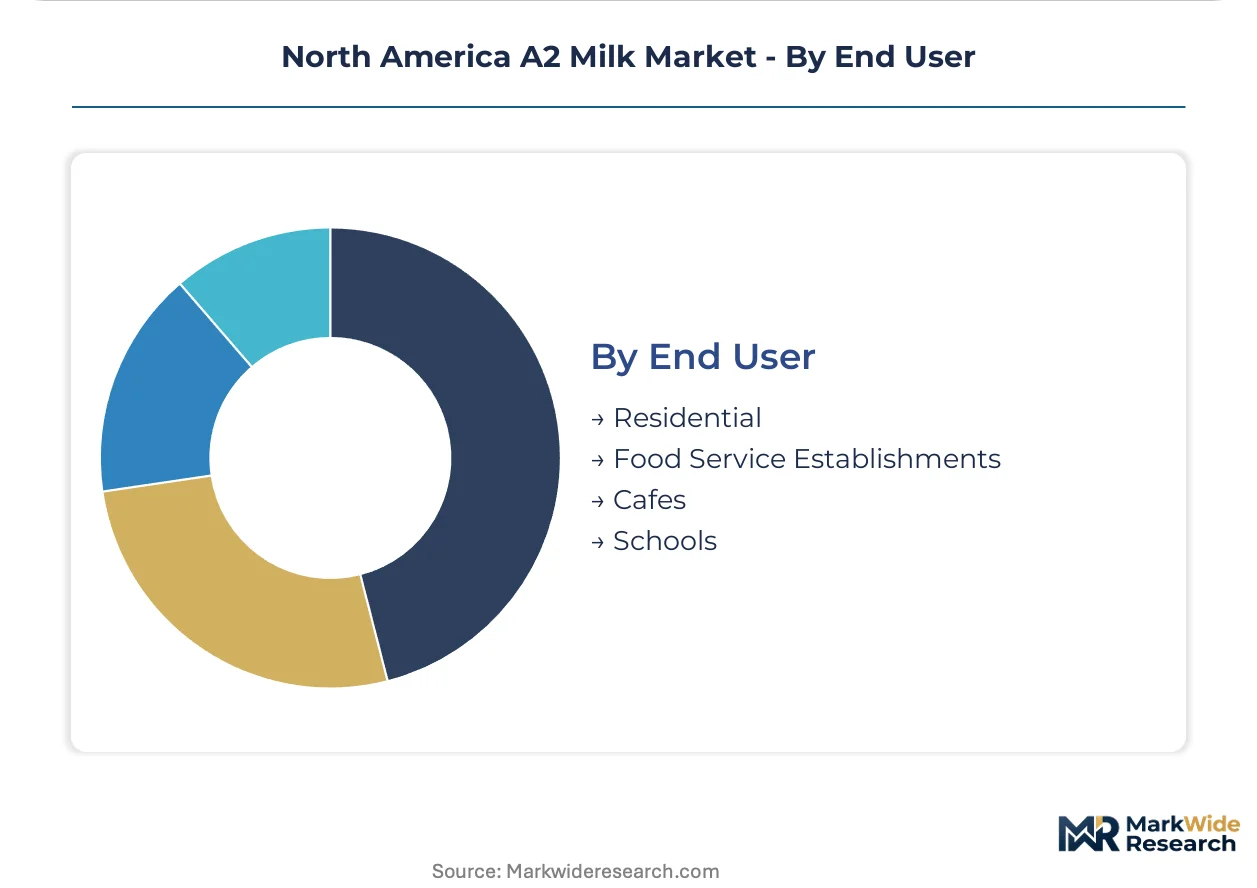
End User:
Consumption setting dictates packaging format and temperature requirements.
- Residential:Home consumption drives gallon and half-gallon fluid milk formats with weekly replenishment cycles. Canadian and U.S. suburban households show divergent preferences for bagged versus carton packaging.
- Food Service Establishments:Restaurants and institutional kitchens adopt A2 cream and whole milk for premium menu differentiation. Quebec hotel breakfast programs are early adopters of A2 yogurt parfaits.
- Cafes:Third-wave coffee operators in Portland and Toronto specify A2 whole milk for latte art performance and customer dietary accommodation.
- Schools:K-12 nutrition programs in California and British Columbia are testing A2 milk in pilot procurement contracts.
Residential settings absorb the dominant volume share; Food Service Establishments are expanding most quickly as post-pandemic away-from-home consumption recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification subsidies and FDA fluid milk identity standards are accelerating A2 dairy infrastructure investment across North American markets. Provincial dairy boards in Canada and state-level agricultural departments in the United States are deploying parallel incentive programs for genomic herd conversion. Cross-border cold-chain logistics networks are consolidating around Great Lakes and Pacific Coast distribution corridors.
United States
California health-conscious households and Pacific Northwest organic dairy adopters are driving A2 whole milk consumption in residential settings. FDA enforcement discretion on beta-casein labeling requires third-party verification documentation for retail packaging claims. Wisconsin specialty dairy processors are adding dedicated A2 segregation lines to serve toll manufacturing demand from emerging brands.
Canada
Ontario and Quebec families with children under twelve are prioritizing A2 fluid milk for perceived digestive gentleness in school nutrition programs. Health Canada and the Canadian Food Inspection Agency maintain dairy grading rules that affect cross-border product positioning and label harmonization. Saputo's dominance over cold-chain distribution networks in the Great Lakes corridor limits independent brand access to mainstream Loblaws and Sobeys retail placement.
Mexico
Mexico City metropolitan area health-conscious consumers are migrating from conventional dairy to A2 fluid milk as digestive wellness positioning gains traction. COFEPRIS nutritional labeling requirements govern protein variant claims on imported dairy products entering through Nuevo Laredo and Lázaro Cárdenas ports. Jalisco dairy cooperatives in the Bajío Region are piloting genomic screening protocols for Holstein herds supplying Mexico City convenience store channels.
North America A2 Milk Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated dairy processors with captive cold-chain infrastructure and genomic verification capabilities. The vendor base stratifies across three strategic archetypes: multinational dairy conglomerates with portfolio diversification strategies, specialized A2-only operators with direct-to-consumer subscription platforms, and regional dairy cooperatives with toll processing flexibility. Dominant competitive moves include backward integration into selective breeding programs and strategic partnerships with third-party genomic testing laboratories.
Within the multinational conglomerate tier, Danone S.A. and Nestlé S.A. exemplify portfolio diversification approaches that leverage existing yogurt and fluid milk distribution networks to absorb A2 product lines. The a2 Milk Company Limited occupies a position as the archetypal A2-specialist operator with direct-to-consumer infrastructure. Groupe Lactalis and Fonterra anchor the cooperative-processor segment with scale advantages in cross-border supply management.
| Leading Market Players |
|---|
| Groupe Lactalis |
| Danone S.A. |
| The a2 Milk Company Limited |
| Westland Milk Products |
| Arla Foods |
| Nestlé S.A. |
| Fonterra |
| Friesland Campina |
| Saputo |
| Others |
Cost & Logistics Intelligence
Undercapacity in Wisconsin and Quebec specialty dairy processing facilities is compressing toll manufacturing margins while amplifying pricing power for vertically integrated operators with captive A2 segregation lines. This utilization asymmetry forces emerging brands to absorb premium third-party processing fees or defer market entry until capacity expansion cycles complete.
Pricing Analysis
Certification level creates the primary spread, with dual USDA organic-A2 verified products commanding shelf-space premiums over conventional A2 fluid milk. Three-tier pricing structure across premium organic-A2, standard A2, and economy conventional dairy segments reflects genomic verification costs and cold-chain investment intensity. Cost compression in standard A2 tier is intensifying because toll processor queue congestion forces brands to discount for volume commitments. Families with children under twelve show lowest price sensitivity, while single-person health-conscious households in metropolitan Vancouver and Los Angeles exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Saputo and Loblaws banner retailers are squeezing working capital for independent A2 brands competing for Canadian retail placement. Supply concentrates in Wisconsin, California, and Quebec, where specialty dairy infrastructure and genomic technician clusters anchor production. Herd conversion depends on Holstein and Jersey cattle sourcing, PCR verification protocols, and selective breeding program timelines. Single-source vulnerability runs through Saputo's Great Lakes cold-chain distribution networks. Distribution runs through supermarket banner consolidation in Ontario and direct-to-consumer subscription platforms in Pacific Coast metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America A2 milk penetration remains in early-cycle expansion, with genomic screening cost compression and subscription channel maturation providing sustained adoption tailwinds through the analysis window.
For Market Incumbents: Insulate margin pools by securing backward integration into selective breeding programs and genomic verification laboratories before technician scarcity intensifies. Saputo's distribution dominance and Danone's yogurt portfolio diversification demonstrate how captive supply and format extension neutralize toll processing queue risk from emerging competitors.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure in British Columbia and Alberta, where retail SKU density lags California and Pacific Northwest penetration benchmarks. Fermented product extension into A2 yogurt and kefir formats penetrates convenience store channels underserved by fluid milk cold-chain requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across toll manufacturing-dependent entrants as asset-light contract manufacturing compresses entry barriers. Long-term viability favors acquisition targets with hybrid capabilities spanning genomic verification partnerships and subscription platform architecture. The signal to monitor is FDA enforcement discretion tightening on beta-casein labeling claims, which would accelerate consolidation toward accredited laboratory networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Verification Partnership | Third-party PCR certification from Wisconsin veterinary laboratories accelerates retail packaging compliance under FDA identity standards. |
| Direct-to-Consumer Subscription Launch | Recurring revenue platforms in Seattle and San Francisco insulate brands from Safeway-Albertsons slotting fee compression. |
| Fermented Product Line Extension | A2 yogurt and kefir formats unlock 45-day shelf stability for convenience store penetration beyond fluid milk limitations. |
| Dual Certification Investment | Unified USDA organic-A2 audit protocols capture Pacific Northwest household willingness-to-pay premiums. |
| Selective Breeding Program Integration | Captive Holstein and Jersey herd conversion compresses 18-24 month supply timelines versus conventional procurement. |
Research Approach
A spread of perspectives from dairy cooperative procurement directors, specialty processor plant managers, retail category buyers at Loblaws and Safeway-Albertsons banners, genomic laboratory technicians, and direct-to-consumer platform operators converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA fluid milk identity standard filings, USDA organic certification databases, Health Canada dairy grading regulations, and Wisconsin Department of Agriculture trade flow data. Bottom-up volume modeling triangulated against top-down addressable household penetration estimates across California, Pacific Northwest, Ontario, and Quebec regional clusters.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product chemistry (fluid versus fermented), distribution channel control intensity, customer motivation archetype, and consumption setting temperature requirements. CAGRs were derived from iterative convergence of adoption curve modeling and input cost trajectory assumptions. Industry-specific forecast inputs incorporated genomic testing cost decline curves and herd conversion timeline compression from CRISPR-assisted screening protocol adoption.
Stress conditions across PCR verification pricing volatility, Canadian cold-chain access concentration, and FDA labeling enforcement discretion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about residential digestive wellness positioning durability and subscription channel retention economics. Macroeconomic deviation, regulatory tightening on protein variant claims, or technological disruption in precision fermentation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Fluid Milk Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
North America Dairy Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Filled Cheese Market
Dairy Products
Ricotta Market
Dairy Products
United States Milk Protein Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Milk Mineral Market
Dairy Products
Dairy Blends Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Recombined Milk Market