
 Casein Hydrolysate Market | 2026-2036
Casein Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Casein Hydrolysate Market Outlook
Asset-light contract manufacturing partnerships is reconfiguring competitive entry barriers for mid-sized ingredient suppliers. FrieslandCampina Ingredients leverages its captive dairy supply base to secure raw material consistency across European production. Kerry Group anchors its position through integrated flavor-mask technology that improves hydrolysate palatability in finished applications. AMCO Proteins specializes in enzymatic hydrolysis customization for niche clinical nutrition clients.
Casein hydrolysate consists of milk protein that has undergone enzymatic breakdown into smaller peptide fractions, typically achieving degrees of hydrolysis between 10% and 20% to enhance digestibility and bioavailability. The ingredient serves primarily as a functional protein source for populations requiring rapid nitrogen absorption or reduced allergenic potential. Hydrolyzed casein leads product type demand due to its established efficacy documentation in infant formula and medical foods. Sports nutrition represents the fastest-growing application segment as endurance athletes and bodybuilders prioritize leucine-rich, rapidly absorbed protein sources. Clinical nutrition maintains the deepest margin pool, with healthcare providers and dietary supplement manufacturers paying premiums for batch-certified, allergen-controlled hydrolysate grades.
The FDA oversees GRAS self-affirmation and food additive petitions for casein hydrolysate entering U.S. food and supplement channels, while EFSA evaluates novel food and health claim submissions across European jurisdictions. ISO 22000 and HACCP certification requirements are tightening for suppliers serving infant formula manufacturers, effectively filtering smaller producers from premium contract opportunities. Stakeholders must monitor evolving peptide-bioactivity research and corresponding regulatory frameworks to anticipate which hydrolysate specifications will command future price premiums.
Market Dynamics
Enzymatic hydrolysis technology maturation is compressing production cycle times while tightening peptide consistency specifications across infant formula and clinical nutrition supply chains.
Growth Catalysts
- Sports Nutrition Demand:Endurance athletes and bodybuilders prioritize leucine-rich, rapidly absorbed protein sources, expanding hydrolyzed casein incorporation into recovery formulations and pre-workout blends.
- FDA GRAS Streamlining:The GRAS self-affirmation pathway accelerates novel protein ingredient clearance timelines, reducing regulatory friction for suppliers entering U.S. food and supplement channels.
- German Clinical Procurement:Healthcare providers in Germany are tightening quality specifications for batch-certified, allergen-controlled hydrolysate grades, pulling premium volumes from verified suppliers.
Market Restraints
- Raw Material Concentration:Captive dairy supply bases in the Netherlands and New Zealand limit independent processor access to consistent casein streams, amplifying price volatility during seasonal milk production swings.
- ISO 22000 Certification Barriers:HACCP and ISO 22000 requirements for infant formula suppliers filter smaller producers from premium contract opportunities, consolidating tender access among established players.
- Whey Hydrolysate Substitution:Alternative dairy protein hydrolysates compete on cost and taste neutrality in sports nutrition applications, pressuring casein hydrolysate volume in price-sensitive segments.
Strategic Opportunities
- Peptide Bioactivity Research:Emerging immunomodulatory and antihypertensive peptide discoveries position specific hydrolysate fractions for medical food and functional ingredient premiums.
- EFSA Health Claim Pathways:Novel food and health claim submissions across European jurisdictions create first-mover advantages for suppliers with clinical trial documentation.
- Contract Manufacturing Partnerships:Asset-light production models enable mid-sized ingredient suppliers to access infant formula manufacturer networks without capital-intensive facility investments.
Industry Challenges
- Flavor-Mask Technology Integration:Hydrolysate bitterness requires sophisticated taste modification systems, demanding cross-functional collaboration between protein scientists and sensory formulation teams.
- Batch-to-Batch Peptide Consistency:Enzymatic hydrolysis variability complicates allergen control and bioactivity claims, necessitating advanced analytical monitoring and process validation.
- Peptide-Bioactivity Regulatory Alignment:Evolving frameworks for structure-function claims create compliance timeline uncertainty as jurisdictions diverge on evidentiary standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein Hydrolysate Market |
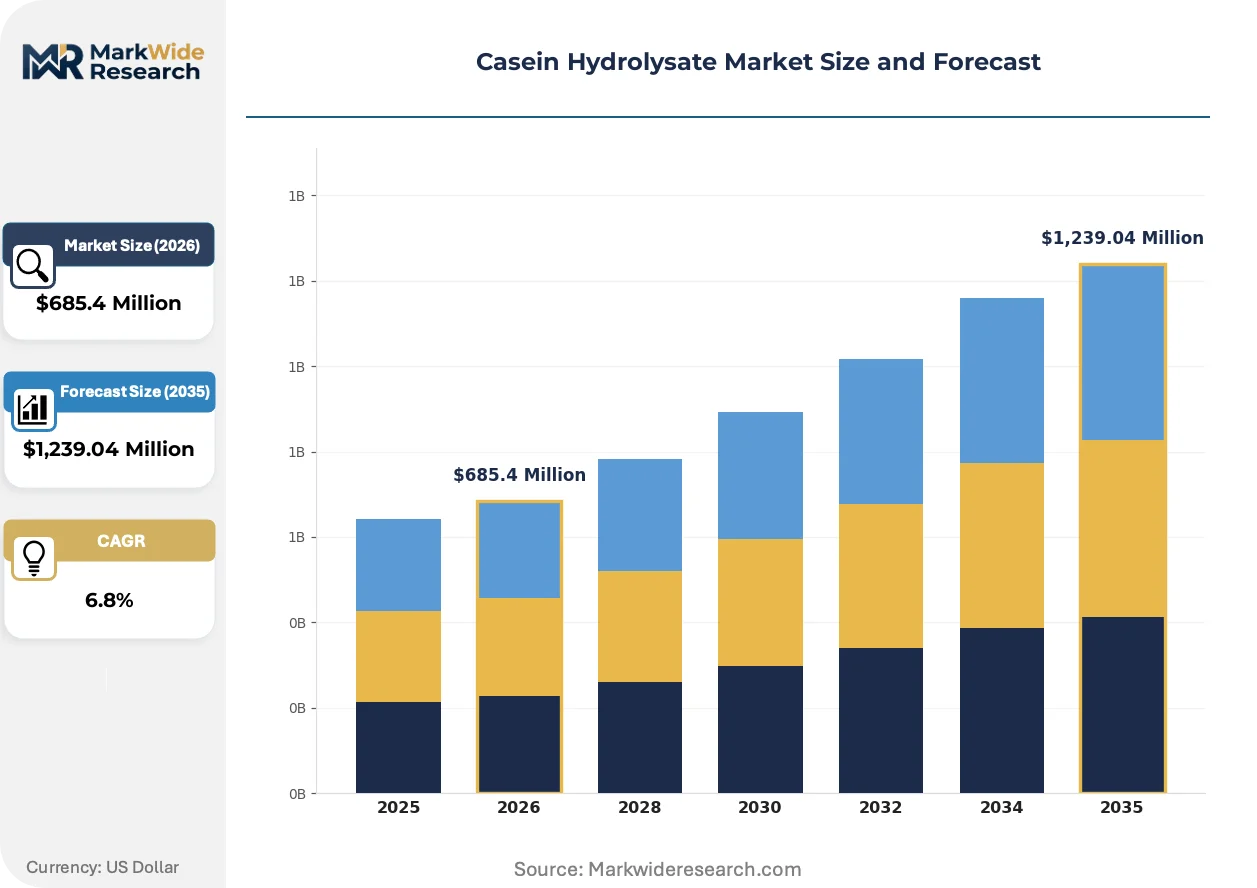
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Casein, Instant Casein, Liquid Casein, Powdered Casein Application: Sports Nutrition, Infant Formula, Clinical Nutrition, Food & Beverages End User: Healthcare Providers, Dietary Supplement Manufacturers, Food Producers, Research Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Kerry Group, FrieslandCampina Ingredients, AMCO Proteins, Lactalis Ingredients, Fonterra Co-operative Group, Cargill, Milk Specialties Global, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein Hydrolysate Market Strategic Shifts
Precision enzymatic engineering and peptide fractionation are redefining hydrolysate value propositions, shifting competition from bulk protein supply to bioactive-specific certification tiers.
Membrane filtration coupled with chromatographic peptide separation is collapsing the cost differential between standard hydrolysates and bioactive-enriched fractions. Infant formula manufacturers in Switzerland and the Netherlands are adopting these integrated systems at pilot scale. This technological convergence is collapsing traditional premium-tier pricing boundaries, forcing suppliers to demonstrate measurable bioactivity rather than degree-of-hydrolysis specifications alone.
EFSA's evolving novel food evaluation protocols are tightening peptide safety documentation requirements for hydrolysates targeting medical food applications. Manufacturers must now submit comprehensive toxicological and allergenicity data packages before market authorization. Clinical nutrition suppliers serving German and French healthcare systems are responding by investing in dedicated regulatory affairs capabilities and third-party peptide characterization laboratories.
Direct procurement relationships between sports nutrition brands and specialized hydrolysate producers are displacing traditional ingredient distributor intermediaries. Endurance supplement companies in Australia and the United States now contract directly with enzymatic processors for custom peptide profiles. This channel disintermediation concentrates volume with suppliers capable of rapid formulation iteration and co-development services.
Casein Hydrolysate Market Segmentation
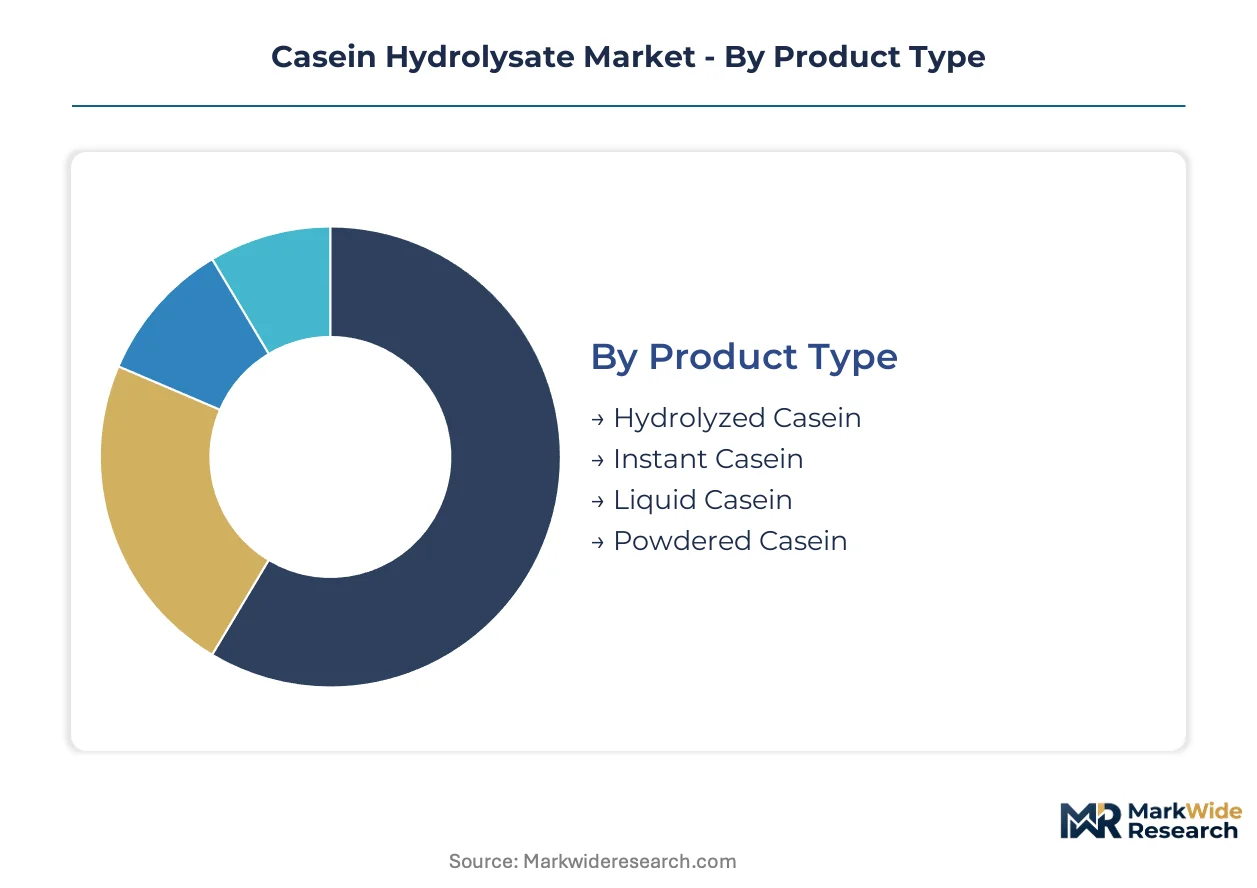
Segmentation in the casein hydrolysate market reveals how technical specifications and procurement channels create divergent margin structures. Manufacturers configure production lines differently for infant formula certification versus sports nutrition speed-to-market requirements.
Product Type:
After-sales service intensity varies sharply across product types, with infant-grade hydrolysates demanding batch-traceability support and sports nutrition variants requiring rapid formulation iteration assistance.
- Hydrolyzed Casein:Enzymatically fragmented to 10-20% degree of hydrolysis with enhanced bioavailability and reduced allergenic potential. Demand concentrates in German clinical nutrition procurement, where healthcare providers mandate batch-certified documentation for enteral feeding applications.
- Powdered Casein:Spray-dried format offering extended shelf stability and standardized particle distribution for industrial-scale blending. Sports nutrition manufacturers in Australia and the United States prioritize this format for direct procurement relationships enabling custom peptide profile co-development.
- Instant Casein:Agglomerated particles engineered for cold-water dispersibility without mechanical shear.
- Liquid Casein:Ready-to-use suspension format eliminating reconstitution steps in beverage manufacturing.
By volume, Powdered Casein leads. By growth pace, Hydrolyzed Casein is expanding most quickly.
Application:
Margin concentration follows application risk profiles, with clinical nutrition commanding premium certification tiers and sports nutrition driving volume scale through direct brand-processor partnerships.
- Clinical Nutrition:Medical-grade hydrolysates for enteral feeding, malabsorption disorders, and post-surgical recovery. German healthcare providers tighten quality specifications, pulling premium volumes from suppliers with ISO 22000 and dedicated peptide characterization laboratories.
- Sports Nutrition:Recovery formulations and pre-workout blends targeting leucine-rich, rapid amino acid delivery. Endurance athletes and bodybuilders in Australia and the United States prioritize this segment, with brands contracting directly with enzymatic processors for custom peptide profiles.
- Infant Formula:Hypoallergenic protein source for cow's milk protein allergy management in neonatal nutrition.
- Food & Beverages:Functional protein enrichment in dairy alternatives, baked goods, and fortified beverages.
Clinical Nutrition captures the deepest margin pool. Sports Nutrition posts the steepest expansion trajectory.
End User:
Procurement sophistication divides end users, with healthcare systems demanding regulatory dossiers and research institutions driving peptide bioactivity discovery.
- Healthcare Providers:Hospitals, long-term care facilities, and home healthcare services administering enteral nutrition. French and German healthcare systems invest in dedicated regulatory affairs capabilities to navigate EFSA novel food evaluation protocols.
- Dietary Supplement Manufacturers:Brands formulating finished products for sports nutrition and wellness channels. Direct procurement relationships with specialized hydrolysate producers are displacing traditional ingredient distributor intermediaries in this segment.
- Food Producers:Industrial manufacturers integrating hydrolysates into processed food matrices.
- Research Institutions:Academic and clinical laboratories investigating immunomodulatory and antihypertensive peptide fractions.
Healthcare Providers dominate premium-tier procurement. Dietary Supplement Manufacturers are gaining share fastest.
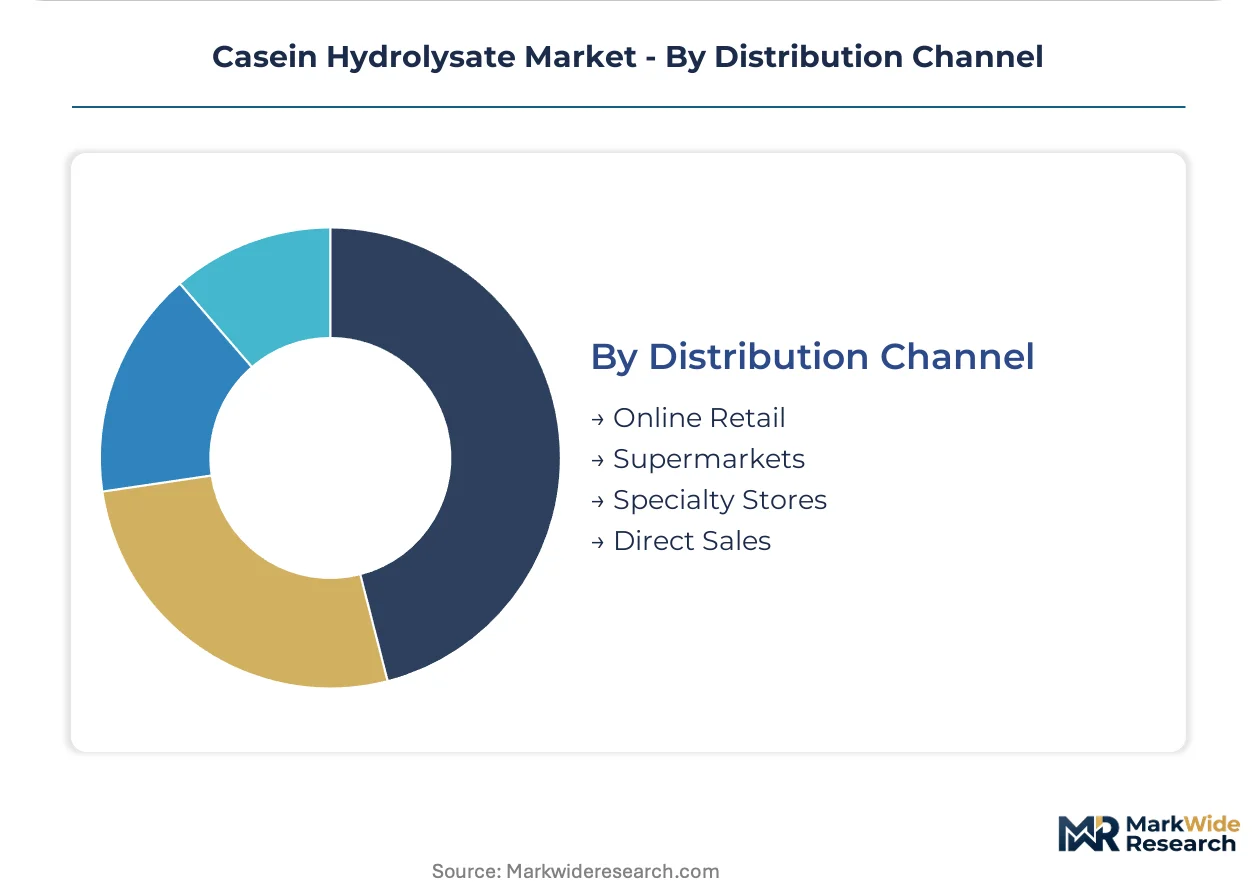
Distribution Channel:
Channel economics reflect order fragmentation patterns, with bulk direct sales supporting production planning and online retail enabling niche product experimentation.
- Direct Sales:Long-term contracts between hydrolysate producers and end-user manufacturers. Sports nutrition brands in Australia and the United States leverage this channel for rapid formulation iteration and co-development services.
- Specialty Stores:Professional-facing outlets serving clinical nutrition and sports performance specialists. Swiss and Dutch infant formula manufacturers source through this channel for pilot-scale membrane filtration and chromatographic peptide separation systems.
- Online Retail:E-commerce platforms enabling small-batch procurement and transparent specification comparison.
- Supermarkets:Mass-market retail for consumer-facing finished products containing hydrolyzed casein.
Direct Sales anchor volume commitment. Specialty Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German healthcare procurement teams command the deepest premium-tier volumes, while Australian sports nutrition brands and Dutch infant formula manufacturers reshape sourcing patterns through direct processor relationships.
Germany
Hospital enteral feeding programs and post-surgical recovery protocols drive medical-grade hydrolysate procurement. EFSA novel food evaluation protocols tighten peptide safety documentation requirements for medical food applications. Bavarian healthcare networks invest in dedicated regulatory affairs capabilities to navigate batch-certification standards.
United States
Endurance supplement companies and bodybuilding brands prioritize leucine-rich protein sources for recovery formulations. FDA GRAS self-affirmation pathways accelerate novel protein ingredient clearance timelines for food and supplement channels. California sports nutrition clusters contract directly with enzymatic processors for custom peptide profile co-development.
Netherlands
Infant formula manufacturers demand hypoallergenic protein sources with batch-traceability documentation. REACH compliance frameworks govern chemical safety assessments for enzymatic processing inputs. Dutch dairy processing corridors adopt membrane filtration and chromatographic peptide separation systems at pilot scale.
Australia
Endurance athletes and performance nutrition brands expand hydrolyzed casein incorporation into pre-workout blends. TGA therapeutic goods regulations shape quality specifications for medical-grade protein ingredients. Melbourne and Sydney sports nutrition clusters displace traditional ingredient distributor intermediaries through direct procurement relationships.
Switzerland
Clinical nutrition suppliers serving alpine healthcare systems require allergen-controlled hydrolysate grades. Swissmedic medical device and food regulations intersect with EFSA health claim pathways for functional ingredients. Basel-area pharmaceutical nutrition clusters invest in third-party peptide characterization laboratories.
Casein Hydrolysate Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Dairy cooperative giants leverage captive milk supply bases to secure raw material consistency, while enzymatic technology specialists customize peptide fractions for niche clinical applications. Strategic archetypes include integrated dairy processors, flavor-mask technology integrators, and contract manufacturing partners. Capacity expansion and asset-light production partnerships represent the dominant competitive moves reshaping market access.
Among integrated dairy processors, FrieslandCampina Ingredients and Fonterra Co-operative Group exemplify the cooperative-owned model with upstream supply control. Kerry Group occupies a position bridging flavor technology integration with protein ingredient supply. These three entities represent distinct strategic positions: cooperative supply security, sensory formulation capability, and hybrid technology-protein portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kerry Group |
| FrieslandCampina Ingredients |
| AMCO Proteins |
| Lactalis Ingredients |
| Fonterra Co-operative Group |
| Cargill |
| Milk Specialties Global |
| Arla Foods Ingredients |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Dutch and New Zealand dairy cooperatives determines both the premium-to-economy price spread across hydrolysate grades and the geographic configuration of enzymatic processing capacity. Buyers face asymmetric leverage where captive milk supply bases compress spot market liquidity while contract indexation clauses pass through seasonal protein concentrate volatility.
Pricing Analysis
Cost-plus contracts with dairy protein indexation dominate procurement between hydrolysate processors and infant formula manufacturers. Pricing stratifies across premium, standard, and economy tiers based on degree-of-hydrolysis certification and ISO 22000 batch-traceability documentation. Cost compression in sports nutrition grades is intensifying because whey hydrolysate substitutes compete on taste neutrality and unit economics. Dietary supplement manufacturers exhibit the highest price sensitivity, while German healthcare providers accept premiums for allergen-controlled medical food specifications.
Supply Chain Analysis
Upstream casein feedstock draws from Netherlands, New Zealand, and French dairy processing corridors with limited spot market depth. Raw material dependencies center on micellar casein isolate, food-grade enzyme preparations, and chromatographic separation media. Single-source vulnerability concentrates in cooperative-owned milk supply bases that restrict independent processor access during seasonal production swings. Distribution runs through long-term direct contracts for clinical and infant nutrition volumes, with spot procurement serving sports nutrition experimentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Casein hydrolysate sits at an early-cycle expansion story where sports nutrition adoption and peptide bioactivity research create new premium tiers faster than commoditization pressures erode existing ones.
For Market Incumbents: Insulate premium positioning by deepening backward integration into captive dairy supply bases and accelerating peptide characterization laboratory investments. Whey hydrolysate substitution in price-sensitive sports nutrition segments threatens volume retention, making ISO 22000 certification maintenance and EFSA health claim dossier preparation the priority defensive levers.
For New Entrants and Emerging Players: Build out asset-light contract manufacturing partnerships targeting Australian and United States sports nutrition brands seeking rapid formulation iteration. Direct procurement relationships displace traditional distributor intermediaries in these geographies, creating accessible entry points for enzymatic technology specialists with custom peptide profile capabilities.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-sized ingredient suppliers with regulatory dossier expertise and established healthcare procurement relationships. Long-term viability rests on peptide bioactivity discovery pipelines and evolving EFSA novel food evaluation protocols. Watch EFSA immunomodulatory health claim approvals as the inflection signal indicating which hydrolysate fractions will command sustained premium pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Characterization Laboratory Investment | EFSA novel food submissions require third-party bioactivity documentation for medical food authorization. |
| Backward Integration into Dairy Supply | FrieslandCampina Ingredients leverages captive milk bases to secure raw material consistency across European production. |
| Direct Procurement Relationship Development | Australian endurance supplement brands contract directly with enzymatic processors for custom peptide profile co-development. |
| Flavor-Mask Technology Integration | Kerry Group anchors market position through sensory formulation capabilities that improve hydrolysate palatability. |
| EFSA Health Claim Dossier Preparation | Swiss and Dutch infant formula manufacturers invest in regulatory affairs capabilities to navigate peptide safety documentation requirements. |
Study Parameters
Desk research of dairy industry trade publications, EFSA novel food submission databases, and FDA GRAS notification records preceded structured interviews with enzymatic processing plant managers, infant formula procurement leads, sports nutrition brand formulators, and clinical nutrition regulatory affairs directors. Primary fieldwork combined with secondary validation from customs trade data, dairy cooperative annual reports, and hospital procurement database analysis. Bottom-up volume modeling and top-down market sizing triangulated across these input streams.
Forecast assumptions held fixed the current EFSA regulatory framework and prevailing dairy protein price indexation structures while varying sports nutrition penetration rates and peptide bioactivity discovery timelines. Segmentation dimensions modeled include product type, application risk profile, end-user procurement sophistication, and distribution channel fragmentation. CAGRs were derived from trend extrapolation calibrated against historical dairy protein ingredient adoption curves and enzymatic hydrolysis technology maturation patterns.
Sensitivities concentrate around EFSA health claim approval timelines, seasonal milk production volatility in Oceania, and whey hydrolysate substitution elasticity in sports nutrition. Forecasts reflect these documented assumptions and industry-specific risk factors. Cross-checking against dairy protein ingredient trade flow data and hospital enteral nutrition procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Notoginseng Root Extract Market
Ingredients
Pea Flour Market
Ingredients
Europe Malt Extract Market
Ingredients
Food Ingredients Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Bromelain Ingredient Market
Ingredients
Jasmine Extract Market
Ingredients
Soy Peptones Market
Ingredients
Campesterol Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Arachidonic Acid Market
Ingredients
Modified Soya Flour Market
Ingredients
Calendula Oil Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Fruit Concentrate Market