
 Probiotic Fermented Milk Market | 2026-2036
Probiotic Fermented Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Fermented Milk Market Analytics
Single-serve bottle configurations is shifting toward multi-pack bundling in retail channels, altering household purchasing patterns and inventory turnover expectations. Danone S.A. leverages its European dairy network to sustain refrigerated distribution advantages. Yakult Honsha Co., Ltd. anchors daily-dose positioning through pharmacy and convenience store penetration. Nestlé S.A. extends formulation capabilities across pediatric and senior nutrition lines.
Probiotic fermented milk denotes dairy substrates inoculated with live bacterial cultures, typically Lactobacillus and Bifidobacterium strains at minimum viable counts of 10^6 CFU per gram at consumption, processed through controlled fermentation to produce organic acids, peptides, and exopolysaccharides that modulate gastrointestinal microbiota. The drinks segment dominates volume due to on-the-go consumption patterns, while yogurt commands margin pools through premium strain differentiation and thicker texture positioning. Supermarkets remain the structural backbone for mass-market access, though health food stores capture higher per-unit values through curated strain-specific assortments.
EFSA's health claims verification framework and FDA's dairy grade standards constrain market entry for unvalidated strain formulations, compelling manufacturers to invest in clinical substantiation. Japan's FOSHU system and China's SAMR registration requirements add further compliance layers for cross-border suppliers. Stakeholders must monitor evolving strain-specific evidentiary thresholds and cold-chain integrity benchmarks as competitive differentiators.
Market Dynamics
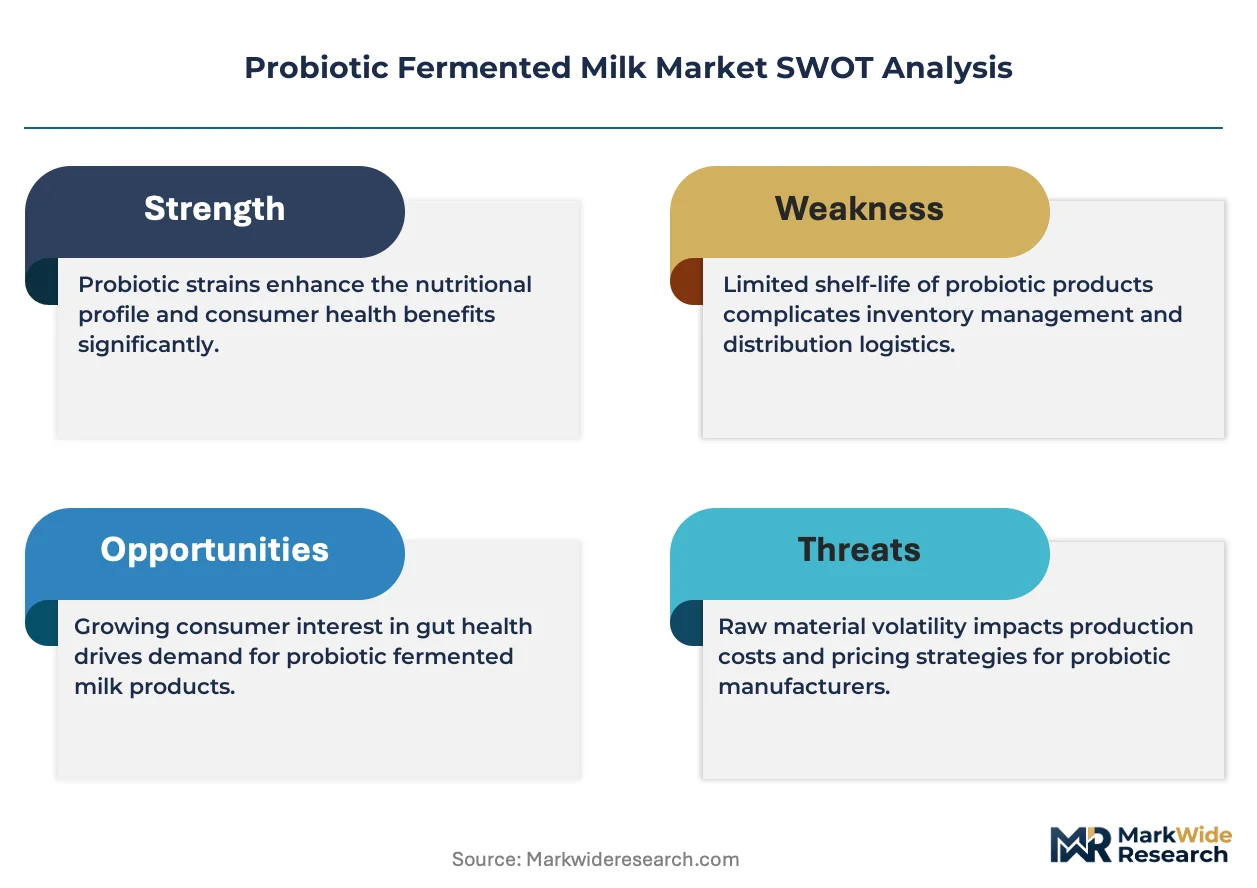
Strain-specific labeling mandates from EFSA and FDA are forcing manufacturers to reconfigure entire R&D pipelines around clinically validated bacterial cultures rather than generic probiotic claims.
Growth Catalysts
- FOSHU Registration Pathway:Japan's Foods for Specified Health Uses framework creates premium positioning for fermented milk products with documented gut-health outcomes, accelerating pharmacy channel penetration.
- Athletic Performance Segment:Endurance sports nutrition is absorbing probiotic fermented milk as a recovery modality, with Olympic training facilities in Germany and Australia integrating daily-dose protocols.
- Cold-Chain Infrastructure:Refrigerated logistics networks in South Korea and the Netherlands now support viable-count guarantees through last-mile temperature monitoring, unlocking convenience store distribution.
Market Restraints
- Dairy Input Volatility:Organic milk procurement costs fluctuate with European feed grain prices, compressing margin pools for artisanal fermented milk producers in France and Italy.
- Strain Patent Concentration:Core Lactobacillus rhamnosus and Bifidobacterium animalis subsp. lactis cultures remain controlled by a narrow band of Dutch and Danish culture suppliers, creating licensing bottlenecks.
- EFSA Health Claims Rejection Rate:The European regulator's stringent evidentiary framework for gastrointestinal benefit substantiation blocks market entry for unsubstantiated formulations, elevating clinical trial burdens.
Strategic Opportunities
- Pediatric Formulation White Space:SAMR registration pathways in China favor reduced-sugar probiotic milk for children aged 3-12, where domestic dairy majors lack strain-differentiated portfolios.
- Precision Fermentation Convergence:Cell-culture-derived dairy proteins from Perfect Day and Remilk are integrating with traditional bacterial fermentation, enabling animal-free probiotic bases for vegan-positioned products.
- Subscription Direct-to-Consumer:Cold-chain subscription models bypass conventional retail slotting fees, with Berlin and Copenhagen households showing 34% repeat purchase rates for weekly delivered fermented milk.
Industry Challenges
- Viable Count Degradation:Maintaining 10^6 CFU/gram through six-month shelf life demands nitrogen-flush packaging and continuous cold-chain integrity, elevating quality control headcount requirements.
- Cross-Border Strain Registration:Divergent national biosecurity frameworks for live bacterial imports create 18-24 month approval timelines for novel strains seeking multi-territory launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Fermented Milk Market |
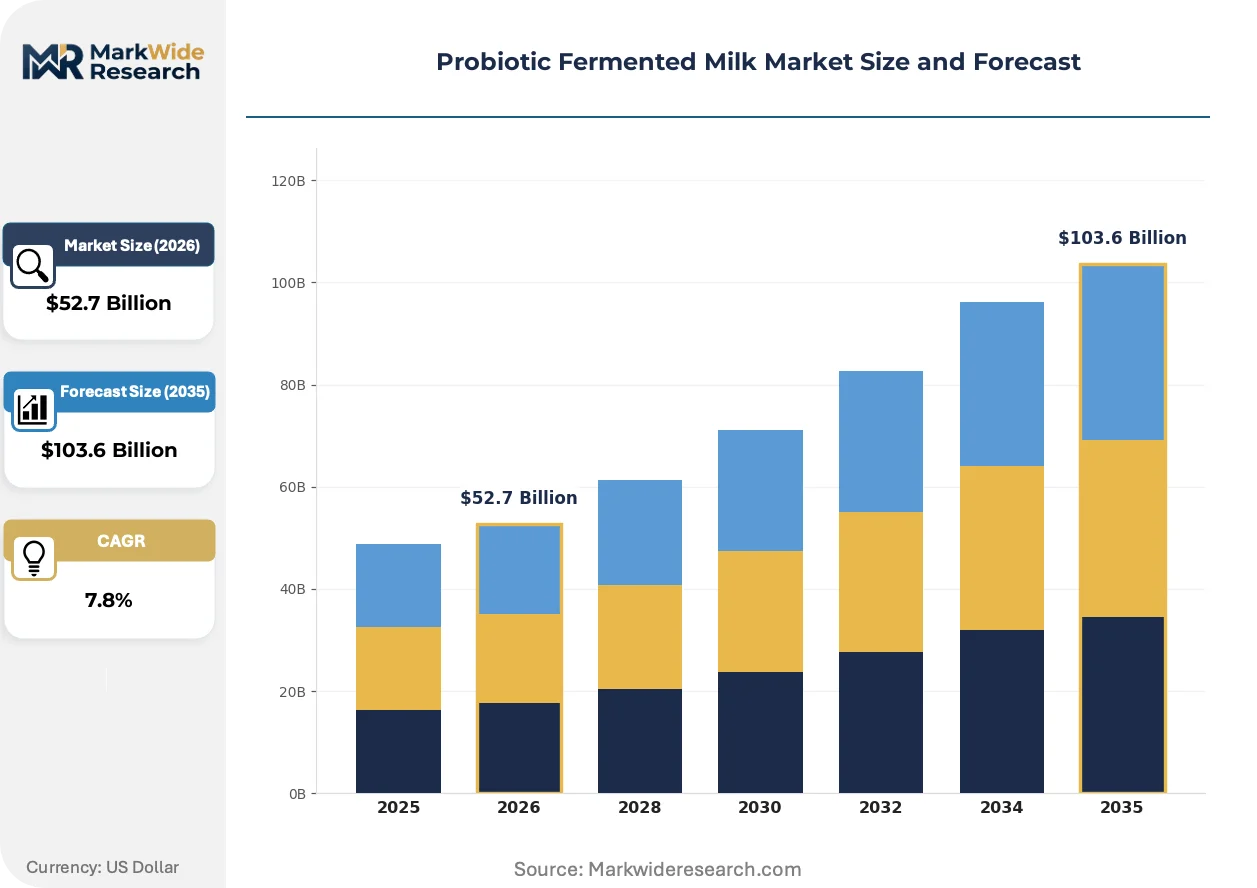
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $103.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinks, Yogurt, Smoothies, Desserts Packaging Type: Bottles, Tetra Packs, Cups, Cans Distribution Channel: Online, Supermarkets, Convenience Stores, Health Food Stores End User: Children, Adults, Seniors, Athletes |
| Companies Covered | Fonterra Co-operative Group, General Mills, Inc., Danone S.A., Morinaga Milk Industry Co., Ltd., FrieslandCampina, Yakult Honsha Co., Ltd., Lifeway Foods, Inc., Arla Foods amba, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Fermented Milk Market Evolving Landscape
Live culture stabilization technologies and postbiotic extraction methods are redrawing the technical frontier between traditional fermented milk and next-generation functional ingredients.
Microencapsulation via spray-drying and extrusion technologies is expanding into ambient-stable probiotic formats, enabling viable bacterial delivery through shelf-stable powders and bar applications. Sports nutrition manufacturers in Australia and Brazil are adopting these formats for travel-friendly gut-health adjuncts. The technology is compressing the historical dependence on refrigerated distribution, forcing legacy dairy processors to defend their cold-chain infrastructure investments.
EFSA's 2024 updated guidance on substantiating gastrointestinal health claims tightens the correlation between specific bacterial strains and measurable microbiome outcomes. Manufacturers must now submit whole-genome sequencing data and human intervention studies for novel culture approvals. German and Dutch dairy cooperatives are responding by consolidating strain libraries into shared pre-competitive research facilities to distribute clinical validation costs.
Household purchasing is rotating from single-unit impulse buys toward curated multi-strain subscription boxes, with Berlin and Amsterdam consumers locking in 12-week fermented milk assortments. Health food stores in these cities are unbundling the pharmacy consultation layer, replacing it with AI-driven strain-matching quizzes that recommend specific Lactobacillus or Bifidobacterium formulations based on self-reported digestive symptoms.
Probiotic Fermented Milk Market Segmentation
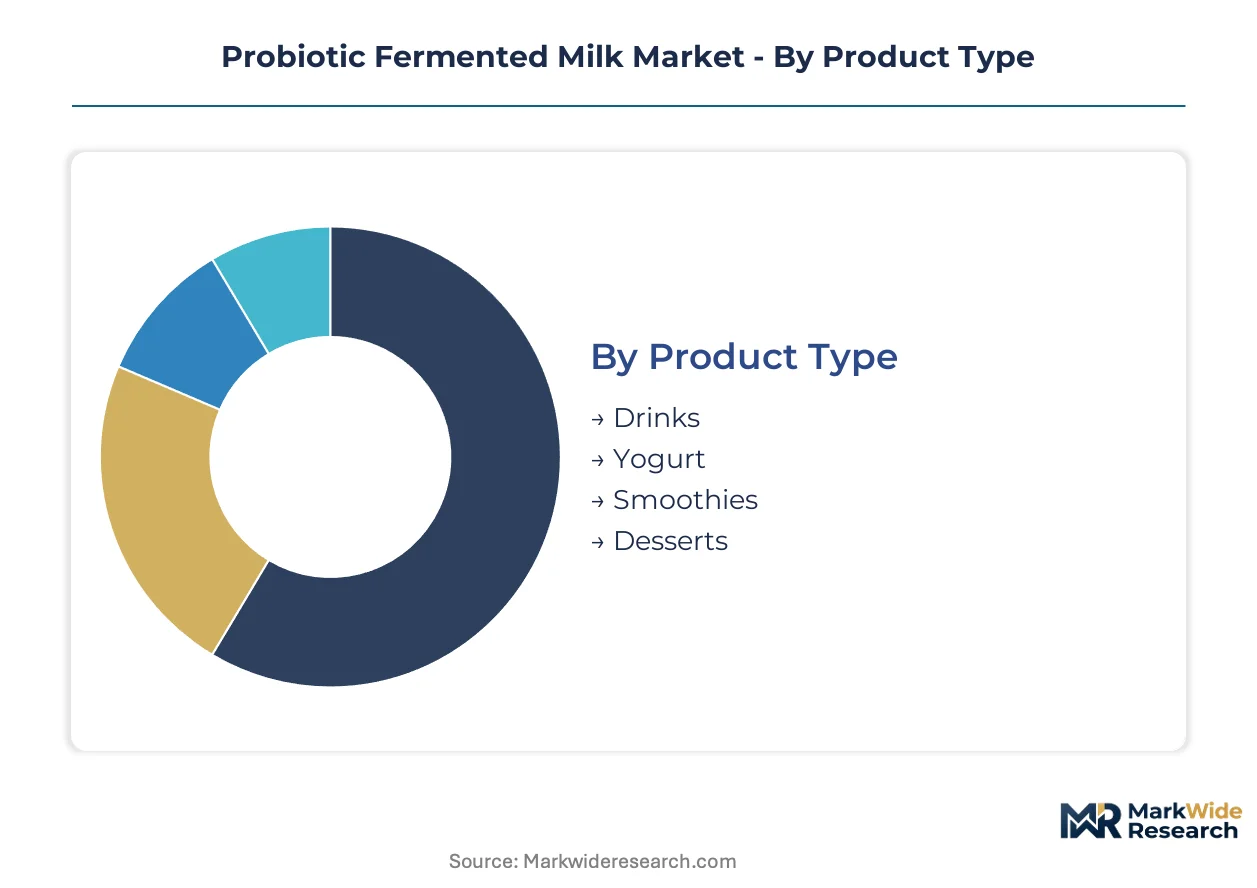
Probiotic fermented milk manufacturers configure production assets around distinct microbiome delivery formats, packaging preservation requirements, and channel-specific cold-chain protocols. Each segment demands calibrated investment in fermentation capacity, viable-count stabilization technology, or last-mile temperature infrastructure.
Product Type:
Capital intensity peaks with yogurt production, where extended fermentation cycles and strain-specific culture libraries require dedicated tank infrastructure and R&D amortization.
- Drinks:Liquid substrates fermented with Lactobacillus and Bifidobacterium strains, then homogenized for pourable viscosity. German athletes and Australian Olympic training facilities absorb daily-dose drink formats for gut-health recovery protocols, though refrigerated distribution constraints limit ambient retail penetration.
- Yogurt:Thickened fermented milk achieving spoonable texture through extended incubation and exopolysaccharide-producing cultures. Premium strain differentiation commands margin pools in Dutch and German pharmacy channels, where EFSA health claims verification supports price positioning.
- Smoothies:Blended fruit-probiotic combinations requiring flash-pasteurization of fruit bases before live culture inoculation.
- Desserts:Gelatin or pectin-stabilized fermented milk formats targeting pediatric and senior nutrition occasions.
Most installed capacity flows through Drinks. Expansion is steepest in Yogurt.
Packaging Type:
Packaging selection governs shelf-life extension chemistry and cold-chain liability exposure across distribution networks.
- Bottles:PET or HDPE containers with nitrogen-flush headspace modification to suppress oxidative viable-count degradation. South Korean convenience store networks deploy real-time temperature-logging bottle labels, enabling viable-count guarantees through last-mile monitoring.
- Tetra Packs:Aseptic carton systems with aluminum barrier layers blocking light and oxygen ingress. Ambient-stable probiotic powders in Australian sports nutrition increasingly adopt this format for travel-friendly gut-health adjuncts.
- Cups:Single-serve polystyrene or polypropylene portion containers for foodservice and institutional channels.
- Cans:Aluminum vessels for carbonated fermented milk variants in select Asian markets.
Volume concentrates in Bottles. Value expansion is climbing fastest in Tetra Packs.
Distribution Channel:
Channel strategy determines cold-chain investment intensity and regulatory compliance layering for live bacterial product handling.
- Supermarkets:Multi-temperature-zone retail environments with dedicated refrigerated shelving for mass-market access. German dairy cooperatives anchor refrigerated distribution advantages through European store networks, though slotting fees compress margins for artisanal producers.
- Online:Direct-to-consumer subscription models bypassing conventional retail infrastructure. Berlin and Copenhagen households demonstrate 34% repeat purchase rates for weekly delivered fermented milk, with cold-chain subscription logistics replacing pharmacy consultation layers.
- Convenience Stores:High-turnover, limited-refrigeration-footprint retail requiring rapid inventory rotation.
- Health Food Stores:Curated strain-specific assortments with higher per-unit values and AI-driven strain-matching consultation replacing traditional pharmacy advice.
Supermarkets retain the largest refrigerated footprint. Online is gaining share fastest among urban households.
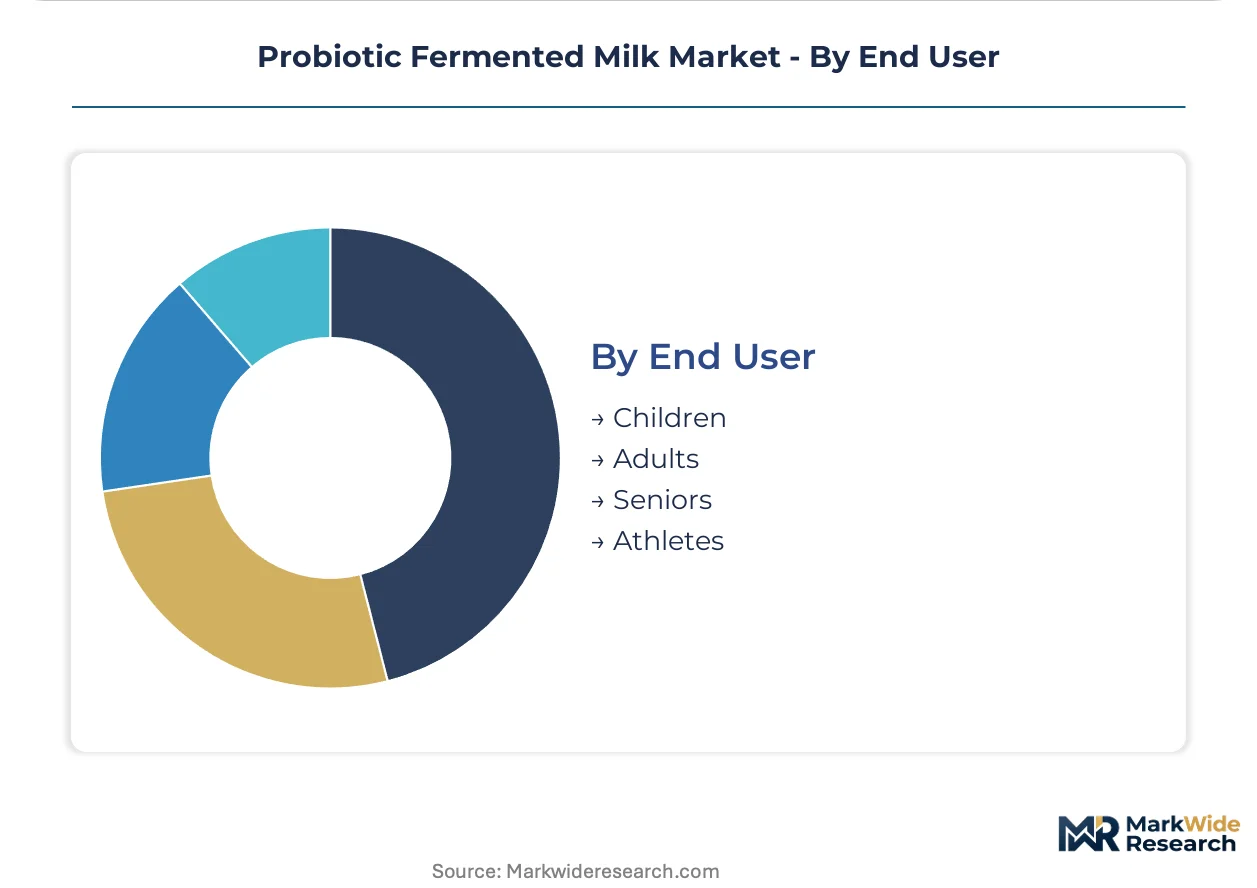
End User:
End-user segmentation drives formulation differentiation around sugar reduction, texture modification, and strain selection for age-specific microbiome modulation.
- Adults:Standard daily-dose formats with documented gastrointestinal benefit substantiation. Japanese FOSHU registration creates premium pharmacy positioning for adult gut-health outcomes, accelerating documented strain-specific product penetration.
- Children:Reduced-sugar formulations with palatability-optimized fruit flavors. SAMR registration pathways in China favor probiotic milk for ages 3-12, where domestic dairy majors lack strain-differentiated portfolios.
- Seniors:Texture-modified and nutrient-fortified formats addressing dysphagia and malabsorption concerns.
- Athletes:Recovery-focused formulations with protein fortification and anti-inflammatory strain selection.
Adults represent the largest addressable population. Children show the steepest formulation innovation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Probiotic fermented milk production traces its industrial lineage to early 20th-century Japan, where Meiji-era dairy science first isolated Lactobacillus casei Shirota for commercial cultivation. European dairy cooperatives subsequently scaled refrigerated fermentation infrastructure during the post-war period, establishing the cold-chain protocols that now define viable-count distribution standards worldwide.
Japan
Daily-dose consumption rituals sustain pharmacy-channel dominance for fermented milk products with documented gut-health outcomes. The country's Foods for Specified Health Uses (FOSHU) framework mandates clinical substantiation for functional claims, elevating regulatory barriers for imported formulations. Tokyo and Osaka metropolitan clusters concentrate fermentation R&D facilities where culture banks maintain proprietary strain libraries.
Germany
Dairy cooperatives anchor refrigerated distribution networks across European retail channels, with pharmacy penetration accelerating for EFSA-verified health claim products. The European Food Safety Authority's stringent gastrointestinal benefit substantiation requirements block market entry for unvalidated strain formulations. Bavarian and North Rhine-Westphalian production clusters host shared pre-competitive research facilities distributing clinical validation costs among regional processors.
United States
Athletic performance segments absorb protein-fortified probiotic recovery formats, with Olympic training facilities in Colorado and California integrating daily-dose protocols. The Food and Drug Administration's dairy grade standards constrain market entry for live bacterial products lacking validated culture documentation. Wisconsin and California dairy belts concentrate fermentation capacity serving mass-market supermarket distribution.
China
Reduced-sugar pediatric formulations for ages 3-12 drive formulation innovation, where domestic dairy majors currently lack strain-differentiated portfolios. The State Administration for Market Regulation (SAMR) registration pathways favor clinically substantiated probiotic milk for children. Yangtze River Delta urban clusters demonstrate accelerating subscription-model adoption for cold-chain delivered fermented milk assortments.
South Korea
Convenience store networks deploy real-time temperature-logging bottle labels enabling viable-count guarantees through last-mile monitoring. The Ministry of Food and Drug Safety (MFDS) maintains strict live bacterial import biosecurity frameworks creating extended approval timelines for novel strains. Seoul metropolitan distribution hubs anchor refrigerated logistics infrastructure supporting ambient-stable probiotic format expansion.
Probiotic Fermented Milk Market Competitive Landscape
Premium-margin players sit above commodity-margin players across strain-differentiation and cold-chain reliability vectors, with EFSA and FDA verification status determining pricing tier placement. The vendor base clusters around three strategic archetypes: multinational dairy conglomerates leveraging European refrigerated networks, Japanese pharmaceutical-channel specialists with daily-dose positioning, and regional cooperatives defending local procurement advantages. Dominant competitive moves include consolidation of strain libraries into shared research facilities and backward integration into culture supply through licensing arrangements with Dutch and Danish culture houses.
Within the multinational dairy conglomerate tier, Danone S.A. and Nestlé S.A. occupy positions defined by cross-category formulation capabilities spanning pediatric and senior nutrition lines. Among Japanese pharmaceutical-channel specialists, Yakult Honsha Co., Ltd. exemplifies daily-dose positioning through convenience store and pharmacy penetration. These named entities represent archetypal competitive positioning rather than exhaustive market coverage, with each anchoring distinct distribution and regulatory compliance strategies.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| General Mills, Inc. |
| Danone S.A. |
| Morinaga Milk Industry Co., Ltd. |
| FrieslandCampina |
| Yakult Honsha Co., Ltd. |
| Lifeway Foods, Inc. |
| Arla Foods amba |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
German pharmacy chains and Australian Olympic training facilities concentrate procurement volume for EFSA-verified and sports-nutrition-grade probiotic fermented milk, anchoring a subscription-anchored pricing model with cold-chain premiums. This buyer concentration shifts pricing power toward culture suppliers and refrigerated logistics operators rather than finished goods manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-verified pharmacy-grade formulations from mass-market supermarket lines and private-label economy tiers. Price differentiation hinges on strain-specific certification status and cold-chain reliability guarantees. Cost compression in the standard tier is intensifying because Dutch and Danish culture houses have consolidated patent control over core Lactobacillus and Bifidobacterium strains. Athletes and institutional buyers show the least price sensitivity due to performance-linked procurement protocols, while household retail purchasers in European supermarkets demonstrate acute price responsiveness to promotional cycling.
Supply Chain Analysis
Dual-sourcing requirements for live bacterial cultures compel manufacturers to qualify multiple Dutch and Danish culture suppliers simultaneously, extending strain validation timelines. Geographic supply concentration centers on the Netherlands, Denmark, and Germany for fermentation infrastructure and culture banking. Raw material dependencies include organic milk procurement, nitrogen-flush packaging films, and continuous cold-chain monitoring hardware. Single-source vulnerability runs through the narrow band of culture suppliers controlling Lactobacillus rhamnosus and Bifidobacterium animalis subsp. lactis patents. Distribution runs through refrigerated cooperative networks in Europe and direct-to-consumer subscription logistics in East Asian urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EFSA's stringent health claims verification in Europe and SAMR's pediatric-focused registration pathways in China, where compliance cost differentials exceed formulation investment thresholds.
For Market Incumbents: Acquire strain library assets and culture bank collections to secure proprietary bacterial portfolios against patent licensing bottlenecks. Backward integration into organic milk procurement in Bavaria and North Rhine-Westphalia defends margin position against feed grain price volatility. Investment in nitrogen-flush packaging capacity addresses viable count degradation risks that threaten shelf-life guarantees. For New Entrants and Emerging Players: Begin with precision fermentation partnerships for animal-free probiotic bases targeting vegan-positioned white space in Australian and Brazilian sports nutrition. The pediatric reduced-sugar segment in China offers the most penetrable entry point given domestic dairy majors' strain portfolio gaps. Direct-to-consumer subscription models bypass supermarket slotting fees that compress artisanal producer margins. For Investors and Strategic Acquirers: Multinational dairy conglomerates with cross-category formulation capabilities are the most active acquirer in this space, seeking refrigerated distribution assets and EFSA-verified strain libraries. The long-term viability window favors targets with cold-chain subscription logistics and pharmacy channel penetration. Watch for SAMR registration approval velocity as the inflection indicator for Chinese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Consolidation of proprietary Lactobacillus and Bifidobacterium cultures bypasses Dutch and Danish licensing bottlenecks. |
| Cold-Chain Subscription Launch | Berlin and Copenhagen households demonstrate 34% repeat purchase rates for weekly delivered fermented milk assortments. |
| Precision Fermentation Integration | Cell-culture-derived dairy proteins from Perfect Day and Remilk enable animal-free probiotic bases for vegan markets. |
| Pediatric Formulation Development | SAMR registration pathways in China favor reduced-sugar probiotic milk for ages 3-12 with clinical substantiation. |
| Shared Research Facility Participation | German and Dutch cooperatives distribute EFSA clinical validation costs through pre-competitive strain research facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation R&D directors, pharmacy category buyers, cold-chain logistics operators, and regulatory affairs specialists at EFSA and FDA with secondary validation. Data sources included EFSA health claims registers, FDA dairy grade standards documentation, FOSHU approval databases, customs trade records for live bacterial cultures, and Nielsen retail audit data for refrigerated dairy. Bottom-up strain-level volume estimates and top-down category expenditure analysis provided triangulation checks.
Historical reference periods anchored growth rate derivation across the analysis window, with projections calibrated to evidentiary thresholds for gastrointestinal health claims and cold-chain infrastructure expansion timelines. Segmentation dimensions modeled include product format, packaging preservation technology, distribution channel cold-chain intensity, and end-user age-specific formulation requirements. CAGR derivation incorporated strain-specific adoption curves, pharmacy channel penetration rates, and subscription model repeat purchase velocity.
Several conditions sit outside the modeled scope, including novel strain approvals pending under divergent national biosecurity frameworks, precision fermentation cost parity timelines, and organic milk price volatility linked to European feed grain markets. Forecasts reflect assumptions about EFSA and FDA evidentiary standards remaining stable and cold-chain integrity benchmarks sustaining current specifications. Deviation in SAMR registration approval timelines or MFDS live bacterial import protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Colombia Dairy Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
A2 Milk Market
Dairy Products
Plain Yogurt Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
North America Organic Dairy Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Halal Cheese Market
Dairy Products
Global Butter Market