
 Butter Concentrate Market | 2026-2036
Butter Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Butter Concentrate Market Outlook
Subscription-based flavor customization services for food manufacturers is rebalancing how butter concentrate suppliers structure long-term contracts. Grassland Dairy Products leverages its captive cream sourcing across Wisconsin to sustain cost advantages in bulk clarified butter production. Amul dominates South Asian supply chains through backward integration into dairy cooperatives, while Organic Valley differentiates via certified organic pasture-to-concentrate traceability programs.
Butter concentrate denotes a high-fat dairy derivative produced through mechanical separation, vacuum evaporation, or centrifugation, typically achieving 82-99% milk fat content depending on the target application. The product serves industrial food producers requiring consistent flavor intensity, extended shelf stability, and precise fat ratios for formulated foods. Organic butter concentrates command premium positioning among clean-label bakeries and confectionery houses, though conventional clarified butter still anchors volume in commercial sauce manufacturing. Food service distribution channels are expanding fastest as restaurant groups centralize procurement through broadline distributors rather than direct dairy sourcing.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern interstate concentrate shipment, while USDA organic certification determines access to premium retail and food manufacturing contracts. The EU's REACH framework and EFSA dairy fat labeling requirements shape export competitiveness for North American suppliers seeking European bakery and confectionery accounts. Stakeholders must monitor evolving trans-fat disclosure mandates and carbon footprint auditing rules that are beginning to appear in dairy procurement specifications across major import markets.
Market Dynamics
Food manufacturers are consolidating procurement through subscription-based flavor customization platforms, rebalancing how butter concentrate suppliers structure long-term contracts and forcing adaptation in pricing frameworks.
Growth Catalysts
- Clean-label bakery certification:Organic Valley's pasture-to-concentrate traceability programs demonstrate how certified organic positioning unlocks premium contract values from artisanal confectionery houses.
- REACH framework compliance:North American suppliers achieving EFSA dairy fat labeling alignment gain competitive access to European bakery and confectionery accounts.
- Clarified butter technology:Vacuum evaporation and centrifugation advances enable 82-99% milk fat precision for industrial sauce formulations requiring consistent flavor intensity.
Market Restraints
- Cream input volatility:Captive cream sourcing advantages concentrate among Wisconsin-based producers, squeezing margin flexibility for non-integrated suppliers.
- South Asian supply dominance:Amul's backward integration into dairy cooperatives creates structural barriers for new entrants seeking comparable cost positions.
- Trans-fat disclosure mandates:Evolving carbon footprint auditing rules in major import markets complicate export qualification timelines.
Strategic Opportunities
- Food service channel expansion:Restaurant groups centralizing procurement through broadline distributors create new volume pathways bypassing direct dairy sourcing.
- USDA organic certification premium:Grade A Pasteurized Milk Ordinance compliance combined with organic credentialing opens retail and food manufacturing contract tiers.
- Confectionery fat ratio precision:High-fat butter concentrate specifications for industrial chocolate and pastry applications remain underpenetrated by regional suppliers.
Industry Challenges
- Interstate shipment compliance:FDA Grade A Pasteurized Milk Ordinance enforcement requires continuous cold-chain documentation across state lines.
- Legacy direct-sourcing relationships:Restaurant groups and bakery chains resist migrating from established dairy supplier contracts to distributor-mediated procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butter Concentrate Market |
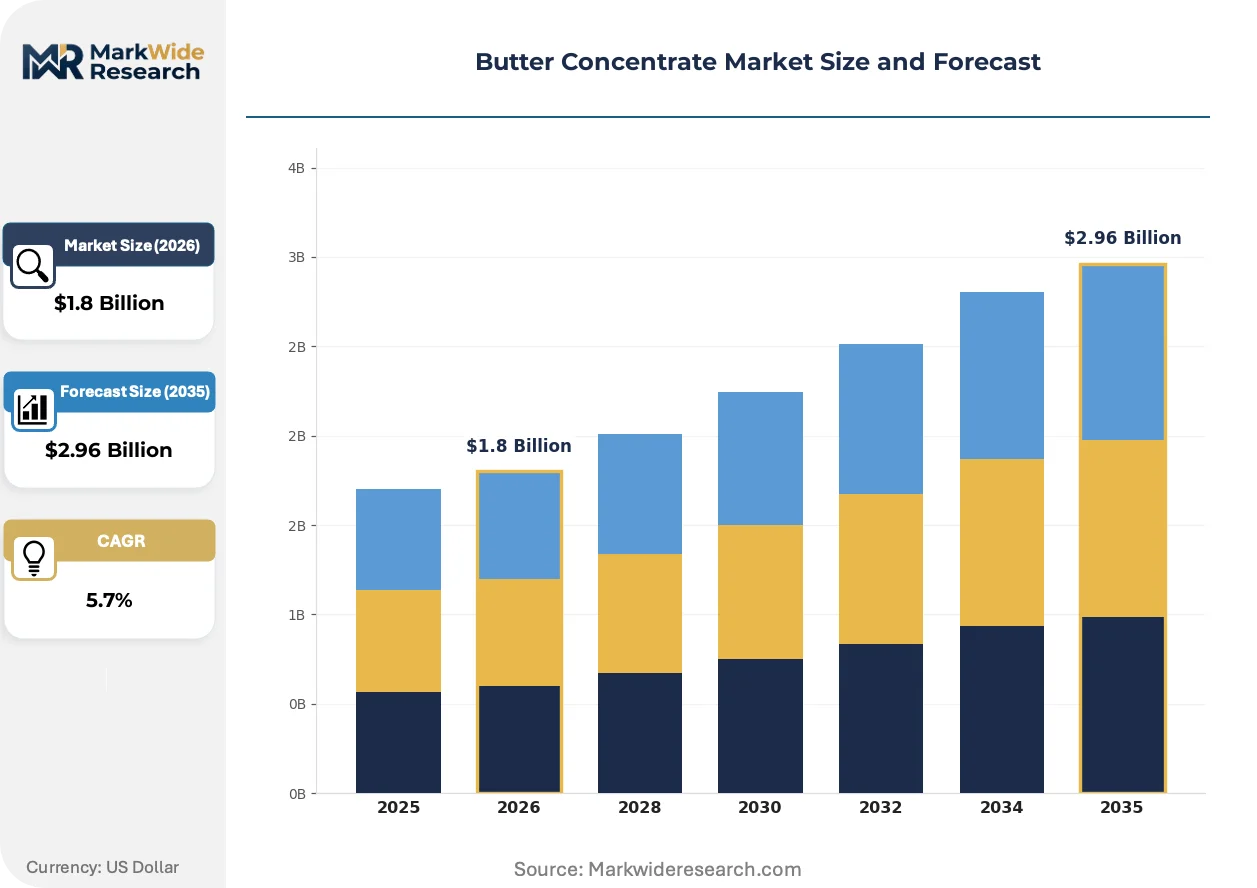
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
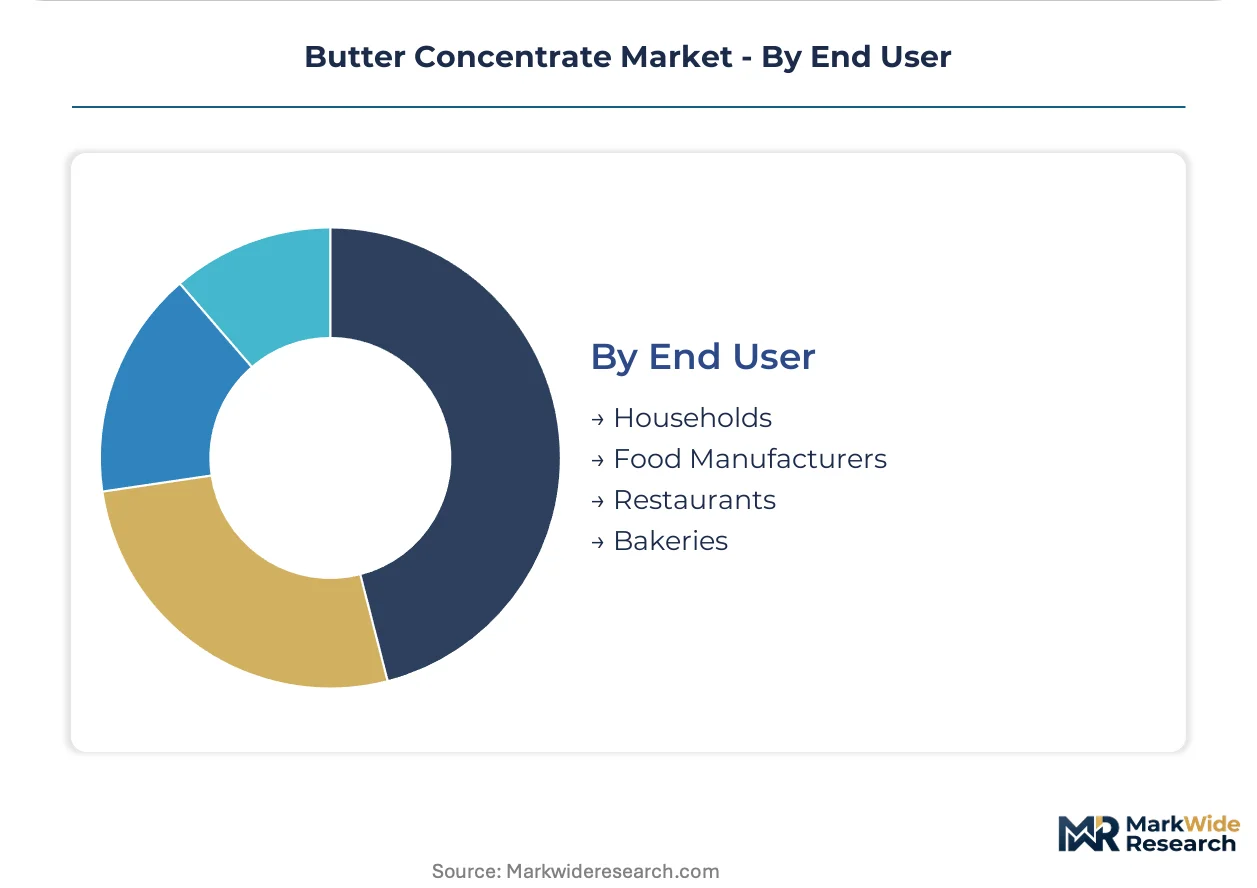
| Segmentation | Product Type: Conventional Butter, Organic Butter, Clarified Butter, Cultured Butter Application: Baking, Sauces, Spreads, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | Roil Foods Ltd., Grassland Dairy Products, Verka USA, Organic Valley, Amul, Nordic Creamery, Beneficial Blends LLC, C.P. Ingredients, Capella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butter Concentrate Market Strategic Shifts
Mechanical separation and vacuum evaporation technologies are compressing production timelines while regulatory pressure on fat disclosure intensifies across import markets.
Membrane filtration systems are rewriting how processors achieve precise milk fat concentrations without thermal degradation. Artisanal bakery chains in Germany are adopting these systems fastest, compressing the gap between premium clarified butter and economy-grade concentrates.
EFSA dairy fat labeling requirements under the EU's REACH framework are forcing reformulation disclosures across exported sauce and confectionery products. North American suppliers face documentation burdens that favor established players with dedicated compliance infrastructure. Bakery and confectionery accounts in France and Germany now require carbon footprint audits alongside traditional quality certifications.
Buyer concentration through broadline distributors is fragmenting traditional direct-sourcing relationships. Restaurant groups in the United States are consolidating procurement decisions at the corporate level, replacing regional dairy contracts with national distribution agreements. Food service channels show the fastest expansion as centralized purchasing displaces legacy supplier networks.
Butter Concentrate Market Segmentation

Segmentation in butter concentrate markets reflects divergent technical specifications and procurement logics across industrial and consumer channels. Product formulation drives pricing architecture, while distribution channel selection determines margin capture and certification requirements.
Product Type:
Mechanical separation and thermal processing specifications create distinct performance envelopes for each butter concentrate variant.
- Clarified Butter:Vacuum evaporation removes water and milk solids to achieve 82-99% milk fat content with extended shelf stability. Industrial sauce manufacturers in Germany concentrate procurement of this grade for premium formulation consistency.
- Organic Butter:Certified pasture-to-concentrate traceability programs command premium positioning among clean-label bakeries and confectionery houses. USDA organic certification combined with Grade A Pasteurized Milk Ordinance compliance opens contract tiers that conventional grades cannot access.
- Conventional Butter:Standard clarified concentrates anchor volume in commercial sauce manufacturing where cost efficiency outweighs certification premiums.
- Cultured Butter:Fermentation-derived flavor intensity serves artisanal bakery chains seeking differentiated taste profiles in laminated dough applications.
Mature deployment sits with Conventional Butter. Newer deployment is concentrated in Organic Butter.
Application:
End-use functionality requirements segment demand by fat ratio precision and thermal stability thresholds.
- Sauces:High-fat clarified concentrates enable consistent emulsion stability and flavor intensity in industrial manufacturing. Food manufacturers expanding premium sauce formulations drive specification tightening toward 99% milk fat targets.
- Baking:Laminated dough applications require precise plasticity ranges that cultured and organic concentrates deliver. Artisanal bakery chains in Germany scale purchases of high-fat concentrates for industrial-scale croissant and puff pastry production.
- Confectionery:Chocolate and pastry fat ratio specifications remain underpenetrated by regional suppliers seeking technical compliance with EFSA dairy fat labeling.
- Spreads:Consumer-facing retail formats emphasize spreadability and flavor modulation through controlled crystallization profiles.
Volume concentration favors Baking. Steepest expansion trajectory belongs to Sauces.
Distribution Channel:
Channel selection determines cold-chain documentation burdens and customer relationship economics.
- Food Service:Broadline distributor consolidation displaces direct dairy sourcing as restaurant groups centralize procurement decisions at corporate level. This channel shows the fastest volume expansion across the analysis window.
- Supermarkets:Mass retail placement requires Grade A Pasteurized Milk Ordinance compliance plus organic credentialing for premium shelf positioning.
- Specialty Stores:Artisanal and ethnic retail formats capture cultured butter concentrates for consumer segments prioritizing provenance and traditional processing methods.
- Online Retail:Direct-to-consumer logistics challenge shelf-stable packaging requirements for high-fat concentrates in ambient shipping conditions.
Established infrastructure sits with Supermarkets. Emerging deployment concentrates in Food Service.
End User:
Procurement scale and specification authority separate industrial buyers from fragmented consumer demand.
- Food Manufacturers:Centralized purchasing power and formulation expertise enable long-term subscription-based flavor customization contracts. These buyers drive precision specifications for fat content and thermal stability.
- Bakeries:Artisanal chains and industrial confectionery producers in Germany scale high-fat concentrate purchases, bridging craft and manufacturing procurement models.
- Restaurants:Corporate-level procurement consolidation through broadline distributors fragments legacy regional dairy contracts.
- Households:Fragmented demand through retail channels exhibits price sensitivity and brand loyalty variation by geography.
Contract maturity sits with Food Manufacturers. Newer deployment is concentrated in Bakeries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Wisconsin and Gujarat, while consumption gravitates toward German industrial bakeries and US food service networks. Trade flows from these hubs supply premium clarified concentrates to European confectionery houses and Asian sauce manufacturers. Regional regulatory divergence around fat disclosure and organic certification shapes competitive access.
United States
Food service procurement consolidation drives volume through broadline distributors replacing direct dairy contracts. FDA Grade A Pasteurized Milk Ordinance enforcement mandates continuous cold-chain documentation across state lines. Wisconsin-based producers leverage captive cream sourcing advantages to supply industrial sauce manufacturers in Chicago and Minneapolis-St. Paul.
Germany
Artisanal bakery chains and industrial confectionery producers scale purchases of high-fat butter concentrates for laminated dough applications. EFSA dairy fat labeling requirements under REACH framework force reformulation disclosures on exported products. Munich and Stuttgart industrial clusters adopt membrane filtration systems fastest, compressing gaps between premium clarified butter and economy-grade concentrates.
India
Amul's backward integration into dairy cooperatives creates structural cost advantages in South Asian supply chains. FSSAI standards govern interstate concentrate movement while state-level dairy boards coordinate cooperative procurement. Gujarat and Maharashtra dairy clusters supply clarified butter concentrates to domestic bakery chains and Middle East export markets.
France
ANSM and DGCCRF enforcement of EU dairy fat labeling requirements complicates North American supplier qualification timelines. Paris and Lyon confectionery houses demand carbon footprint audits alongside traditional quality certifications. Specialty retailers in Provence-Alpes-Côte d'Azur capture cultured butter concentrates for provenance-focused consumer segments.
Canada
Health Canada dairy standards align with FDA Grade A requirements, enabling cross-border supply integration with US producers. CFIA inspection protocols govern import qualification for European concentrates seeking access to Toronto and Vancouver food manufacturing accounts. Prairie dairy cooperatives in Alberta and Manitoba supply clarified concentrates to US border-state sauce manufacturers.
Butter Concentrate Market Competitive Environment
Top-tier vendors anchor premium organic and clarified butter segments, while mid-tier regional dairies compete on cost efficiency and geographic proximity. Wisconsin-based processors and Indian dairy cooperatives occupy distinct structural positions based on captive cream access. Three archetypes dominate: vertically integrated cooperatives with backward supply control, specialty organic certifiers with pasture-to-concentrate traceability, and scale-driven clarified butter specialists serving industrial accounts. Competitive moves center on M&A consolidation of regional dairy assets and strategic partnerships with broadline food service distributors.
Among US-based processors, Grassland Dairy Products and Organic Valley exemplify contrasting strategic positions. Grassland Dairy Products represents scale-driven clarified butter production anchored in Wisconsin cream sourcing. Organic Valley occupies the certified organic tier with pasture-to-concentrate traceability programs. Amul, the Indian dairy cooperative, anchors South Asian supply chains through cooperative-based backward integration. These three entities illustrate how geographic concentration and certification positioning separate competitive tiers in concentrate markets.
| Leading Market Players |
|---|
| Roil Foods Ltd. |
| Grassland Dairy Products |
| Verka USA |
| Organic Valley |
| Amul |
| Nordic Creamery |
| Beneficial Blends LLC |
| C.P. Ingredients |
| Capella |
| Others |
Value Chain & Pricing Dynamics
Captive cream sourcing across Wisconsin dairy cooperatives anchors both supply security and pricing power for clarified butter concentrate producers serving industrial sauce manufacturers. This backward integration into upstream milk fat inputs insulates integrated processors from spot cream volatility while squeezing margin flexibility for non-integrated competitors dependent on open-market procurement.
Pricing Analysis
Margin tightening in conventional clarified concentrates reflects captive supply advantages concentrating among Wisconsin-based producers with in-house cream access. Three-tier pricing structure across organic-certified, Grade A compliant, and economy grades separates contract tiers by certification burden and thermal stability specifications. Food manufacturers with subscription-based procurement platforms exhibit lowest price sensitivity due to formulation lock-in effects, while fragmented bakery chains dependent on spot purchasing face highest cost-down pressure.
Supply Chain Analysis
Single-source vulnerability sits with Gujarat dairy cooperatives supplying South Asian clarified butter networks and Middle East export corridors. Raw material flows draw from Wisconsin cream streams, Indian cooperative milk pools, and Canadian prairie dairy clusters. Tariff exposure on cross-border concentrate movements between US and Canadian processing hubs complicates just-in-time delivery commitments to Chicago and Minneapolis-St. Paul sauce manufacturers. Distribution runs through broadline food service networks displacing legacy direct-sourcing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream cream control and downstream distributor partnerships determine competitive survival. Players are pursuing captive supply of high-fat milk inputs as the decisive lever.
For Market Incumbents: Hedge against membrane filtration technology diffusion by locking long-term contracts with artisanal bakery chains before regional dairies achieve comparable fat precision. Defend margin position through accelerated USDA organic certification timelines that open retail contract tiers unavailable to conventional-grade competitors.
For New Entrants and Emerging Players: Begin with carbon footprint audit capabilities targeting French and German confectionery houses now requiring environmental credentials alongside traditional quality certifications. Penetrate the under-served high-fat concentrate segment for industrial chocolate applications where EFSA dairy fat labeling compliance remains scarce among North American suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty organic certifiers with pasture-to-concentrate traceability infrastructure. Long-term viability favors processors with demonstrated REACH framework alignment and dedicated compliance documentation systems. Watch for FDA enforcement intensity on interstate cold-chain documentation as the signal for regulatory-capability premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cream Sourcing | Wisconsin dairy cooperatives secure cost advantages against spot-market dependent competitors. |
| USDA Organic Certification Investment | Pasture-to-concentrate traceability unlocks premium contract tiers from clean-label bakeries. |
| Broadline Distributor Partnership | Corporate procurement consolidation at US restaurant groups displaces regional dairy contracts. |
| Membrane Filtration Technology Adoption | German industrial clusters compress production timelines between premium and economy grades. |
| Carbon Footprint Audit Capability | French confectionery houses now require environmental credentials alongside quality certifications. |
Study Parameters
Document review covered FDA Grade A Pasteurized Milk Ordinance filings, EU REACH framework guidance, and FSSAI dairy standards, complemented by interviews with procurement directors at industrial sauce manufacturers, technical leads at Wisconsin dairy processors, regulatory affairs specialists at organic certifiers, and distribution managers at broadline food service networks. Secondary validation drew from USDA dairy production statistics, EFSA scientific opinions on dairy fat labeling, and customs trade data on clarified butter movements. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Segment-level projections across product type, application, distribution channel, and end-user categories were generated through the analytical framework over the projection horizon. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated membrane filtration deployment rates in German industrial clusters and carbon footprint audit penetration in French and German procurement specifications.
Underlying measurement precision varies by segment; food manufacturer contract data carries tighter precision than fragmented household retail estimates. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology diffusion timelines. Deviation in FDA interstate shipment compliance stringency or EFSA dairy fat labeling scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Skimmed Milk Market
Dairy Products
Global Dairy Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Fluid Milk Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Japan Casein Market
Dairy Products
Greek Yogurt Market
Dairy Products
North America Dairy Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Europe Cheese Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Global Specialty Cheese Market