
 Global Reduced Fat Butter Market | 2026-2036
Global Reduced Fat Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reduced Fat Butter Market Foresight
Plant-based fat blends is expanding its footprint in reduced fat butter formulations as dairy processors seek cost-stable alternatives to conventional cream sourcing. Arla Foods leverages its cooperative milk supply network to sustain volume consistency across Nordic and British retail channels. Upfield competes aggressively in the European spreadables segment with emulsion technology optimized for lower fat retention. Fonterra Co-operative Group anchors Oceania supply through backward integration into grass-fed dairy farming operations.
Reduced fat butter denotes a dairy spread with butterfat content typically ranging from 25% to 40%, achieved through churning cream with controlled fat separation or blending with water and milk solids, designed to deliver functional plasticity and flavor at lower caloric density than standard butter. Spreadable Butter leads product type demand due to its direct substitution equivalence in household and foodservice applications; Food Manufacturers represent the fastest-growing end user segment as industrial bakers reformulate for clean-label claims. Margin pools concentrate in Cultured Butter variants where fermentation protocols command price premiums from specialty retail and artisan bakery channels.
FDA standards of identity in the United States govern minimum milkfat thresholds and labeling nomenclature, while EFSA and EU Green Deal sustainability metrics shape reformulation incentives across European production facilities. BIS certification requirements in India affect import access for foreign reduced fat butter brands seeking entry into organized retail. Stakeholders must monitor evolving trans fat restrictions and front-of-pack labeling mandates as these frameworks increasingly determine which formulations qualify for preferred shelf placement and institutional procurement contracts.
Market Dynamics
EU F-Gas Regulation compliance deadlines are forcing dairy processors across Western Europe to accelerate reformulation toward lower saturated fat profiles, compressing product development cycles and reshaping procurement priorities for industrial bakery chains.
Growth Catalysts
- Clean-label industrial baking:Food manufacturers in Germany and France are reformulating pastry and laminated dough applications to meet retailer front-of-pack scoring requirements, pulling volume toward reduced fat butter with simplified ingredient decks.
- EU Green Deal sustainability metrics:EFSA-aligned environmental labeling incentives reward lower carbon intensity in dairy processing, directing investment toward fat separation technologies that reduce energy-intensive cream churning.
- Plant-based fat blending:Water-in-oil emulsion advances allow partial substitution of dairy fat with structured oleogels, giving processors cost-stable alternatives to volatile cream commodity markets.
Market Restraints
- Cream input cost volatility:Grass-fed dairy farming output fluctuations in New Zealand and Ireland transmit directly to butterfat pricing, compressing margins for standard-grade reduced fat butter.
- Technical flavor fidelity limits:Fat reduction below 30% butterfat threshold degrades mouthfeel and aromatic release in high-heat baking applications, constraining substitution in croissant and puff pastry segments.
- Substitution by margarine-spread hybrids:Upfield and Bunge Loders Croklaan formulations achieve similar functional plasticity at lower price points in foodservice channels.
Strategic Opportunities
- Underpenetrated Indian organized retail:BIS certification requirements currently block most foreign reduced fat butter brands; domestic processors with compliant facilities can capture shelf space in Mumbai and Bangalore hypermarket chains.
- Fermentation-derived cultured variants:Lactic acid bacteria protocols create flavor differentiation that commands specialty retail premiums in British and Nordic markets.
- Direct-to-bakery distribution:Bypassing traditional wholesale layers, processors are building captive supply relationships with artisan bakery clusters in Paris and Copenhagen.
Industry Challenges
- Clean-label certification timeline compression:Multiple retailer proprietary schemes (Nutri-Score, traffic light labels, carbon footprint badges) require parallel documentation, stretching technical regulatory affairs teams.
- Emulsion stability at scale:Maintaining water droplet distribution uniformity across temperature fluctuations during industrial batch processing demands capital investment in scraped-surface heat exchangers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reduced Fat Butter Market |
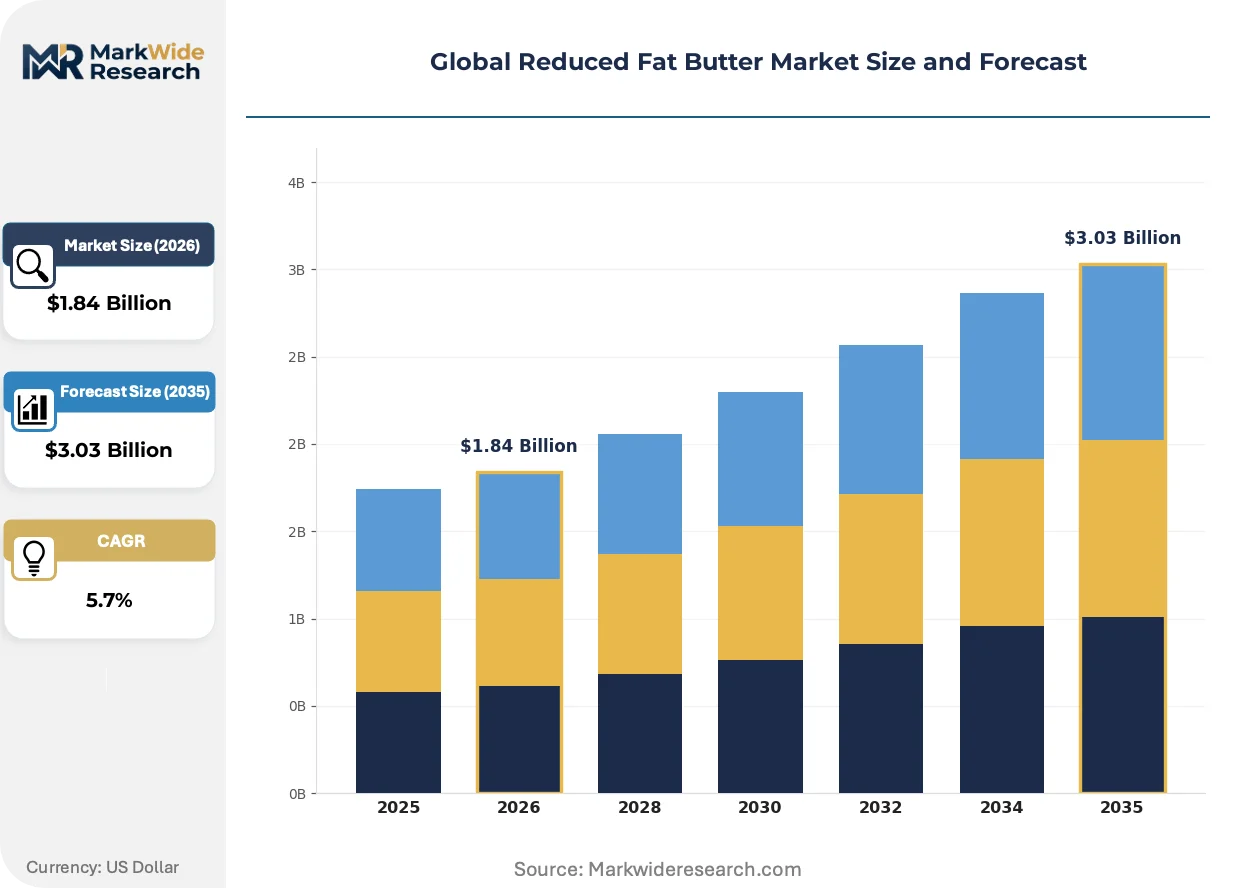
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.03 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable Butter, Clarified Butter, Whipped Butter, Cultured Butter, Unsalted Butter Application: Baking, Cooking, Confectionery, Foodservice, Household Consumption Packaging Type: Foil Wrap, Paper Wrap, Plastic Container, Butter Tub, Bulk Packs End User: Bakeries, Restaurants, Caterers, Food Manufacturers, Retail Consumers |
| Companies Covered | Palsgaard, AMUL (Gujarat Cooperative Milk Marketing Federation Ltd.), Land O'Lakes, Inc., Ornua Co-operative Limited, Saputo Inc., Arla Foods, Fonterra Co-operative Group, Finlandia Cheese, Inc., Upfield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reduced Fat Butter Market Shifts & Advancements
Micro-encapsulation of dairy flavor compounds and advances in oleogel structuring are expanding formulation possibilities, while regulatory pressure on saturated fat disclosure accelerates transparency requirements across retail and foodservice channels.
High-pressure processing of cream prior to churning is expanding into reduced fat butter manufacturing as a non-thermal pathogen reduction method. Industrial bakeries in the Netherlands and Belgium are adopting these formulations to extend shelf life without chemical preservatives. This technology is expanding into clean-label supply chains by eliminating the need for potassium sorbate or calcium disodium EDTA, compressing ingredient list length to meet retailer scorecard thresholds.
REACH chemical safety assessments and EU F-Gas phase-down mandates are converging to restrict hydrofluorocarbon use in dairy processing refrigeration. Butter manufacturers in Denmark and Ireland face retrofit deadlines for cold-chain equipment, redirecting capex toward ammonia-based or transcritical CO2 systems. The regulatory pressure is concentrating investment among cooperative processors with pooled technical resources, widening the compliance capability gap versus smaller independent dairies.
Foodservice distributors are unbundling bulk butter procurement from bundled ingredient supply contracts, allowing bakery chains to negotiate direct processor relationships for reduced fat specifications. This disintermediation is most visible in the United Kingdom, where Costa Coffee and Greggs have established captive supply lines with Arla for spreadable formats. The shift compresses distributor margins while giving end-users greater transparency into fat content variability and origin documentation.
Global Reduced Fat Butter Market Segmentation
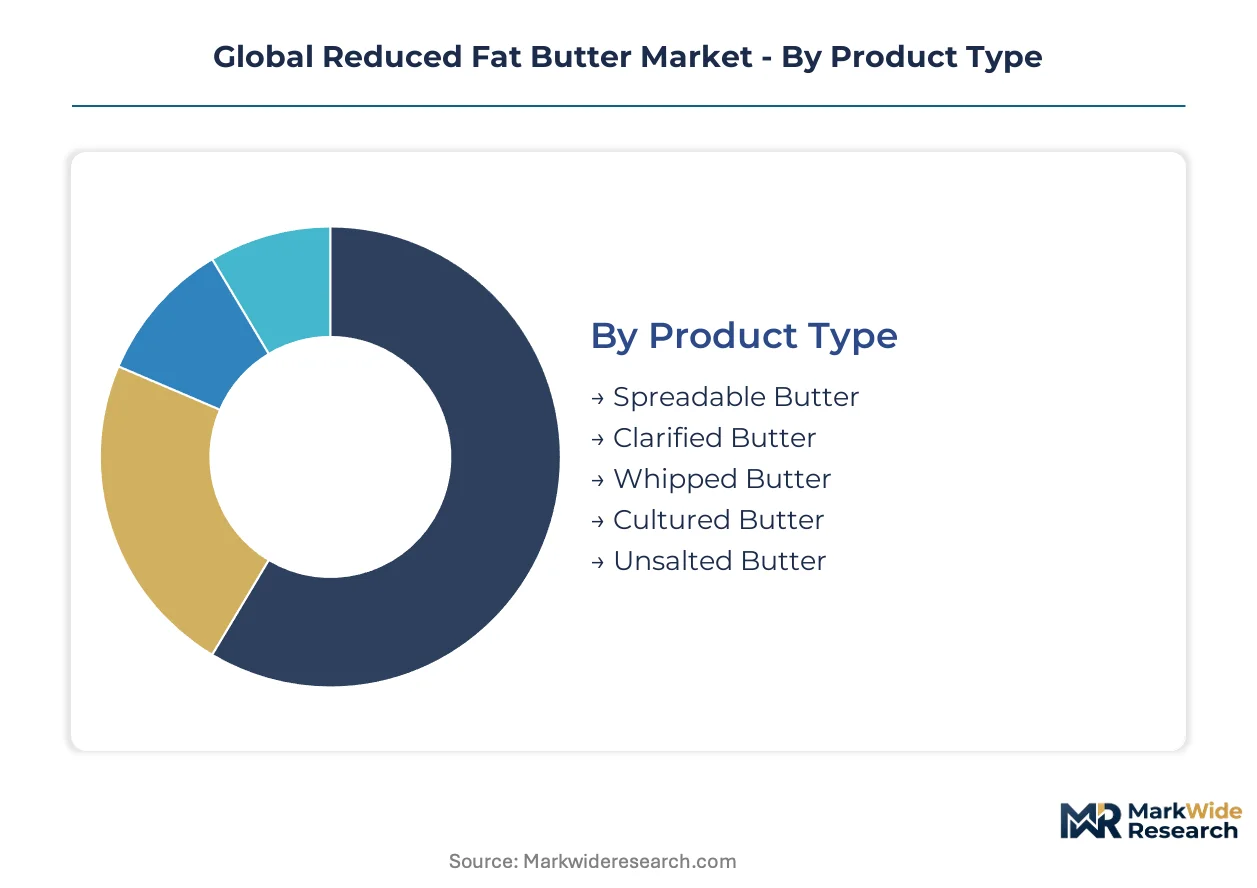
Reduced fat butter formulations vary sharply in functional performance across temperature thresholds, fat content gradients, and shear stability requirements. Processors must align product architecture with specific end-use constraints rather than pursuing universal formulations.
Product Type:
Customization intensity spans from standardized commodity formats to fermentation-protocol specialty grades with pronounced margin stratification.
- Spreadable Butter:Achieves functional plasticity through controlled water-in-oil emulsion structuring at 25-40% butterfat content. Demand concentrates in German and British household retail where refrigerator-to-table spreadability eliminates tempering steps. Reformulation toward lower saturated fat profiles accelerates under EU F-Gas Regulation compliance timelines.
- Cultured Butter:Lactic acid bacteria fermentation develops diacetyl and acetoin flavor compounds that command specialty retail premiums. Paris and Copenhagen artisan bakery clusters drive procurement of small-batch cultured variants for laminated dough applications where aromatic complexity differentiates finished products.
- Clarified Butter:Milk solids removal extends smoke point for high-heat cooking applications in foodservice channels.
- Whipped Butter:Nitrogen or air incorporation reduces density for portion-controlled foodservice dispensing.
- Unsalted Butter:Neutral flavor base supports precision control in industrial baking formulations.
Leading the category by volume: Spreadable Butter. Expanding most quickly: Cultured Butter.
Application:
Volume concentration versus value capture diverges across temperature-stressed industrial processes and ambient-stable retail formats.
- Baking:Laminated dough applications in croissant and puff pastry production demand precise fat plasticity across thermal working ranges. Industrial bakeries in Belgium and the Netherlands specify reduced fat butter with emulsion stability below 30% butterfat to meet clean-label scorecard thresholds.
- Food Manufacturers:Mass-scale reformulation for front-of-pack labeling compliance drives procurement of simplified ingredient decks. German and French pastry manufacturers are accelerating specification shifts toward reduced fat butter as retailers enforce Nutri-Score minimums.
- Cooking:Sauté and pan-fry applications in foodservice favor clarified or high-smoke-point formulations.
- Confectionery:Tempered fat crystallization requirements constrain substitution in chocolate and praline production.
- Household Consumption:Spreadable formats dominate breakfast and sandwich applications in British and Nordic retail channels.
Food Manufacturers claim the steepest expansion trajectory as clean-label industrial baking mandates tighten across EU member states.
Packaging Type:
Barrier performance requirements scale with shelf-life targets and distribution temperature integrity.
- Butter Tub:Injection-molded polypropylene with oxygen scavenging liners supports 90-day refrigerated shelf life for spreadable retail formats. British supermarket private-label programs specify tub formats for portion consistency and resealability.
- Foil Wrap:Aluminum-laminate barrier provides premium positioning for cultured and specialty variants in French and Danish retail.
- Paper Wrap:Grease-resistant cellulose serves artisan bakery direct distribution with shorter turnover cycles.
- Plastic Container:Modified atmosphere options for foodservice bulk dispensing.
- Bulk Packs:25kg polyethylene-lined corrugated for industrial bakery and food manufacturing procurement.
Butter Tub configurations lead retail volume. Bulk Packs are gaining share fastest in direct-to-bakery distribution models.
End User:
Specification authority and price sensitivity inversely correlate across fragmented retail versus concentrated industrial procurement.
- Food Manufacturers:Centralized technical teams dictate fat content tolerances, emulsion stability parameters, and origin documentation for clean-label claims. Industrial bakers in Germany reformulate laminated dough lines to meet retailer front-of-pack scoring requirements.
- Bakeries:Artisan clusters in Paris and Copenhagen negotiate direct processor relationships bypassing traditional wholesale layers.
- Restaurants:Foodservice distributors face disintermediation pressure as chains establish captive supply lines.
- Caterers:Volume volatility favors flexible procurement terms over long-term contracts.
- Retail Consumers:Price elasticity concentrates demand in private-label spreadable formats across British and German supermarket channels.
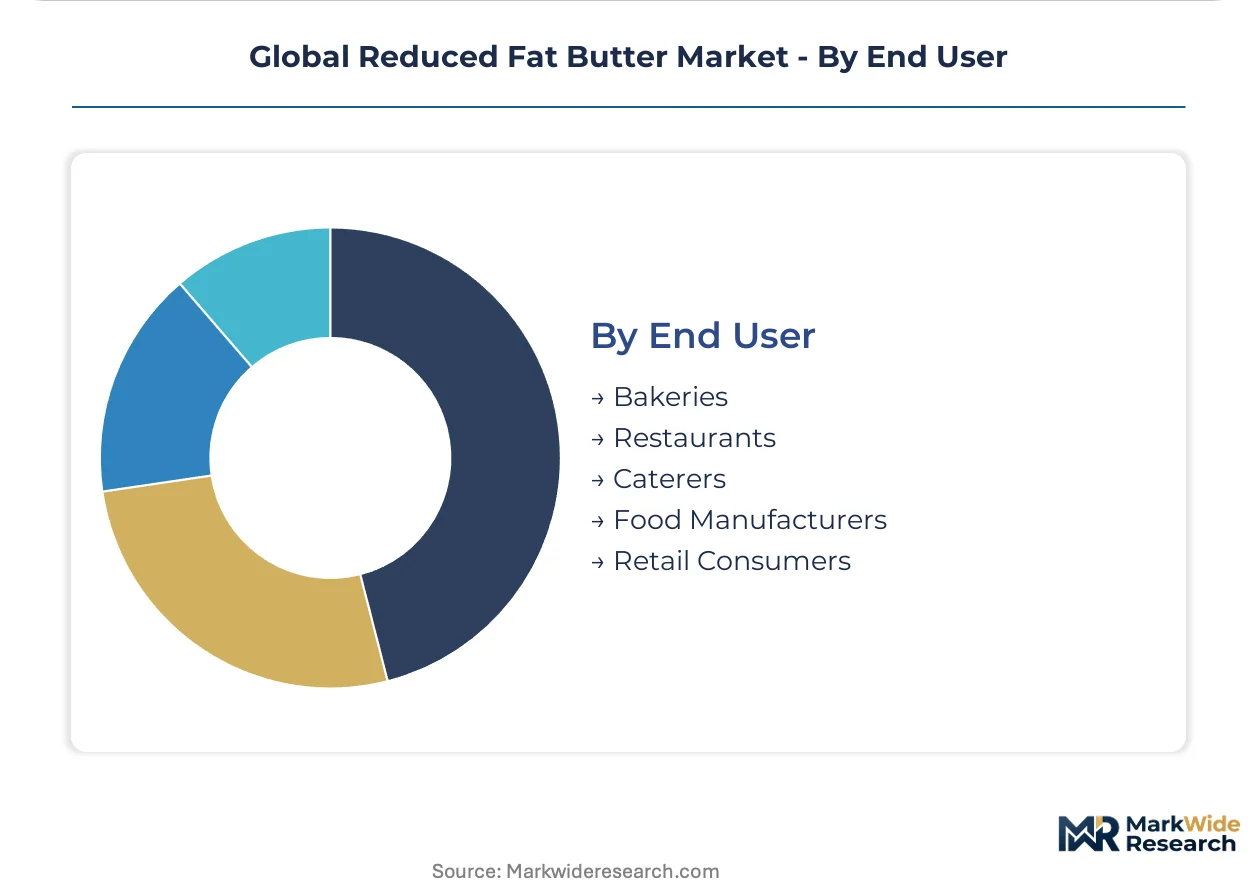
Food Manufacturers dominate procurement volume. Bakeries are climbing the fastest as direct distribution models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra channel dairy processing investment into tax-advantaged corridors. These designated manufacturing clusters concentrate reduced fat butter capacity near port infrastructure and cold-chain logistics hubs.
Germany
Industrial bakery chains in Bavaria and North Rhine-Westphalia accelerate procurement of reformulated spreads. The EU F-Gas Regulation mandates refrigeration equipment retrofits by 2030, compressing product development timelines for lower saturated fat profiles. Frankfurt and Munich host technical centers where emulsion stability testing aligns with retailer Nutri-Score thresholds.
United States
Food manufacturers in Wisconsin and California reformulate for FDA standards of identity compliance. The Inflation Reduction Act channels biofuel and climate credits toward dairy processing energy efficiency. Chicago and Los Angeles distribution hubs disaggregate bulk procurement from bundled ingredient contracts, enabling direct processor negotiations.
India
Organized retail expansion in Mumbai and Bangalore drives demand for BIS-certified reduced fat butter. The FSSAI front-of-pack labeling mandate accelerates clean-label reformulation timelines. Gujarat Cooperative Milk Marketing Federation anchors domestic supply through cooperative procurement networks spanning Anand and surrounding districts.
United Kingdom
Bakery chains including Costa Coffee and Greggs establish captive supply relationships for spreadable formats. The Competition and Markets Authority scrutinizes wholesale distribution consolidation, creating openings for direct-to-bakery models. London and Copenhagen artisan clusters negotiate small-batch cultured butter specifications bypassing traditional layers.
France
Parisian artisan bakeries command specialty premiums for fermentation-protocol cultured variants. EFSA-aligned environmental labeling rewards lower carbon intensity in dairy processing. Brittany and Normandy cooperative processors pool technical resources for ammonia-based refrigeration retrofits under EU Green Deal compliance deadlines.
Global Reduced Fat Butter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Cooperative structures dominate volume supply through backward integration into farming operations, while proprietary emulsion technology holders compete on functional performance. Three archetypes anchor positioning: dairy cooperatives with captive milk supply, multinational spreadables specialists with water-in-oil expertise, and regional private-label processors with retail channel access. Consolidation pressure intensifies through cooperative mergers and technology licensing arrangements.
Within the cooperative tier, Arla Foods and Fonterra Co-operative Group represent scale-driven supply anchors with grass-fed sourcing networks. Upfield occupies a position among emulsion-technology specialists competing on spreadable functionality at reduced fat thresholds. These three exemplify divergent strategic postures—cooperative volume consolidation versus proprietary formulation differentiation versus hybrid plant-dairy blending capabilities.
| Leading Market Players |
|---|
| Palsgaard |
| AMUL (Gujarat Cooperative Milk Marketing Federation Ltd.) |
| Land O'Lakes, Inc. |
| Ornua Co-operative Limited |
| Saputo Inc. |
| Arla Foods |
| Fonterra Co-operative Group |
| Finlandia Cheese, Inc. |
| Upfield |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance deadlines are compressing product development timelines for lower saturated fat profiles, forcing dairy processors to absorb retrofit costs or pass them through to bakery chains negotiating long-term supply agreements.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as industrial bakeries in Germany and France demand rapid reformulation cycles to meet retailer Nutri-Score thresholds. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-protocol cultured variants from commodity spreadable formats and private-label economy grades. Price differentiation hinges on clean-label certification tier and volume scale, with food manufacturers showing highest sensitivity to per-unit costs while artisan bakeries absorb premiums for origin documentation. Pricing pressure stems from cream input cost volatility transmitting from New Zealand and Ireland, squeezing margins on standard-grade formulations.
Supply Chain Analysis
Single-source vulnerability sits with grass-fed dairy farming output in New Zealand and Ireland, where climatic fluctuations transmit directly to butterfat availability. Raw material dependencies center on cream supply, milk solids, and structured oleogel substitutes for plant-based blending. Supply chain risk concentrates in tariff exposure for cross-border cream movements between EU member states and third-country sourcing. Distribution runs through cooperative processor networks with captive cold-chain infrastructure, though direct-to-bakery models in Paris and Copenhagen are disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cooperative processors with pooled technical resources for ammonia-based refrigeration retrofits, squeezing independent dairies unable to meet EU Green Deal compliance deadlines.
For Market Incumbents: Deploy backward integration into grass-fed farming operations to secure cost-stable cream supply against New Zealand and Irish output fluctuations. Arla Foods and Fonterra Co-operative Group exemplify this posture through captive milk networks. Channel control through direct-to-bakery relationships in Paris and Copenhagen bypasses distributor margin compression. Certification investment in BIS compliance for Indian organized retail opens shelf space in Mumbai and Bangalore hypermarket chains before foreign competitors achieve entry.
For New Entrants and Emerging Players: Enter via underpenetrated Indian organized retail where BIS requirements currently block most foreign brands. Domestic processors with compliant facilities can capture shelf space ahead of liberalization. Target food manufacturing segment in Germany and France where clean-label industrial baking mandates are accelerating specification shifts toward simplified ingredient decks. Go-to-market angle should emphasize emulsion stability testing aligned with retailer Nutri-Score thresholds.
For Investors and Strategic Acquirers: The window for entry favors cooperative processors with pooled technical resources and ammonia-based refrigeration retrofit capabilities. Long-term viability over the next decade rests on compliance capability gaps widening versus smaller independent dairies. Acquisition target archetype: regional private-label processors with retail channel access and existing BIS certification for Indian market entry. Signal to watch is front-of-pack labeling mandate tightening across EU member states accelerating procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming | Arla Foods and Fonterra anchor supply through grass-fed dairy networks spanning Nordic and Oceania regions. |
| Direct-to-Bakery Distribution | Costa Coffee and Greggs bypass wholesale layers to negotiate captive supply lines for spreadable formats. |
| Clean-Label Reformulation | Industrial bakers in Belgium and Netherlands adopt high-pressure processed cream to eliminate potassium sorbate preservatives. |
| Refrigeration Retrofit Compliance | Danish and Irish cooperatives pool technical resources for ammonia-based systems under EU F-Gas phase-down mandates. |
| BIS Certification Investment | Gujarat Cooperative Milk Marketing Federation captures domestic shelf space in Mumbai and Bangalore hypermarket chains. |
Research Methodology
Document review covered EU F-Gas Regulation compliance filings, EFSA environmental labeling guidelines, and FSSAI front-of-pack labeling mandates, complemented by interviews with dairy processing plant managers, procurement leads at industrial bakery chains, retail category buyers, and technical R&D directors at emulsion technology specialists. Secondary validation drew from customs and trade data on cream movements, cooperative processor annual disclosures, and retailer Nutri-Score implementation reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Historical shipment data cross-referenced against panel input from procurement executives at bakery chains in Germany, France, and the United Kingdom anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application temperature stress, packaging barrier performance, and end-user specification authority. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label mandate acceleration and plant-based fat blending adoption curves. Industry-specific inputs captured emulsion stability thresholds and fermentation-protocol premium capture rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under trans fat restriction tightening or front-of-pack labeling mandate acceleration beyond current EFSA timelines. Forecasts reflect assumptions on cooperative merger velocity and technology licensing arrangement density. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Cream Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Paneer Market
Dairy Products
North America Casein Market
Dairy Products
GCC Cheese Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Canada Dairy Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Canada Milk Protein Market