
 South America Insoluble Dietary Fibers Market | 2026-2036
South America Insoluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Insoluble Dietary Fibers Market Analytics
CE marking alignment for food-contact materials is bifurcating competitive access across the South America Insoluble Dietary Fibers Market. Cargill, Incorporated leverages its integrated grain supply chain to anchor cellulose fiber production at scale. DuPont de Nemours, Inc. differentiates through specialty lignin applications targeting pharmaceutical-grade specifications. Roquette Frères competes with pea-derived fiber technology adapted to regional crop availability.
Insoluble dietary fibers comprise non-digestible carbohydrate polymers and ligneous compounds that resist hydrolysis by human digestive enzymes, typically retaining structural integrity with particle sizes between 50-500 microns and moisture absorption capacities exceeding five times their dry weight. These functional ingredients primarily serve to enhance stool bulk, reduce caloric density, and improve texture in formulated foods. Cellulose dominates volume across food and beverage applications where powder form factors integrate into bakery and dairy matrices with minimal process disruption. Lignin commands premium positioning in nutraceuticals targeting gut microbiome modulation, while chitin from crustacean sources occupies a narrow but expanding niche in pharmaceutical capsules.
ANVISA governs food additive approvals and fiber content claims in Brazil, while Argentina's national food safety authority enforces Mercosur-aligned labeling standards that mandate quantitative fiber disclosure on consumer packages. REACH-equivalent chemical safety protocols through Brazil's CONAMA resolutions restrict residual solvent levels in extraction processes, elevating compliance costs for imported raw materials. Stakeholders must monitor evolving Mercosur technical regulations on novel fiber sources and decide whether to localize extraction capacity or secure long-term supply agreements with Andean and Southern Cone grain processors.
Market Dynamics
Clean-label reformulation mandates across Brazil and Argentina are compressing traditional ingredient procurement windows, forcing food processors to validate fiber sourcing against ANVISA's updated disclosure rules before product relaunch cycles complete.
Growth Catalysts
- ANVISA Nutritional Labeling Mandate:Brazil's fiber disclosure requirement on packaged foods compels manufacturers to reformulate with quantifiable insoluble fiber content, expanding verified supply contracts.
- Pharmaceutical-Grade Lignin Demand:Nutraceutical formulators in Argentina's Buenos Aires corridor specify high-purity lignin for gut microbiome modulation applications, pulling premium extraction capacity.
- São Paulo Food Processing Concentration:Brazil's southeastern state hosts dense bakery and dairy manufacturing clusters that integrate cellulose fibers at scale for texture and caloric reduction.
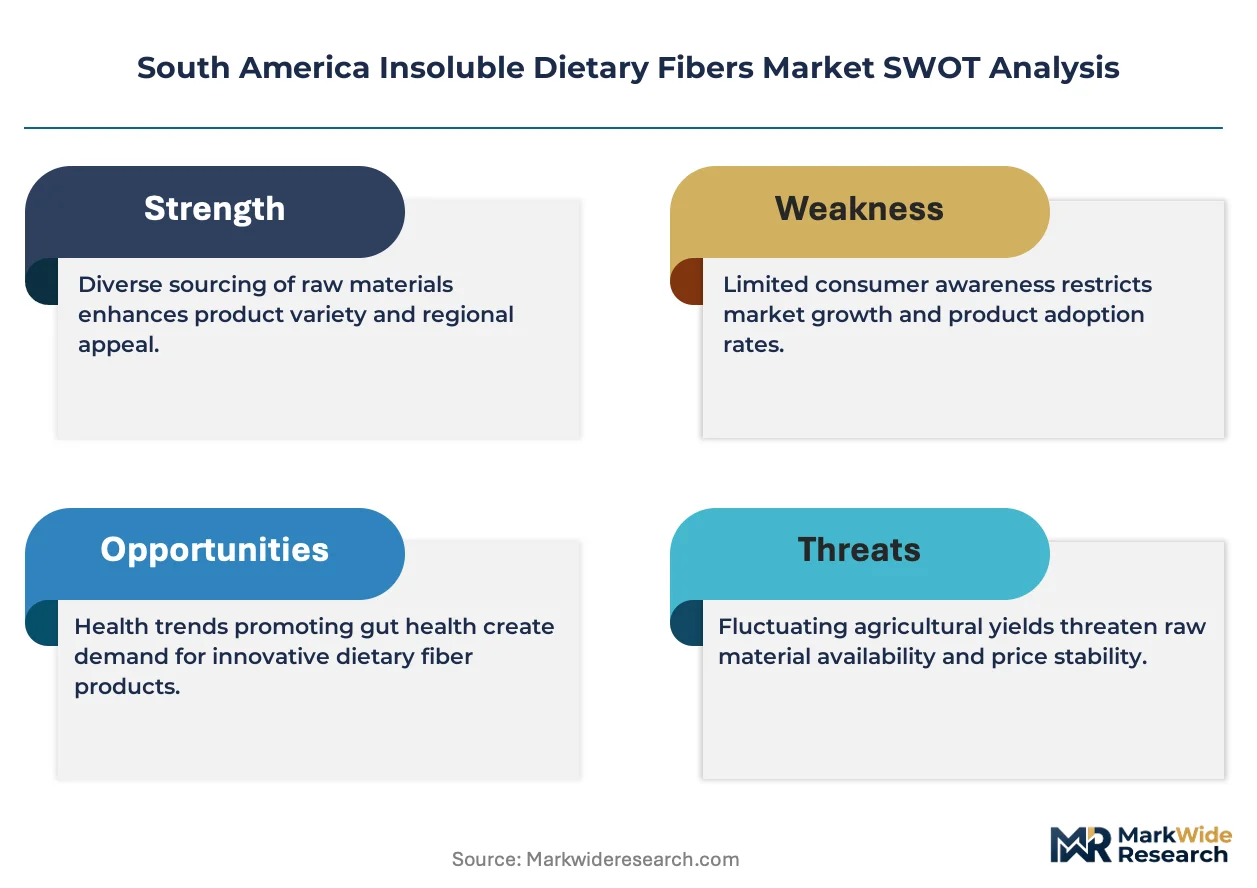
Market Restraints
- Residual Solvent Compliance Costs:Brazil's CONAMA resolutions enforcing REACH-equivalent chemical safety protocols elevate extraction costs for imported raw materials, squeezing margin on cross-border supply.
- Andean Grain Processor Concentration:Limited regional extraction capacity concentrates upstream supply among Southern Cone grain processors, creating bottleneck risk during harvest volatility.
- Chitin Supply Limitation:Pharmaceutical capsule manufacturers face constrained crustacean-derived chitin availability from Argentina's coastal fisheries, restricting niche expansion.
Strategic Opportunities
- Pea-Derived Fiber Localization:Argentina's pulse crop base supports domestic extraction infrastructure for pea fiber, reducing import dependency for regional food formulators.
- Mercosur Novel Fiber Pathway:Evolving technical regulations on emerging fiber sources create first-mover advantage for stakeholders establishing approved ingredient dossiers.
- Direct Processor Partnerships:Long-term supply agreements with Brazilian and Argentine grain cooperatives bypass trader markups and secure volume commitments.
Industry Challenges
- Clean-Label Validation Timeline:Fiber ingredient certification against ANVISA's quantitative disclosure standards extends product development cycles by 8-14 months.
- Extraction Equipment Capex:Pharmaceutical-grade lignin purification requires solvent recovery systems that demand significant capital deployment in a thin-margin environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Insoluble Dietary Fibers Market |
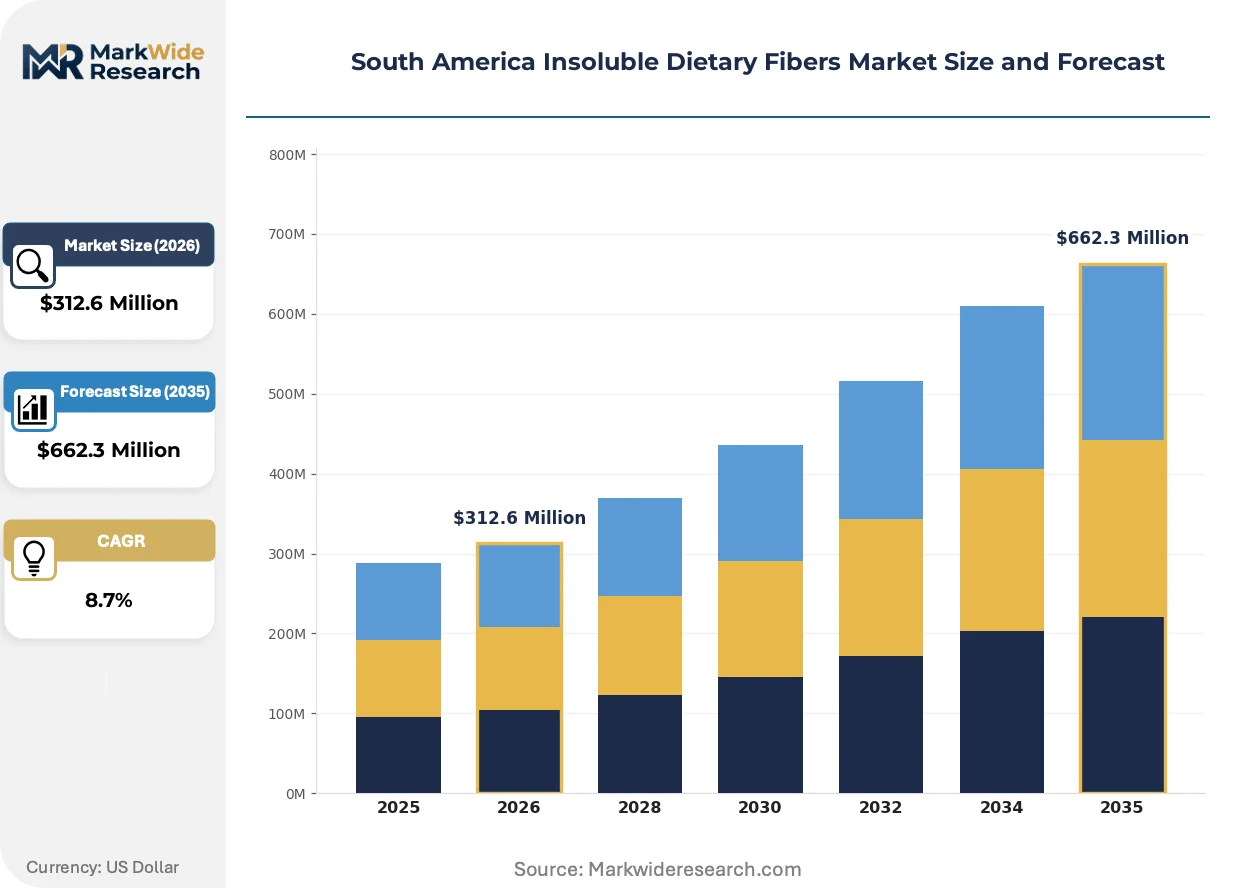
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Lignin, Oligofructose, Chitin Application: Food & Beverages, Pharmaceuticals, Animal Feed, Nutraceuticals End User: Retail Consumers, Food Manufacturers, Healthcare Providers, Feed Producers Form: Powder, Granules, Tablets, Capsules |
| Companies Covered | Cargill, Incorporated, DuPont de Nemours, Inc., Grain Processing Corporation, Ingredion, Inc., J. Rettenmaier & Söhne GmbH + Co KG, Roquette Frères, Archer Daniels Midland Company, Tate & Lyle, SunOpta, Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Insoluble Dietary Fibers Market Evolving Landscape
Mechanical fiber refinement technologies are compressing particle size tolerances while enzymatic extraction methods reduce solvent dependency, reshaping how South American processors qualify for clean-label positioning.
Cellulose microcrystalline fiber production is fragmenting traditional supply hierarchies. Brazilian bakery manufacturers adopt sub-100-micron grades for seamless dough integration without process line modification. This particle standardization is fragmenting procurement patterns, enabling mid-tier mills to compete with established chemical suppliers on specification compliance rather than scale alone.
ANVISA's alignment with Mercosur labeling harmonization protocols is tightening quantitative fiber claim enforcement. Processors must now submit third-party analytical verification for insoluble fiber content declarations. Argentina's national food safety authority mirrors these standards, compressing formulation timelines for cross-border product launches.
Buyer concentration among São Paulo-based dairy conglomerates is shortening ingredient qualification cycles. These processors now demand pilot-scale validation data before contract execution, displacing traditional specification-sheet procurement. Argentina's nutraceutical contract manufacturers exhibit similar behavior, prioritizing suppliers with in-house application laboratories.
South America Insoluble Dietary Fibers Market Segmentation
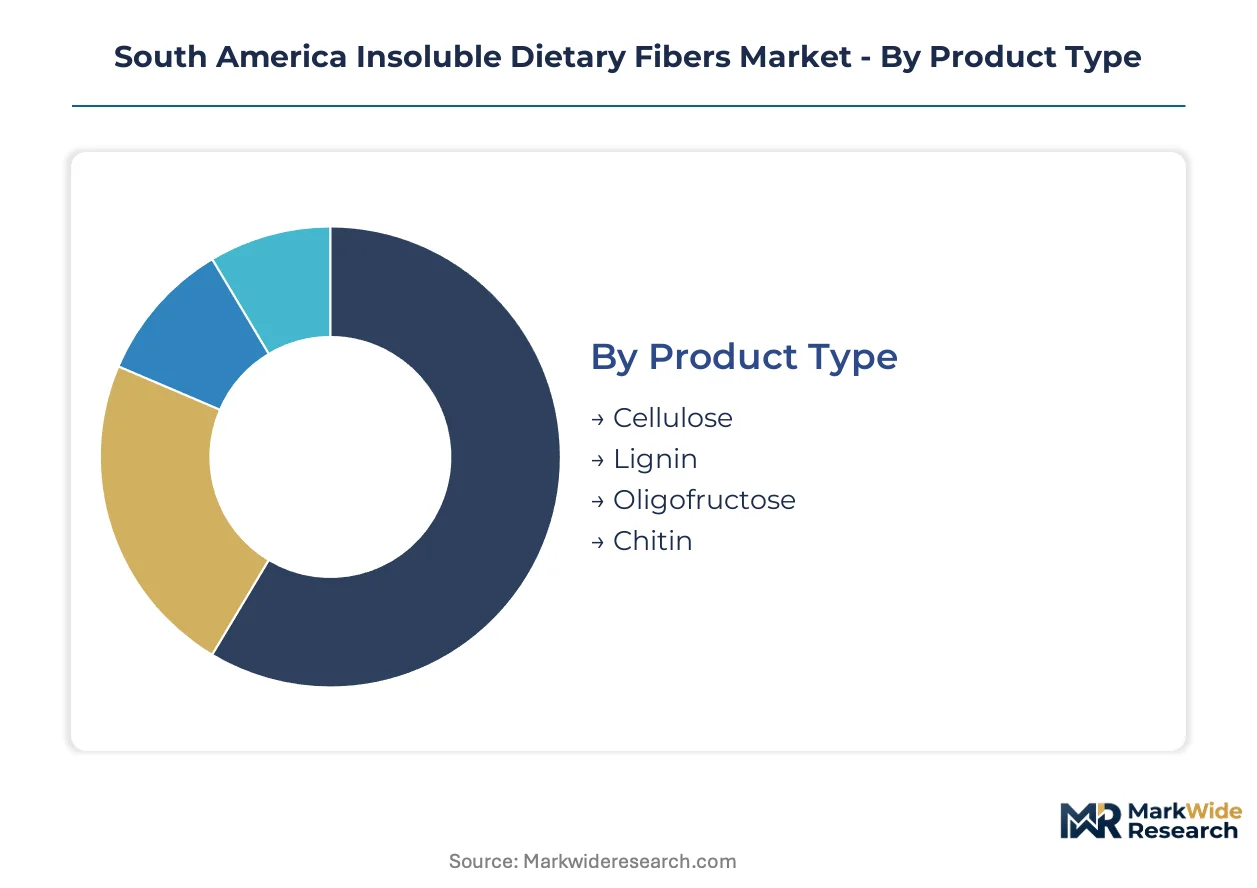
Segmentation across South America's insoluble dietary fibers market reveals how regulatory mandates and processing infrastructure reshape competitive positioning. ANVISA's disclosure requirements and São Paulo's manufacturing density create divergent growth patterns across product categories and end-use channels.
Product Type:
Export-oriented cellulose production dominates cross-border trade, while lignin extraction serves primarily domestic pharmaceutical demand concentrated in Brazil and Argentina.
- Cellulose:Non-digestible carbohydrate polymers with particle sizes between 50-500 microns and moisture absorption exceeding five times dry weight. São Paulo's bakery and dairy manufacturers integrate powder-form cellulose at scale for texture enhancement and caloric reduction, driven by clean-label reformulation cycles.
- Lignin:Ligneous compounds resistant to human digestive enzyme hydrolysis, commanding premium positioning in gut microbiome modulation applications. Buenos Aires corridor nutraceutical formulators specify high-purity grades, pulling specialized extraction capacity toward pharmaceutical-grade specifications.
- Oligofructose:Short-chain fructose oligomers with prebiotic functionality, finding application in functional dairy products across Brazilian retail channels.
- Chitin:Crustacean-derived structural polysaccharide constrained by Argentina's coastal fishery supply limitations, occupying narrow pharmaceutical capsule niches.
Cellulose holds the largest share; momentum sits with lignin as pharmaceutical-grade specifications expand.
Application:
Cost-tier differentiation separates commodity food-grade formulations from premium pharmaceutical and nutraceutical specifications requiring third-party analytical verification.
- Food & Beverages:Largest volume application where cellulose fibers integrate into bakery and dairy matrices with minimal process disruption. Brazilian manufacturers reformulate packaged foods to meet ANVISA's mandatory fiber disclosure rules, compressing procurement validation timelines.
- Pharmaceuticals:High-specification lignin and chitin applications targeting gut microbiome modulation and controlled-release capsule formulations. Argentina's contract manufacturers demand pilot-scale validation data before supplier qualification.
- Animal Feed:Functional fiber additives supporting digestive health in livestock operations across Brazil's agricultural interior.
- Nutraceuticals:Premium positioning for microbiome-targeted formulations, with Buenos Aires processors leading regional demand concentration.
Food & Beverages anchors volume; Pharmaceuticals commands the steepest expansion trajectory as regulatory disclosure tightens.
End User:
Customer-type concentration creates divergent procurement patterns, with industrial food manufacturers demanding specification compliance while retail channels prioritize price accessibility.
- Food Manufacturers:São Paulo-based dairy conglomerates and bakery processors dominate contract volume, shortening ingredient qualification cycles through pilot-scale validation requirements.
- Healthcare Providers:Clinical nutrition programs and hospital formulary committees specifying fiber-enriched therapeutic foods.
- Feed Producers:Livestock and aquaculture operations integrating functional fibers into ration formulations.
- Retail Consumers:Packaged goods purchasers responding to ANVISA-mandated fiber content disclosures on product labels.
Food Manufacturers represent the dominant demand source; Healthcare Providers are gaining share fastest as clinical nutrition protocols expand.
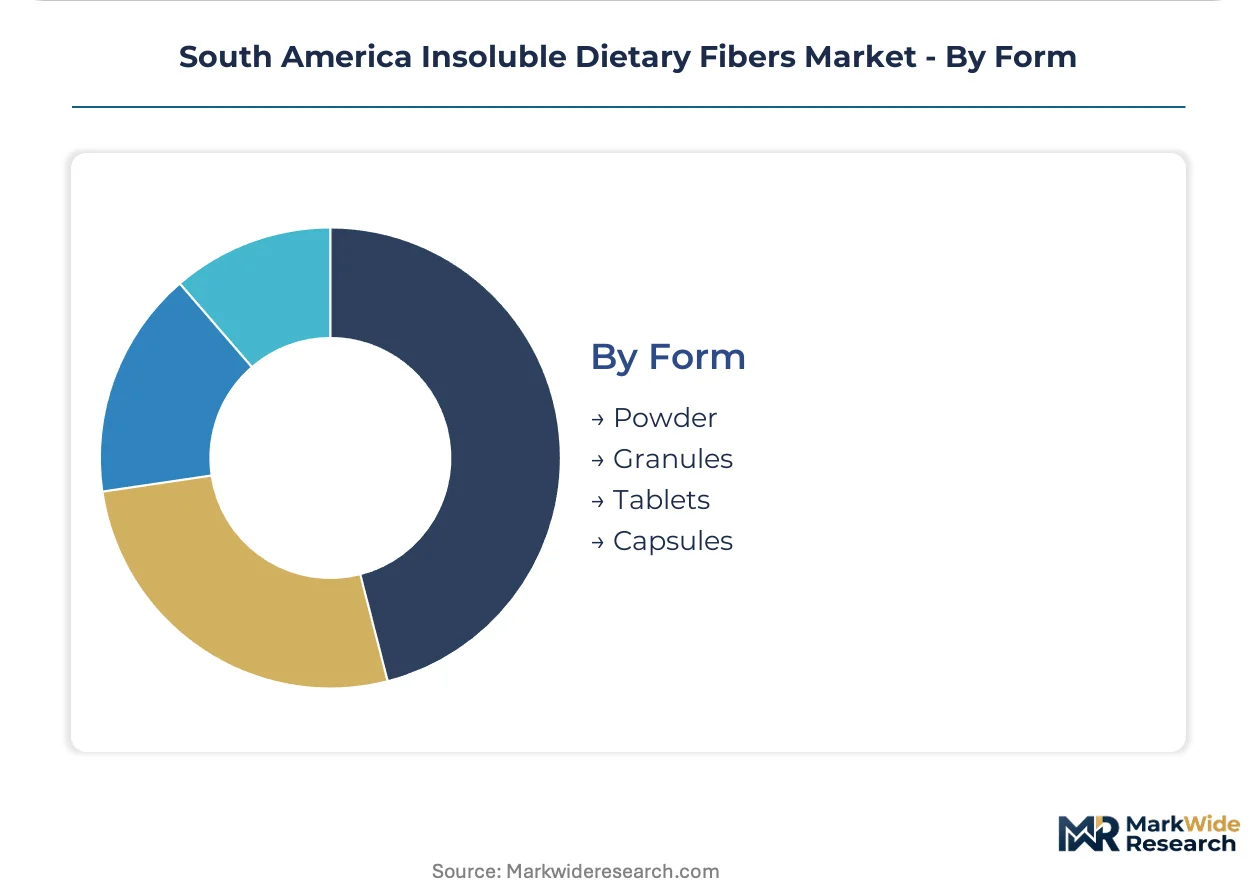
Form:
Supply concentration among powder processors reflects São Paulo's manufacturing infrastructure dominance, while capsule and tablet forms depend on specialized Argentine pharmaceutical packaging capacity.
- Powder:Dominant form factor enabling seamless integration into bakery dough and dairy matrices without production line modification. Brazilian mills compete on sub-100-micron specification compliance.
- Granules:Intermediate processing form supporting bulk handling in feed and industrial food applications.
- Tablets:Compressed delivery format for nutraceutical and clinical nutrition segments.
- Capsules:Pharmaceutical-grade delivery constrained by Argentina's limited crustacean-derived chitin availability for hard-shell production.
Powder holds the largest share; Capsules face supply headwinds despite expanding pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in São Paulo's processing corridor dominate procurement volume, while pharmaceutical-grade demand concentrates in Buenos Aires. Buyer archetypes split between cost-driven commodity cellulose purchasers and specification-sensitive lignin formulators.
Brazil
São Paulo state's bakery and dairy conglomerates integrate cellulose fibers at scale for texture modification and caloric reduction. ANVISA's updated nutritional labeling rules now mandate quantitative fiber disclosure on all packaged foods, compressing supplier validation timelines. The southeastern manufacturing belt hosts dense clusters of mid-tier mills competing on sub-100-micron specification compliance.
Argentina
Buenos Aires corridor nutraceutical formulators drive premium lignin demand for gut microbiome modulation applications. The national food safety authority enforces Mercosur-aligned labeling standards that mirror Brazil's quantitative disclosure requirements. Pharmaceutical contract manufacturers in the metropolitan region now require pilot-scale validation data before supplier qualification.
Chile
Santiago-based food exporters source cellulose fibers for clean-label reformulation targeting North American and European retail channels. The country's sanitary regulations align with Codex Alimentarius standards for fiber content claims. Central Valley agricultural processors are exploring pea-derived fiber extraction from domestic pulse crop production.
Colombia
Bogotá's packaged food manufacturers respond to evolving Ministry of Health labeling guidelines with fiber fortification programs. Andean grain processors concentrate upstream supply for regional cellulose raw material, creating harvest-dependent bottleneck risk. Antioquia's emerging food technology sector is attracting pilot-scale fiber application laboratories.
Peru
Lima's functional food startups leverage indigenous crop fibers including quinoa and amaranth hulls for differentiated positioning. The General Directorate of Environmental Health regulates novel fiber sources through pre-market safety assessments. Coastal aquaculture operations provide limited chitin raw material for pharmaceutical capsule manufacturers.
South America Insoluble Dietary Fibers Market Competitive Landscape
Player mix skews toward integrated grain processors and specialty extraction specialists competing across tiered specification bands. Market structure concentrates upstream capacity among Southern Cone agricultural conglomerates with captive cellulose supply chains. Three archetypes dominate: multinational ingredient platforms with regional formulation support, regional mill operators competing on particle size compliance, and pharmaceutical-grade purification specialists serving nutraceutical demand. Competitive dynamics center on backward integration into grain sourcing and technology licensing for solvent-reduced extraction methods.
Among the multinational ingredient platforms, Cargill, Incorporated and Roquette Frères exemplify scale-driven positioning anchored to integrated supply chain control. DuPont de Nemours, Inc. occupies a position within the specialty specification tier, representing pharmaceutical-grade purification capabilities. These three companies illustrate how competitive positioning splits between volume cellulose production and premium lignin extraction serving divergent end-use requirements across Brazilian food manufacturing and Argentine nutraceutical formulating.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont de Nemours, Inc. |
| Grain Processing Corporation |
| Ingredion, Inc. |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Roquette Frères |
| Archer Daniels Midland Company |
| Tate & Lyle |
| SunOpta, Inc. |
| Others |
Value Network & Pricing Analysis
Mill-scale capacity utilization in Brazil's São Paulo corridor anchors price floors for cellulose fiber grades, compressing margin structures for smaller Argentine processors unable to match backward integration into grain sourcing. ANVISA's disclosure mandates amplify buyer concentration among dairy conglomerates, translating procurement volume into pricing leverage that squeezes mid-tier suppliers.
Pricing Analysis
Cost-plus contracts indexed to Brazilian grain futures dominate long-term supply agreements, with pharmaceutical-grade lignin commanding premium-mid-economy pricing differentiation based on CONAMA solvent-residue certification. Price differentiation separates ANVISA-validated suppliers from unverified competitors, with São Paulo-based food manufacturers exhibiting lowest price sensitivity due to clean-label compliance deadlines. Pricing pressure stems from Argentine peso volatility elevating import substitution economics for pea-derived fiber extraction.
Supply Chain Analysis
Port congestion at Santos and Buenos Aires elevates inbound logistics costs for specialty extraction equipment, compressing working capital cycles for lignin purification projects. Supply concentrates in Brazil, Argentina, and Chile, with raw material dependencies on Southern Cone wheat bran, Andean pulse crops, and coastal crustacean waste. Single-source vulnerability runs through São Paulo's mid-tier mill concentration. Distribution runs through grain cooperative networks and pharmaceutical ingredient distributors serving Buenos Aires nutraceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for fiber application laboratories represent a recurring-revenue layer expanding faster than commodity cellulose sales, as São Paulo dairy processors demand pilot-scale validation before supplier qualification.
For Market Incumbents: Compound backward integration into Andean grain sourcing to neutralize harvest volatility exposure, while securing ANVISA pre-approval dossiers for novel fiber sources before Mercosur harmonization tightens. Capacity addition in Argentina's pulse belt counters import dependency risks. For New Entrants and Emerging Players: Lead with pea-derived fiber extraction targeting Argentina's domestic crop base, where clean-label validation timelines create incumbency gaps. The most penetrable segment sits with Bogotá's emerging food technology sector seeking localized supply alternatives. Go-to-market should emphasize in-house application laboratories matching São Paulo buyer requirements. For Investors and Strategic Acquirers: Specialty extraction specialists with CONAMA-compliant solvent recovery systems represent the priority acquisition archetype, given pharmaceutical-grade lignin demand concentration in Buenos Aires. Long-term viability hinges on regulatory alignment capacity rather than scale alone. Watch Mercosur novel fiber approval velocity as inflection indicator for first-mover returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Sourcing | Captive wheat bran supply from Southern Cone cooperatives insulates against harvest price spikes. |
| ANVISA Pre-Approval Dossier Investment | Novel fiber source validation compresses competitor entry timelines by 8-14 months. |
| Application Laboratory Buildout | In-house pilot-scale validation matches São Paulo dairy procurement requirements. |
| Pea Fiber Extraction Localization | Argentina's pulse crop base reduces import dependency for regional formulators. |
| CONAMA Solvent Recovery Compliance | Pharmaceutical-grade lignin purification unlocks Buenos Aires nutraceutical premium pricing. |
Research Methodology
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings, combining primary interviews with ANVISA compliance officers, São Paulo procurement directors, Buenos Aires nutraceutical formulators, and Andean grain cooperative managers with secondary validation from customs records, CONAMA resolution databases, and Mercosur technical regulation filings. Bottom-up fiber volume estimates triangulate against top-down food processing capacity assessments across the analysis window.
Sensitivity analysis around ANVISA enforcement intensity and Argentine currency volatility frames the analytical framework, modeling cellulose grade tier, pharmaceutical certification level, end-use application channel, and regional production hub segmentation throughout the forecast period. CAGRs derive from installed processing capacity expansion rates and clean-label reformulation pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA disclosure enforcement or Mercosur regulatory harmonization would require recalibration. Forecasts reflect assumptions of continued Southern Cone agricultural output stability and solvent extraction technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
North America Phytosterols Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Sweet Almond Oil Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Organic Starch Market
Ingredients
Soluble Fibers Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Ground-Nut Oil Market
Ingredients
Hydrogenated Starch Market
Ingredients
Grape Skin Extract Market
Ingredients
Gluten-Free Flour Market
Ingredients
Agar Market
Ingredients
Bulk Food Ingredients Market