
 North America Dairy Market | 2026-2036
North America Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Market Insights
The gap between premium artisan dairy and commodity fluid milk is broadening as consumer willingness to pay for provenance and nutritional density splits from price-driven bulk purchasing. Dairy Farmers of America leverages its cooperative scale to dominate commodity milk pooling across the central United States. Land O'Lakes sustains brand strength in butter and dairy ingredients through farmer-owned supply control. Saputo anchors cheese production capacity with significant plant infrastructure in Wisconsin and Quebec.
North America dairy encompasses milk-derived products and byproducts processed through pasteurization, fermentation, separation, and drying into forms ranging from fluid milk to concentrated proteins, serving nutritional, culinary, and industrial formulation purposes. Cheese and yogurt command disproportionate margin pools relative to fluid milk, which faces structural demand erosion in direct consumption. Online retail distribution is gaining velocity as cold-chain logistics improve, while food manufacturers represent a concentrated buyer segment for bulk butter and milk powder inputs.
The USDA and FDA govern Grade A standards, labeling integrity, and interstate milk shipment rules in the United States, while Health Canada and the Canadian Food Inspection Agency administer parallel dairy compositional standards and supply management quotas. These frameworks shape product formulation requirements, cross-border trade access, and pricing structures for imported dairy ingredients. Stakeholders must track evolving plant-based labeling disputes and carbon accounting mandates that threaten to redraw competitive boundaries between conventional and alternative dairy.
Market Dynamics
Clean-label procurement mandates from U.S. and Canadian food manufacturers are compressing ingredient qualification timelines while simultaneously fragmenting supplier pools as regional dairies struggle to meet documentation requirements.
Growth Catalysts
- USDA Grade A Certification Expansion:Extended pooling arrangements across Midwest cooperatives reduce per-unit compliance costs for fluid milk processors seeking interstate distribution access.
- Precision Fermentation Scale-Up:Bioprocessing infrastructure investments in Wisconsin and Quebec enable recombinant protein production that supplements conventional milk solids in industrial formulations.
- Food Manufacturer Procurement Consolidation:CPG buyers in Chicago and Toronto are centralizing dairy ingredient sourcing through long-term offtake agreements with processor cooperatives.
Market Restraints
- Feed Cost Volatility:Corn and soybean meal price swings in the U.S. grain belt transmit directly to farm-gate milk production economics, compressing processor margins during commodity spikes.
- Supply Management Quotas:Health Canada's dairy compositional standards and production limits restrict volume flexibility for Quebec and Ontario processors seeking export market expansion.
- Plant-Based Substitution:Oat and almond protein isolates from extrusion facilities in California and Minnesota are displacing skim milk powder in beverage and bakery applications.
Strategic Opportunities
- Carbon Accounting Integration:The Canadian federal carbon pricing framework and emerging U.S. SEC climate disclosure rules create premium positioning for verified low-emission dairy ingredient suppliers.
- Specialized Nutrition Applications:Medical and senior nutrition formulations in Texas and Florida represent underpenetrated demand for high-protein concentrates and hydrolyzed caseinates.
- Cold-Chain E-Commerce Expansion:Direct-to-consumer refrigerated logistics networks in Vancouver and Boston enable artisan cheese and cultured product bypass of conventional retail distribution.
Industry Challenges
- Microbiological Testing Bottlenecks:Extended pathogen verification timelines for raw milk intake are forcing processors to carry larger safety stock and compress production scheduling flexibility.
- Legacy ERP Integration:Batch-oriented manufacturing execution systems at mid-sized Wisconsin cheese plants require costly retrofitting to support real-time traceability demanded by FDA Food Safety Modernization Act enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Market |
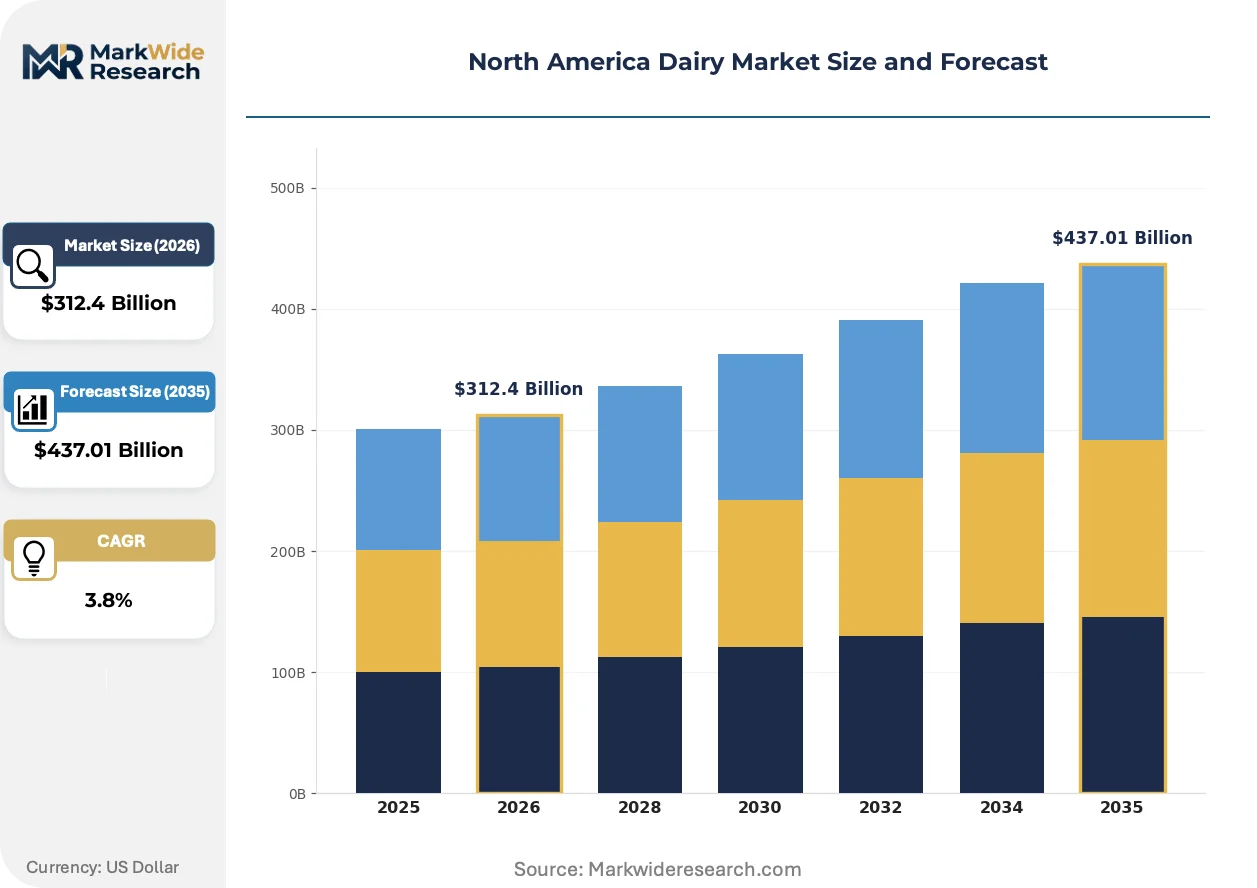
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Farmers' Markets End User: Households, Restaurants, Cafés, Food Manufacturers Packaging Type: Bottles, Tetra Packs, Cartons, Bulk Containers |
| Companies Covered | Dairy Farmers of America, Land O'Lakes, Saputo, Nestlé North America, Lactalis Group, Danone, Agropur, Kraft Heinz, Schreiber Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Market Trends and Innovations
Processing technology convergence and regulatory disclosure requirements are compressing product development cycles while simultaneously elevating the technical threshold for market participation across the value chain.
Membrane filtration technology is unifying protein fractionation and lactose recovery into continuous-flow operations that previously required discrete processing stages. Large-scale cheese manufacturers in the upper Midwest are retrofitting ultrafiltration systems at accelerated capital deployment schedules. This unifying architecture is compressing unit economics for whey protein isolate production and displacing older diafiltration batch methods.
The FDA's evolving enforcement posture on plant-based dairy labeling terminology is creating definitional battles over "milk" and "cheese" descriptor usage in interstate commerce. Food manufacturers reformulating with hybrid dairy-analog blends face reformulation costs and packaging redesign obligations. Alternative protein startups in California and Minnesota are most affected, responding with nutritional equivalence testing to defend shelf positioning.
Foodservice procurement teams are consolidating supplier relationships and demanding consolidated ingredient deliveries that bundle butter, cream, and cheese varieties through single-source agreements. Regional distributors in Texas and Florida are losing share to direct processor relationships as chain restaurant operators seek volume commitments and price predictability. This concentration is most visible in the quick-service restaurant segment, where menu standardization across corporate locations favors national supply contracts over fragmented local sourcing.
North America Dairy Market Segmentation
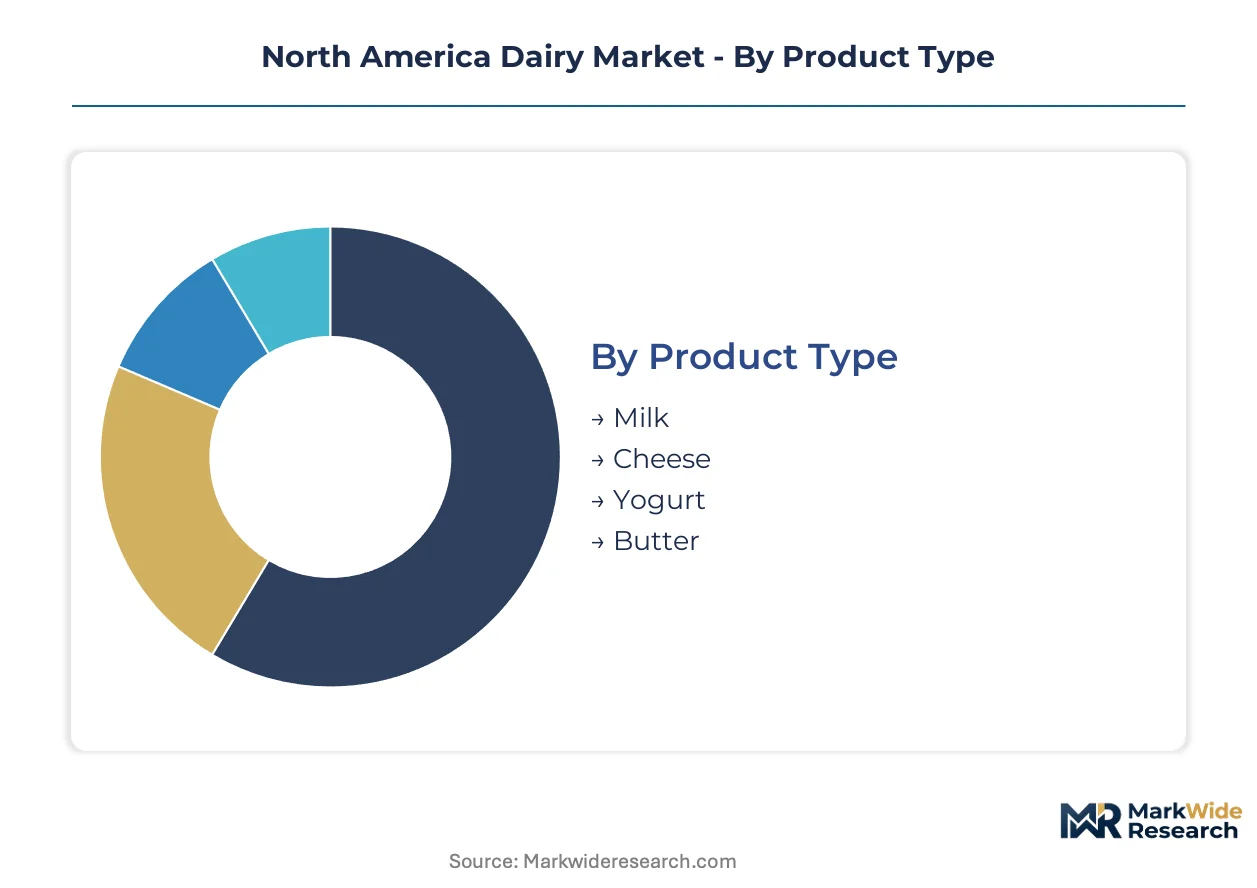
Dairy market segmentation in North America reflects divergent margin structures across processing intensity levels and channel access requirements. Product type and packaging format decisions determine cold-chain investment thresholds, while distribution channel selection governs geographic reach and price realization.
Product Type:
Standalone consumption formats dominate retail shelf placement, whereas ingredient-grade outputs embed into downstream food manufacturing systems with distinct specification requirements.
- Milk:Fluid milk undergoes pasteurization and homogenization to achieve Grade A interstate shipment eligibility under USDA pooling standards. Demand concentrates in the U.S. Midwest dairy belt where cooperative processing infrastructure achieves scale economies, though direct consumption volumes face persistent displacement from plant-based alternatives in coastal metropolitan markets.
- Cheese:Natural and processed cheese varieties command disproportionate margin pools relative to fluid milk through aged inventory appreciation and functional ingredient applications. Wisconsin and Quebec processing clusters supply CPG manufacturers in Chicago and Toronto with standardized mozzarella and cheddar blocks for foodservice and retail shredding operations.
- Yogurt:Greek and traditional yogurt production utilizes ultrafiltration to concentrate protein solids before fermentation.
- Butter:Butterfat separation from cream supports both retail table butter and industrial bakery shortening formulations.
Volume placements concentrate in Milk; the faster expansion belongs to Cheese.
Distribution Channel:
Channel selection determines temperature control obligations and margin capture, with direct-to-consumer formats requiring specialized logistics versus consolidated wholesale delivery.
- Supermarkets:Multi-temperature zone retail environments in Texas and Florida allocate refrigerated case space to fluid milk and fresh cheese based on velocity metrics and slotting fee structures.
- Convenience Stores:Grab-and-go dairy purchases concentrate in single-serve milk and yogurt formats for immediate consumption occasions.
- Online Retail:Cold-chain logistics investments in Vancouver and Boston enable direct-to-home delivery of temperature-sensitive cultured products and artisan cheese.
- Farmers' Markets:Unpasteurized specialty milk and farmstead cheese sales operate under state-level raw milk permits with restricted interstate movement.
Supermarkets capture the dominant volume share; Online Retail is climbing the fastest.
End User:
End-user segmentation separates household discretionary purchasing from commercial procurement governed by specification contracts and volume commitments.
- Households:Retail consumers select dairy products based on nutritional labeling, price promotions, and brand recognition in conventional grocery environments.
- Restaurants:Foodservice operators in the quick-service segment demand standardized cheese shreds and portion-control butter with consistent melt performance across franchise locations.
- Cafés:Specialty coffee chains require high-fat cream and milk varieties for beverage foam stability and mouthfeel consistency.
- Food Manufacturers:Industrial buyers procure bulk butter, milk powder, and whey protein concentrates through long-term offtake agreements with processor cooperatives.
Food Manufacturers anchor procurement volume; Cafés are gaining share fastest.
Packaging Type:
Packaging format selection balances shelf-life extension against material cost and recycling infrastructure compatibility across provincial and state regulatory frameworks.
- Bottles:HDPE and PET bottle formats for fluid milk support closed-loop recycling in jurisdictions with extended producer responsibility mandates.
- Tetra Packs:Aseptic carton technology enables ambient distribution of UHT milk and cream with reduced refrigeration requirements.
- Cartons:Gable-top paperboard containers remain standard for fresh fluid milk in conventional retail channels.
- Bulk Containers:Stainless steel totes and bag-in-box systems serve food manufacturing ingredient delivery with reduced per-unit packaging cost.
Bottles retain volume leadership; Bulk Containers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Upper Midwest dairy belt stretching from Wisconsin through Minnesota anchors North American milk production density, with processing infrastructure clustering around Chicago distribution corridors and Twin Cities logistics hubs.
United States
Wisconsin and California processing plants convert raw milk into cheese and protein concentrates for CPG manufacturers. The USDA enforces Grade A interstate shipment standards that determine pooling eligibility for fluid milk. Chicago-area cooperatives negotiate volume contracts with quick-service restaurant chains seeking standardized cheese shreds.
Canada
Quebec and Ontario dairy farms operate under supply management quotas that limit production expansion. Health Canada administers compositional standards for butterfat content and protein labeling. Montreal and Toronto processors face volume constraints when pursuing export market opportunities beyond domestic quota allocations.
Mexico
Northern border states import U.S. milk powder for reconstitution into fluid products serving price-sensitive consumers. Mexican federal standards agencies coordinate with U.S. FDA on cross-border dairy safety protocols. Monterrey and Guadalajara distribution centers consolidate refrigerated cargo for domestic retail chains.
North America Dairy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ingredient specialization and brand recognition dimensions. The North American dairy sector exhibits cooperative-dominated structure at the farm-gate level transitioning to consolidated processor concentration downstream. Three archetypes predominate: farmer-owned cooperatives pooling raw milk supply, multinational CPG conglomerates with diversified dairy portfolios, and specialized cheese and ingredient processors. Competitive moves concentrate on long-term offtake contracting with food manufacturers and precision fermentation technology licensing.
Among farmer-owned cooperatives, Dairy Farmers of America and Land O'Lakes occupy positions defined by scale and geographic coverage of the central U.S. milk shed. Saputo represents the specialized processor archetype with significant plant infrastructure concentration in Wisconsin and Quebec. These entities exemplify how supply control and processing capacity integration create defensive positioning against commodity price volatility.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Land O'Lakes |
| Saputo |
| Nestlé North America |
| Lactalis Group |
| Danone |
| Agropur |
| Kraft Heinz |
| Schreiber Foods |
| Others |
Pricing and Supply Chain Analysis
Corn and soybean meal price volatility in the U.S. grain belt transmits directly through farm-gate milk economics into processor margins and retail pricing tiers downstream. Feed cost swings compress commodity fluid milk profitability while reinforcing premium positioning for grass-fed and organic certification grades that command shelf price separation.
Pricing Analysis
Yield-per-cow productivity anchors value-based pricing tiers across the North American dairy sector. Contract-based long-term offtake agreements dominate food manufacturer procurement, with price differentiation resting on butterfat content grading and USDA Grade A certification status. Cost compression in commodity fluid milk is intensifying because plant-based alternatives erode volume leverage at retail. Quick-service restaurant chains exhibit lowest price sensitivity due to menu standardization requirements, while private-label retail buyers drive hardest bargain pressure.
Supply Chain Analysis
Direct-to-processor channels handle consolidated food manufacturer demand across Chicago and Toronto logistics corridors. Raw milk supply concentrates in the United States, Canada, and northern Mexico border states. The supply chain draws from corn silage, alfalfa hay, and protein supplement inputs. Single-source vulnerability threatens processors dependent on Midwest cooperative pooling arrangements. Distribution runs through cold-chain networks linking Wisconsin and Quebec processing clusters to coastal metropolitan retail markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's supply management quotas constrain Canadian production expansion, propping pricing power for U.S. processors with unregulated volume flexibility. This supply-constrained dynamic favors incumbents with captive milk shed access.
For Market Incumbents: Deepen backward integration into feed production and precision fermentation capacity to offset plant-based substitution pressure. Lock in long-term offtake agreements with quick-service restaurant chains before emerging precision fermentation entrants achieve cost parity. Prioritize carbon accounting certification investment to capture premium positioning under evolving SEC climate disclosure rules. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer the most penetrable route for artisan cheese and cultured product specialists seeking bypass of conventional retail slotting fee barriers. Target medical nutrition and senior care facility segments in Texas and Florida where specification contracts remain underpenetrated. Pursue hybrid dairy-plant blend formulations to defend shelf positioning amid FDA labeling disputes. For Investors and Strategic Acquirers: USDA Grade A certification expansion announcements are the leading indicator that Midwest cooperative consolidation is accelerating and valuation multiples for processing assets will compress. Position for five-to-ten-year horizon around specialized whey protein isolate and precision fermentation technology licensing platforms. Monitor Health Canada quota relaxation signals as inflection point for Canadian export market access.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant protein production in Wisconsin and Quebec supplements conventional milk solids for industrial formulations. |
| Carbon Accounting Integration | Verified low-emission certification captures premium positioning under Canadian federal carbon pricing and emerging SEC rules. |
| Long-Term Offtake Contracting | Consolidated CPG buyer sourcing through processor cooperatives reduces price volatility exposure across the value chain. |
| Cold-Chain E-Commerce Expansion | Direct-to-home refrigerated logistics in Vancouver and Boston enables artisan product bypass of conventional retail distribution. |
| Membrane Filtration Retrofit | Ultrafiltration system deployment at Midwest cheese plants compresses unit economics for whey protein isolate production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America dairy sector analysis. Primary interviews with dairy cooperative procurement directors, food manufacturer ingredient buyers, plant operations managers, and cold-chain logistics providers combined with USDA pooling reports, FDA enforcement actions, Health Canada compositional standards, and Canadian Food Inspection Agency quota disclosures. Bottom-up volume modeling and top-down value reconciliation triangulated across these data streams.
Data-stream reconciliation across production volume, processing capacity utilization, and end-use consumption patterns shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, distribution channel, end-user category, and packaging format alongside regional regulatory cluster variations. CAGRs derived from trend extrapolation of historical volume movements adjusted for supply management constraints and precision fermentation penetration assumptions. Feed cost index trajectories and cold-chain infrastructure investment pipelines served as dairy-specific forecast inputs.
The model holds under stable feed cost regimes and intact interstate milk shipment rules; deviation in corn price spikes or FDA labeling enforcement shifts would revise volume and value outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Donkey Milk Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Whipping Cream Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Dairy Carton Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Goat Milk Powder Market